
 Europe Branded Generics Market | 2026-2036
Europe Branded Generics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Branded Generics Market Intelligence
Market Context
Hospital procurement consolidation across Western Europe is expanding branded generics uptake as centralized purchasing authorities negotiate volume-based contracts. Sanofi SA leverages its established brand equity and pan-European distribution infrastructure to secure long-term hospital supply agreements. Viatris Inc anchors its position through manufacturing scale across multiple dosage platforms, while Sandoz International GmbH specializes in complex injectable and biosimilar-adjacent branded generic portfolios.
Technical Definition and Structural Segments
Branded generics are pharmaceutical products containing off-patent active pharmaceutical ingredients that manufacturers market under proprietary trade names, typically incorporating differentiated formulations, delivery mechanisms, or quality certifications beyond standard generic specifications. Oral dosage forms dominate volume throughput across European pharmacy and hospital channels, while injectable branded generics command premium positioning due to sterility requirements and higher regulatory barriers to entry. Oncology and cardiovascular therapy areas concentrate margin pools as clinicians prioritize supply security and batch consistency in critical care settings.
Regulatory Framework and Outlook
EMA marketing authorization procedures, EU Falsified Medicines Directive serialization requirements, and national reimbursement frameworks such as Germany's AMNOG and France's CEPS pricing protocols collectively shape product registration timelines and commercial access across Europe. REACH compliance for excipient sourcing and MDR-aligned quality management systems add layered compliance costs that favor established manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving national tender designs and biosimilar interchangeability rulings that could recategorize competitive boundaries between pure generics and value-added branded alternatives.
Market Dynamics
Hospital procurement consolidation across Western Europe is compressing supplier margins while simultaneously elevating contract security as the decisive purchasing criterion over unit price alone.
Growth Catalysts
- Therapeutic Substitution Policies:Germany's AMNOG framework incentivizes physicians to prescribe bioequivalent branded generics in hospital settings, expanding volume access for qualified suppliers.
- EMA Centralized Procedures:The streamlined marketing authorization process accelerates cross-border product registration, reducing time-to-revenue for manufacturers with established quality management systems.
- Injectable Complexity Premiums:Sterility requirements and aseptic manufacturing barriers limit competitor entry in parenteral dosage forms, protecting margin pools for incumbent producers.
Market Restraints
- API Sourcing Concentration:Active pharmaceutical ingredient supply chains concentrate in India and China, exposing European formulators to geopolitical disruption and customs delay risks.
- REACH Excipient Compliance:ECHA registration requirements for novel excipients add EUR 50,000-200,000 per substance in testing and documentation costs, discouraging formulation innovation.
- Biosimilar Category Blur:EMA interchangeability rulings for certain biologics threaten to recategorize value-added branded generics into pure commodity segments.
Strategic Opportunities
- Central and Eastern Europe:Poland, Hungary, and Romania exhibit underpenetrated hospital procurement sophistication, offering first-mover advantages for compliant Western suppliers.
- MDR-Aligned Device-Drug Combinations:The EU Medical Device Regulation creates regulatory pathways for novel delivery mechanisms that differentiate branded generics from standard alternatives.
- Serialized Direct-to-Pharmacy Distribution:EU Falsified Medicines Directive compliance infrastructure enables bypass of traditional wholesale layers, capturing margin through channel disintermediation.
Industry Challenges
- Qualified Person Scarcity:The EU requirement for named Qualified Persons in pharmacovigilance and batch release functions faces talent shortages, constraining manufacturing expansion timelines.
- Legacy ERP Serialization Integration:EU Falsified Medicines Directive track-and-trace mandates force costly modifications to established manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Branded Generics Market |
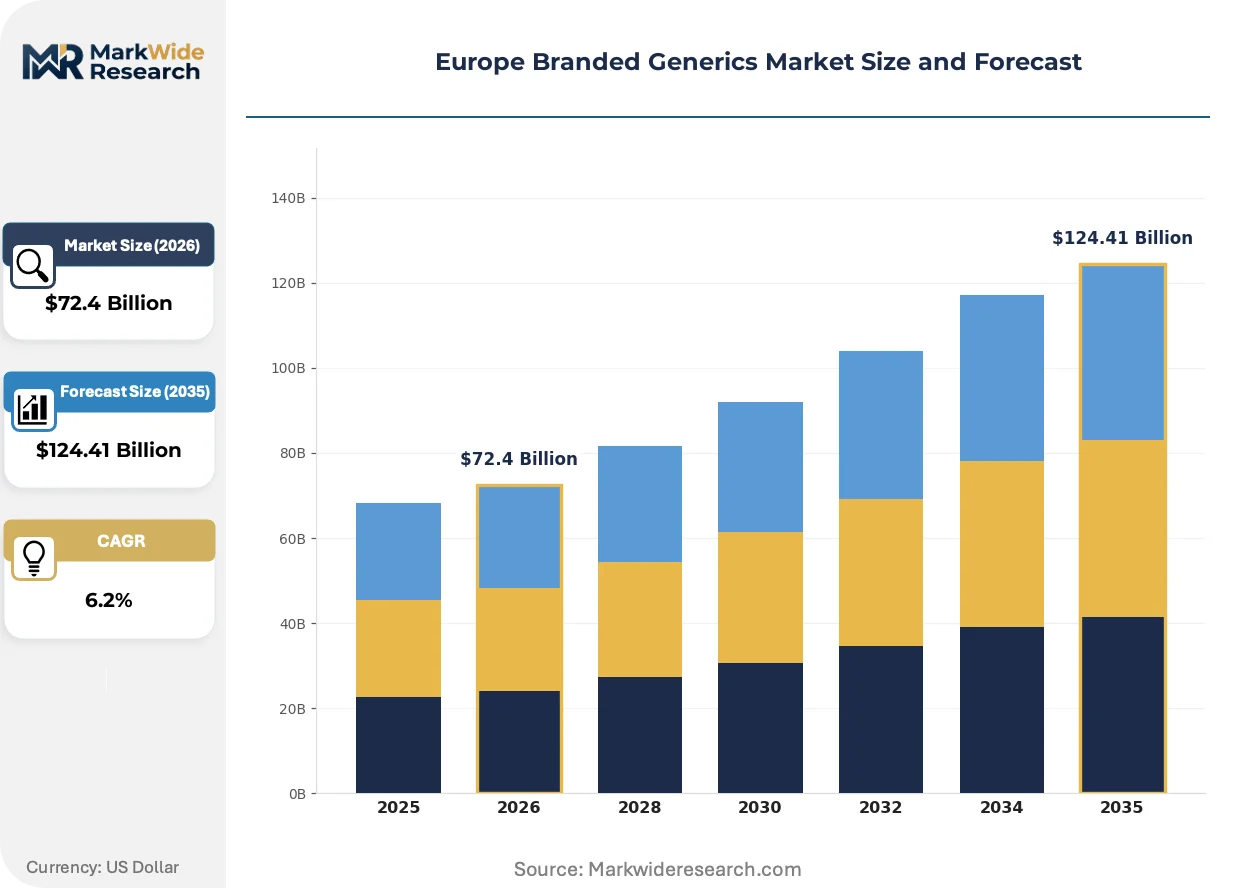
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $124.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral, Injectable, Topical, Inhalation End User: Hospitals, Pharmacies, Clinics, Homecare Therapy Area: Cardiovascular, Oncology, Neurology, Diabetes Distribution Channel: Wholesale, Retail, Online, Direct |
| Companies Covered | Sanofi SA, Viatris Inc, Sandoz International GmbH, Lupin, Sun Pharmaceutical Industries Ltd, Teva Pharmaceutical Industries Ltd, GlaxoSmithKline plc, Dr. Reddy’s Laboratories Ltd, STADA Arzneimittel AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Branded Generics Market Strategic Shifts & Innovations
Continuous manufacturing technologies and digital quality systems are displacing batch-based production paradigms, compressing lead times while tightening regulatory compliance standards across European pharmaceutical operations.
Hot-melt extrusion and spray-dried dispersion technologies are integrating into oral solid dose production lines to enhance bioavailability of poorly soluble APIs. Mid-sized European contract manufacturers are adopting these platforms to secure differentiated branded generic contracts from originator companies divesting mature products. The technology is integrating quality-by-design principles directly into process development, reducing regulatory query cycles.
EMA's strengthened pharmacovigilance requirements under the EU Good Pharmacovigilance Practices mandate real-world evidence collection for all marketed products. This regulatory tightening forces manufacturers to maintain active surveillance infrastructure rather than passive adverse event reporting. Oncology and immunology branded generics face the steepest compliance cost escalation.
Hospital purchasing consortia in France, Italy, and Spain are consolidating tender volumes into multi-year framework agreements with sole or dual-source provisions. This buyer concentration displaces fragmented spot purchasing, rewarding suppliers with demonstrated supply continuity records. German university hospitals pioneered this model; Southern European systems are replicating it rapidly.
Europe Branded Generics Market Segmentation
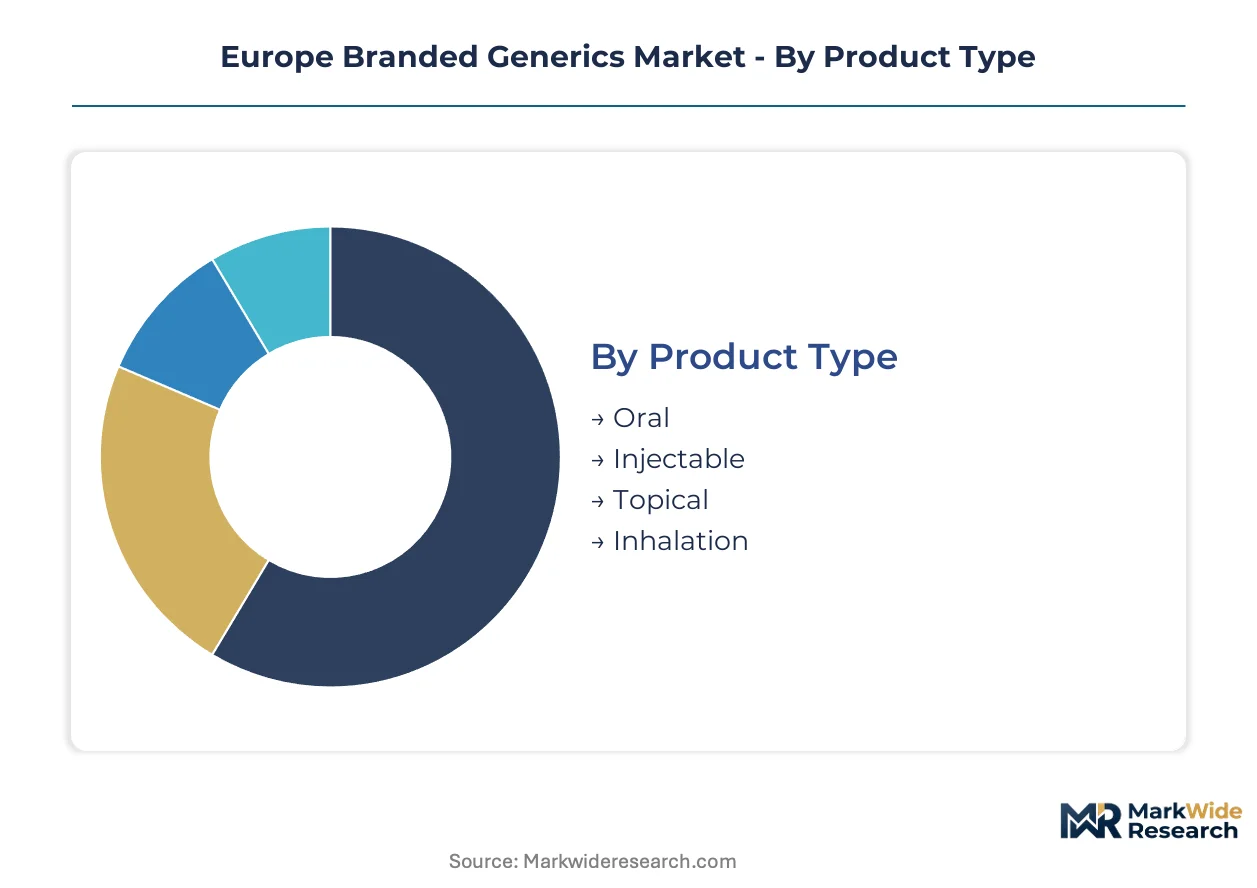
Branded generics manufacturers in Europe deploy differentiated formulations across dosage platforms and therapy areas to capture procurement contracts. Segmentation strategy determines which production capabilities warrant capital investment versus outsourcing partnerships.
Product Type:
Formulation technology dictates regulatory pathway complexity and manufacturing capital intensity across European production facilities.
- Oral:Tablets and capsules utilizing modified-release coatings and fixed-dose combinations dominate volume throughput across German and French pharmacy networks. Demand concentrates in cardiovascular and metabolic therapy areas where patient compliance drives preference for once-daily formulations.
- Injectable:Parenteral dosage forms require aseptic filling lines and dedicated cleanroom infrastructure, limiting viable suppliers to established manufacturers with EMA-certified facilities. Hospital procurement tenders in Italy and Spain prioritize injectable supply security for oncology and critical care applications.
- Topical:Transdermal patches and dermatological creams incorporate proprietary adhesion or penetration technologies for differentiation.
- Inhalation:Dry powder and metered-dose devices demand specialized formulation expertise and device-drug combination regulatory pathways.
Oral dosage forms lead on scale; injectable platforms lead on momentum.
End User:
Procurement sophistication varies sharply across customer categories, compressing margins for fragmented buyers while rewarding supply continuity commitments from consolidated purchasers.
- Hospitals:Centralized purchasing authorities in France and Germany negotiate multi-year framework agreements with volume guarantees and sole-source provisions. EMA serialization compliance and batch traceability function as mandatory qualification criteria.
- Pharmacies:Independent and chain retail dispensaries across Italy and Spain stock branded generics for therapeutic substitution where national reimbursement frameworks permit.
- Clinics:Outpatient specialist centers in Poland and Hungary represent emerging demand for parenteral oncology and immunology products.
- Homecare:Self-administration trends expand addressable market for pre-filled syringes and patient-friendly oral packaging formats.
Hospitals anchor volume concentration; homecare channels expand most quickly.
Therapy Area:
Clinical risk tolerance and supply chain redundancy requirements determine branded generic penetration depth across medical specialties.
- Cardiovascular:Statins, antihypertensives, and anticoagulants constitute the largest volume pool as Germany's AMNOG framework incentivizes therapeutic substitution in hospital discharge protocols.
- Oncology:Cytotoxic injectables and supportive care agents command premium positioning due to sterility requirements and clinician preference for established batch consistency records.
- Neurology:Extended-release formulations for epilepsy and Parkinson's disease leverage proprietary delivery technologies.
- Diabetes:Oral hypoglycemics and insulin delivery devices compete with biosimilar categories in reimbursement-sensitive markets.
Cardiovascular therapy leads on scale; oncology leads on margin expansion.
Distribution Channel:
EU Falsified Medicines Directive compliance infrastructure enables channel restructuring that captures margin through disintermediation.
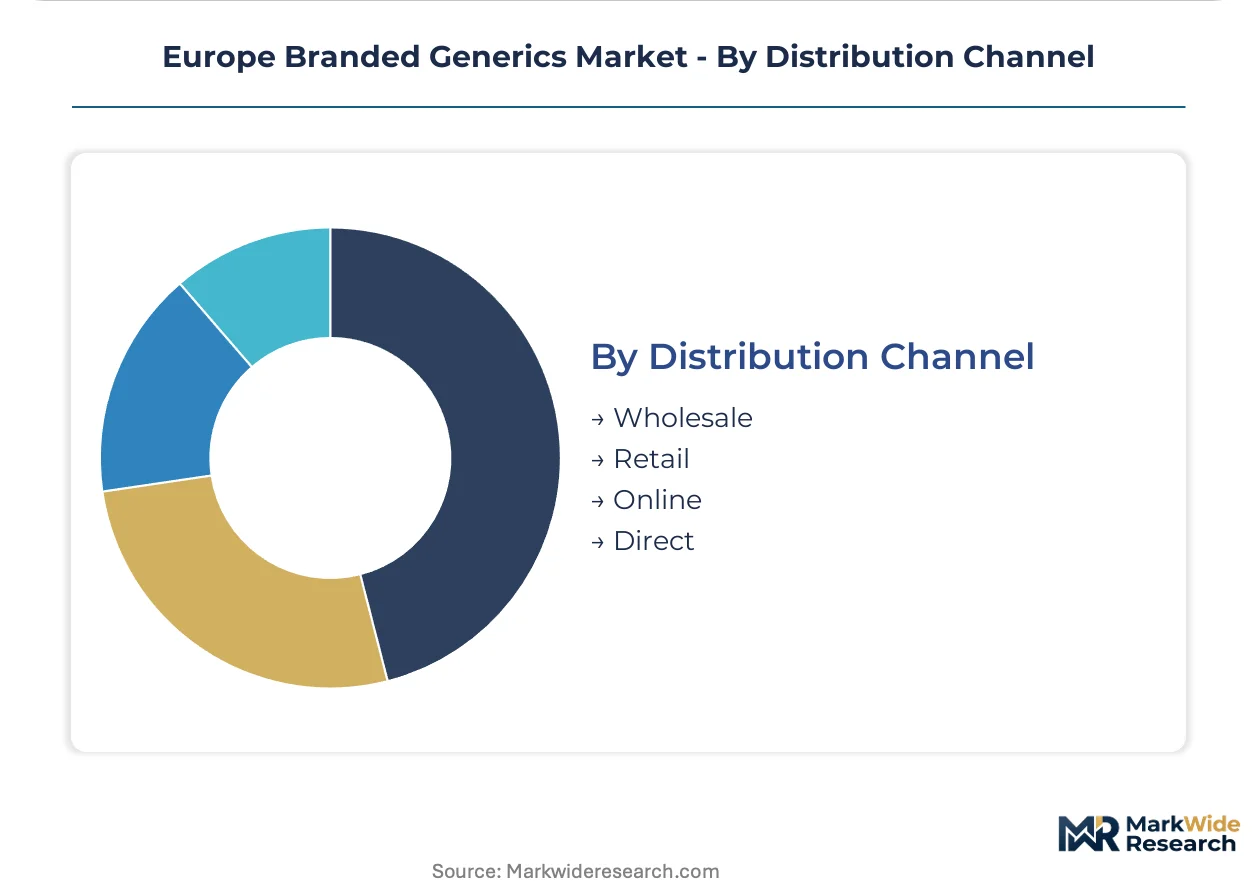
- Wholesale:Traditional full-line distributors across Western Europe retain dominance for fragmented pharmacy accounts requiring credit terms and consolidated delivery.
- Retail:Direct pharmacy contracts with national chains in the UK and Netherlands bypass wholesale markups for high-volume oral solid dose products.
- Online:Verified internet pharmacies under national regulatory supervision expand patient access in markets with geographic pharmacy deserts.
- Direct:Serialized track-and-trace capabilities permit manufacturer-to-hospital shipments for large-volume injectable contracts.
Wholesale channels retain volume leadership; direct distribution gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Person talent pools concentrate in Germany's Rhine-Main and Rhine-Ruhr corridors, anchoring Europe's branded generics manufacturing base. France's Île-de-France region hosts EMA headquarters and dense regulatory affairs expertise. Italy's Emilia-Romagna and Lombardy clusters specialize in sterile injectable production for hospital networks.
Germany
AMNOG therapeutic substitution policies drive hospital formulary adoption of cardiovascular and metabolic branded generics. The Federal Joint Committee (G-BA) mandates health technology assessments that favor bioequivalent alternatives with established batch consistency. Frankfurt's Rhine-Main corridor hosts manufacturing facilities serving pan-European hospital procurement consortia.
France
CEPS pricing protocols and hospital purchasing consolidation elevate contract security as the decisive tender criterion over unit price. ANSM pharmacovigilance requirements enforce real-world evidence collection for oncology and immunology products. Paris-Île-de-France anchors regulatory strategy functions for companies targeting Southern European markets.
Italy
Regional health authorities in Lombardy and Emilia-Romagna negotiate multi-year framework agreements with sole-source provisions for critical care injectables. AIFA national reimbursement listings require demonstrated supply continuity records. Milan's pharmaceutical cluster specializes in aseptic filling capacity for cytotoxic and supportive care agents.
Spain
Autonomous community purchasing consortia in Catalonia and Madrid consolidate tender volumes into multi-year agreements with dual-source security requirements. AEMPS marketing authorization procedures align with EMA centralized pathways for cross-border registration. Barcelona's contract manufacturing base serves Portuguese and North African export markets.
Poland
Hospital procurement modernization in Masovia and Silesia creates first-mover opportunities for Western suppliers with EMA serialization compliance. The Polish Ministry of Health's reimbursement framework expands therapeutic substitution for chronic disease management. Warsaw's emerging pharma cluster attracts qualified personnel from neighboring Baltic states.
Europe Branded Generics Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. Market structure concentrates around three to five integrated manufacturers with pan-European distribution infrastructure, while mid-scale formulators occupy niche dosage or therapy segments. Strategic archetypes include originator-divestiture specialists, complex generic technology platforms, and hospital-contract anchoring operations. Dominant competitive moves encompass portfolio diversification through mature product acquisitions and manufacturing scale expansion in Central European markets.
Within the diversified pharmaceutical tier, Sanofi SA and Viatris Inc exemplify contrasting strategic positions. Sanofi SA leverages established brand equity and hospital supply relationships across Western European markets. Viatris Inc anchors manufacturing scale across multiple dosage platforms. Sandoz International GmbH occupies a specialized position in complex injectable and biosimilar-adjacent portfolios. These three entities represent the primary competitive anchors shaping procurement dynamics and pricing benchmarks across national tender systems.
| Leading Market Players |
|---|
| Sanofi SA |
| Viatris Inc |
| Sandoz International GmbH |
| Lupin |
| Sun Pharmaceutical Industries Ltd |
| Teva Pharmaceutical Industries Ltd |
| GlaxoSmithKline plc |
| Dr. Reddy's Laboratories Ltd |
| STADA Arzneimittel AG |
| Others |
Cost & Logistics Intelligence
Active pharmaceutical ingredient feedstock costs from Indian and Chinese manufacturers cascade through formulation, packaging, and distribution tiers before reaching hospital procurement consortia across Germany, France, and Italy. EMA serialization mandates add EUR 0.02-0.05 per unit in compliance overhead, compressing margins for standard oral generics while protecting premium positioning for complex injectables with sterility-assured batch records.
Pricing Analysis
Bundled multi-year hospital supply contracts incorporating batch traceability, pharmacovigilance data, and stockholding guarantees command 15-25% premiums over unbundled spot purchasing from fragmented pharmacy buyers. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and therapeutic criticality. Cost compression in the oral solid dose segment is intensifying as German AMNOG therapeutic substitution policies expand qualified supplier lists. Hospital purchasing consortia exhibit lowest price sensitivity due to sole-source security requirements, while independent pharmacies in Southern Europe face acute margin pressure.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume injectable contracts for oncology and critical care applications across French and Italian hospital networks. API manufacturing concentrates in India, China, and Switzerland, with European formulators dependent on imported raw materials for 60-70% of off-patent molecules. Excipient sourcing draws from German and Dutch chemical clusters, creating dual-dependency exposure. Single-source vulnerability in aseptic filling capacity for cytotoxic products represents the dominant structural risk. Distribution runs through traditional full-line wholesalers for fragmented pharmacy accounts, while serialized track-and-trace infrastructure enables manufacturer-direct hospital shipments for framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Branded Generics Market functions as a regulatory compounder where EU Falsified Medicines Directive serialization mandates and national tender consolidation create structural advantages for compliant incumbents with established Qualified Person networks.
For Market Incumbents: Lock in multi-year hospital framework agreements before Central and Eastern European procurement modernization attracts new entrants. Expand aseptic filling capacity in Italy's Emilia-Romagna cluster to capture oncology injectable premiums. Invest in backward integration into API sourcing for high-volume cardiovascular molecules to offset geopolitical disruption risks from Indian and Chinese supply concentration.
For New Entrants and Emerging Players: Capture underpenetrated hospital procurement channels in Poland and Romania where EMA serialization compliance remains scarce among local suppliers. Target parenteral oncology and immunology segments where sterility requirements limit viable competitors. Establish partnerships with established Italian contract manufacturers for aseptic production qualification rather than greenfield facility investment.
For Investors and Strategic Acquirers: Consolidation pressure builds where Qualified Person talent scarcity constrains manufacturing expansion timelines for mid-scale formulators. Position portfolios for 5-10 year horizon returns centered on hospital-contract anchoring operations with demonstrated supply continuity records. Monitor EMA interchangeability rulings for biosimilar categories as the critical inflection signal that could recategorize value-added branded generics into commodity segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Aseptic filling capacity expansion in Italy's Lombardy cluster captures oncology injectable premiums from hospital tenders. |
| Regulatory Approval Pathway | EMA centralized procedures accelerate cross-border registration for manufacturers with established quality management systems. |
| Backward Integration | In-house API production for high-volume cardiovascular molecules reduces exposure to Indian and Chinese supply disruption. |
| Hospital System Partnership | Multi-year framework agreements with French and German purchasing consortia secure volume guarantees and sole-source provisions. |
| Pipeline Diversification | Complex generic acquisitions in neurology and diabetes therapeutic areas expand addressable procurement contract pools. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down API import tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors, hospital formulary managers, pharmaceutical manufacturing executives, and GPO contract specialists were validated against EMA marketing authorization databases, national tender publication records, and REACH excipient registration filings. Secondary sources include customs trade data for API shipments, AMNOG health technology assessment documentation, and CEPS pricing protocol publications.
Historical trendline analysis of formulation technology adoption, therapeutic substitution policy expansion, and hospital purchasing consolidation patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated dosage form complexity, therapy area clinical risk tolerance, distribution channel structure, and regional regulatory cluster variations. CAGRs were derived from volume-weighted average growth trajectories calibrated to documented tender award patterns and manufacturing capacity expansion announcements.
Geopolitical disruption in API supply chains, EMA biosimilar interchangeability rulings, and Qualified Person talent availability constraints are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
GCC Generic Drug Market
Generics and Biosimilars
Super Generics Market
Generics and Biosimilars
West Africa Generic Drug Market
Generics and Biosimilars
Europe Specialty Generics Market
Generics and Biosimilars
Latin America Generic Drug Market
Generics and Biosimilars
US Specialty Injectable Generics Market
Generics and Biosimilars
Global Adalimumab Drugs Market
Generics and Biosimilars
Adalimumab Market