
 Latin America Generic Drug Market | 2026-2036
Latin America Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Generic Drug Market Intelligence
WHO prequalification status is unwinding competitive access across Latin America, as only manufacturers meeting international bioequivalence standards secure tenders from large public purchasers. Eurofarma leverages its vertically integrated manufacturing base in Brazil to dominate federal procurement cycles. Tecnoquímicas anchors Andean supply through its Colombian production network and deep wholesaler relationships.
Generic drugs are chemically equivalent copies of originator pharmaceuticals, manufactured after patent expiry and required to demonstrate bioequivalence through pharmacokinetic studies comparing plasma concentration profiles. They deliver identical therapeutic outcomes at reduced cost, serving as the backbone of public health procurement across Latin America. Tablet formulations occupy the largest volume share due to stability advantages and patient compliance, while injectable generics capture premium positioning in hospital settings where sterility requirements raise barriers to entry. Cardiovascular therapy areas sustain the deepest generic penetration, whereas oncology biosimilars represent the fastest-expanding margin pool as biologic patents expire.
ANVISA enforces bioequivalence mandates and GMP inspections that determine which manufacturers qualify for Brazil's public tenders, while COFEPRIS in Mexico operates accelerated approval pathways for generics meeting US FDA or EMA standards. These dual regulatory frameworks concentrate market access among firms with multinational certification portfolios. Stakeholders must monitor pending harmonization initiatives across Mercosur and the Pacific Alliance, as mutual recognition agreements could reshape which production sites serve cross-border demand.
Market Dynamics
ANVISA's 2024 bioequivalence mandate is compressing supplier pools across Brazil's public procurement, forcing manufacturers to rebuild quality systems around international inspection standards or exit federal tenders entirely.
Growth Catalysts
- ANVISA Streamlined Registration:Brazil's updated generic pathways reduce approval timelines for manufacturers holding US FDA or EMA certifications, accelerating market entry for qualified foreign suppliers.
- Sistema Único de Saúde Volume Expansion:Brazil's unified health system is expanding chronic disease formularies, driving sustained procurement of cardiovascular and diabetes generics through centralized federal purchasing.
- COFEPRIS Accelerated Pathways:Mexico's regulator grants priority review to generics with prior FDA approval, compressing time-to-market for multinational manufacturers targeting IMSS and ISSSTE tenders.
Market Restraints
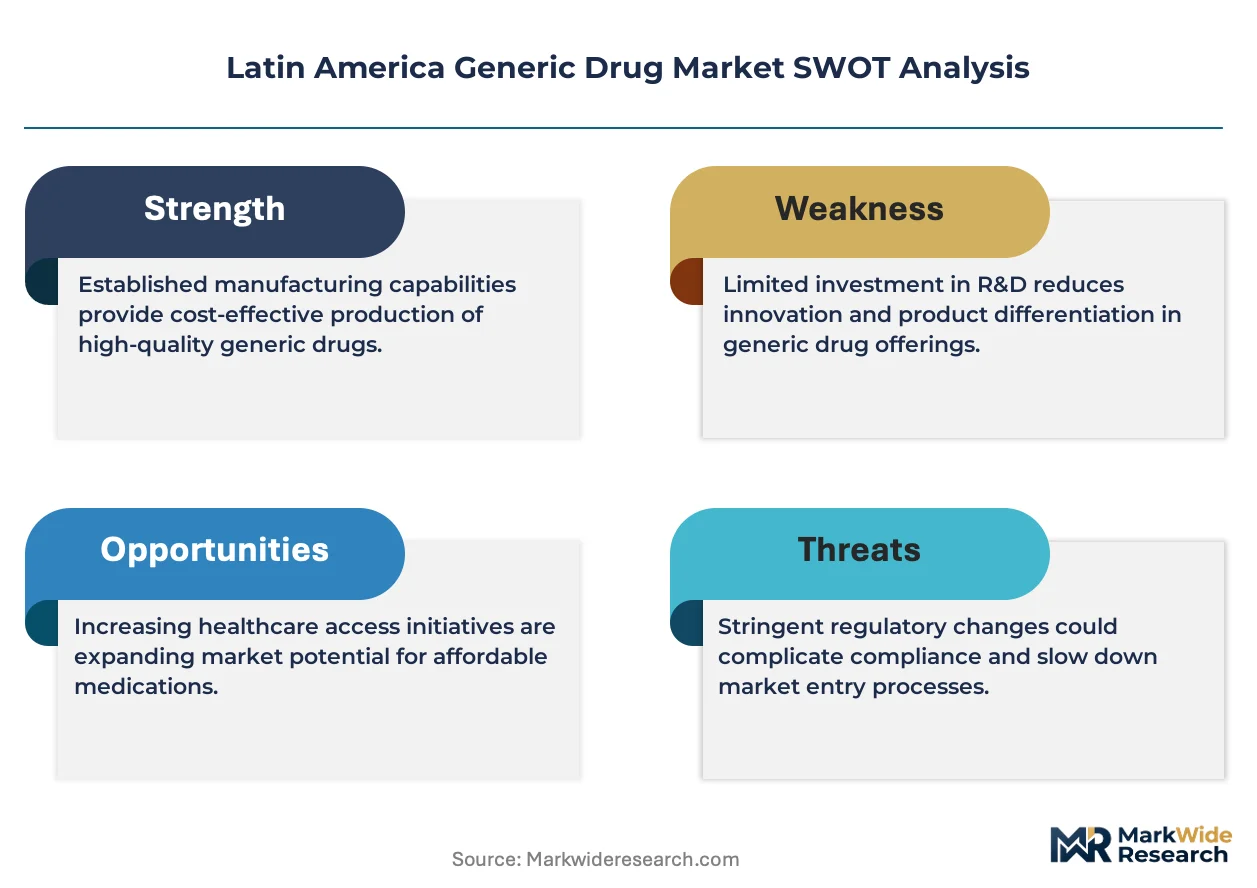
- Active Pharmaceutical Ingredient Dependence:Latin American finished dose manufacturers source over 80% of APIs from Indian and Chinese suppliers, exposing margins to freight volatility and currency swings.
- Bioequivalence Study Capacity Bottleneck:Brazil and Mexico host limited certified clinical pharmacology units, creating queues that delay generic submissions and extend regulatory timelines.
- Originator Patent Thickets:Secondary patents on formulation modifications and dosing regimens block generic entry in oncology and respiratory categories despite compound patent expiry.
Strategic Opportunities
- Andean Wholesaler Consolidation:Colombia's Tecnoquímicas and Genfar distribution networks remain fragmented, creating acquisition targets for Brazilian and Mexican manufacturers seeking Andean market access.
- Biosimilar Infrastructure Gap:Cold chain biologics manufacturing capacity is concentrated in São Paulo and Mexico City, leaving Argentina, Chile, and Peru dependent on imports for insulin and monoclonal antibodies.
- IMSS Direct Contracting Pilot:Mexico's social security institute is testing manufacturer-direct purchasing for high-volume generics, bypassing traditional distributor markups for qualified suppliers.
Industry Challenges
- Qualified Person Shortage:Brazil and Mexico lack sufficient pharmacists and chemists trained in EU GMP Annex standards, forcing manufacturers to recruit from Spain and Portugal at premium compensation.
- Legacy ERP Integration:Mid-size Argentine and Colombian manufacturers operate on disconnected inventory and batch record systems, complicating traceability requirements for ANVISA and COFEPRIS inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Generic Drug Market |
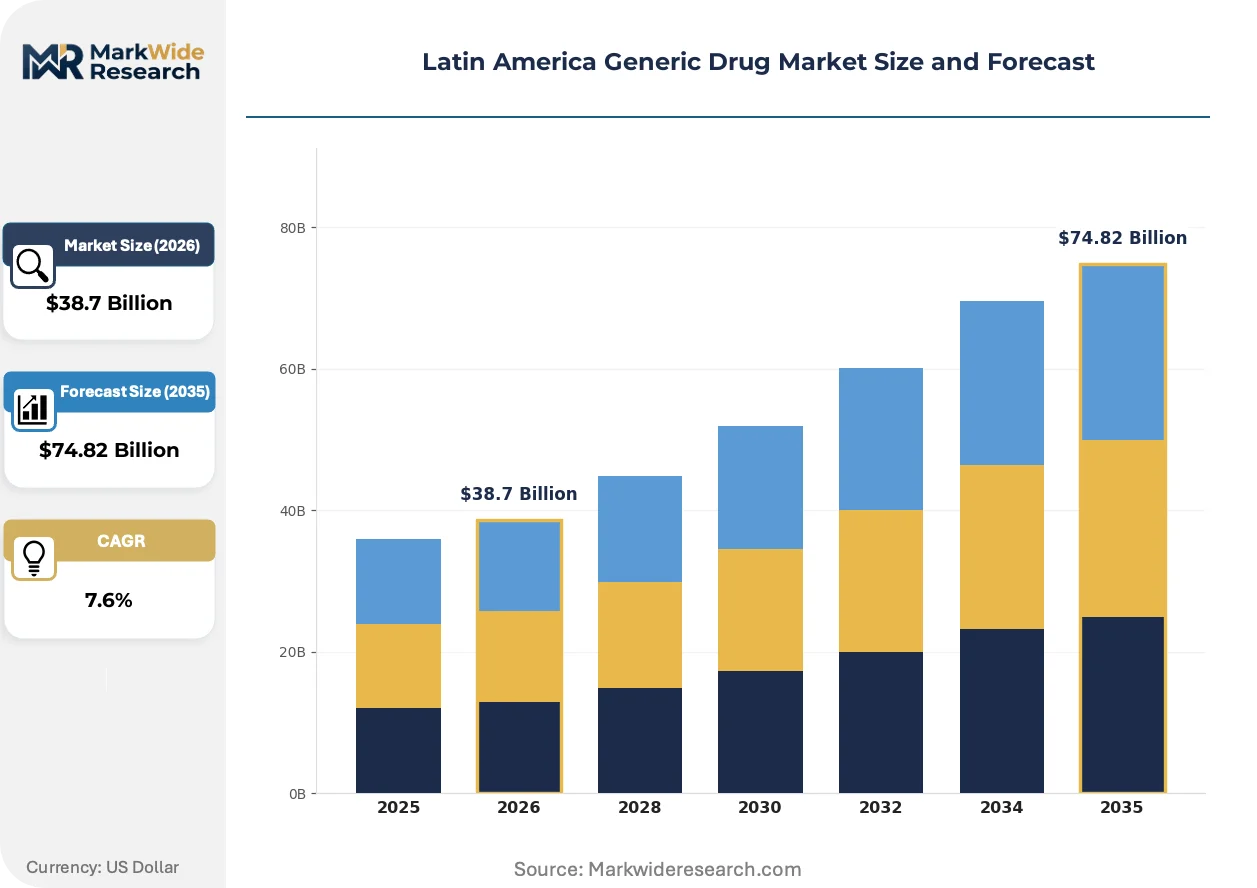
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $74.82 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injectable, Topical End User: Pharmacies, Hospitals, Clinics, Long-term Care Facilities Distribution Channel: Wholesale, Retail, Online, Direct Sales Therapy Area: Cardiovascular, Oncology, Neurology, Infectious Diseases |
| Companies Covered | Pfizer, Tecnoquímicas, Hypera Pharma, Merck, Bayer, Eurofarma, Viatris, GlaxoSmithKline, Novartis (Sandoz), Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Generic Drug Market Strategic Shifts & Innovations
Continuous manufacturing and real-time release testing are displacing batch processing in Latin American generic facilities, while regulatory data harmonization initiatives reshape cross-border supply patterns.
Continuous direct compression systems are fragmenting the traditional batch-oriented manufacturing model in Brazilian tablet production. Eurofarma and EMS have installed continuous lines at their São Paulo state facilities, cutting cycle times from weeks to hours. This technology is fragmenting competitive advantage away from scale economies toward process analytical technology capabilities and real-time quality control integration.
COFEPRIS and ANVISA are converging bioequivalence study protocols around ICH M13A guidelines, eliminating redundant local clinical trials for generics already approved by FDA or EMA. This harmonization reduces registration costs for multinational manufacturers but raises compliance barriers for domestic firms lacking international certification portfolios. Brazilian cardiovascular and anti-infective generics are experiencing the fastest protocol convergence, with Mexican regulators accepting foreign reference products for bioequivalence comparisons.
Public hospital consortia in São Paulo, Minas Gerais, and Rio Grande do Sul are consolidating purchasing volumes through regional procurement blocs, displacing fragmented municipal tendering. These blocs negotiate directly with manufacturers for multi-year supply agreements, extracting price concessions in exchange for volume guarantees. The concentration is most advanced in Brazil's southeast, where state-level health secretariats now coordinate formularies and supplier qualification across dozens of municipalities simultaneously.
Latin America Generic Drug Market Segmentation
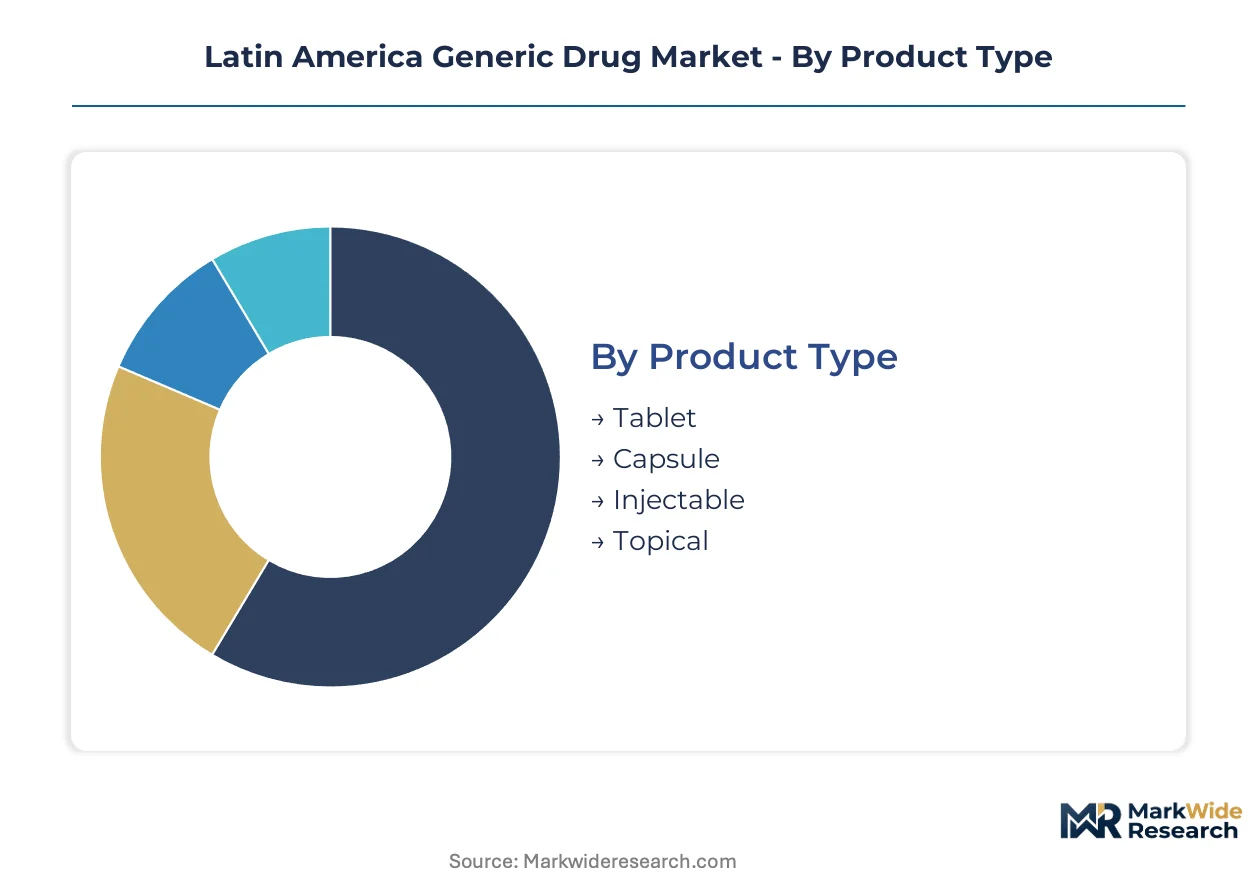
Segmentation in Latin America's generic drug market reveals how regulatory requirements, procurement structures, and patient access patterns concentrate demand across distinct product categories and channel configurations. Understanding these divisions exposes where bioequivalence mandates, cold chain infrastructure, and tender participation rules create divergent competitive dynamics.
Product Type:
ANVISA and COFEPRIS apply differentiated stability testing and manufacturing standards across solid and liquid dosage forms, fragmenting supplier qualification requirements.
- Tablet:Compressed solid dosages dominate outpatient dispensing through Brazil's Sistema Único de Saúde due to extended shelf stability and simplified logistics. Federal procurement for hypertension and diabetes maintenance therapies drives volume concentration in São Paulo and Minas Gerais manufacturing corridors.
- Injectable:Sterile parenteral formulations require aseptic filling lines and endotoxin testing that filter out smaller manufacturers from hospital tender participation. Demand clusters in tertiary care facilities across Mexico City and Rio de Janeiro where surgical and oncology protocols mandate IV administration.
- Capsule:Gelatin or HPMC shells accommodate moisture-sensitive APIs with modified release profiles for neurological and psychiatric indications.
- Topical:Creams, ointments, and transdermal patches serve dermatology and pain management clinics with lower regulatory barriers than sterile manufacturing.
Tablets handle the majority of throughput; injectables are gaining share fastest as hospital procurement consolidates around higher-barrier formulations.
End User:
Procurement scale and payment reliability separate institutional purchasers from fragmented retail dispensers across the region's healthcare systems.
- Hospitals:Inpatient facilities in Brazil's southeast and Mexico's central region negotiate multi-year supply agreements through consolidated purchasing blocs. ANVISA's GMP inspection requirements and COFEPRIS bioequivalence documentation filter supplier pools to manufacturers with multinational certification portfolios.
- Pharmacies:Community dispensaries in Colombia and Argentina operate on cash-and-carry terms with regional distributors, exposing margins to currency volatility and inventory carrying costs.
- Clinics:Outpatient specialty centers concentrate demand for chronic disease management in urban corridors.
- Long-term Care Facilities:Nursing homes and rehabilitation centers generate steady demand for polypharmacy regimens in aging population clusters.
Hospitals absorb the largest procurement volumes; long-term care facilities are climbing fastest on share as demographic shifts expand institutionalized elder care.
Distribution Channel:
Channel selection determines working capital intensity and regulatory traceability burdens for manufacturers serving distinct customer tiers.
- Wholesale:Regional distributors in São Paulo, Mexico City, and Bogotá aggregate fragmented pharmacy demand while managing ANVISA and COFEPRIS batch documentation requirements. These intermediaries absorb credit risk from smaller retail accounts but extract margin spreads that compress manufacturer returns.
- Direct Sales:IMSS pilot programs and Brazilian state procurement blocs enable qualified manufacturers to bypass distributor markups through tender-based contracting.
- Retail:Chain pharmacies and independent dispensaries serve insured and out-of-pocket patients with immediate fulfillment.
- Online:E-pharmacy platforms face regulatory ambiguity across Mercosur jurisdictions regarding prescription validation and cold chain verification.
Wholesale channels move the bulk of volume; direct sales are expanding most quickly as public purchasers test manufacturer bypass models.
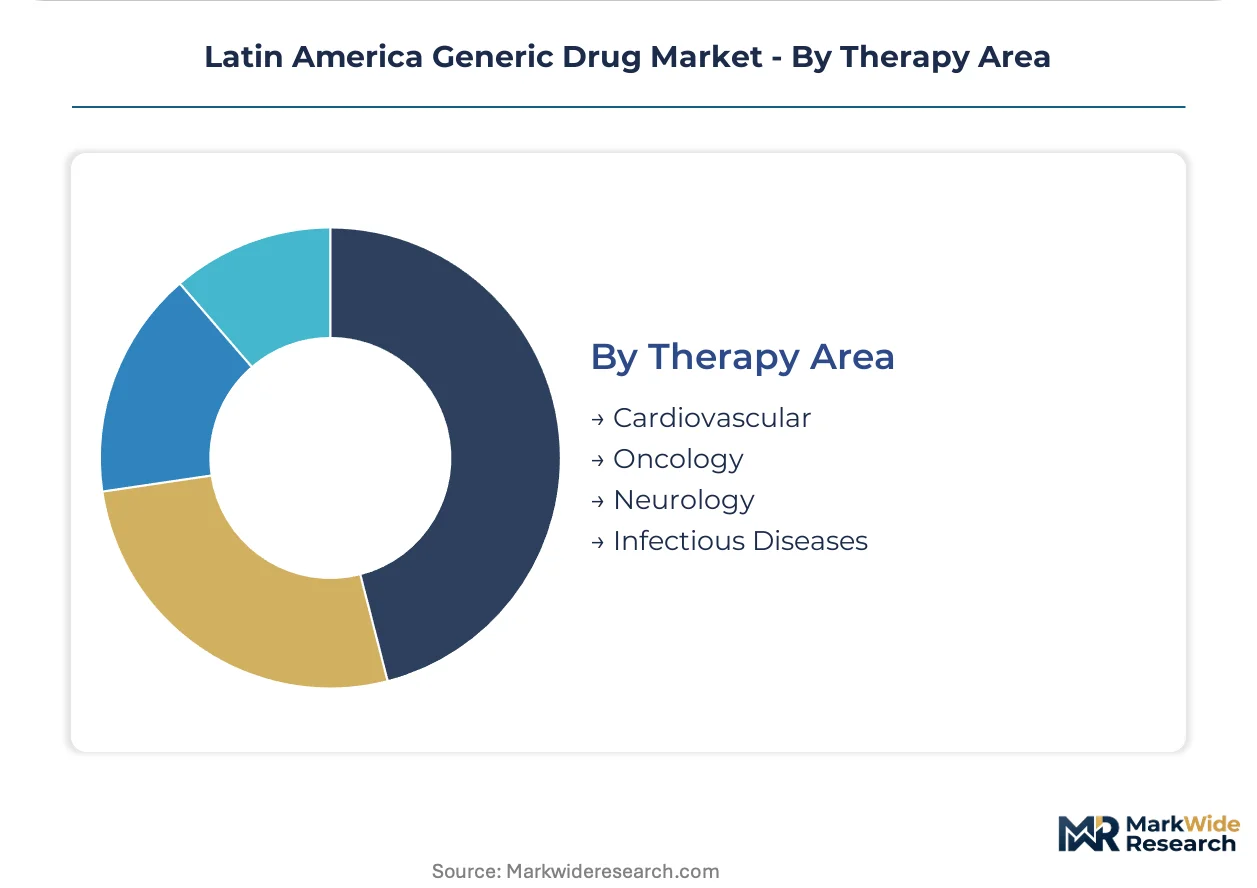
Therapy Area:
Patent expiry schedules and clinical trial infrastructure availability create staggered generic entry opportunities across disease categories.
- Cardiovascular:Statins, ACE inhibitors, and antihypertensives sustain the deepest generic penetration following decades of compound patent expiries. Brazil's SUS and Mexico's IMSS maintain open formularies for these categories, driving volume through centralized federal tenders with aggressive price competition.
- Oncology:Biosimilar monoclonal antibodies and cytotoxic generics command premium positioning as biologic patents expire, though cold chain requirements and bioanalytical testing capacity constrain supplier participation.
- Infectious Diseases:Antibiotic and antiviral generics face procurement concentration through national immunization programs and HIV/AIDS treatment initiatives.
- Neurology:CNS-active compounds with narrow therapeutic indices require specialized bioequivalence study designs that extend regulatory timelines.
Cardiovascular therapies carry the heaviest volume load; oncology is the steepest expansion trajectory as biosimilar pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public hospital procurement concentrates demand across Brazil, Mexico, and Argentina, where federal health systems drive volume through centralized tendering. ANVISA and COFEPRIS bioequivalence mandates filter supplier access, while state-level purchasing blocs extract price concessions through multi-year agreements.
Brazil
Sistema Único de Saúde procurement absorbs the region's largest generic volumes through federal tenders for cardiovascular and diabetes therapies. ANVISA's 2024 bioequivalence mandate compresses qualified supplier pools, forcing manufacturers to rebuild quality systems around international inspection standards. São Paulo state hosts Eurofarma's vertically integrated manufacturing base, which dominates federal procurement cycles through continuous direct compression lines.
Mexico
Instituto Mexicano del Seguro Social and ISSSTE tenders concentrate demand for chronic disease generics across Mexico City and central region hospitals. COFEPRIS grants priority review to manufacturers holding FDA or EMA certifications, accelerating market entry for qualified foreign suppliers. The IMSS direct contracting pilot enables selected manufacturers to bypass traditional distributor markups through tender-based purchasing agreements.
Argentina
Provincial health ministries in Buenos Aires, Córdoba, and Santa Fe negotiate fragmented tenders for anti-infective and cardiovascular generics amid currency volatility. The national pharmaceutical regulator maintains bioequivalence requirements aligned with Mercosur harmonization initiatives, though enforcement capacity lags Brazil and Mexico. Buenos Aires province anchors domestic manufacturing through legacy facilities serving local hospital networks.
Colombia
Tecnoquímicas anchors Andean supply through its Colombian production network and deep wholesaler relationships across Bogotá and Medellín distribution corridors. The national health regulator applies stability testing standards that filter smaller manufacturers from institutional procurement participation. Antioquia and Cundinamarca departments concentrate manufacturing capacity for regional export to Ecuador and Peru.
Chile
FONASA procurement drives generic substitution programs through centralized hospital purchasing in Santiago and Valparaíso metropolitan regions. The national pharmaceutical agency enforces bioequivalence documentation requirements that favor manufacturers with multinational certification portfolios. Biobío and Araucanía regions remain dependent on imported cold chain biologics due to limited local sterile manufacturing infrastructure.
Latin America Generic Drug Market Key Industry Players
Player mix skews toward multinational pharmaceutical corporations with established certification portfolios alongside domestic vertically integrated manufacturers. Market structure concentrates around firms capable of meeting ANVISA and COFEPRIS bioequivalence mandates while sustaining participation in federal tender cycles. Three archetypes dominate: multinational originators with generic divisions, domestic vertically integrated manufacturers, and regional specialists with deep wholesaler relationships. Competitive dynamics center on M&A targeting Andean distribution networks and capacity expansion into continuous manufacturing platforms.
Among multinational pharmaceutical corporations, Pfizer and Novartis (Sandoz) occupy positions representing originator-to-generic strategic pivots, leveraging multinational certification portfolios to accelerate regulatory pathways across Brazil and Mexico. Eurofarma exemplifies the domestic vertically integrated archetype, anchoring competitive positioning through São Paulo state manufacturing infrastructure and federal procurement dominance. Tecnoquímicas represents the regional specialist model, with Colombian production networks and Andean wholesaler relationships filtering market access for competitors seeking Pacific Alliance expansion.
| Leading Market Players |
|---|
| Pfizer |
| Tecnoquímicas |
| Hypera Pharma |
| Merck |
| Bayer |
| Eurofarma |
| Viatris |
| GlaxoSmithKline |
| Novartis (Sandoz) |
| Others |
Cost & Logistics Intelligence
Multi-year offtake agreements between Brazilian state procurement blocs and ANVISA-certified manufacturers lock in supply access for Sistema Único de Saúde formularies while anchoring price visibility through volume-guaranteed contracting cycles. These arrangements concentrate purchasing power in São Paulo and Minas Gerais health secretariats, compressing margins for suppliers unable to meet bioequivalence mandates or sustain continuous manufacturing scale.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate procurement negotiations, tying finished dose prices to Indian and Chinese API market movements. Three-tier pricing structure across WHO-prequalified, ANVISA-certified, and non-certified supply tiers reflects quality grade and regulatory investment differentiation. Cost compression in economy-tier tablet categories is intensifying because of consolidated state-level tendering. Municipal pharmacies exhibit highest price sensitivity; tertiary hospital oncology units demonstrate lowest sensitivity due to cold chain sterility requirements.
Supply Chain Analysis
Strategic stockpiling of cardiovascular and diabetes APIs characterizes procurement behavior among Brazilian and Mexican manufacturers facing freight volatility from Asian supply origins. API manufacturing concentrates in India, China, and selected European specialist producers. Finished dose production draws from gelatin, HPMC, and sterile vial packaging inputs. Single-source vulnerability pervades insulin and monoclonal antibody supply. Distribution runs through São Paulo, Mexico City, and Bogotá wholesale corridors serving fragmented retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American generic procurement is approaching a platform-economics inflection as ANVISA and COFEPRIS data harmonization creates interoperability between national regulatory repositories, enabling cross-border supplier qualification and consolidated purchasing consortiums.
For Market Incumbents: Shield federal tender positions by accelerating backward integration into API synthesis capabilities, reducing exposure to Indian and Chinese currency swings. Lock in multi-year supply agreements with emerging Andean procurement blocs before regional consolidation completes. Certification investment in continuous manufacturing platforms represents the critical defensive lever against multinational entrants leveraging FDA and EMA fast-track recognition. For New Entrants and Emerging Players: COFEPRIS accelerated approval pathways for FDA-certified products offer the fastest regulatory entry into IMSS and ISSSTE tender participation. Target biosimilar cold chain categories in Chile and Peru where sterile manufacturing infrastructure gaps persist. Pursue white-label manufacturing partnerships with Colombian distributors seeking Andean market expansion without captive production assets. For Investors and Strategic Acquirers: Mid-size Argentine manufacturers with legacy GMP facilities and established provincial hospital relationships represent acquisition targets for platform consolidation plays. Long-term viability hinges on regulatory data harmonization completion across Mercosur and Pacific Alliance jurisdictions. Watch for IMSS direct contracting pilot expansion as signal of distributor disintermediation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Eurofarma's São Paulo direct compression lines compress cycle times from weeks to hours. |
| Regulatory Certification Fast-Track | COFEPRIS priority review for FDA-approved generics accelerates IMSS tender eligibility. |
| Andean Distribution Network Acquisition | Tecnoquímicas wholesaler relationships filter Pacific Alliance market access for competitors. |
| API Backward Integration | Domestic synthesis capabilities reduce freight volatility exposure from Indian suppliers. |
| Biosimilar Cold Chain Infrastructure | Insulin and monoclonal antibody capacity gaps in Argentina and Chile create import-dependent demand. |
Research Approach
Desk research of ANVISA registration databases, COFEPRIS approval filings, and Sistema Único de Saúde tender records preceded structured interviews with regulatory affairs directors, hospital procurement managers, and pharmaceutical distribution executives. Secondary validation drew from FDA Orange Book listings, EMA bioequivalence study summaries, and WHO prequalification registers. Bottom-up volume modeling triangulated against top-down macroeconomic health expenditure projections.
Variance decomposition across dosage form, therapy area, and regulatory certification tier segments isolates growth contribution by category throughout the forecast period. CAGRs were derived from regression analysis of historical procurement volume trends against projected formulary expansion. Modeled inputs include ANVISA inspection capacity constraints, COFEPRIS harmonization timeline assumptions, and API price index trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained SUS and IMSS funding levels and progressive regulatory harmonization; material deviation in public health budget allocation or Mercosur mutual recognition delays would warrant model refresh. Revision becomes warranted when API import dependency ratios or bioequivalence study queue lengths cross thresholds that alter manufacturer competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
Global Adalimumab Drugs Market
Generics and Biosimilars
Adalimumab Market
Generics and Biosimilars
Super Generics Market
Generics and Biosimilars
West Africa Generic Drug Market
Generics and Biosimilars
US Specialty Injectable Generics Market
Generics and Biosimilars
GCC Generic Drug Market
Generics and Biosimilars
Europe Specialty Generics Market
Generics and Biosimilars
Europe Branded Generics Market