
 Adalimumab Market | 2026-2036
Adalimumab Market Size, Share, and Industry Trends Forecast 2026-2036
Adalimumab Market Analysis
Specialty pharmacy buyers is bifurcating between originator-loyal accounts and cost-driven biosimilar switchers. AbbVie anchors its position through chronic disease program investments and patient support infrastructure. Amgen leverages its established biologics manufacturing network to compete on supply reliability. Samsung Bioepis differentiates through competitive pricing and European regulatory precedents that smooth FDA reviews.
Adalimumab is a recombinant human monoclonal antibody that binds tumor necrosis factor-alpha, manufactured through mammalian cell culture in Chinese hamster ovary systems at titers exceeding five grams per liter. It suppresses systemic inflammation in autoimmune conditions by neutralizing soluble and transmembrane TNF. The therapy area segmentation shows rheumatoid arthritis maintains the largest patient pool, while Crohn's disease represents the fastest-expanding indication as gastroenterologists expand biologic penetration. Product type segmentation reveals biosimilars are displacing reference volumes in European markets first, with injectable formulations capturing margin pools through convenience premiums over vial presentations.
FDA biosimilar interchangeability designations and EMA biosimilar approval pathways shape prescriber confidence and pharmacy substitution rights across the United States and European markets. The country's national pharmaceutical regulator in India, CDSCO, governs biosimilar licensing through its unique similar biologics framework, creating a distinct access corridor for domestic manufacturers. Stakeholders must monitor evolving interchangeability state legislation and payer rebate structures to determine whether to defend originator share or accelerate biosimilar portfolio transitions.
Market Dynamics
Biosimilar interchangeability designations are fragmenting prescriber loyalty and rewiring pharmacy substitution economics across the United States and European markets.
Growth Catalysts
- FDA Interchangeability Pathway:The United States regulator's designation allows pharmacy-level substitution without prescriber consultation, accelerating biosimilar volume capture.
- Chinese Hamster Ovary Titers:Mammalian cell culture yields exceeding five grams per liter compress manufacturing costs and expand supply elasticity for biosimilar producers.
- Rheumatology Clinic Expansion:Specialist practices in the United States are expanding biologic penetration into moderate disease severity patients previously managed with conventional DMARDs.
Market Restraints
- Originator Rebate Walls:AbbVie's contracting structures with United States pharmacy benefit managers create formulary exclusion barriers that delay biosimilar access.
- Immunogenicity Surveillance Burden:Post-market pharmacovigilance requirements for biosimilars impose ongoing clinical trial obligations that compress margins.
- Subcutaneous Formulation Complexity:Citrate-free and high-concentration device innovations require capital-intensive manufacturing retooling that limits competitor entry.
Strategic Opportunities
- CDSCO Similar Biologics Framework:India's distinct regulatory pathway creates a streamlined corridor for domestic manufacturers to supply emerging markets with lower-cost alternatives.
- Gastroenterology Biologic Naivety:Crohn's disease and ulcerative colitis patient pools remain underpenetrated relative to rheumatoid arthritis, offering indication expansion runway.
- Auto-Injector Convenience Premium:Device differentiation around injection pain reduction and travel portability commands pricing power in patient-directed pharmacy channels.
Industry Challenges
- Pharmacovigilance Talent Scarcity:Biosimilar sponsors struggle to recruit immunogenicity specialists capable of designing equivalence trials that satisfy FDA and EMA reviewers.
- Legacy Patient Support Infrastructure:Originators have built decades of hub services and copay assistance programs that create switching friction even after patent expiry.
- Cold Chain Integrity Costs:Temperature-controlled distribution requirements for protein therapeutics inflate logistics spend and complicate pharmacy inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adalimumab Market |
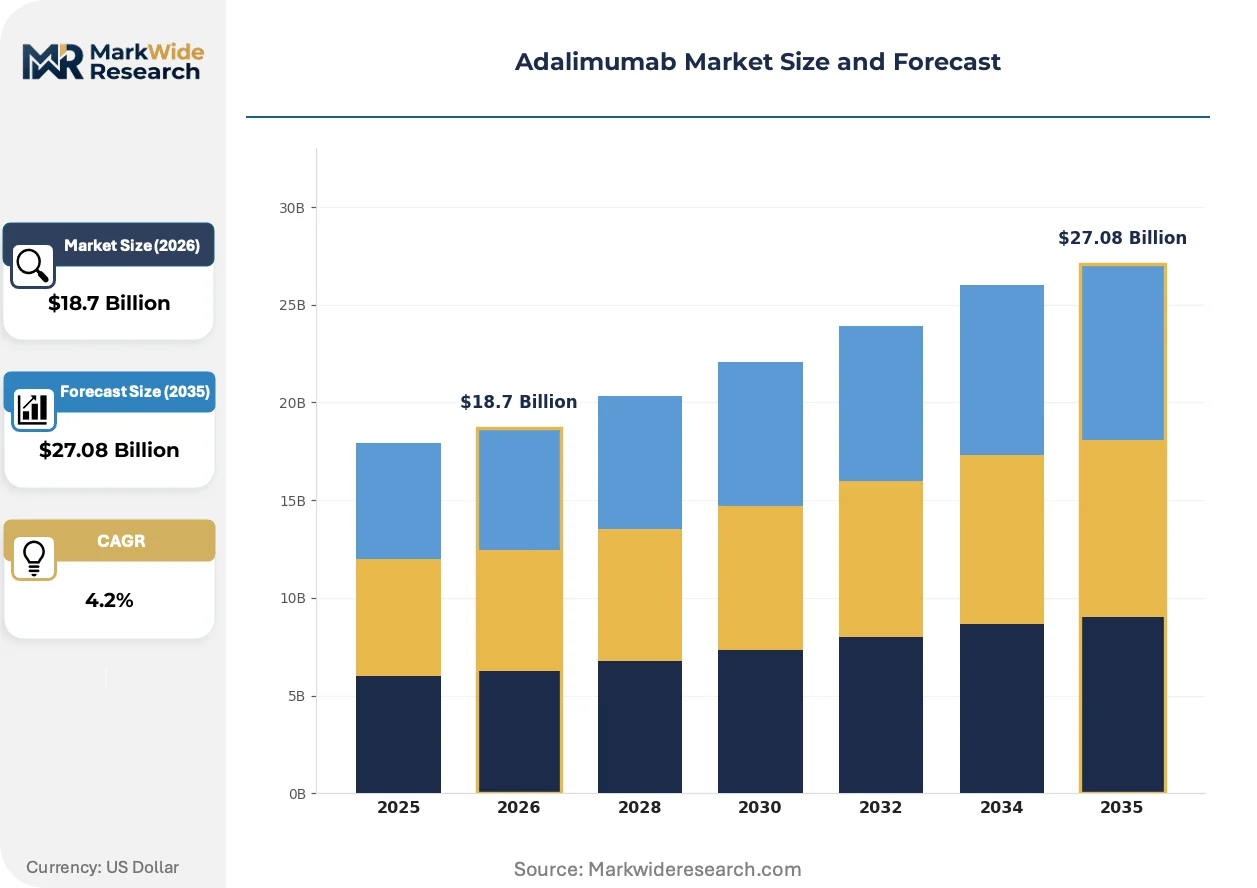
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Biosimilar, Reference, Combination Therapy Area: Rheumatoid Arthritis, Psoriasis, Crohn's Disease, Ulcerative Colitis End User: Hospitals, Clinics, Home Care, Retail Pharmacies Packaging Type: Syringe, Auto-Injector, Vial, Others |
| Companies Covered | AbbVie, Amgen, Pfizer, Sandoz, Samsung Bioepis, Celltrion, Boehringer Ingelheim, Fresenius Kabi, Zydus Cadila, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adalimumab Market Emerging Trajectories
High-concentration citrate-free formulations and interchangeable biosimilar designations are compressing the competitive moat around reference products while shifting value capture toward device differentiation.
High-concentration citrate-free formulations reduce injection volume and pain perception for patients self-administering subcutaneous doses. Rheumatology practices in the United States are migrating patient cohorts to these presentations at accelerating pace. This technology is supplanting legacy citrate-buffered vial presentations in new-to-brand prescriptions.
EMA's biosimilar approval pathway and FDA's interchangeability designation create divergent substitution rights across Atlantic markets. European pharmacy substitution proceeds under national competence while United States state laws determine automatic substitution authority. Biosimilar sponsors are prioritizing interchangeability studies in the United States to unlock pharmacy-level volume.
Specialty pharmacy buyers are consolidating procurement decisions through integrated delivery networks that standardize formularies across multiple sites. Independent rheumatology practices are losing purchasing autonomy as hospital outpatient departments and pharmacy benefit manager-owned specialty pharmacies capture patient flows. This concentration is most visible in United States metropolitan markets where vertical integration between payers and dispensers has advanced furthest.
Adalimumab Market Segmentation
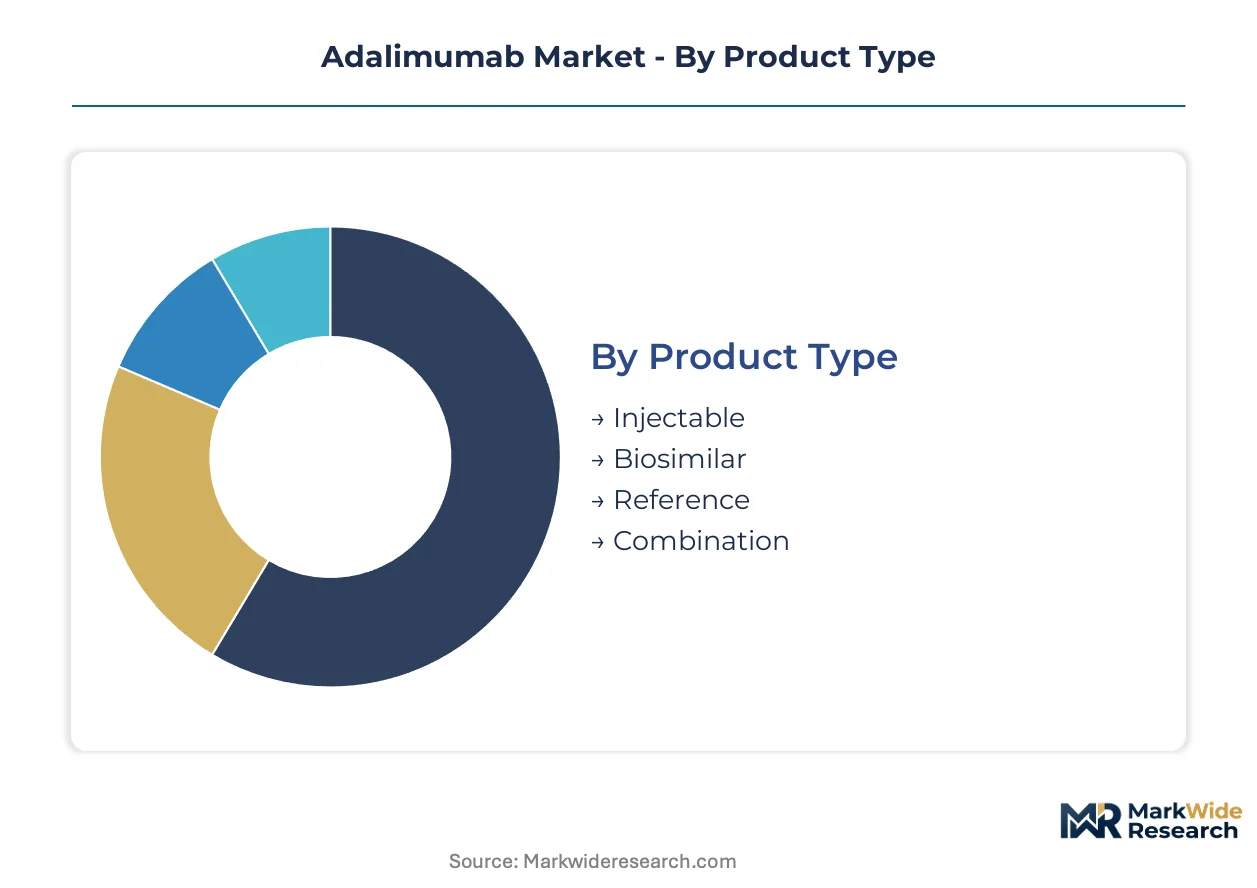
Adalimumab market segmentation reveals how regulatory pathways and delivery technologies fragment commercial opportunities. Understanding these divisions helps stakeholders align portfolio investments with substitution economics and prescriber workflow preferences.
Product Type:
FDA interchangeability designations and EMA biosimilar approval pathways create divergent competitive positions across product categories.
- Injectable:Subcutaneous presentations dominate outpatient administration, with citrate-free high-concentration formulations capturing preference in United States rheumatology practices seeking reduced injection pain. Payer formulary tiers increasingly favor these presentations for naive patient starts.
- Biosimilar:Interchangeable designations unlock pharmacy-level substitution without prescriber consultation, compressing originator volume in United States markets where state laws permit automatic switching. Manufacturing scale from Chinese hamster ovary systems exceeding five grams per liter enables competitive pricing.
- Reference:AbbVie's originator maintains residual loyalty through legacy patient support infrastructure and contracting structures with pharmacy benefit managers.
- Combination:Fixed-dose pairings with methotrexate or other conventional DMARDs address specific protocol requirements in academic medical centers.
Injectable formats handle the majority of throughput; Biosimilar is the fastest mover on share.
Therapy Area:
Clinical expansion patterns vary by specialist penetration and biologic naivety across immune-mediated conditions.
- Rheumatoid Arthritis:The largest established patient pool with mature biologic penetration in United States and European rheumatology practices. Conventional DMARD failure protocols standardize adalimumab positioning as second-line therapy.
- Crohn's Disease:Gastroenterology practices are expanding biologic penetration into moderate disease severity patients previously managed with immunomodulators, creating indication expansion runway. United States academic medical centers drive adoption protocols.
- Psoriasis:Dermatology biologic penetration lags rheumatology, with prior authorization requirements creating access friction in United States commercial insurance plans.
- Ulcerative Colitis:Similar gastroenterology expansion dynamics to Crohn's, though with more restricted formulary positioning in European hospital systems.
Rheumatoid Arthritis handles the majority of throughput; Crohn's Disease is climbing the fastest on specialist adoption.
End User:
Site-of-care migration and vertical integration between payers and dispensers reshape procurement concentration.
- Hospitals:Inpatient initiation protocols and 340B pricing programs in United States academic medical centers create distinct procurement economics. Biosimilar tenders in European hospital systems accelerate reference product displacement.
- Clinics:United States rheumatology practices are losing purchasing autonomy as integrated delivery networks standardize formularies across multiple sites. Independent practices in metropolitan markets face specialty pharmacy consolidation.
- Home Care:Self-administration training programs and hub services support patient-directed therapy management, particularly for citrate-free auto-injector presentations.
- Retail Pharmacies:United States pharmacy benefit manager-owned specialty pharmacies capture patient flows through mail-order mandatory programs and narrow network designs.
Hospitals handle the majority of throughput; Retail Pharmacies is gaining share fastest on substitution authority.
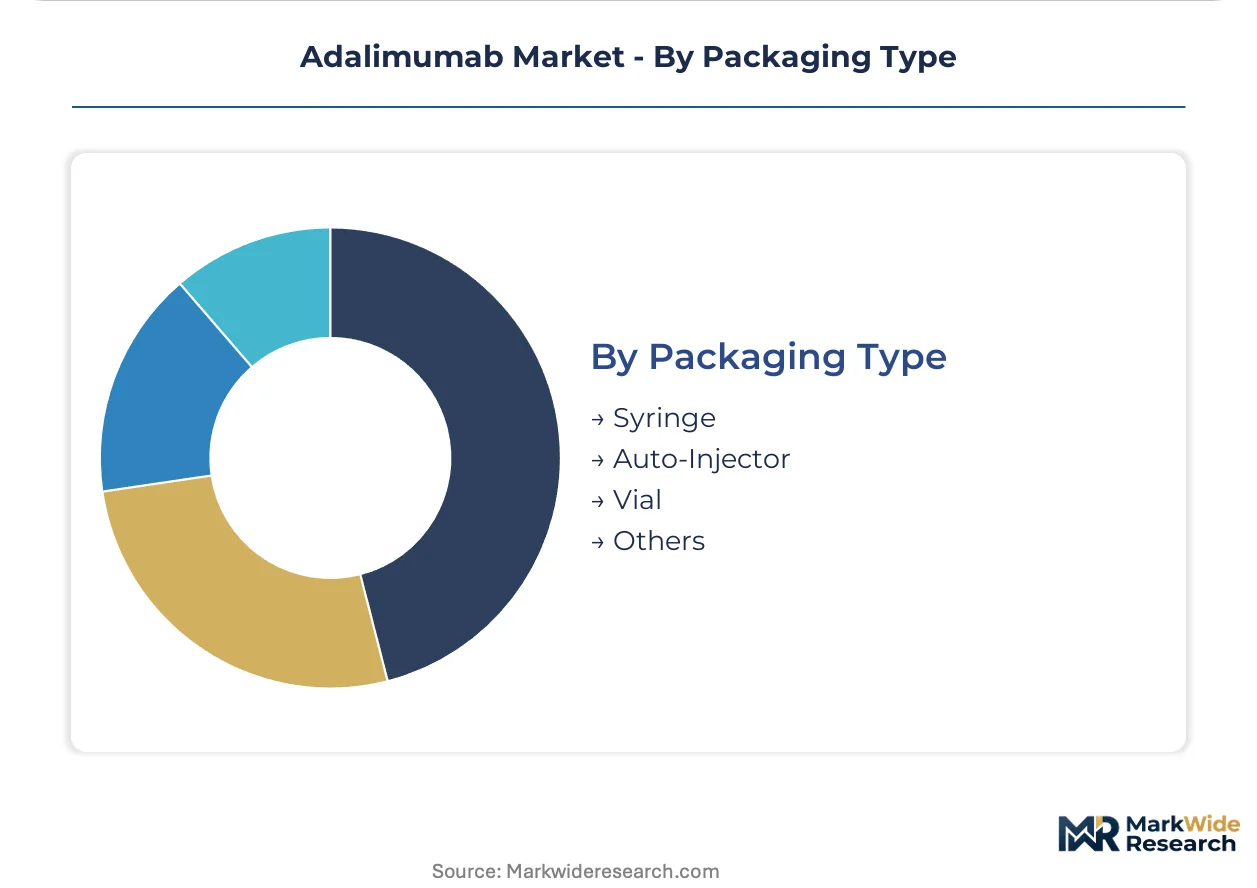
Packaging Type:
Device differentiation commands pricing power through patient experience and convenience premiums.
- Syringe:Standard prefilled presentations serve cost-sensitive segments and institutional procurement tenders in European markets. Healthcare professional administration remains common in hospital outpatient departments.
- Auto-Injector:Needle-guard mechanisms and travel portability features command patient-directed pharmacy premiums in United States commercial channels. High-concentration citrate-free variants reduce injection volume and pain perception.
- Vial:Legacy presentations persist in infusion center protocols and certain European hospital systems with established compounding workflows.
- Others:Emerging connected device platforms with adherence monitoring capabilities target value-based contracting arrangements in United States integrated delivery networks.
Syringe formats handle the majority of throughput; Auto-Injector shows the steepest expansion trajectory on patient preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmacy buyers in the United States concentrate procurement decisions through integrated delivery networks, while European hospital systems accelerate biosimilar tenders. Emerging markets in India leverage distinct regulatory pathways to supply lower-cost alternatives. Manufacturing scale from Chinese hamster ovary systems exceeding five grams per liter enables competitive positioning across multiple geographies.
United States
Rheumatology practices and gastroenterology clinics drive demand through biologic penetration into moderate disease severity patients. FDA interchangeability designations allow pharmacy-level substitution without prescriber consultation, accelerating biosimilar volume capture. The Boston-Cambridge biopharma corridor anchors patient support infrastructure and hub service development for chronic disease programs.
Germany
Hospital outpatient departments and academic medical centers standardize formularies through integrated procurement networks. EMA biosimilar approval pathways create substitution rights under national competence, with Germany's AMNOG early benefit assessment shaping reimbursement positioning. The Rhine-Ruhr metropolitan region concentrates specialty pharmacy distribution and cold chain logistics infrastructure.
India
Domestic manufacturers target emerging market supply through cost-competitive production from mammalian cell culture systems. CDSCO's similar biologics framework creates a streamlined licensing corridor distinct from FDA or EMA pathways. The Hyderabad-Bangalore pharmaceutical cluster anchors biosimilar development and contract manufacturing organization capacity for export markets.
Japan
PMDA biosimilar guidelines and pricing policies shape prescriber confidence in academic medical center protocols. The country's national pharmaceutical regulator maintains stringent immunogenicity surveillance requirements that compress sponsor margins. The Tokyo-Osaka corridor concentrates rheumatology specialist practices and hospital outpatient biologic administration.
United Kingdom
NHS England biosimilar switching programs and national procurement frameworks accelerate reference product displacement in hospital trusts. The MHRA post-Brexit regulatory pathway diverges from EMA procedures, creating distinct approval timelines. The London-Oxford-Cambridge golden triangle anchors clinical trial infrastructure and pharmacovigilance specialist talent pools.
Adalimumab Market Vendor Landscape
Player mix skews toward originator-loyal multinationals and cost-driven biosimilar specialists. The market structure concentrates around two dominant archetypes: vertically integrated biopharma conglomerates defending patent-expired franchises, and contract manufacturing-backed biosimilar pure-plays competing on supply reliability. Competitive moves center on interchangeability study investments and patient support infrastructure buildout to capture switching economics.
Among vertically integrated originators, AbbVie anchors the reference product tier through legacy hub services and copay assistance programs. Amgen and Pfizer occupy positions within the biosimilar competitive set, leveraging established biologics manufacturing networks. Samsung Bioepis represents the contract manufacturing-backed specialist archetype, with competitive pricing and European regulatory precedents smoothing market entry pathways.
| Leading Market Players |
|---|
| AbbVie |
| Amgen |
| Pfizer |
| Sandoz |
| Samsung Bioepis |
| Celltrion |
| Boehringer Ingelheim |
| Fresenius Kabi |
| Zydus Cadila |
| Others |
Supply Flow & Price Mechanics
Chinese hamster ovary titers exceeding five grams per liter compress manufacturing costs and anchor supply concentration among biosimilar producers with scaled mammalian cell culture capacity. This scale dynamic simultaneously depresses price floors for interchangeable products and elevates cost barriers for new entrants lacking comparable fermentation yields.
Pricing Analysis
Cost-plus contracts with pharmacy benefit managers in the United States index rebates to volume thresholds and formulary tier placement. Three-tier pricing structure across premium auto-injector, standard syringe, and economy vial presentations segments buyer archetypes by convenience sensitivity. Pricing pressure stems from interchangeable biosimilar entry and tightening payer formularies. Hospital procurement teams exhibit highest price sensitivity; patient-directed pharmacy channels in commercial insurance demonstrate lowest sensitivity due to hub service stickiness.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Singapore ports fluctuate with container availability and cold chain integrity requirements for temperature-controlled protein therapeutics. Manufacturing concentrates in the United States, Germany, and India for finished dose forms; active pharmaceutical ingredient production draws from Chinese hamster ovary cell banks in South Korea and China. Supply chain risk centers on single-source vulnerability for high-concentration citrate-free formulation devices. Distribution runs through specialty pharmacy channels and integrated delivery network warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where decades of patient support infrastructure create switching costs that delay biosimilar conversion even after patent expiry. Regulatory entrenchment through FDA interchangeability designations further hardens competitive positions.
For Market Incumbents: Compound defensive advantages by deepening hub service relationships with rheumatology practices and gastroenterology clinics. Accelerate citrate-free high-concentration device transitions to capture convenience premiums before biosimilar parity. Prioritize formulary exclusion contracting with pharmacy benefit managers to delay automatic substitution authority.
For New Entrants and Emerging Players: FDA interchangeability fast-track studies unlock pharmacy-level substitution without prescriber consultation. Target Crohn's disease and ulcerative colitis patient pools where gastroenterology biologic naivety exceeds rheumatology penetration. Pursue academic medical center partnerships to establish protocol credibility before payer formulary expansion.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturing-backed biosimilar specialists with scalable Chinese hamster ovary production and European regulatory precedents smoothing FDA pathways. Long-term viability hinges on interchangeability study completion and integrated delivery network procurement consolidation. Monitor state-level automatic substitution legislation as inflection indicator for volume capture acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Interchangeability Study Investment | FDA designation unlocks pharmacy substitution without prescriber consultation in permissive states. |
| Patient Support Infrastructure Buildout | Hub services and copay assistance programs create switching friction against biosimilar conversion. |
| High-Concentration Formulation Transition | Citrate-free auto-injectors command convenience premiums in United States rheumatology practices. |
| Integrated Delivery Network Partnership | Standardized formularies across hospital outpatient departments consolidate procurement decisions. |
| CDSCO Similar Biologics Registration | India's streamlined pathway enables emerging market supply at cost-competitive positioning. |
Methodological Framework
Cross-validation between primary interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings against secondary validation. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases provide regulatory and pipeline intelligence. Bottom-up patient volume modeling and top-down revenue triangulation reconcile demand estimates across therapy areas and product formats.
Sensitivity analysis tests forecast robustness across interchangeability adoption scenarios and payer formulary tightening assumptions over the projection horizon. Segmentation dimensions include therapy area, product type, end user site-of-care, and packaging device format. CAGRs derive from patient population growth, biologic penetration rates, and biosimilar substitution elasticity. Manufacturing scale assumptions and regulatory approval timelines feed directly into supply-side capacity modeling.
Decision-makers should treat outputs as directional under base assumptions of moderate biosimilar interchangeability adoption and stable payer rebate structures; material deviation would warrant model refresh. Forecasts reflect assumptions around FDA review timelines, state substitution legislation progression, and immunogenicity surveillance burden evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
West Africa Generic Drug Market
Generics and Biosimilars
Europe Branded Generics Market
Generics and Biosimilars
Latin America Generic Drug Market
Generics and Biosimilars
US Specialty Injectable Generics Market
Generics and Biosimilars
Super Generics Market
Generics and Biosimilars
GCC Generic Drug Market
Generics and Biosimilars
Global Adalimumab Drugs Market
Generics and Biosimilars
Europe Specialty Generics Market