
 Deodorant Products Market | 2026-2036
Deodorant Products Market Size, Share, and Industry Trends Forecast 2026-2036
Deodorant Products Market Insights
Multi-source fragrance and active-ingredient procurement is broadening as brands seek supply resilience against raw-material volatility. Unilever PLC leverages its integrated supply chain to control costs across spray and stick formats. Procter & Gamble sustains R&D intensity in encapsulated fragrance technologies. Beiersdorf AG anchors its position through dermatological testing protocols that differentiate Nivea variants in European pharmacies.
Deodorant products are topical formulations containing antimicrobial agents, fragrance compounds, and aluminum-based or aluminum-free actives designed to inhibit bacterial growth and mask or prevent body odor; they are manufactured through emulsion, aerosol filling, or solid-molding processes and serve daily personal hygiene needs across consumer demographics. Spray formats dominate volume in Latin American and European markets due to cultural preference and climate-driven usage frequency, while stick and gel segments capture margin pools in North American premium channels through natural and clean-label positioning. Roll-on demand is accelerating in Asia-Pacific urban centers where compact packaging aligns with smaller retail formats and on-the-go consumption patterns.
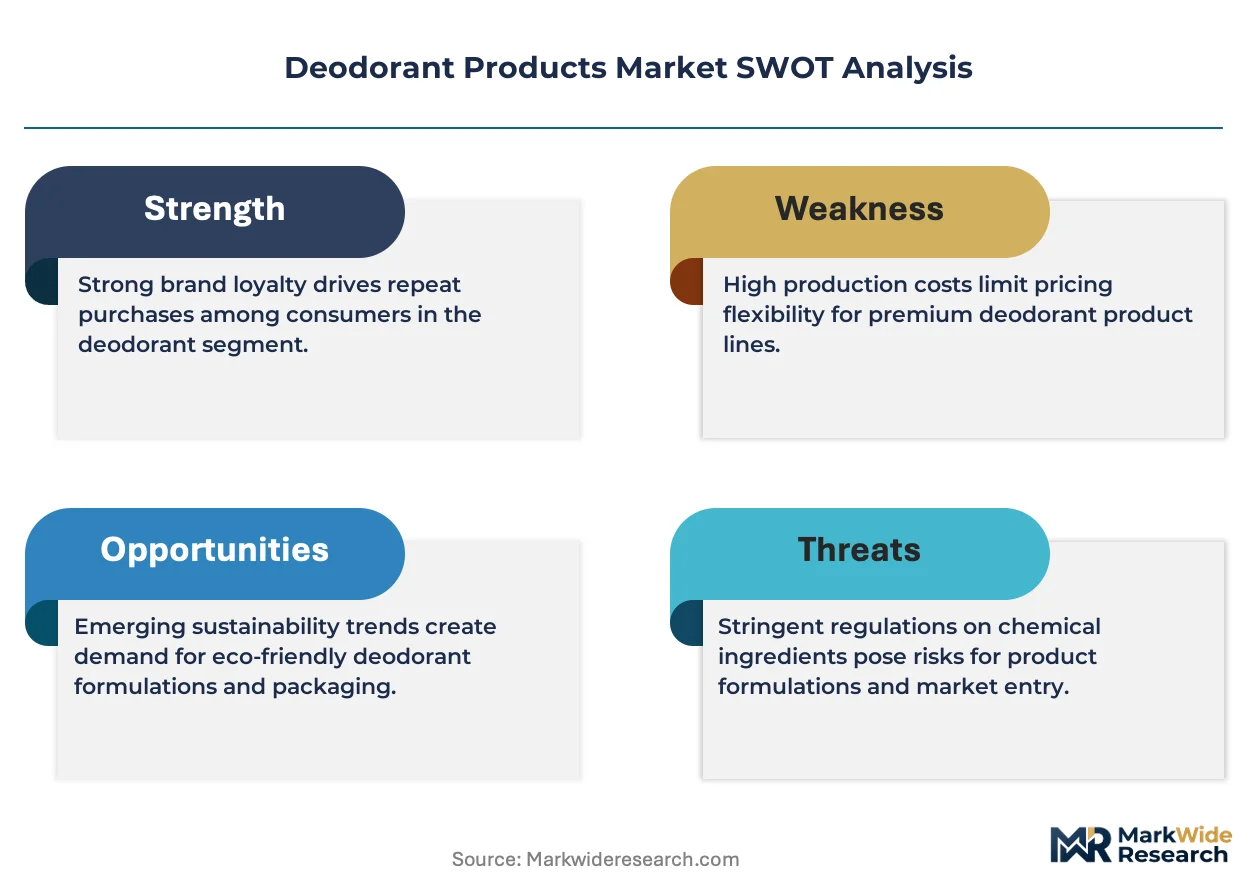
The US FDA regulates cosmetic labeling and antimicrobial claims under the Federal Food, Drug, and Cosmetic Act, while the EPA oversees volatile organic compound emissions from aerosol propellants; in Europe, the REACH framework and F-Gas Regulation constrain formulation chemistry and packaging choices, directly elevating compliance costs for cross-market portfolios. India's BIS certification and CDSCO oversight on medicated variants create additional entry barriers for imported brands. Stakeholders must monitor regulatory divergence between fragrance allergen disclosure mandates and propellant phase-down timelines to align R&D pipelines with region-specific compliance requirements.
Market Dynamics
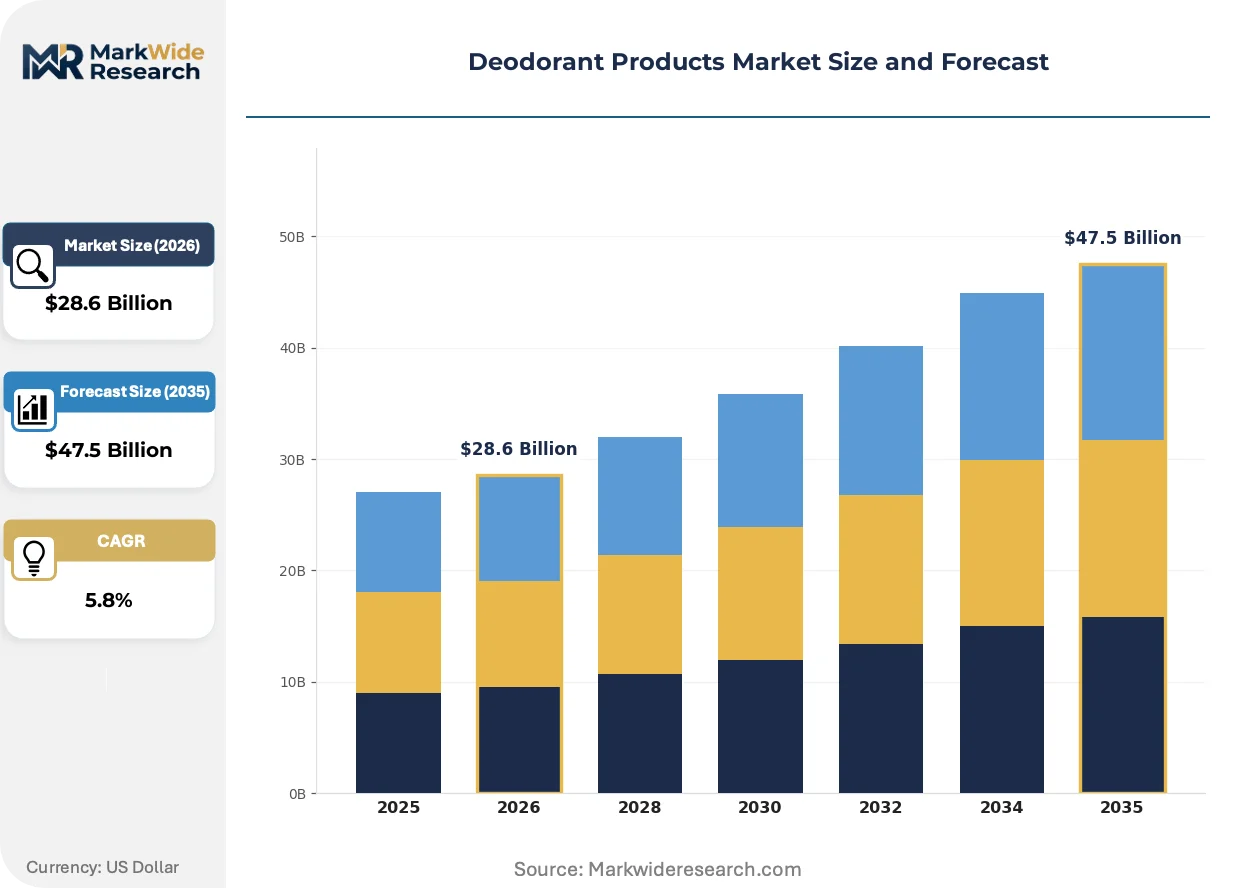
The EU's F-Gas Regulation is forcing aerosol propellant reformulation across European manufacturing footprints, while teen-segment demand acceleration and India's premium personal care expansion are compressing traditional category boundaries. Supply chains must simultaneously decarbonize propellant chemistry and capture emerging-market volume pools.
Growth Catalysts
- Teen hygiene habit formation:Younger consumers are adopting daily deodorant routines earlier than previous cohorts, expanding the addressable base beyond traditional adult demographics and driving trial-size and fragrance-forward SKU proliferation.
- REACH-compliant natural actives:European manufacturers are substituting aluminum salts with mineral-based and plant-derived alternatives, opening premium positioning in pharmacy and dermocosmetic channels where ingredient transparency commands shelf space.
- India urban retail densification:Modern trade expansion in Mumbai, Delhi, and Bangalore is concentrating distribution for roll-on and gel formats suited to compact household storage and on-the-go application.
Market Restraints
- Propellant input cost volatility:Hydrofluorocarbon phase-down timelines under F-Gas Regulation are compressing supply availability for conventional aerosol formats, elevating reformulation capex for manufacturers with legacy filling lines.
- Fragrance allergen disclosure mandates:EU regulation on fragrance component labeling is extending compliance timelines for new product launches, particularly for complex multi-note formulations targeting mass-market price points.
- Aluminum-free efficacy gap:Technical limitations in natural active performance versus aluminum-based antiperspirants are constraining conversion rates among heavy-use consumers in humid climates.
Strategic Opportunities
- Men's grooming line extensions:Underpenetrated male segments in India and Southeast Asia present white space for clinical-strength and sport-positioned variants with localized fragrance profiles.
- Refill and concentrate formats:Concentrate pods and reusable applicator systems are emerging in European premium channels, aligning with packaging waste directives and capturing sustainability-motivated switching.
- Pharmacy channel dermatological positioning:BIS-certified medicated variants in India and CDSCO-registered sensitive-skin lines are accessing professional recommendation networks that mass retail cannot replicate.
Industry Challenges
- Cross-regional formulation complexity:Divergent fragrance allergen thresholds between EU REACH, US FDA labeling, and India's BIS standards are fragmenting SKU architectures and compressing production run lengths.
- Aerosol line reconfiguration capex:Propellant transition timelines are forcing simultaneous investment in compressed gas and bag-on-valve technologies while depreciating legacy HFC-capable equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deodorant Products Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Roll-On, Stick, Gel End User: Men, Women, Unisex, Teens Distribution Channel: Online, Supermarkets, Drugstores, Specialty Stores Packaging Type: Aerosol, Bottle, Jar, Tube |
| Companies Covered | Unilever PLC, Procter & Gamble, Beiersdorf AG, Henkel AG & Co KGaA, L'Oreal S.A., Colgate-Palmolive Company, Church & Dwight Co., Inc., Reckitt Benckiser, Revlon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deodorant Products Market Trends and Innovations
Encapsulated fragrance release systems and microbiome-friendly actives are compressing the innovation cycle, while regulatory pressure on propellant chemistry and teen-segment digital engagement are rewriting go-to-market architectures. Three forces merit particular attention.
Microencapsulation technology is electrifying fragrance longevity claims in stick and gel formats. Premium brands in North American and European markets are adopting shell-in-shell polymer systems that extend scent release across 48-hour wear windows. This technology is electrifying competitive positioning by collapsing the efficacy gap between aluminum-based and aluminum-free formats.
REACH authorization requirements for fragrance allergens are tightening disclosure granularity across European supply chains. Manufacturers must now map sub-component concentrations previously treated as trade secrets, extending safety assessment timelines. Aerosol and spray segments face the steepest compliance burden due to higher fragrance loadings and inhalation exposure profiles.
Gen Z purchasing patterns are compressing traditional retail discovery cycles toward TikTok and Instagram commerce. Influencer-driven trial is displacing shelf-based brand loyalty in teen and young adult segments, with fragrance-forward and limited-edition drops capturing disproportionate share of voice. This shift is most visible in US and UK markets where direct-to-consumer fulfillment infrastructure supports impulse conversion.
Deodorant Products Market Segmentation
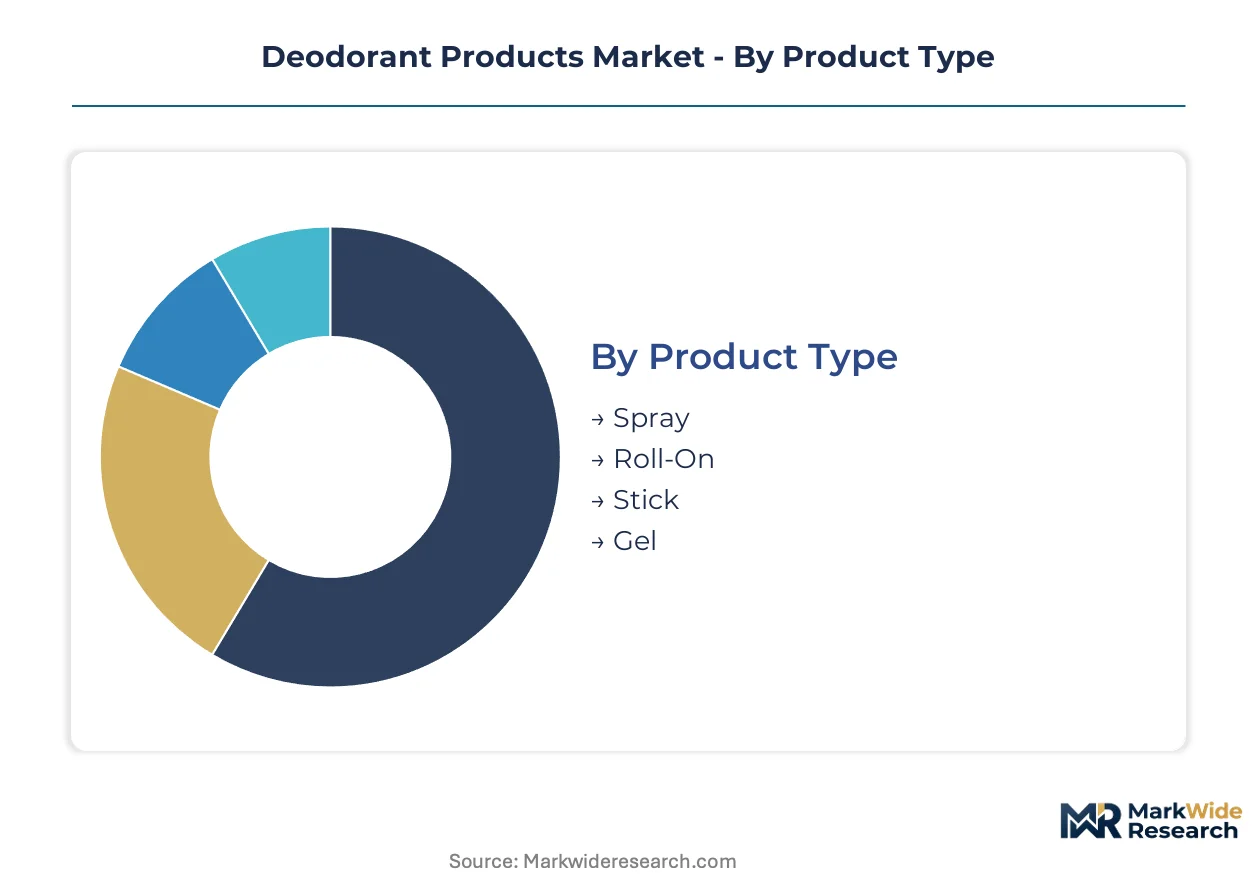
Deodorant product architectures fragment across four distinct category axes, each commanding differentiated margin pools and regulatory exposure. Manufacturers must align formulation chemistry, channel strategy, and packaging investment to capture volume in mass-market aerosols while extracting premium in dermocosmetic sticks and gels.
Product Type:
Spray formats dominate volume throughput in humid climates, while stick and gel variants command premium shelf positioning through natural-actives positioning.
- Spray:Aerosol and pump-dispensed formulations rely on compressed gas or bag-on-valve propellant systems to deliver fine-mist aluminum-based or aluminum-free actives. Demand concentrates in Brazil and Mexico where climate-driven reapplication frequency sustains household stock-up purchasing.
- Stick:Solid-molded emulsion bases incorporating microencapsulated fragrance systems and dermatological actives. German and French pharmacy channels favor stick formats for sensitive-skin positioning where ingredient transparency commands price premiums.
- Roll-On:Liquid-active suspension in ball-applicator packaging suited to compact household storage. Mumbai and Bangalore modern-trade expansion is accelerating roll-on adoption among urban apartment dwellers.
- Gel:Clear-drying silicone and water-based formulations targeting visible-residue avoidance. US prestige retailers stock gel variants for professional-wear occasions where fabric protection matters.
Mature deployment sits with Spray. Newer deployment is concentrated in Gel.
End User:
Gendered positioning fragments into clinical-strength male segments, fragrance-forward female lines, and emerging teen cohorts rewriting habit-formation timelines.
- Men:Sport-positioned and clinical-strength variants with higher aluminum-chlorohydrate concentrations. Underpenetrated demand in Jakarta and Manila is expanding addressable base for localized fragrance profiles.
- Women:Multi-note fragrance architectures and skin-conditioning additives dominate SKU proliferation. UK and US direct-to-consumer channels are displacing mass-retail discovery for female-targeted lines.
- Unisex:Neutral fragrance palettes and minimalist packaging aesthetics. Scandinavian markets favor unisex positioning where sustainability credentials outweigh gendered marketing.
- Teens:Trial-size formats and influencer-driven limited drops. TikTok commerce in Los Angeles and London is compressing traditional retail loyalty cycles for this cohort.
Volume concentration rests with Women. Steepest expansion trajectory belongs to Teens.
Distribution Channel:
Channel selection determines compliance burden and margin capture, with digital fulfillment rewriting last-mile economics for fragrance-forward SKUs.
- Online:Direct-to-consumer and marketplace fulfillment enabling subscription replenishment and limited-edition drops. Amazon and dedicated brand sites are capturing trial conversion for aluminum-free variants in California and New York.
- Supermarkets:High-velocity mass-market shelving for family-size aerosol packs. São Paulo and Mexico City hypermarket chains concentrate volume for price-promoted spray formats.
- Drugstores:Pharmacy-adjacent positioning with dermocosmetic and sensitive-skin claims. Boots and dm-drogerie markt in London and Berlin allocate premium shelf space to REACH-compliant natural actives.
- Specialty Stores:Prestige fragrance retail and clean-beauty boutiques. Sephora and Space NK in Paris and New York curate aluminum-free and microbiome-friendly lines for ingredient-conscious consumers.
Established throughput centers on Supermarkets. Emerging share capture is accelerating in Online.
Packaging Type:
Packaging selection locks in propellant chemistry investment and regulatory compliance pathways across manufacturing footprints.
- Aerosol:Pressurized metal cans with liquefied gas propellants requiring F-Gas Regulation compliance in European production. Reformulation capex is elevating costs for legacy filling lines in Germany and France.
- Bottle:Pump-spray and squeeze formats for liquid roll-on and splash applications. Indian urban retail densification favors bottle formats for bathroom-counter visibility in Mumbai apartments.
- Jar:Cream and pomade deodorants in wide-mouth containers. Niche positioning in Japanese specialty channels targets older consumers preferring manual application control.
- Tube:Squeeze-dispensed gel and cream formats with controlled dosing. Refill-compatible tube systems are emerging in Amsterdam and Copenhagen under packaging waste directive pressure.
Installed base concentrates in Aerosol. Fastest-gaining share is concentrated in Tube.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum feedstock availability in Guinea and Australia underpins antiperspirant active production networks. Propellant chemistry constraints in Europe and aerosol format dominance in Latin America create divergent regional manufacturing footprints. Teen-segment demand acceleration and pharmacy channel expansion are rewriting distribution economics across urban clusters.
United States
Encapsulated fragrance R&D concentrates in New Jersey and Ohio research corridors, with Procter & Gamble sustaining investment in extended-release polymer systems. FDA labeling enforcement under the Federal Food, Drug, and Cosmetic Act elevates compliance costs for aluminum-free efficacy claims. Los Angeles and New York Metro anchor TikTok-commerce fulfillment networks for teen-targeted limited drops.
Germany
Beiersdorf AG leverages Hamburg headquarters proximity to ECHA regulatory intelligence, accelerating REACH-compliant natural active substitution. F-Gas Regulation phase-down timelines compress hydrofluorocarbon propellant availability for legacy aerosol lines. Cologne and Düsseldorf manufacturing clusters absorb reformulation capex for compressed gas and bag-on-valve transitions.
India
Urban retail densification in Mumbai, Delhi, and Bangalore accelerates roll-on and gel format adoption among apartment-dwelling consumers. BIS certification requirements and CDSCO oversight on medicated variants create entry barriers for imported brands. Gujarat and Maharashtra industrial corridors concentrate contract manufacturing for Unilever PLC's regional SKU proliferation.
Brazil
Climate-driven reapplication frequency sustains aerosol spray volume leadership across São Paulo and Rio de Janeiro hypermarket chains. ANVISA cosmetic registration timelines extend launch windows for fragrance-forward formulations. São Paulo state anchors Latin America's largest propellant filling capacity, with local suppliers adapting to compressed gas transitions.
United Kingdom
Boots pharmacy networks in London and Manchester allocate premium shelf space to dermatological-positioned sticks with allergen-disclosure compliance. UKCA marking divergence from EU REACH creates parallel assessment burdens for cross-channel portfolios. Midlands manufacturing clusters specialize in refill-compatible tube formats under packaging waste directive pressure.
Deodorant Products Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents balance aerosol line reconfiguration against natural-active premium positioning. The vendor base stratifies across integrated FMCG conglomerates with captive fragrance supply, mid-scale dermocosmetic specialists leveraging pharmacy channel access, and private-label contract manufacturers serving price-compressed retail tiers. Three archetypes anchor competitive positioning: science-backed pharmacy channel occupants, mass-market aerosol volume leaders, and digital-native direct-to-consumer entrants. M&A activity targets microbiome-friendly active suppliers, while capacity expansion concentrates in India and Southeast Asia to capture teen-segment growth.
Within the integrated conglomerate tier, Unilever PLC and Procter & Gamble exemplify scale-driven supply chain control across spray and stick formats. Beiersdorf AG occupies a dermatological-positioning anchor in European pharmacy channels. These three entities represent divergent strategic bets: Unilever PLC on emerging-market volume capture, Procter & Gamble on encapsulated fragrance technology leadership, and Beiersdorf AG on sensitive-skin clinical credibility.
| Leading Market Players |
|---|
| Unilever PLC |
| Procter & Gamble |
| Beiersdorf AG |
| Henkel AG & Co KGaA |
| L'Oreal S.A. |
| Colgate-Palmolive Company |
| Church & Dwight Co., Inc. |
| Reckitt Benckiser |
| Revlon Inc. |
| Others |
Pricing and Supply Chain Analysis
Teen-segment procurement through TikTok commerce and influencer drops anchors the dominant freemium-plus-limited-edition pricing model, where trial-size conversion subsidizes full-format retention and scarcity-driven drops command 40-60% shelf price premiums over standard SKUs.
Pricing Analysis
Warranty and efficacy guarantees remain unbundled from base product pricing, with dermatological testing and clinical validation treated as premium-tier add-ons. Three-tier pricing structure across premium, standard, and economy levels stratifies by aluminum-active concentration and fragrance complexity. Cost compression in mass-market aerosol tiers intensifies because F-Gas Regulation propellant reformulation elevates per-unit manufacturing overhead. Price sensitivity concentrates among teen and young adult first-time buyers, while pharmacy-channel consumers in Germany and France exhibit lowest elasticity for sensitive-skin positioned variants.
Supply Chain Analysis
India's phased manufacturing program and domestic-content mandates for personal care packaging are reshaping sourcing patterns for multinational brands. Aluminum feedstock draws from Guinea and Australian bauxite refining corridors, while fragrance compound synthesis concentrates in Grasse-region French suppliers and Swiss specialty chemical houses. Single-source vulnerability sits with hydrofluorocarbon propellant suppliers facing EU phase-down deadlines. Distribution runs through modern-trade hypermarkets in São Paulo and Mumbai, with direct-to-consumer fulfillment capturing accelerating share in Los Angeles and London metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The deodorant category is becoming a vertical-integration race, with captive fragrance compound production and in-house propellant chemistry emerging as decisive cost-control levers against raw-material volatility.
For Market Incumbents: Deploy microencapsulation R&D partnerships to collapse the efficacy gap between aluminum-based and aluminum-free formats. Secure compressed gas and bag-on-valve filling capacity in Cologne and São Paulo manufacturing clusters before legacy HFC equipment depreciation accelerates. Counter TikTok-native entrant disruption by acquiring limited-edition drop infrastructure or influencer-network agencies.
For New Entrants and Emerging Players: Microbiome-friendly active technologies offer the clearest technology-first wedge against established efficacy claims. White space concentrates in BIS-certified medicated variants for Indian pharmacy channels and refill-compatible tube formats under European packaging waste directives. Go-to-market should prioritize Sephora and Space NK specialty retail partnerships for clean-beauty credentialing before mass-market expansion.
For Investors and Strategic Acquirers: The window for entry favors microbiome-active suppliers and regional contract manufacturers with pharmacy-channel certification. Long-term viability hinges on reformulation agility under divergent REACH, FDA, and BIS regulatory frameworks. Watch ANVISA registration timeline compression in Brazil as the inflection signal for Latin American manufacturing consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Chemistry Transition | Compressed gas and bag-on-valve adoption in Cologne and São Paulo lines meets F-Gas Regulation compliance deadlines. |
| Microencapsulation R&D Partnership | Shell-in-shell polymer systems from New Jersey research corridors extend fragrance release claims against aluminum-free competitors. |
| Pharmacy Channel Certification | BIS and CDSCO registration unlocks professional recommendation networks in Mumbai and Delhi that mass retail cannot replicate. |
| Refill Format Infrastructure | Tube-compatible concentrate pods in Amsterdam and Copenhagen align with EU packaging waste directive requirements. |
| Influencer Commerce Integration | TikTok fulfillment partnerships in Los Angeles and London compress discovery-to-trial cycles for teen-segment acquisition. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fragrance compound procurement directors, aerosol filling plant managers, pharmacy category buyers at Boots and dm-drogerie markt, and regulatory affairs leads at ECHA and FDA. Nielsen retail audit data, CDSCO registration databases, ANVISA cosmetic filings, and EU F-Gas Regulation compliance disclosures provided volume and pricing benchmarks. Bottom-up SKU-level modeling triangulated against top-down category spending estimates from national statistical offices.
Data-stream reconciliation across shipment volumes, propellant chemistry transition timelines, and teen-segment digital commerce metrics informed the analytical framework. Segmentation dimensions included product format, aluminum-active versus aluminum-free positioning, distribution channel, and regional regulatory cluster. CAGRs derived from slope-intercept modeling of historical trajectory and elasticity-adjusted demand projections. Forecast inputs incorporated urban retail densification rates in Indian metros and TikTok commerce penetration curves in US and UK markets.
Several conditions sit outside the modeled scope, including abrupt F-Gas Regulation acceleration, aluminum salt health claim litigation outcomes, and pandemic-scale disruption to fragrance compound supply chains. Forecasts reflect documented assumptions regarding regulatory timeline adherence and consumer habit persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Depilatory Product Market
Beauty & Personal Care
South America Bath and Shower Products Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Refillable Deodorants Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Hairstyling Products Market
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
North America Hair Removal Wax Market