
 Global Family Entertainment Center Market | 2026-2036
Global Family Entertainment Center Market Size, Share, and Industry Trends Forecast 2026-2036
Global Family Entertainment Center Market Analysis
The shift from single-source attraction procurement to multi-vendor technology partnerships is broadening how family entertainment centers source interactive systems. Dave & Buster's leverages in-house game development to control content refresh cycles, while Merlin Entertainments sustains geographic dominance through clustered attraction networks across multiple countries. KidZania differentiates by operating educational role-play concepts that anchor mall-based entertainment zones.
A family entertainment center constitutes a commercial facility combining amusement attractions, dining, and social recreation within a controlled environment, typically spanning 20,000 to 100,000 square feet with climate-controlled infrastructure and integrated point-of-sale systems. Indoor centers capture the largest revenue share due to year-round operational reliability and lower weather-dependent revenue volatility. Virtual Reality installations within the technology segment attract premium pricing and extended dwell times, while food and beverage services generate margin pools that subsidize capital-intensive gaming equipment.
The US Consumer Product Safety Commission enforces ASTM F24 amusement ride standards, while the EU's CE marking and Machinery Directive govern attraction safety across European installations. China's SAMR oversees operational licensing for large-scale entertainment venues under national safety codes. Stakeholders must monitor how evolving accessibility mandates and digital privacy frameworks reshape guest data collection practices and attraction design requirements.
Market Dynamics
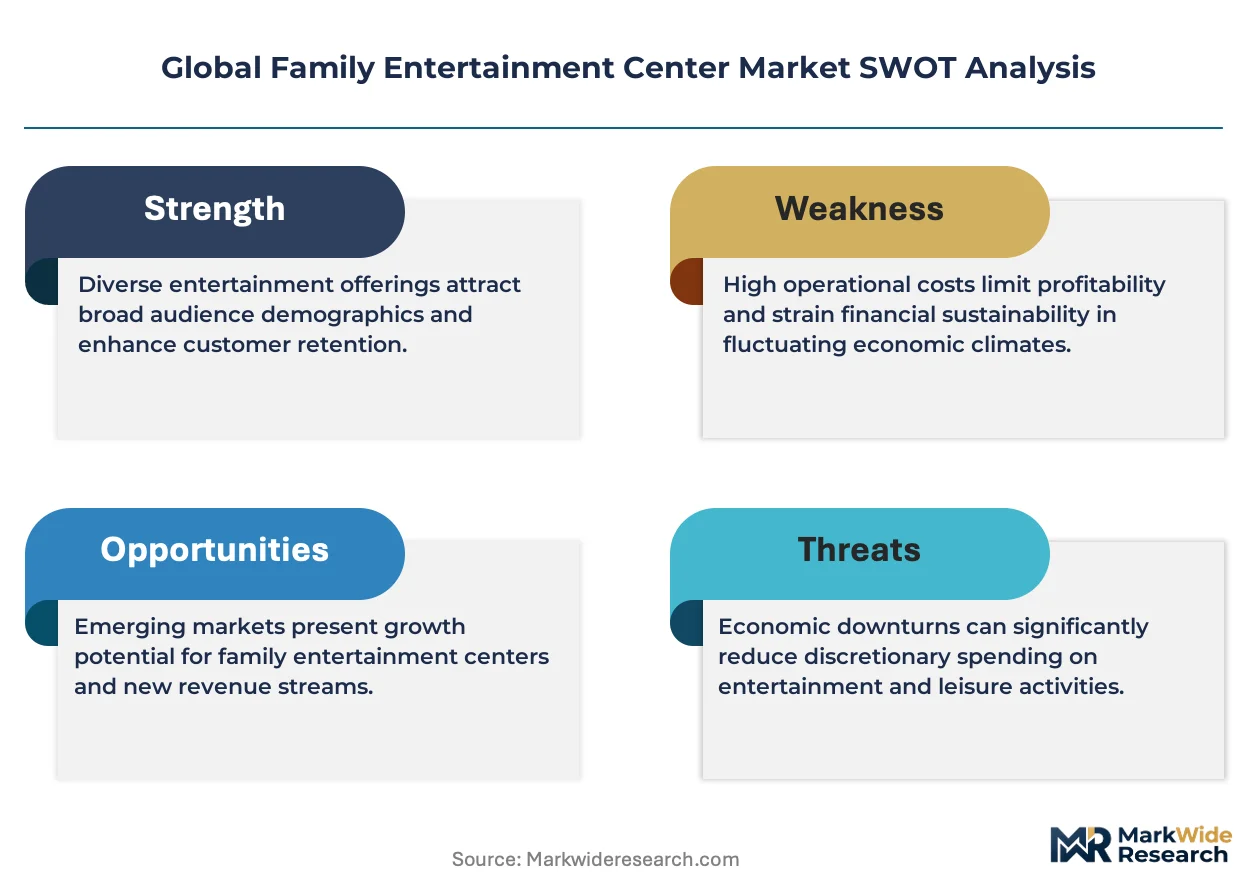
Immersive technology integration is compressing attraction refresh cycles and forcing operators to choose between proprietary content development and multi-vendor licensing partnerships. This structural tension between control and flexibility now defines capital allocation across the sector.
Growth Catalysts
- ASTM F24 Standards:The US Consumer Product Safety Commission's amusement ride safety framework reduces liability exposure for operators adopting certified equipment, accelerating insurance market access for new entrants.
- Urban Mixed-Use Development:Entertainment complexes anchor retail developments in the United States, China, and the United Kingdom, generating foot traffic synergies that subsidize attraction operating costs.
- Virtual Reality Hardware:Premium VR installations command extended dwell times and higher per-visit spending from teen and young adult demographics seeking differentiated social experiences.
Market Restraints
- Climate-Controlled Infrastructure:Indoor centers require substantial HVAC and electrical capacity investments that lock operators into fixed-cost structures regardless of seasonal demand fluctuations.
- Gaming Equipment Depreciation:Arcade and redemption hardware faces accelerated obsolescence cycles, forcing continuous capital reinvestment to maintain guest engagement metrics.
- Food and Beverage Margin Dependency:F&B operations subsidize gaming equipment costs, creating vulnerability when labor or commodity input costs spike unexpectedly.
Strategic Opportunities
- Educational Role-Play Formats:Mall-based concepts combining vocational simulation with entertainment address parental demand for value-added experiences during routine shopping trips.
- China's SAMR Licensing Framework:National safety code compliance creates barriers that protect established operators while enabling premium positioning for certified venues in tier-one cities.
- Multi-Vendor Technology Partnerships:Sourcing flexibility allows smaller operators to access interactive systems previously reserved for vertically integrated chains, democratizing competitive capability.
Industry Challenges
- Point-of-Sale Integration Complexity:Legacy ticketing and payment systems resist seamless connection with modern guest data platforms, fragmenting customer relationship management.
- Digital Privacy Compliance:Evolving guest data collection mandates across the United States, Germany, and Japan require continuous operational protocol adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Family Entertainment Center Market |
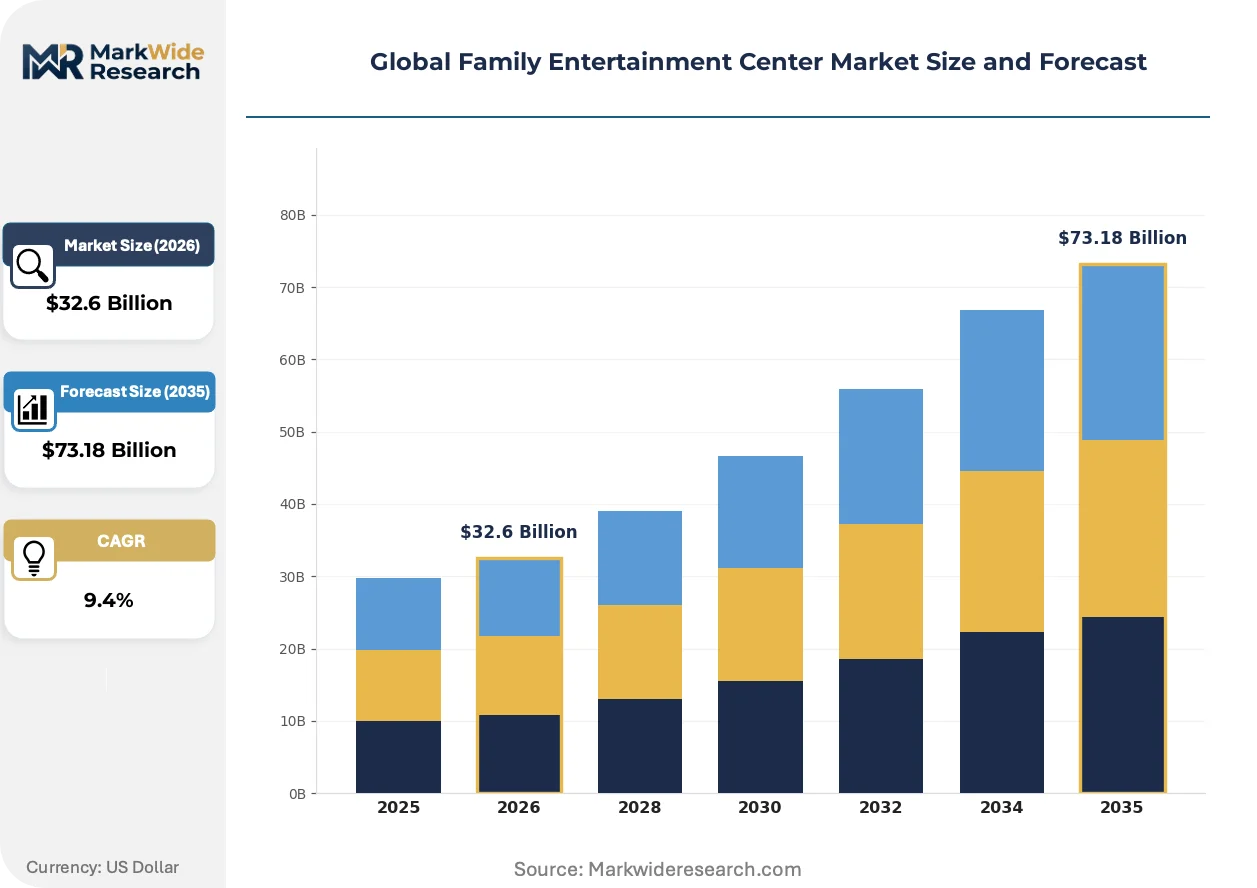
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $73.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Indoor Centers, Outdoor Parks, Arcade Facilities, Play Zones Technology: Virtual Reality, Augmented Reality, Interactive Games, Digital Attractions Target Audience: Children, Teens, Families, Adults Service Type: Food & Beverage, Entertainment Services, Event Hosting, Recreational Activities |
| Companies Covered | Dave & Buster's, CEC Entertainment, Merlin Entertainments, KidZania, Bowlero Corp., Main Event Entertainment, Chuck E. Cheese, Round1 Entertainment, Urban Air Adventure Park, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Family Entertainment Center Market Emerging Trajectories
Technology convergence is redefining how family entertainment centers balance physical and digital experiences. Operators now face compressed decision timelines for adopting immersive systems that reshape guest expectations.
Extended reality platforms are integrating haptic feedback and spatial computing into attraction design. Family entertainment centers in the United Kingdom and Japan are deploying these systems to extend session durations. The technology is integrating previously separate entertainment modalities into unified experiences that justify premium admission pricing.
China's SAMR operational licensing requirements for large-scale venues are tightening equipment certification timelines. Manufacturers serving the Chinese market must now front-load compliance documentation. Indoor centers above 50,000 square feet face the most stringent documentation burdens, driving consolidation toward larger operators with dedicated regulatory affairs capacity.
Guest expectations for seamless digital booking and personalized attraction recommendations are reshaping operator technology priorities. Family groups now expect mobile-first reservation systems with real-time capacity visibility. This shift is most pronounced in the United States, where urban entertainment complexes compete for limited weekend leisure windows through dynamic pricing and loyalty program integration.
Global Family Entertainment Center Market Segmentation
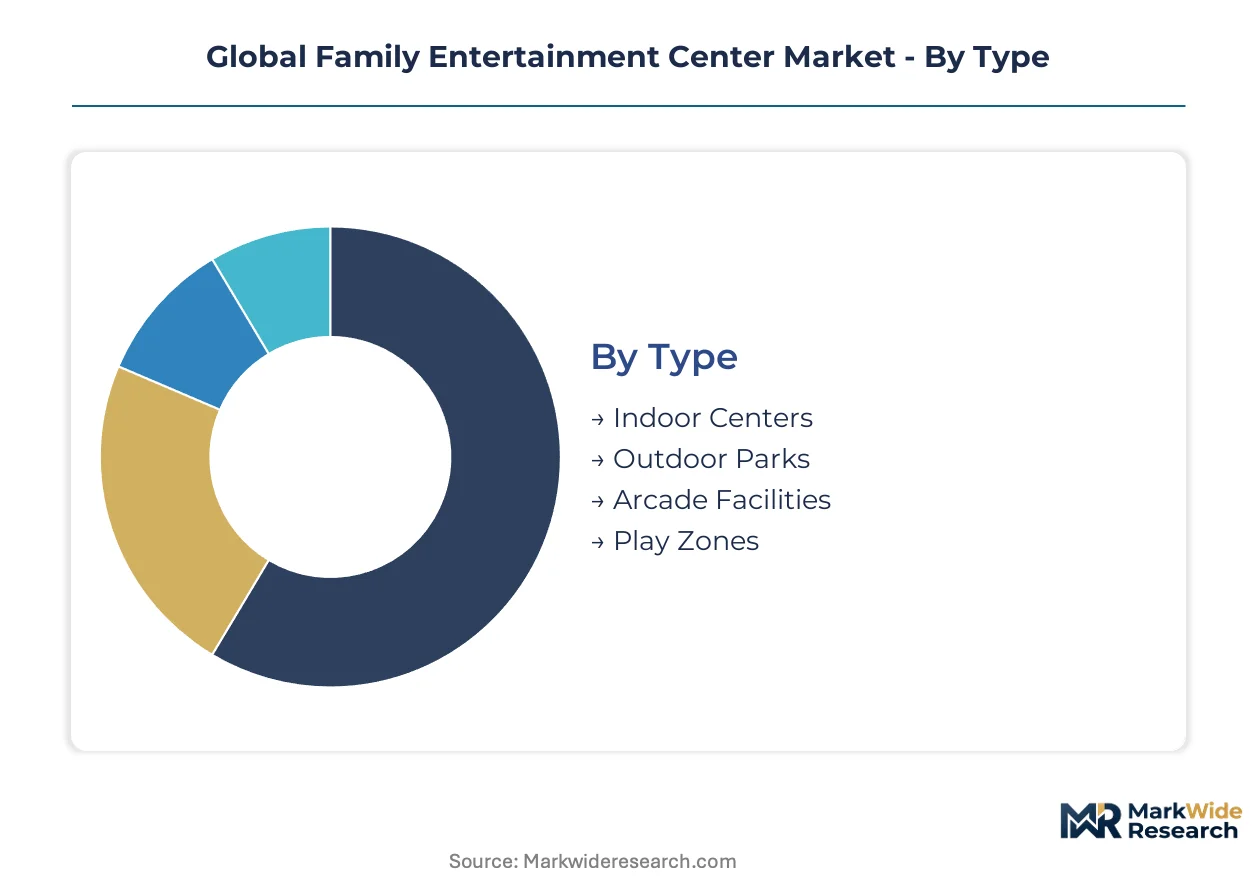
Family entertainment centers segment across facility type, technology integration, audience targeting, and service mix. Each dimension shapes capital deployment, operational complexity, and revenue stability differently.
Type:
Standardized formats dominate high-volume deployment, while customized concepts command premium positioning in mixed-use developments.
- Indoor Centers:Climate-controlled facilities ranging 20,000 to 100,000 square feet with integrated point-of-sale systems. Demand concentrates in the United States, China, and the United Kingdom where urban entertainment complexes anchor retail developments and generate year-round revenue reliability.
- Outdoor Parks:Weather-dependent attractions requiring seasonal staffing models and higher liability coverage. Operators in Germany and Japan face compressed operating calendars that demand aggressive summer programming to recover fixed land costs.
- Arcade Facilities:Redemption-focused venues with accelerated gaming equipment refresh cycles.
- Play Zones:Toddler-oriented soft-play structures with lower per-square-foot buildout costs.
Most installed capacity flows through Indoor Centers. Expansion is steepest in Outdoor Parks.
Technology:
Technology deployment separates premium positioning from commodity entertainment, with hardware sourcing decisions locking in multi-year content roadmaps.
- Virtual Reality:Premium installations integrating haptic feedback and spatial computing that extend session durations. The United Kingdom and Japan deploy these systems to justify premium admission pricing from teen and young adult demographics seeking differentiated social experiences.
- Augmented Reality:Overlay systems blending physical environments with digital content layers. China's SAMR licensing framework for large-scale venues is tightening equipment certification timelines for AR hardware deployments above 50,000 square feet.
- Interactive Games:Motion-sensing and touch-based systems with lower capital barriers.
- Digital Attractions:Screen-based entertainment with compressed development cycles.
Virtual Reality commands the highest capital allocation per square foot. Augmented Reality is gaining share fastest as manufacturers front-load compliance documentation for Chinese market access.
Target Audience:
Audience targeting determines programming mix, pricing architecture, and facility design specifications across demographic life stages.
- Children:Educational role-play formats combining vocational simulation with entertainment. KidZania operates these concepts to anchor mall-based zones in the United States and United Kingdom, addressing parental demand for value-added experiences during routine shopping trips.
- Teens:Social gaming environments with extended dwell times and higher per-visit spending. VR installations and competitive esports formats concentrate demand from this demographic in China and Japan.
- Families:Multi-generational programming requiring simultaneous engagement across age ranges.
- Adults:Evening-focused entertainment with food and beverage integration.
Family-oriented programming generates the highest visit frequency. Teen-focused concepts show the steepest expansion trajectory as operators compete for limited weekend leisure windows.
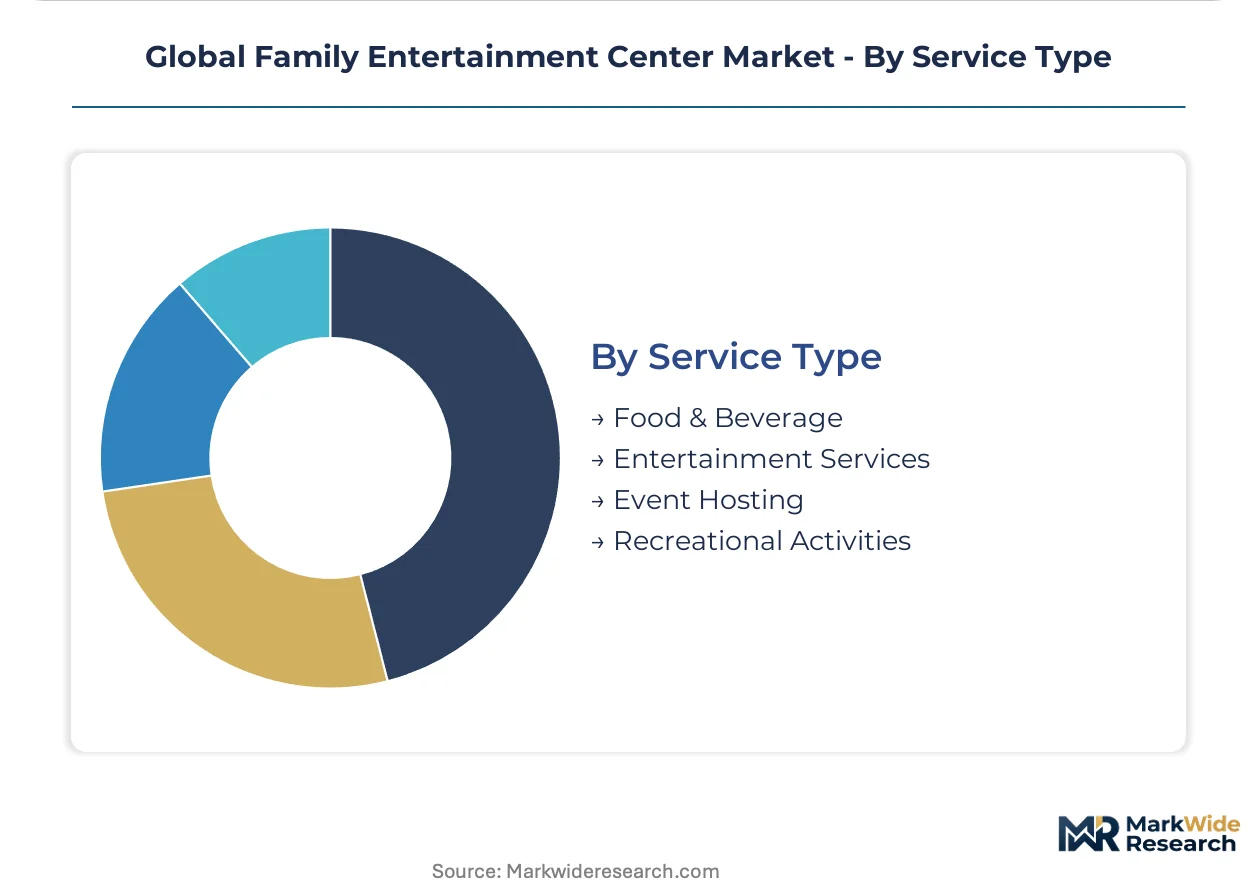
Service Type:
Service mix determines margin structure, with high-turnover offerings subsidizing capital-intensive attraction infrastructure.
- Food & Beverage:Full-service and quick-service operations generating margin pools that subsidize gaming equipment costs. Labor and commodity input spikes create vulnerability for operators dependent on F&B cross-subsidization.
- Entertainment Services:Core attraction operations including rides, games, and immersive experiences. Dave & Buster's controls content refresh cycles through in-house game development rather than multi-vendor licensing partnerships.
- Event Hosting:Private party and corporate programming with premium pricing and guaranteed minimums.
- Recreational Activities:Bowling, mini-golf, and skill-based attractions with longer asset lifecycles.
Food & Beverage operations carry the highest revenue weight. Event Hosting is expanding most quickly as operators pursue predictable booking revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where family entertainment center operators deploy capital, as compliance cost differentials between the United States, China, and the United Kingdom create distinct investment thresholds for venue development.
United States
Urban mixed-use developments in Dallas, Houston, and Atlanta anchor entertainment complexes that generate foot traffic synergies with retail tenants. The US Consumer Product Safety Commission enforces ASTM F24 amusement ride standards that reduce liability exposure for certified equipment adopters. Dave & Buster's leverages in-house game development in Texas and California markets to control content refresh cycles without multi-vendor dependencies.
China
Tier-one cities including Shanghai, Beijing, and Shenzhen concentrate demand for premium indoor entertainment venues exceeding 50,000 square feet. SAMR operational licensing requirements for large-scale venues are tightening equipment certification timelines and documentation burdens. KidZania operates educational role-play concepts in mall-based zones across Guangdong and Jiangsu provinces, addressing parental demand for value-added experiences during routine shopping trips.
United Kingdom
London and Manchester entertainment complexes compete for limited weekend leisure windows through dynamic pricing and loyalty program integration. CE marking and the EU Machinery Directive govern attraction safety across English and Scottish installations. Merlin Entertainments sustains geographic dominance through clustered attraction networks that spread regulatory compliance costs across multiple venues.
Japan
Tokyo and Osaka metropolitan areas deploy extended reality platforms with haptic feedback to extend session durations from teen and young adult demographics. METI oversight and JIS standards shape equipment certification protocols for immersive technology installations. Round1 Entertainment operates competitive social gaming environments that concentrate demand in Greater Tokyo and Kansai corridor markets.
Germany
Berlin and Munich anchor outdoor park developments that face compressed operating calendars demanding aggressive summer programming. KBA and federal state regulators enforce liability protocols that influence attraction design specifications. Operators in Bavaria and North Rhine-Westphalia navigate seasonal staffing models and higher weather-dependent revenue volatility than climate-controlled indoor alternatives.
Global Family Entertainment Center Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue immersive technology integration and educational role-play formats. The vendor base separates into vertically integrated chains controlling content development, multi-venue operators spreading fixed costs across geographic clusters, and specialized concept developers anchoring mall-based entertainment zones. Three archetypes dominate: in-house game developers, clustered attraction networks, and educational experience specialists. Competitive moves concentrate on multi-vendor technology partnerships and proprietary content development to compress attraction refresh cycles.
Within the vertically integrated tier, Dave & Buster's exemplifies operators controlling content refresh cycles through in-house development rather than external licensing. Merlin Entertainments occupies a position as the clustered network archetype, spreading regulatory compliance and marketing costs across multiple country installations. KidZania represents the specialized concept developer, anchoring mall-based educational role-play zones that address parental demand for value-added experiences.
| Leading Market Players |
|---|
| Dave & Buster's |
| CEC Entertainment |
| Merlin Entertainments |
| KidZania |
| Bowlero Corp. |
| Main Event Entertainment |
| Chuck E. Cheese |
| Round1 Entertainment |
| Urban Air Adventure Park |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists including Dave & Buster's and Bowlero Corp. anchor supply discipline through centralized procurement consortia, compressing vendor margins while enforcing volume-based pricing tiers across gaming equipment and foodservice inputs.
Pricing Analysis
Distributor margins on redemption hardware and VR systems typically absorb 15-25 points before venue operators apply per-visit admission and pay-per-play pricing. Price differentiation rests on certification tier—ASTM F24-compliant attractions command premium positioning against uncertified alternatives—and geographic delivery cost differentials between domestic and imported equipment. Pricing pressure stems from accelerated gaming equipment obsolescence forcing continuous capital reinvestment. Family groups exhibit highest price sensitivity on admission tickets, while teen demographics tolerate premium spend for differentiated social experiences.
Supply Chain Analysis
Regional distribution centers in Dallas, Shanghai, and Rotterdam anchor hub-and-spoke patterns for gaming hardware and immersive technology components. Manufacturing concentrates in China, Taiwan, and South Korea for VR headsets, motion sensors, and redemption equipment. Raw material dependencies span semiconductors, precision motors, and specialized plastics. Single-source vulnerability in haptic feedback componentry creates chokepoint exposure. Distribution runs through authorized equipment dealers with certified installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by repeat-visit economics and subscription-like membership models that generate predictable revenue streams.
For Market Incumbents: Anticipate margin compression from multi-vendor technology partnerships democratizing competitive capability among smaller operators. Defend positioning through backward integration into proprietary content development, mirroring Dave & Buster's in-house game studio model. Prioritize certification investment in ASTM F24 and SAMR compliance to create regulatory moats against unlicensed entrants. For New Entrants and Emerging Players: Begin with mall-based educational role-play formats in tier-two Chinese cities where SAMR documentation burdens have slowed established operators. White-space concentrates in vocational simulation concepts addressing parental demand for value-added experiences. Pursue multi-vendor licensing partnerships to access interactive systems without captive R&D investment. For Investors and Strategic Acquirers: Valuations sit cheapest among clustered attraction networks with regulatory compliance costs already amortized across multiple country installations. Long-term viability frames around 5-10 year windows of immersive technology refresh cycles. Target operators with dedicated regulatory affairs capacity for Chinese market access. Monitor equipment certification timeline tightening as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Content Development | In-house game studios compress refresh cycles and reduce licensing dependency for operators like Dave & Buster's. |
| Multi-Vendor Technology Partnership | Sourcing flexibility democratizes access to immersive systems previously reserved for vertically integrated chains. |
| Regulatory Certification Investment | ASTM F24 and SAMR compliance creates barriers protecting established operators while enabling premium positioning. |
| Educational Role-Play Format Expansion | Mall-based vocational simulation concepts anchor entertainment zones and address parental value demands. |
| Clustered Attraction Network Buildout | Geographic concentration spreads compliance and marketing costs across multiple venues as Merlin Entertainments demonstrates. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with venue operations directors, gaming equipment procurement managers, mall development leasing executives, and immersive technology integrators informed demand-side assessment. Secondary sources include SEC 10-K filings from publicly traded operators, SAMR equipment certification databases, ASTM F24 standards documentation, and urban mixed-use development planning records. Bottom-up venue count and spend-per-visit estimates triangulated against top-down market sizing from regulatory filings and industry associations.
Rate-of-change decomposition separates volume expansion from pricing evolution across the projection horizon. Segmentation dimensions modeled include facility type, technology integration tier, target audience demographic, and service mix composition. CAGRs derive from installed base growth, per-visit spend trajectories, and technology refresh cycle frequencies. Forecast inputs incorporate SAMR licensing timeline changes, ASTM F24 standards evolution, and urban entertainment complex development pipelines.
Caveats apply where regulatory timeline acceleration, equipment certification backlogs, or consumer leisure budget reallocation could materially shift the outlook. Forecasts reflect assumptions around continued urban mixed-use development momentum and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Indoor Entertainment Center Market
Events and Festivals
India Event Services Market
Events and Festivals
Global Exhibition Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Global Roller Coaster Market
Events and Festivals
Events Market
Events and Festivals
Virtual Events Market
Events and Festivals
Global Live Event Ticketing Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
Event Photography Service Market
Events and Festivals
US Amusement and Theme Park Market
Events and Festivals
Global Special Effects Fog and Smoke Machines Market
Events and Festivals
Stage and Scenery Equipment Market
Events and Festivals
Asia-Pacific K-Pop Events Market
Events and Festivals
Photo Booth Market
Events and Festivals
Professional Speaker Market