
 Liquid Hand Soap Market | 2026-2036
Liquid Hand Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Hand Soap Market Analysis
Buyer concentration in healthcare facilities is pivoting as hospital networks consolidate purchasing through group procurement organizations, reducing vendor counts while raising volume thresholds. Unilever leverages its global manufacturing footprint to serve these consolidated buyers with standardized formulations. Procter & Gamble anchors its position through R&D intensity in surfactant chemistry and dermatological testing. Henkel competes via specialized dispensing systems that reduce per-use waste in high-traffic institutional settings.
Liquid hand soap comprises surfactant-based cleansing formulations, typically containing anionic or nonionic detergents at concentrations between 10% and 20% active matter, designed to remove soil and microorganisms from skin through emulsification and mechanical action. Its primary commercial purpose spans infection prevention in clinical environments, hygiene compliance in food service, and daily personal care in residential settings. Foaming soap commands volume leadership in institutional channels where dilution-at-point-of-use reduces shipping costs and dispenser maintenance. Antimicrobial soap concentrates margin pools in healthcare and food-processing applications where regulatory validation commands price premiums. Moisturizing soap sustains household penetration where frequent washing drives dermatological sensitivity concerns.
The EPA regulates antimicrobial claims under FIFRA, requiring substantiated efficacy data before products enter US healthcare and food-service markets. The EU ECHA enforces REACH restrictions on specific biocides, forcing reformulation of legacy antimicrobial actives across export-bound production lines. FDA oversight of healthcare hand hygiene products intersects with CDC infection-control guidelines, creating layered compliance requirements for institutional suppliers. Stakeholders must monitor pending state-level chemical disclosure mandates and shifting biocide authorization timelines to anticipate reformulation costs and portfolio rebalancing needs.
Market Dynamics
Healthcare procurement consolidation through group purchasing organizations is compressing vendor counts while amplifying volume concentration, forcing suppliers to restructure pricing and service models around institutional-scale contracts rather than fragmented facility-by-facility sales.
Growth Catalysts
- REACH biocide restrictions:EU ECHA mandates on legacy antimicrobial actives are accelerating reformulation investment, opening market share for compliant suppliers with validated alternative chemistries.
- Foaming dispenser systems:Dilution-at-point-of-use technology is reducing per-unit shipping weight for institutional buyers, cutting logistics costs by half versus ready-to-use liquid formats.
- Hospital network consolidation:Merged health systems in the US are standardizing hand hygiene protocols across dozens of facilities simultaneously, creating single-vendor opportunities at unprecedented scale.
Market Restraints
- Palm kernel oil price volatility:Surfactant feedstock costs swing with Malaysian and Indonesian harvest cycles, compressing margins for producers locked into annual institutional pricing contracts.
- EPA FIFRA registration timelines:Antimicrobial claim substantiation requires months of efficacy testing and review, delaying new product launches and freezing portfolio refresh cycles.
- Refill pouch substitution:Concentrated at-home dilution formats are capturing household volume from traditional pump bottles, threatening brand loyalty and shelf space economics.
Strategic Opportunities
- India PLI scheme for chemicals:Production-linked incentives for specialty surfactant manufacturing are attracting contract producers to serve both domestic retail and export markets.
- Touchless dispensing convergence:Integration of IoT sensors with soap reservoirs enables usage tracking and predictive refill alerts, creating subscription revenue streams from hardware-software bundles.
- Clean label dermatological positioning:Fragrance-free, dye-free formulations for sensitive skin are commanding shelf space in premium pharmacy channels where clinical validation drives repeat purchase.
Industry Challenges
- Biocide chemist talent scarcity:Formulation scientists with dual expertise in surfactant chemistry and regulatory toxicology command premium compensation, constraining R&D team expansion.
- Legacy dispenser incompatibility:New concentrate formats require retrofitting thousands of installed pump mechanisms in schools and airports, slowing adoption despite operational savings.
- ISO 16110 certification complexity:Virucidal efficacy testing for healthcare claims demands specialized laboratory partnerships and extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Hand Soap Market |
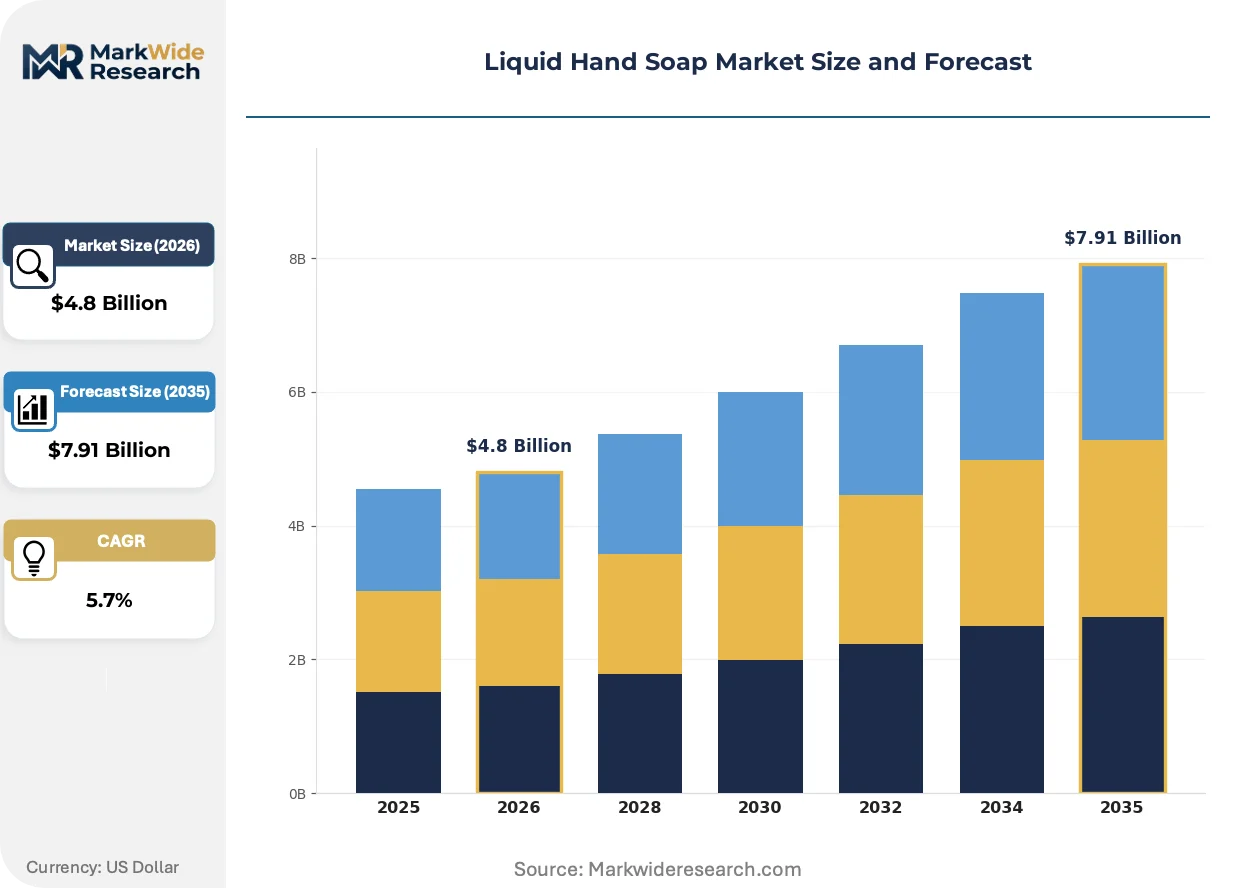
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foaming Soap, Antimicrobial Soap, Moisturizing Soap, Scented Soap End User: Households, Healthcare Facilities, Educational Institutions, Corporate Offices Packaging Type: Pump Bottles, Bulk Dispensing, Travel Size, Refillable Containers Sales Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Unilever, Procter & Gamble, Colgate-Palmolive, Reckitt Benckiser, Henkel, GOJO Industries, 3M, SC Johnson, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Hand Soap Market Emerging Trajectories
Reformulation chemistry and dispensing hardware are converging to reshape competitive positioning, with regulatory pressure on legacy actives accelerating investment in alternative antimicrobial systems and smart infrastructure.
Plant-derived surfactant blends based on coconut and corn feedstocks are consolidating market share in premium household and institutional channels. Food service operators and boutique hotel chains are adopting these formulations at pace to meet corporate sustainability commitments and preempt disclosure mandates. This shift is consolidating supplier relationships around biobased chemical specialists with integrated agricultural sourcing.
EU ECHA REACH authorization timelines for isothiazolinone biocides are forcing staged withdrawal of legacy preservatives from export-bound production lines. Manufacturers serving European markets must validate alternative preservation systems or face market exclusion, with antimicrobial hand soap portfolios facing the most acute reformulation pressure. Contract producers in Southeast Asian manufacturing clusters are responding by building dual-formulation capabilities to serve REACH-compliant and legacy markets simultaneously.
Group purchasing organizations are unbundling hand hygiene procurement from broader infection control bundles, enabling direct supplier relationships for high-volume liquid soap categories. Hospital networks are replacing distributor-mediated purchasing with centralized contracts that specify formulation standards, dispenser compatibility, and compliance reporting. This pattern is most visible in US integrated delivery networks where procurement teams negotiate multi-year agreements covering hundreds of affiliated facilities.
Liquid Hand Soap Market Segmentation
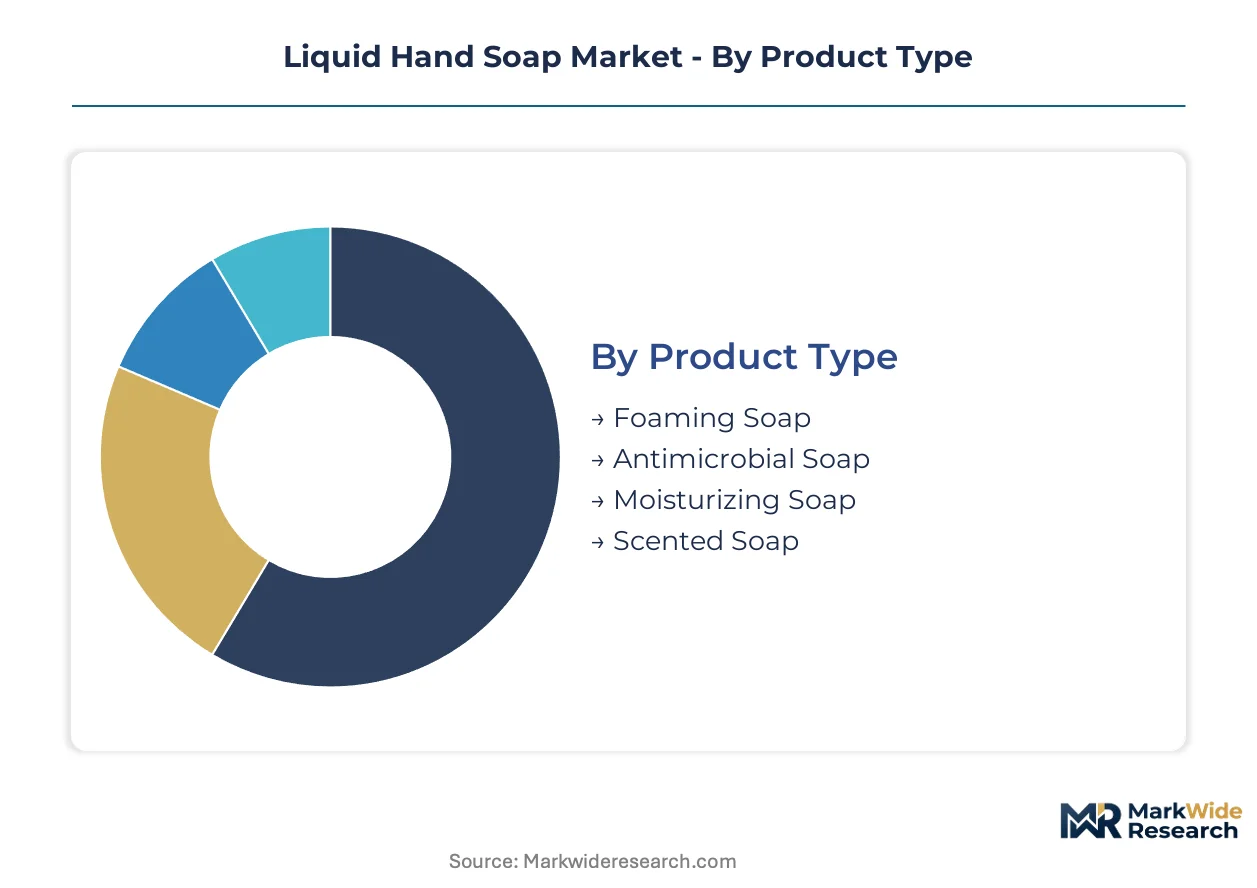
Liquid hand soap segmentation reveals how formulation chemistry, dispensing infrastructure, and procurement channels create distinct margin pools. Manufacturers must align R&D investment and distribution strategy to the specific compliance and volume requirements of each segment cluster.
Product Type:
Supply concentration for surfactant actives and biocide alternatives varies sharply across formulation categories, with institutional buyers driving standardization while household channels reward differentiation.
- Foaming Soap:Dilution-at-point-of-use systems reduce active surfactant concentration to 5-8% versus 15-20% in conventional liquids. Demand concentrates in US hospital networks and Southeast Asian manufacturing facilities where shipping weight reduction cuts logistics spend by 40-50%.
- Antimicrobial Soap:Formulations containing benzalkonium chloride or alternative actives require EPA FIFRA registration for healthcare claims. Procurement is consolidating through group purchasing organizations in merged US health systems, creating single-vendor contracts spanning hundreds of facilities.
- Moisturizing Soap:Glycerin and aloe-enriched variants target dermatological sensitivity from frequent washing. Premium pharmacy channels in Germany and France prioritize fragrance-free, dye-free certifications.
- Scented Soap:Essential oil and synthetic fragrance formulations dominate household retail in India and Brazil where sensorial attributes drive impulse purchase.
Today's leader: Foaming Soap. Tomorrow's challenger: Antimicrobial Soap.
End User:
Cost tier segmentation separates commodity procurement from validated supply relationships, with compliance burden and volume scale determining supplier economics.
- Households:Individual consumers purchase through retail and e-commerce channels, with refill pouch formats capturing volume from traditional pump bottles in European and North American markets.
- Healthcare Facilities:Infection-control protocols mandate antimicrobial formulations with documented efficacy against specific pathogens. US hospital networks standardize protocols across integrated delivery networks, consolidating vendor relationships.
- Educational Institutions:K-12 schools and universities prioritize bulk dispensing systems with low per-use cost. Budget constraints favor foaming concentrates over ready-to-use liquids.
- Corporate Offices:Facility management companies specify touchless dispensing systems with IoT-enabled refill monitoring. Class A commercial buildings in Singapore and Dubai mandate premium formulations aligned with sustainability certifications.
Healthcare Facilities extract maximum compliance value; Households offer the steepest expansion trajectory for alternative formats.
Packaging Type:
Volume concentration in institutional channels is reshaping packaging innovation, with dilution economics and dispenser retrofit requirements determining adoption speed.
- Pump Bottles:Standard 250-500ml polyethylene terephthalate containers dominate household retail shelf space. Brand loyalty and shelf visibility sustain this format despite environmental pressure.
- Bulk Dispensing:5-20 liter bag-in-box systems serve food processing plants and airport terminals. Malaysian contract manufacturers specialize in these formats for export to Middle Eastern and African markets.
- Travel Size:TSA-compliant 100ml containers target hospitality amenity programs and airline partnerships. Boutique hotel chains in Italy and Japan specify biodegradable formulations.
- Refillable Containers:Concentrate-at-home systems with aluminum or glass permanent dispensers are gaining traction in Scandinavian markets where extended producer responsibility regulations apply.
Bulk Dispensing commands institutional volume leadership; Refillable Containers are climbing the fastest as regulatory pressure intensifies.
Sales Channel:
Customer type segmentation separates transactional retail from relationship-driven institutional supply, with data access and service bundling determining channel economics.
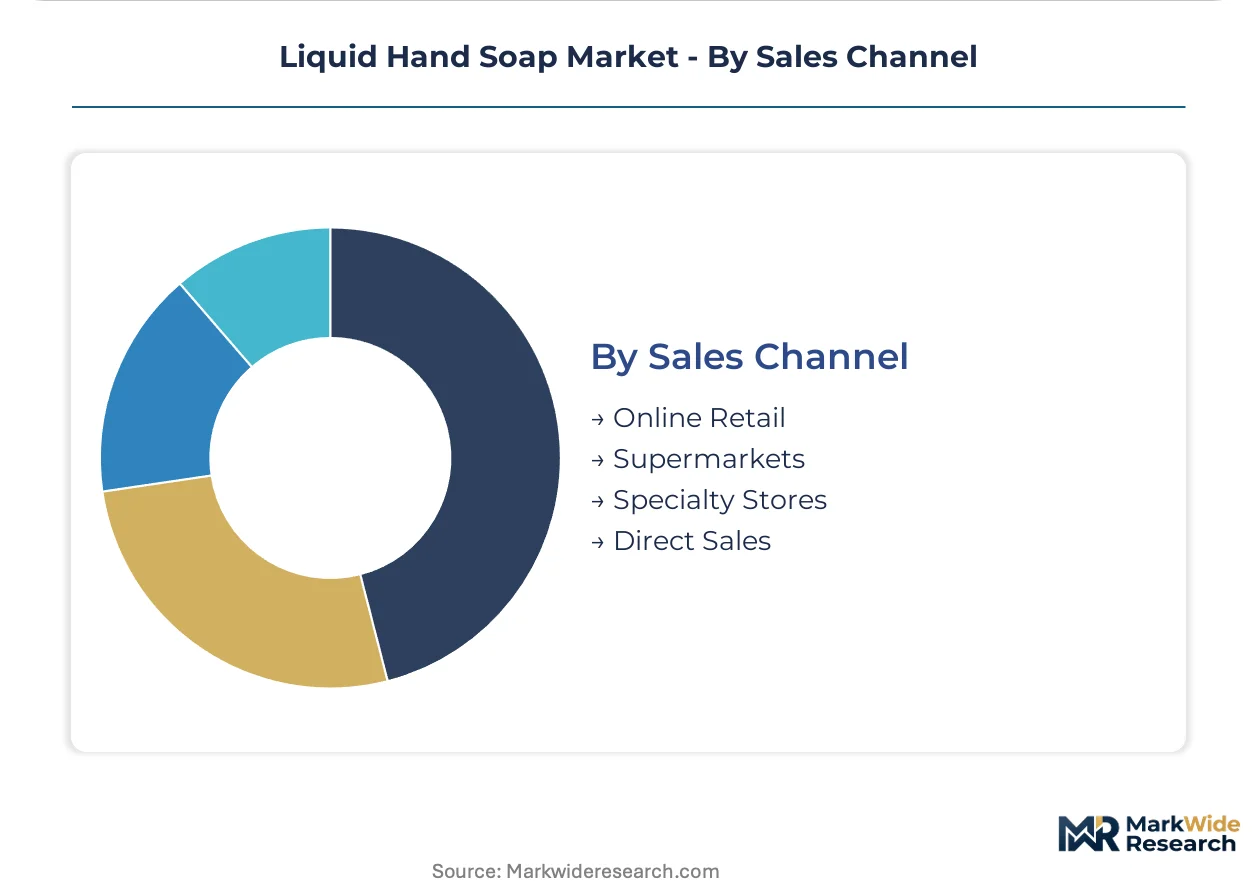
- Online Retail:E-commerce platforms enable direct-to-consumer subscription models for refill cartridges. Amazon and regional platforms in India and Southeast Asia capture growing household volume.
- Supermarkets:Mass merchandisers in the US, UK, and Australia control shelf space allocation through category management fees. Private label penetration is highest in this channel.
- Specialty Stores:Pharmacy chains and organic retailers in Germany and France command premium pricing for clean-label, dermatologically tested formulations.
- Direct Sales:Manufacturer representatives negotiate multi-year contracts with hospital networks and corporate facility managers. Compliance reporting and dispenser maintenance are bundled into pricing.
Supermarkets maintain household volume dominance; Direct Sales is gaining share fastest as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces REACH biocide restrictions more stringently than the United States, where EPA FIFRA registration timelines create divergent compliance burdens for multinational suppliers.
United States
Hospital network consolidation through integrated delivery networks is standardizing hand hygiene protocols across hundreds of facilities simultaneously. The EPA regulates antimicrobial claims under FIFRA, requiring substantiated efficacy data before products enter healthcare markets. Cincinnati and Chicago host major manufacturing operations serving these consolidated buyers with institutional-scale contracts.
Germany
Premium pharmacy channels prioritize fragrance-free, dermatologically tested formulations for sensitive skin applications. The EU ECHA enforces REACH restrictions on specific biocides, forcing reformulation of legacy antimicrobial actives. Düsseldorf and Hamburg anchor contract manufacturing clusters serving both domestic retail and export channels with dual-formulation capabilities.
China
Domestic manufacturing capacity is expanding to serve Southeast Asian export demand for bulk dispensing systems. The country's national chemical regulator monitors surfactant production standards under evolving GB frameworks. Guangdong and Zhejiang provinces concentrate contract producers supplying foaming concentrate formats to institutional buyers across Asia-Pacific.
India
Production-linked incentives for specialty surfactant manufacturing are attracting contract producers to serve domestic retail and export markets. The BIS framework governs quality standards for personal care formulations entering institutional channels. Maharashtra and Gujarat host expanding manufacturing clusters producing both antimicrobial and moisturizing variants for regional distribution.
Brazil
Scented formulations dominate household retail where sensorial attributes drive impulse purchase behavior. ANVISA oversees cosmetic and hygiene product registration requirements for antimicrobial claims. São Paulo anchors distribution networks serving both domestic mass merchandisers and export channels to neighboring South American markets.
Liquid Hand Soap Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure concentrates volume among multinational consumer goods groups with integrated surfactant supply chains, while mid-tier regional manufacturers capture institutional niches through dispensing system specialization. Strategic archetypes include global brand owners with R&D-intensive dermatological portfolios, contract manufacturers with flexible formulation capabilities, and dispensing hardware integrators bundling IoT-enabled infrastructure. Dominant competitive moves encompass backward integration into biobased surfactant feedstocks and multi-year procurement contracts with consolidated healthcare networks.
Within the diversified multinational tier, Unilever, Procter & Gamble, and Henkel occupy positions exemplifying distinct strategic orientations toward institutional versus household channel concentration. Unilever leverages global manufacturing footprint advantages to serve consolidated buyers with standardized formulations. Procter & Gamble anchors market presence through surfactant chemistry expertise and dermatological testing infrastructure. Henkel competes via specialized dispensing systems that reduce per-use waste in high-traffic institutional settings, representing the hardware-software convergence archetype.
| Leading Market Players |
|---|
| Unilever |
| Procter & Gamble |
| Colgate-Palmolive |
| Reckitt Benckiser |
| Henkel |
| GOJO Industries |
| 3M |
| SC Johnson |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EPA-registered antimicrobial formulations and commodity surfactant blends manifests in both pricing premiums and supply chain sourcing strategies. REACH-compliant biocide alternatives command 15-25% raw material cost premiums that concentrate procurement relationships around validated chemical suppliers in Germany and the Netherlands, while bulk institutional contracts for foaming concentrates compress margins through annual volume commitments.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors for standard surfactant grades across Asia-Pacific institutional channels. Three-tier pricing structure across premium dermatological, standard institutional, and economy household levels differentiates primarily on certification burden and dispenser compatibility rather than base chemistry. Pricing pressure stems from palm kernel oil feedstock volatility tied to Malaysian harvest cycles, compressing margins for producers locked into multi-year healthcare contracts. Hospital procurement teams exhibit lowest price sensitivity due to infection-control liability exposure, while K-12 educational buyers prioritize per-use cost minimization above formulation sophistication.
Supply Chain Analysis
Specialized formulation chemists in Düsseldorf, Hamburg, and Guangdong anchor global production of REACH-compliant antimicrobial actives. Surfactant manufacturing draws from coconut-derived feedstocks in Southeast Asia, corn-based alternatives in the US Midwest, and palm kernel oil from Malaysian estates. Single-source vulnerability concentrates in isothiazolinone biocide alternatives where ECHA authorization timelines lag reformulation demand. Distribution runs through group purchasing organization networks for healthcare volumes, diverging to mass merchandiser and e-commerce channels for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where dermatological validation and IoT-enabled dispensing infrastructure command durable premium positioning. Demand is shifting toward fragrance-free, clinically tested formulations that justify subscription-based hardware-software bundles in corporate and healthcare settings.
For Market Incumbents: Extend formulation certification pipelines to preempt REACH biocide phase-outs, securing dual-formulation capabilities in Southeast Asian contract manufacturing clusters. Deepen backward integration into biobased surfactant feedstocks to insulate margin structures from palm oil volatility. Channel control through direct sales relationships with consolidated hospital networks offers defensive moats against refill pouch substitution in household segments. For New Entrants and Emerging Players: E-commerce subscription routes for concentrate-at-home systems present the most penetrable white space in Scandinavian and German markets where extended producer responsibility regulations accelerate format transition. Target corporate facility management segments in Singapore and Dubai where sustainability certification mandates create specification advantages for plant-derived formulations. A direct-to-consumer launch with aluminum permanent dispensers and refill cartridge subscriptions bypasses supermarket slotting fee barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital network procurement teams unbundle hand hygiene from broader infection control bundles, favoring suppliers with integrated dispensing hardware capabilities. Long-term viability centers on dermatological testing infrastructure and regulatory affairs expertise rather than commodity surfactant production scale. Acquisition target archetypes include IoT-enabled dispensing system specialists and biobased surfactant producers with agricultural sourcing relationships. Monitor ECHA biocide authorization timelines as the critical inflection signal for portfolio rebalancing needs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biobased Feedstocks | Captive supply of coconut and corn-derived surfactants insulates margin structures from Malaysian palm oil price swings. |
| IoT Dispenser Hardware-Software Bundles | Touchless systems with predictive refill alerts create subscription revenue streams from corporate facility managers. |
| REACH-Compliant Reformulation Investment | Alternative biocide validation secures European market access as ECHA withdraws legacy preservative authorizations. |
| Direct Sales to Consolidated Hospital Networks | Multi-year contracts with integrated delivery networks replace fragmented distributor-mediated purchasing relationships. |
| Clean Label Dermatological Positioning | Fragrance-free certifications command pharmacy channel shelf space in Germany and France where clinical validation drives repeat purchase. |
Methodological Framework
Multiple input streams — primary interviews with procurement directors at group purchasing organizations, formulation scientists at contract manufacturers, and facility managers in healthcare and corporate settings — were reconciled against secondary validation from EPA FIFRA registration databases, EU ECHA biocide authorization records, and customs trade data on surfactant feedstock flows. Bottom-up volume modeling across product type, end user, and packaging format segments was cross-checked against top-down market sizing derived from institutional procurement spend analysis.
Data-stream reconciliation anchored volume and value outputs to segment-specific growth trajectories across the projection horizon. The analytical framework modeled formulation chemistry tiers, dispensing infrastructure types, procurement channel structures, and regional regulatory clusters as independent demand drivers. CAGRs were derived from elasticity-adjusted volume projections incorporating healthcare facility expansion rates and household format substitution patterns. Forecast inputs included REACH biocide authorization timelines and hospital network consolidation velocity as structural demand modifiers.
The model assumes a particular technology adoption path for touchless dispensing convergence; alternative pathways for IoT sensor integration or concentrate-at-home formats would alter the outlook for hardware-software bundle penetration. Forecasts reflect assumptions on regulatory enforcement consistency and institutional procurement centralization velocity. Material deviation in ECHA authorization timelines or palm kernel oil supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
US Soap Dispenser Market
Household Items
Plastic Carafe Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Enameled Cookware Market
Household Items
Kitchen Towel Market
Household Items
Shoe Shine Machine Market
Household Items
Window Rain Guards Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Canada Digital Showers Market
Household Items
US Digital Showers Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Folded Tissues Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Book Light Market
Household Items
Sanitary Metal Ware Market
Household Items
Home Scales Market