
 Europe Home Fitness Equipment Market | 2026-2036
Europe Home Fitness Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Fitness Equipment Market Foresight
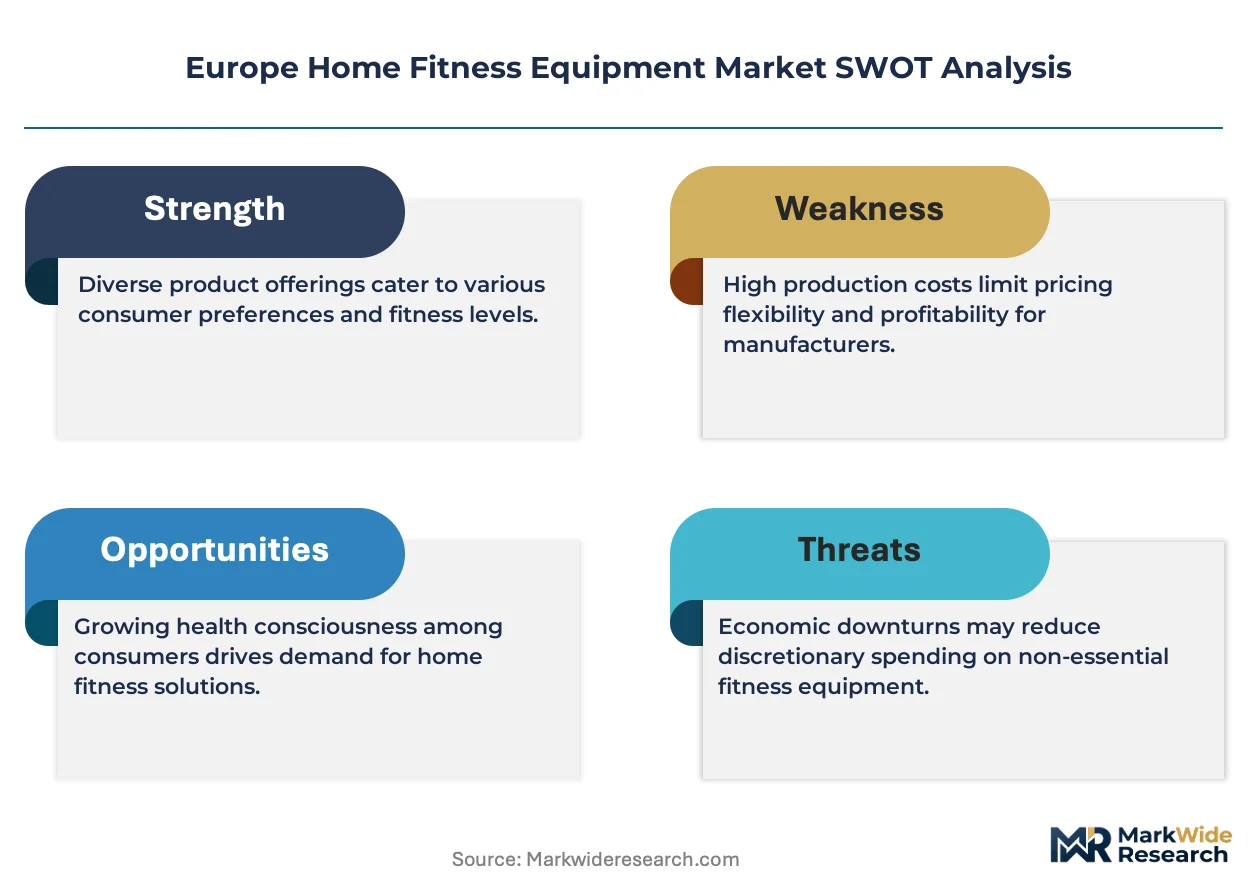
Apartment-dwelling professionals are redrawing demand patterns in the Europe Home Fitness Equipment Market as space-constrained buyers replace bulky gym machines with compact, multi-functional systems. Technogym leverages its Italian manufacturing heritage to sustain premium positioning across European capitals. BH Fitness anchors Iberian market penetration through specialized distribution in Spain and Portugal. NordicTrack competes aggressively on connected content subscriptions that differentiate its hardware from commodity alternatives.
Europe home fitness equipment encompasses mechanically or electronically powered apparatus designed for cardiovascular, strength, or flexibility training within residential settings, typically featuring adjustable resistance mechanisms, foldable frames, or integrated sensor arrays for performance tracking. Treadmills and exercise bikes remain the volume backbone, though margin pools have shifted toward smart equipment with embedded screens and biometric feedback loops. Free weights occupy a mature, price-sensitive tier where brand loyalty weakens and direct-to-consumer channels erode traditional retail margins. Connected devices and wearable technology integrations represent the fastest-expanding segment as interoperability standards consolidate around Bluetooth and ANT+ protocols.
CE marking under the EU Machinery Directive governs mechanical safety, while REACH compliance restricts hazardous substances in rubber grips and polymer coatings, effectively raising compliance costs for budget manufacturers. Germany's national product safety regulator and France's DGCCRF enforce additional national standards that fragment certification requirements across borders. Stakeholders must monitor whether the EU AI Act extends its scope to algorithmic coaching features in smart equipment, as this would trigger new conformity assessment obligations before products reach European households.
Market Dynamics
Hybrid work permanence across European capitals is compressing commercial gym memberships while redirecting capital toward residential fitness infrastructure, fundamentally restructuring equipment procurement cycles and channel economics.
Growth Catalysts
- EU Green Deal product sustainability mandates:REACH compliance requirements for recyclable polymers and reduced hazardous substances in rubber components are accelerating R&D investment in circular material design.
- Bluetooth and ANT+ protocol standardization:Interoperability consolidation between wearable sensors and stationary equipment is enabling seamless biometric data streaming that premium buyers now expect as baseline functionality.
- German urban apartment density:Space-constrained households in Berlin, Munich, and Hamburg are driving foldable frame innovation and multi-functional system development across cardiovascular and strength categories.
Market Restraints
- Steel and aluminum input volatility:Frame material cost swings compress margin pools for mid-tier manufacturers unable to pass through commodity fluctuations.
- CE marking fragmentation:Divergent national interpretations of the EU Machinery Directive between Germany's KBA-adjacent safety regulators and France's DGCCRF create redundant certification burdens.
- Commercial gym subscription recovery:Post-pandemic return rates to traditional fitness facilities in Spain and Italy limit total addressable market expansion for residential alternatives.
Strategic Opportunities
- Eastern European underpenetration:Poland, Czech Republic, and Romania exhibit equipment ownership rates substantially below Western European averages, creating first-mover positioning for compact system specialists.
- EU AI Act algorithmic coaching scope:Pending extension of conformity assessment obligations to embedded training algorithms would advantage early-compliant vendors with established documentation protocols.
- Direct-to-consumer channel maturation:Subscription-integrated hardware models bypass traditional sporting goods retail, capturing lifetime value through content monetization rather than one-time equipment margins.
Industry Challenges
- Embedded software compliance timeline:Anticipated EU AI Act algorithmic accountability requirements demand legal and engineering resources that stretch mid-cap manufacturer capabilities.
- Cross-border logistics reconfiguration:Post-Brexit customs friction and divergent national packaging waste regulations complicate pan-European fulfillment network optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Fitness Equipment Market |
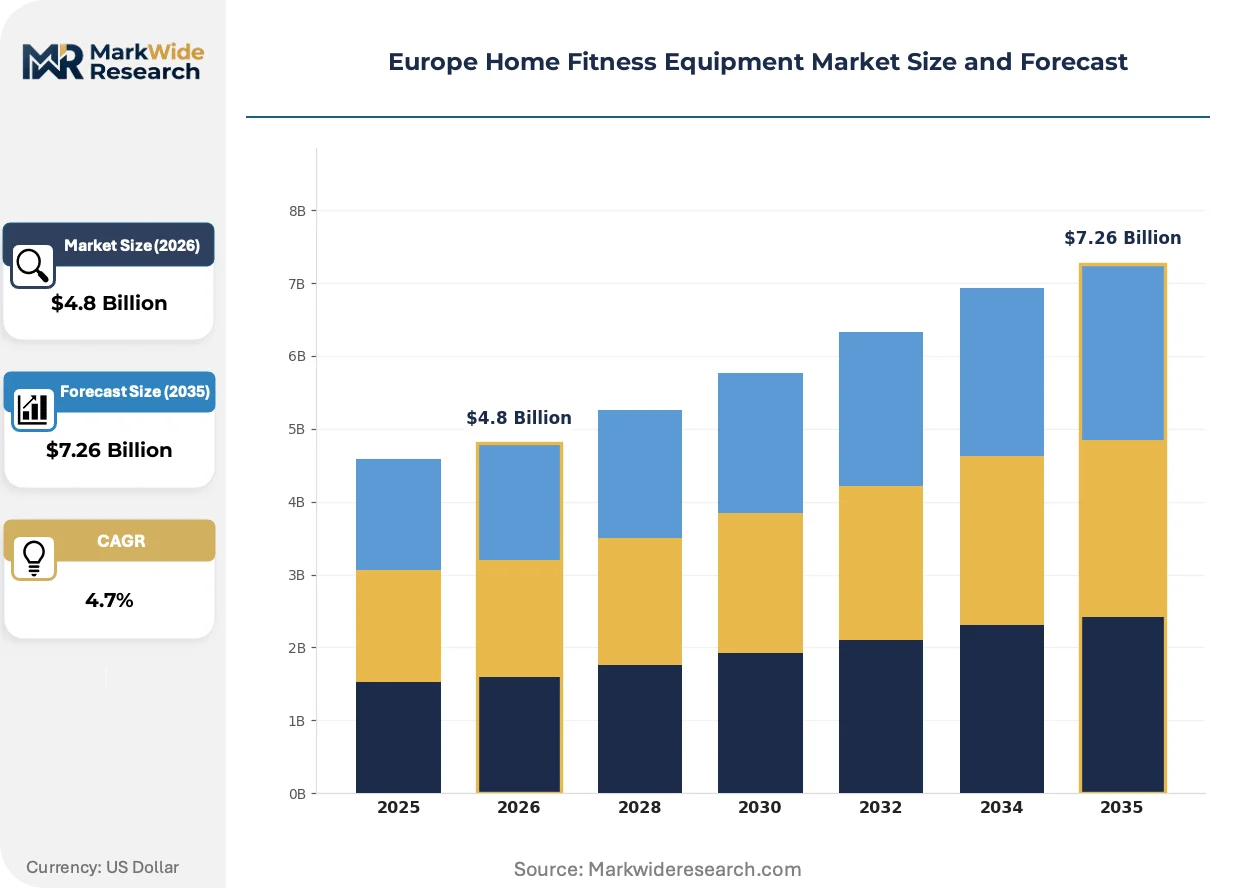
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Exercise Bikes, Free Weights, Resistance Bands End User: Home Users, Fitness Enthusiasts, Athletes, Seniors Technology: Smart Equipment, Traditional Equipment, Connected Devices, Wearable Technology Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Peloton, Gymleco, Technogym, Pulse Fitness, ERGO-FIT, Life Fitness, BH Fitness, NOHrD / WaterRower, NordicTrack, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Fitness Equipment Market Shifts & Advancements
Connected content ecosystems are becoming the primary value differentiator rather than hardware specifications alone, compressing traditional equipment margin structures and elevating software development capabilities to core competitive necessity.
Generative AI-powered coaching algorithms are supplanting static pre-programmed workout libraries. Premium equipment manufacturers deploy adaptive training protocols that adjust resistance and duration in real-time based on biometric feedback. This capability is compressing differentiation timelines for hardware-only competitors and accelerating R&D spend on sensor fusion and machine learning integration.
REACH substance restrictions on phthalates and heavy metals in polymer coatings are forcing reformulation of rubber grip compounds across the supply base. Manufacturers serving Germany and France face the most accelerated compliance timelines due to stricter national enforcement postures. Budget-tier producers without captive chemical engineering resources are exiting or consolidating rather than absorbing certification costs.
Apartment-dwelling professionals now prioritize footprint-to-functionality ratios over absolute performance specifications. Compact multi-modal systems combining resistance training, cardiovascular output, and flexibility work in sub-one-square-meter configurations are displacing single-purpose machines in urban markets. This preference shift is most visible in German and Dutch metropolitan areas where average residential floor space continues contracting.
Europe Home Fitness Equipment Market Segmentation
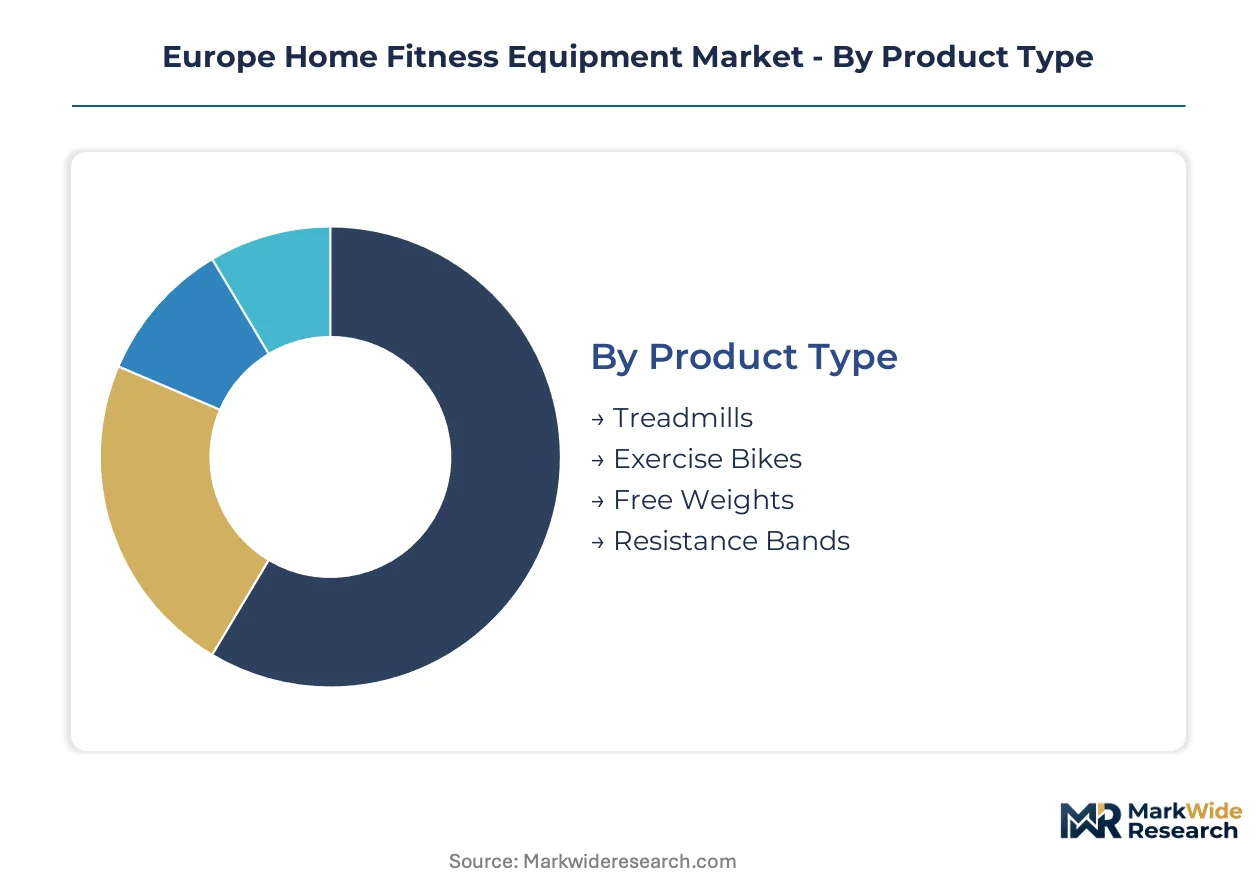
Segmentation in the Europe Home Fitness Equipment Market reveals how margin pools concentrate around technology integration and space-efficient designs. Manufacturers prioritize R&D allocation across these dimensions to capture hybrid work-driven demand.
Product Type:
Premium margin capture concentrates in equipment categories that accommodate embedded screens and sensor arrays without expanding physical footprints.
- Treadmills:Motorized belt systems with adjustable incline mechanisms dominate cardiovascular equipment revenue. German apartment dwellers in Berlin and Munich increasingly specify foldable deck designs that reduce storage depth by sixty percent or more.
- Exercise Bikes:Stationary cycling platforms with magnetic resistance systems and integrated tablet mounts command sustained replacement cycles. Dutch urban households prioritize compact footprint models that slide under standard work surfaces when idle.
- Free Weights:Cast iron and neoprene-coated dumbbell sets occupy mature price tiers where direct-to-consumer channels erode traditional retail margins.
- Resistance Bands:Elastic polymer training systems with graduated tension ratings serve entry-level buyers and travel-oriented fitness routines across Southern Europe.
The dominant share belongs to Treadmills, while Exercise Bikes is closing the gap fastest.
End User:
Customer lifetime value diverges sharply between casual purchasers and subscription-committed enthusiasts who generate recurring software revenue.
- Home Users:Occasional exercisers seeking basic cardiovascular and strength apparatus for residential installation. French regulatory compliance costs from DGCCRF enforcement disproportionately burden budget-tier suppliers serving this cohort.
- Fitness Enthusiasts:Dedicated training populations demanding biometric feedback integration and connected content ecosystems. These buyers drive the steepest expansion trajectory for smart equipment with embedded coaching algorithms.
- Athletes:Performance-focused individuals requiring calibrated resistance precision and power output measurement for sport-specific conditioning protocols.
- Seniors:Age-specific buyers prioritizing low-impact motion ranges and stability-enhancing frame designs with accessible mounting heights.
Home Users still account for the largest installed base, though Fitness Enthusiasts generates the highest revenue per customer.
Technology:
Hardware-software integration intensity determines which technology tiers capture recurring revenue versus one-time equipment sales.
- Smart Equipment:Embedded screen systems with proprietary operating platforms and subscription-locked content libraries. REACH compliance for recyclable polymers in frame construction adds certification overhead that favors established European manufacturers.
- Connected Devices:Sensor-equipped apparatus streaming biometric data to third-party applications via Bluetooth and ANT+ protocols. These systems expand most quickly in German and Benelux markets where wearable technology penetration already exceeds continental averages.
- Traditional Equipment:Mechanically operated apparatus without electronic components or data connectivity, serving price-sensitive segments.
- Wearable Technology:Fitness trackers and smartwatches that synchronize with stationary equipment to unify performance metrics across training modalities.
Smart Equipment holds the revenue concentration, yet Connected Devices is gaining adoption fastest among mid-tier buyers.
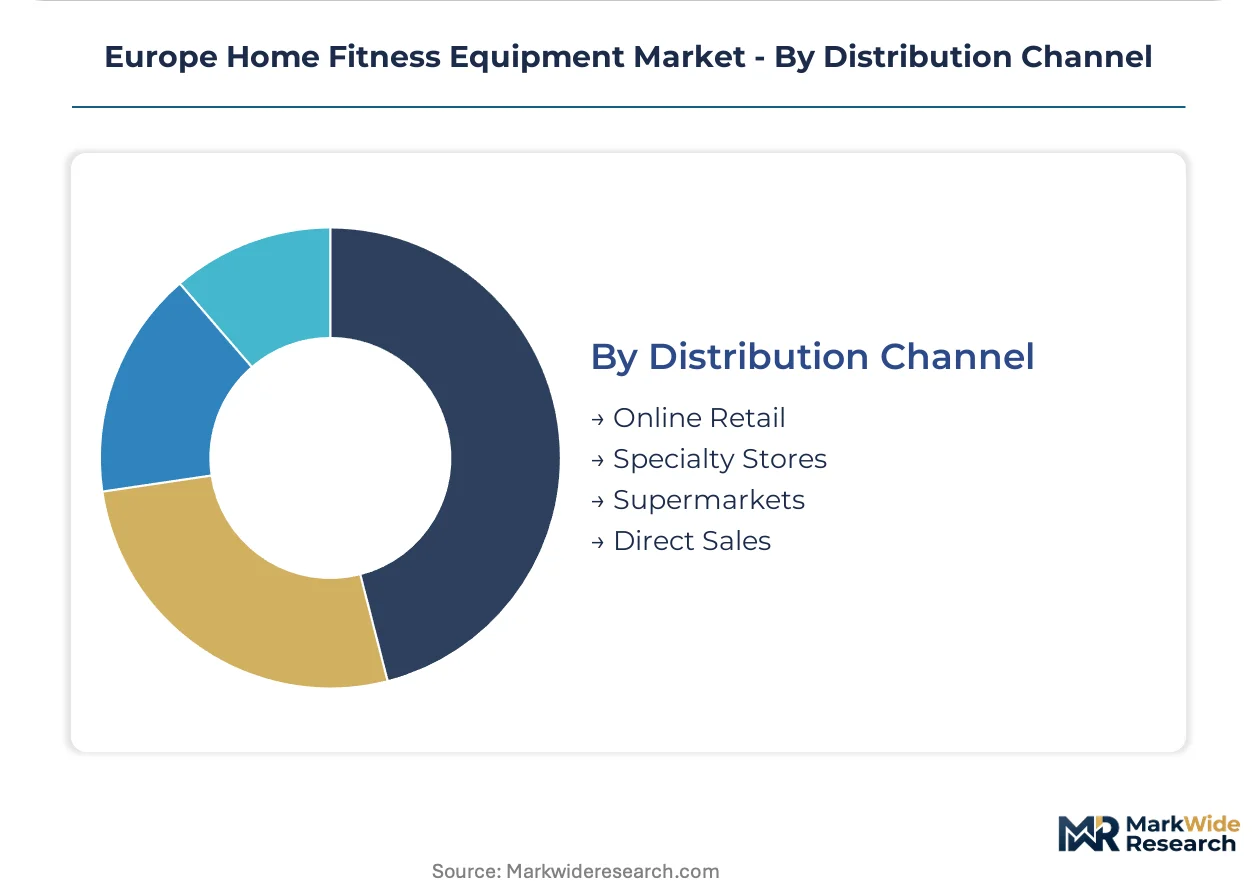
Distribution Channel:
Channel economics shift as content-integrated hardware models bypass traditional retail intermediaries to capture lifetime value directly.
- Online Retail:E-commerce platforms and brand-direct storefronts offering configuration tools and subscription bundling. Post-Brexit customs friction complicates pan-European fulfillment network optimization for UK-based warehouses serving continental buyers.
- Specialty Stores:Dedicated fitness equipment retailers providing assembly services and in-person product demonstration. These outlets retain importance in Spain and Italy where tactile evaluation influences high-consideration purchases.
- Supermarkets:Mass-market retail channels stocking entry-level resistance bands and basic cardiovascular equipment with limited warranty terms.
- Direct Sales:Manufacturer-owned channels eliminating intermediary margins through proprietary websites and field sales teams.
Online Retail commands the volume lead, while Direct Sales is expanding most rapidly among premium smart equipment vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Apartment-dwelling professionals dominate equipment procurement across European capitals, with space-constrained buyers in dense urban centers driving compact multi-functional system demand above all other archetypes.
Germany
Berlin, Munich, and Hamburg households prioritize foldable treadmills and under-desk exercise bikes that reclaim floor space when idle. The KBA-adjacent national product safety regulator enforces stricter CE marking interpretations than neighboring jurisdictions, extending certification timelines for imported equipment. Stuttgart's industrial corridor hosts precision motor manufacturers supplying quiet-drive systems for premium residential cardio machines.
United Kingdom
London's hybrid workforce sustains demand for connected fitness subscriptions bundled with hardware purchases. Post-Brexit customs friction complicates pan-European fulfillment from UK-based warehouses serving continental buyers. Manchester's logistics clusters are reconfiguring distribution networks to bypass Dover-Calais bottlenecks for equipment imports.
France
Parisian professionals favor aesthetic-integrated equipment that complements apartment interiors rather than utilitarian gym designs. DGCCRF enforcement of REACH substance restrictions on rubber grips and polymer coatings accelerates compliance costs for budget-tier suppliers. Lyon houses specialized coating formulators reformulating phthalate-free grip compounds for EU Green Deal alignment.
Italy
Milan and Rome exhibit slower residential equipment penetration as commercial gym subscription recovery limits addressable market expansion. Technogym leverages Italian manufacturing heritage to sustain premium positioning across domestic and export markets. Bologna's engineering districts concentrate frame fabrication for compact strength training systems.
Netherlands
Amsterdam and Rotterdam households lead wearable technology integration rates, driving Bluetooth and ANT+ protocol standardization demand. National packaging waste regulations impose extended producer responsibility obligations that fragment compliance across Benelux borders. Eindhoven's sensor technology cluster supplies biometric feedback components for smart equipment manufacturers.
Europe Home Fitness Equipment Market Competitive Landscape
Player mix skews toward premium-tier specialists and connected-content integrators rather than commodity hardware fabricators. The vendor base concentrates around three strategic archetypes: heritage European manufacturers with domestic production footprints, North American subscription-hardware hybrids, and Asian-origin value producers. Dominant competitive moves include direct-to-consumer channel bypass of traditional retail intermediaries and embedded software development for algorithmic coaching differentiation.
Within the heritage European tier, Technogym and BH Fitness exemplify manufacturing-origin positioning that leverages domestic production credibility for premium pricing power. NordicTrack occupies the subscription-integrated archetype, representing North American content-hardware hybrid models competing aggressively on recurring revenue capture rather than equipment margins alone. Peloton sits within the same tier, illustrating the scale requirements for content ecosystem viability in European market penetration.
| Leading Market Players |
|---|
| Peloton |
| Gymleco |
| Technogym |
| Pulse Fitness |
| ERGO-FIT |
| Life Fitness |
| BH Fitness |
| NOHrD / WaterRower |
| NordicTrack |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for steel frame components compress margin buffers for mid-tier manufacturers while amplifying pricing power for vertically integrated European heritage brands with captive motor production in Stuttgart and Bologna corridors. This lead-time asymmetry stratifies the market into premium subscription-integrated hardware vendors and price-pressured commodity fabricators.
Pricing Analysis
Next-generation smart equipment with embedded generative AI coaching commands three-tier pricing structure across premium, standard, and economy levels that widens against prior-generation connected devices and basic mechanical units. Price differentiation rests on REACH certification tier and embedded software development intensity, with premium tiers bundling multi-year content subscriptions. Pricing pressure stems from steel and aluminum input volatility that commodity-frame manufacturers cannot pass through to German apartment-dwelling buyers. Fitness enthusiasts show lowest price sensitivity while occasional home users in Southern Europe exhibit highest elasticity.
Supply Chain Analysis
Taiwanese semiconductor foundries and Chinese rare-earth magnet processors constitute chokepoints for sensor array and quiet-drive motor production that European equipment vendors cannot easily bypass. Frame fabrication concentrates in Italy and Germany, while polymer coating formulators cluster in Lyon and Eindhoven to meet REACH phthalate restrictions. Single-source vulnerability in Bluetooth chipset supply creates exposure to tariff escalation. Distribution runs through direct-to-consumer brand storefronts that bypass traditional sporting goods retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment ownership rates in Eastern European capitals sit at roughly half Western European penetration, positioning the market for sustained early-cycle expansion as hybrid work patterns normalize across Poland, Czech Republic, and Romania.
For Market Incumbents: Shield premium positioning by deepening in-house production of quiet-drive motor systems in Stuttgart industrial corridors, eliminating exposure to Asian component volatility. Accelerate EU AI Act documentation protocols for algorithmic coaching features before conformity assessment obligations harden. Vertical integration into sensor fusion R&D at Eindhoven technology clusters defends against North American subscription-hardware hybrids. For New Entrants and Emerging Players: CE marking fast-track through German KBA-adjacent regulatory consultants opens first-mover positioning in Warsaw and Prague compact equipment markets. Target underpenetrated Eastern European urban households with foldable multi-functional systems priced below Technogym premium tiers. Direct-to-consumer launch with localized content partnerships bypasses entrenched retail channels in Madrid and Milan. For Investors and Strategic Acquirers: Long-term, this sits as a connected-content infrastructure play because recurring software revenue multiples increasingly dominate hardware-only valuation frameworks. Acquisition candidates with established documentation protocols for EU AI Act algorithmic accountability and captive coating formulation capabilities in Lyon or Eindhoven warrant priority. Watch for inflection when DGCCRF enforcement timelines accelerate REACH compliance costs that force budget-tier exits.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Bypasses Spanish and Italian retail intermediaries to capture lifetime subscription value from fitness enthusiasts. |
| EU AI Act Compliance Documentation | Establishes conformity assessment protocols ahead of algorithmic coaching scope extension by ECHA. |
| REACH-Compliant Coating Formulation | Lyon-based phthalate-free grip compound R&D aligns with DGCCRF enforcement acceleration in France. |
| Compact Multi-Functional System Development | Berlin and Munich apartment density drives foldable frame innovation with sixty percent storage reduction. |
| Eastern European Distribution Partnership | Warsaw and Prague logistics clusters enable first-mover positioning in underpenetrated equipment ownership markets. |
Research Methodology
The analysis maps smart equipment, connected devices, traditional apparatus, and wearable technology segments, each validated through equipment procurement managers at hybrid-work employers, regulatory affairs leads at REACH-compliant coating formulators, direct-to-consumer channel heads, and biomedical engineers integrating Bluetooth sensor protocols. Primary interview insights triangulate against ECHA substance restriction databases, EU Machinery Directive CE marking filings, Benelux packaging waste regulation texts, and customs records for steel and aluminum frame imports. Bottom-up equipment shipment estimates reconcile with top-down hybrid work penetration indices across European capitals.
Consistency checks validate volume and value outputs against external benchmarks for wearable technology adoption rates in Amsterdam and Rotterdam metropolitan areas and REACH compliance cost surveys among Lyon coating specialists. The analytical framework models product type, technology tier, end-user commitment level, and distribution channel intensity across the projection horizon. CAGRs derive from equipment replacement cycle compression observed in German foldable treadmill purchases and subscription attach rate trajectories for NordicTrack-style content-hardware bundles.
Decision-makers should treat outputs as directional under persistent hybrid work patterns and stable REACH enforcement timelines; material deviation in commercial gym subscription recovery rates or EU AI Act scope expansion would warrant model refresh. Practitioners should keep alternative scenarios live as DGCCRF inspection intensity and post-Brexit customs friction at Dover-Calais evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Gym Ball Market
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
Exercise Bike Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
BMI Machine Market
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
Hydrotherapy Treadmills Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
US Fitness Rings Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market