
 Functional Fitness Equipment Market | 2026-2036
Functional Fitness Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Fitness Equipment Market Analysis
Equipment leasing and subscription-based financing is tilting competitive dynamics toward asset-light operators that can refresh inventory without capital strain. Rogue Fitness leverages its captive foundry capacity in Ohio to control kettlebell and bumper plate supply chains. REP Fitness sustains price competitiveness through direct-to-consumer channels that bypass distributor markups. Concept2 anchors the rowing ergometer segment with a reputation for durability metrics that outlast commercial warranty periods.
Functional fitness equipment encompasses strength and conditioning apparatus designed for multi-planar, compound movement patterns rather than isolated muscle targeting, typically fabricated from powder-coated steel with knurled grip surfaces and rated for dynamic loading. These systems serve commercial gyms, military training facilities, and home installations where space efficiency and movement versatility replace single-station machines. The product type dimension shows kettlebells and resistance bands capturing volume leadership due to low unit cost and minimal footprint, while wall-mounted and modular installations are gaining share as boutique studios optimize floor plans. Distribution through online retail and specialty stores now competes with direct sales for customer relationships, particularly among home users seeking configuration guidance.
The US Consumer Product Safety Commission and ASTM International govern structural integrity and pinch-point safety for free-standing rigs, while the EU Machinery Directive and EN ISO 20957 standards mandate CE marking and documented risk assessments for equipment sold across member states. These frameworks elevate compliance costs for new entrants but protect incumbent manufacturers with established testing protocols. Stakeholders must monitor how evolving hybrid work patterns reshape the split between corporate wellness budgets and individual home gym investments.
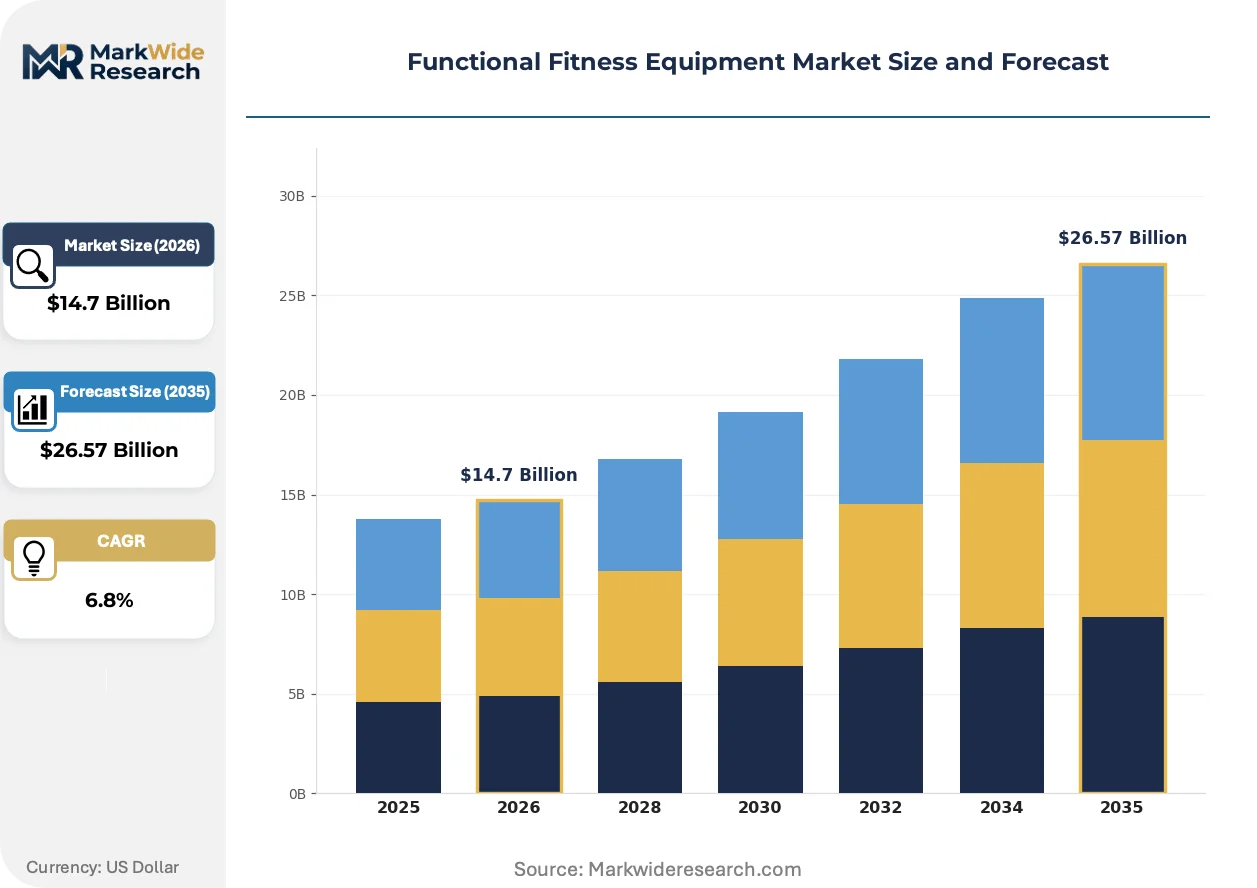
Market Dynamics
Equipment leasing and subscription-based financing is tilting competitive dynamics toward asset-light operators that can refresh inventory without capital strain. Boutique fitness studios and hybrid training facilities are expanding procurement of rigs and racks while ASTM F1749 and ISO 20957 standards tighten certification requirements in North America and Europe.
Growth Catalysts
- ASTM F1749 Certification Mandate:North American commercial gym operators face mandatory structural integrity testing for free-standing rigs, accelerating replacement cycles for aging equipment inventories.
- HYROX Affiliate Network Expansion:Germany's standardized competition format drives premium equipment refresh cycles across Central European boutique studios seeking competition-grade specifications.
- Powder-Coated Steel Fabrication:Advanced coating technologies extend equipment lifespan in high-humidity environments, reducing total cost of ownership for coastal facility operators.
Market Restraints
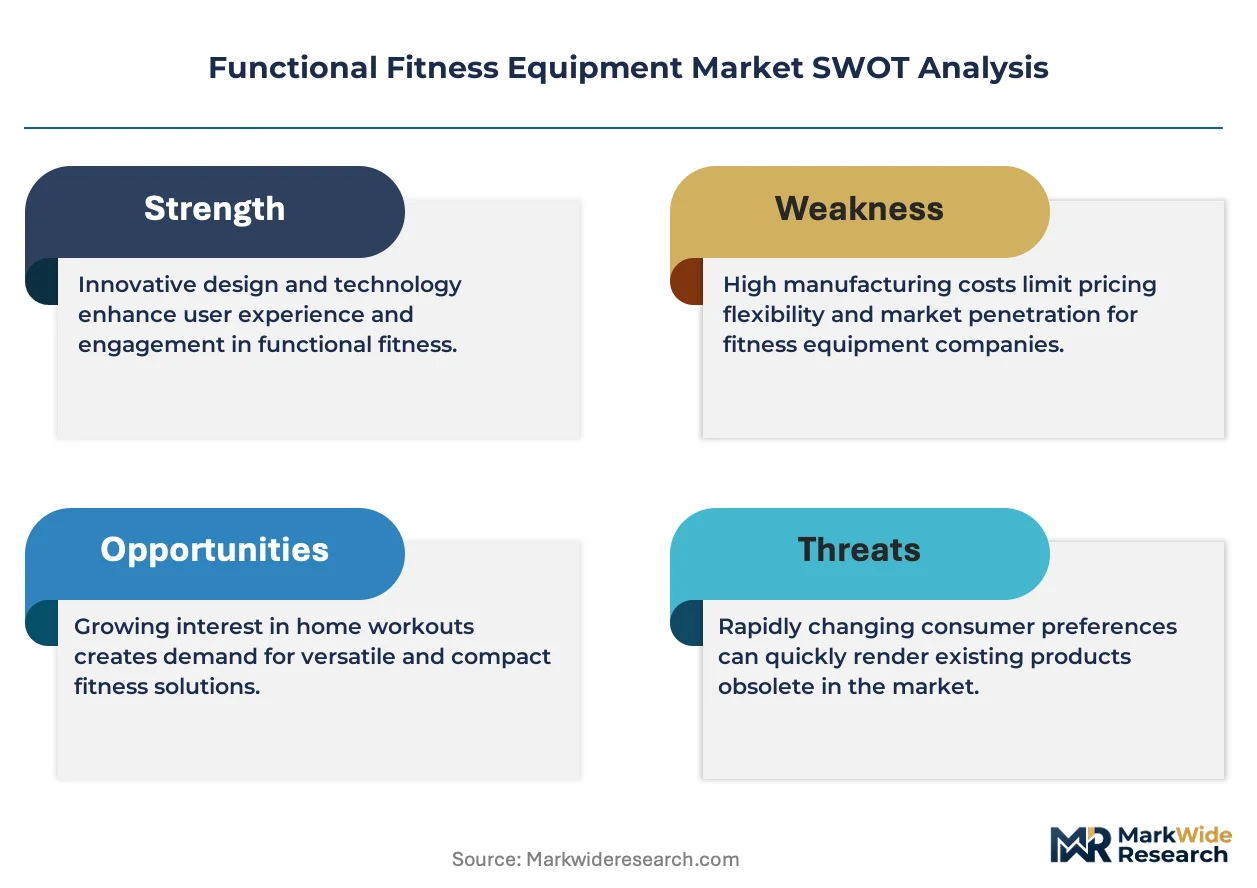
- Steel Input Cost Volatility:Powder-coated steel and knurled grip surface materials face commodity price swings that compress margin predictability for fabrication-heavy product lines.
- Ohio Foundry Concentration:Captive kettlebell and bumper plate supply chains cluster in single-region production capacity, creating geographic vulnerability to logistics disruption.
- CE Marking Documentation Burden:EU Machinery Directive compliance requires extensive risk assessment protocols that extend time-to-market for new modular rig configurations.
Strategic Opportunities
- Corporate Wellness Budget Reallocation:Hybrid work patterns redirect employer fitness spending toward home gym stipends and decentralized equipment subsidies.
- Direct-to-Consumer Channel Bypass:Specialty retailers and online platforms displace traditional distributor networks, enabling margin capture through configuration guidance services.
- Modular Wall-Mounted Systems:Space-constrained urban studios in dense metropolitan clusters drive demand for floor-plan-optimized installations.
Industry Challenges
- Multi-Planar Movement Certification Gap:Equipment testing protocols lag behind dynamic loading requirements for compound exercise patterns, creating liability exposure.
- Inventory Refresh Cycle Compression:Rapid aesthetic and feature turnover forces capital-intensive stock rotation for retailers holding physical demonstration units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Fitness Equipment Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kettlebells, Resistance Bands, Medicine Balls, Stability Balls End User: Commercial Gyms, Home Users, Corporate Wellness, Athletic Trainers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Fitness Equipment Distributors Installation: Portable, Wall-Mounted, Free-Standing, Modular |
| Companies Covered | Concept2, REP Fitness, Rogue Fitness, Atlantis Strength, TRX, Life Fitness, Bowflex, Precor, Hammer Strength, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Fitness Equipment Market Emerging Trajectories
Connected sensor integration and embedded performance tracking are actively reshaping how equipment manufacturers differentiate commodity hardware. Three distinct developments are compressing traditional competitive advantages.
Force plate and accelerometer embedding in kettlebells and resistance bands is digitizing workout data capture for remote coaching applications. Boutique studios in metropolitan clusters adopt these systems fastest, compressing the advantage gap between premium facilities and independent trainers.
EU Machinery Directive amendments to EN ISO 20957 standards mandate documented risk assessments for equipment sold across member states. Commercial distributors face elevated compliance costs that favor incumbent manufacturers with established testing protocols, squeezing new entrant market access.
Home users now seek configuration guidance through video-enabled sales channels rather than physical showroom visits. Specialty retailers respond with virtual space-planning services, with this behavioral shift most visible in suburban markets where studio density remains low.
Functional Fitness Equipment Market Segmentation
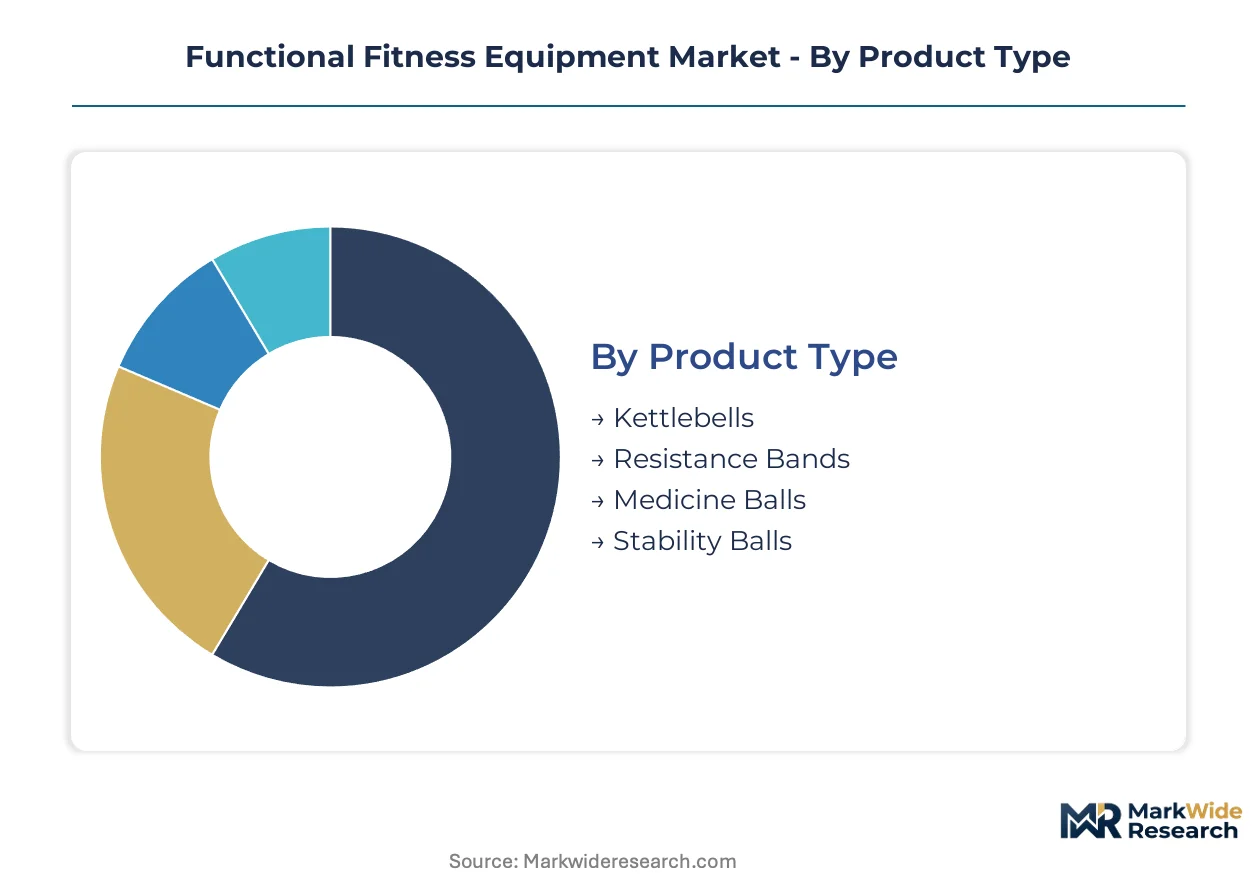
Equipment specification varies sharply across use environments, from space-constrained urban apartments to high-traffic commercial facilities. Segmentation reveals how fabrication standards, load ratings, and connectivity features align with distinct procurement budgets and floor-plan constraints.
Product Type:
Mature cast-iron and rubber-composite formats dominate volume, while sensor-embedded variants represent the emerging premium tier.
- Kettlebells:Cast-iron or steel construction with powder-coated finishes and color-coded weight denominations. Commercial gyms in Germany and the United States refresh inventories most aggressively as HYROX affiliate networks standardize competition-grade specifications.
- Resistance Bands:Latex or fabric-composite elastic loops with calibrated resistance gradients and reinforced anchoring points. Home users in suburban markets drive replacement cycles through subscription-based fitness programming that specifies band tension protocols.
- Medicine Balls:Leather or rubber-shell constructions with stitched or molded grip patterns for rotational throwing and slamming exercises.
- Stability Balls:Anti-burst PVC or thermoplastic elastomer spheres rated for dynamic loading in physical therapy and core conditioning protocols.
Kettlebells handle the majority of throughput; resistance bands are expanding most quickly on share.
End User:
Procurement authority splits between capital-budget facility operators and individual consumers exercising purchasing autonomy through direct channels.
- Commercial Gyms:Multi-location operators with standardized equipment specifications and centralized procurement teams. Boutique studios in metropolitan clusters optimize floor plans with wall-mounted and modular installations that maximize member throughput per square meter.
- Home Users:Individual consumers with space constraints and budget sensitivity driving demand for compact, multi-functional apparatus. Suburban markets with low studio density show highest propensity for connected sensor integration and virtual coaching compatibility.
- Corporate Wellness:Employer-funded fitness stipends and on-site facility investments redirecting traditional gym membership subsidies.
- Athletic Trainers:Individual practitioners and small-group coaches requiring portable equipment for off-site client sessions.
Commercial gyms absorb the largest equipment volume; home users are climbing the fastest as hybrid work patterns persist.
Distribution Channel:
Margin capture shifts from distributor networks toward direct relationships as configuration guidance moves online.
- Online Retail:E-commerce platforms with video-enabled product demonstrations and virtual space-planning tools. Specialty retailers bypass traditional markups through direct-to-consumer channels that bundle assembly guidance and warranty support.
- Specialty Stores:Physical showrooms with equipment testing areas and staff expertise in load-rating specifications and ASTM compliance.
- Direct Sales:Manufacturer-owned channels serving commercial accounts with volume pricing and custom fabrication options.
- Fitness Equipment Distributors:Regional wholesalers maintaining demonstration inventory and installation service networks for institutional buyers.
Online retail captures the dominant transaction flow; direct sales are gaining share fastest among commercial accounts.
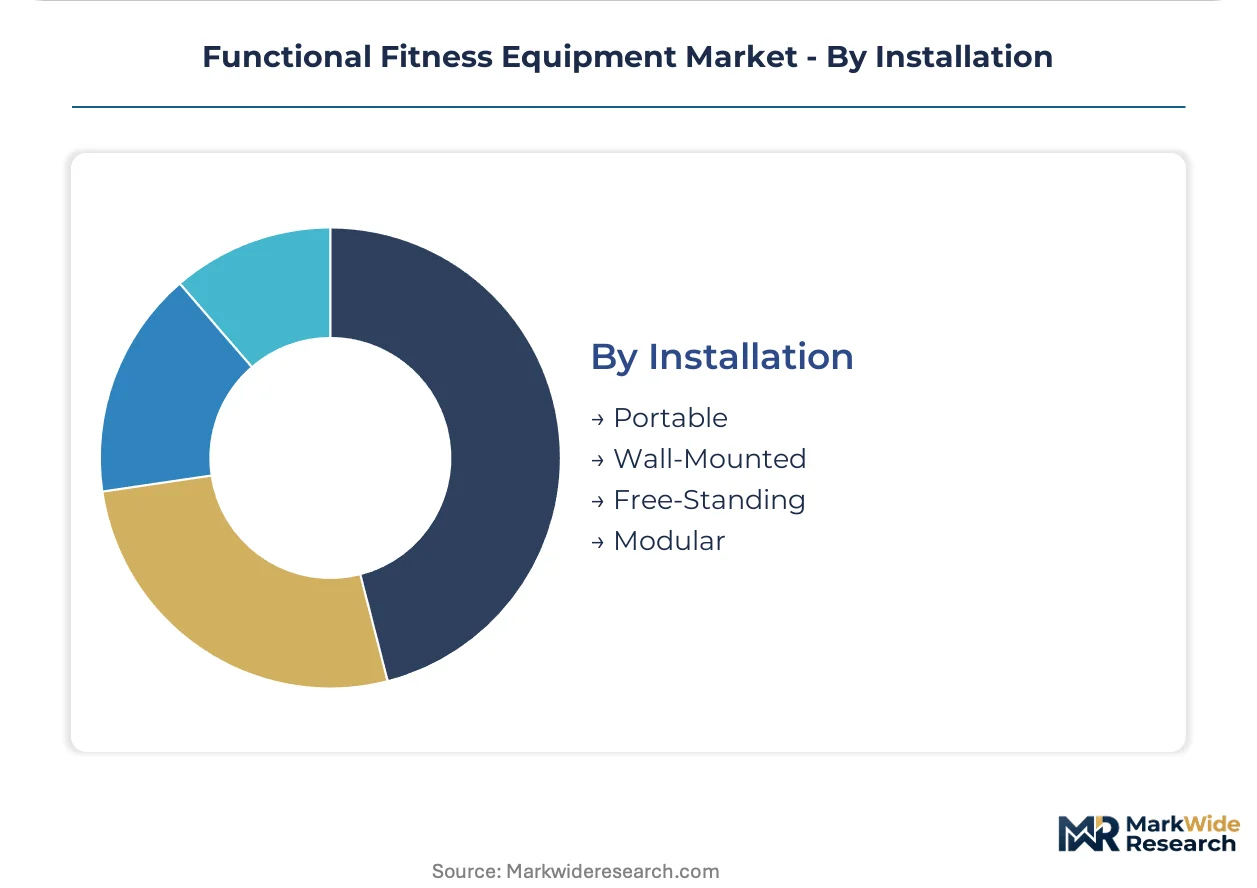
Installation:
Floor-plan optimization drives specification divergence between permanent infrastructure and reconfigurable systems.
- Portable:Non-fixed apparatus requiring no anchoring or structural modification. Athletic trainers and home users in rental properties prioritize this category for deployment flexibility and relocation ease.
- Wall-Mounted:Bracket-fixed rigs and storage systems that reclaim floor space in constrained environments. Boutique studios in dense metropolitan clusters specify these configurations to maximize programming density.
- Free-Standing:Self-supporting rigs and racks requiring ASTM F1749 structural integrity certification for North American commercial deployment.
- Modular:Interchangeable components allowing reconfiguration of pull-up stations, squat racks, and storage attachments without full replacement.
Free-standing installations account for the largest installed base; wall-mounted systems are expanding most rapidly in urban studio construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government fitness incentives and workplace wellness tax credits are redirecting procurement budgets toward home gym installations and boutique studio construction across major economies.
United States
Employer-sponsored wellness stipends and IRS Section 213 medical expense deductions for fitness equipment are accelerating home gym adoption. The US Consumer Product Safety Commission enforces ASTM F1749 structural integrity standards for commercial rigs. Columbus, Ohio hosts captive foundry operations supplying kettlebell and bumper plate fabrication to domestic distributors.
Germany
HYROX affiliate network standardization and CrossFit box expansion are driving premium equipment refresh cycles across boutique studios. The EU Machinery Directive mandates CE marking and EN ISO 20957 compliance for modular rig configurations. Berlin and Hamburg metropolitan clusters concentrate wall-mounted system installations optimizing floor-plan density.
China
Rising disposable incomes and urban fitness culture penetration are expanding demand for compact, multi-functional home apparatus. The State Administration for Market Regulation (SAMR) oversees GB standards for fixed training equipment safety certification. Guangdong Province manufacturing bases supply powder-coated steel fabrication for export-oriented equipment lines.
United Kingdom
Corporate wellness budget reallocation and hybrid work permanence are sustaining home gym investment levels post-pandemic. The Health and Safety Executive references EN ISO 20957 for commercial gym equipment compliance. London boutique studio construction favors modular installations maximizing member throughput per square meter.
Australia
Military and law enforcement physical training procurement is stabilizing demand for competition-grade conditioning apparatus. The Therapeutic Goods Administration (TGA) and state-level consumer protection frameworks govern equipment safety claims. Melbourne and Sydney metropolitan clusters concentrate specialty retailer networks offering virtual space-planning services.
Functional Fitness Equipment Market Vendor Landscape
On the supply side, the industry is moderately consolidated around a mix of vertically integrated domestic fabricators and direct-to-consumer specialists. Three strategic archetypes dominate: captive foundry operators controlling raw material conversion, direct-channel brands bypassing distributor markups, and connected-sensor integrators digitizing commodity hardware. Competitive moves concentrate on geographic capacity expansion and technology licensing partnerships for embedded performance tracking.
Among North American fabricators, Rogue Fitness and REP Fitness exemplify divergent channel strategies, with the former leveraging in-house production capacity and the latter sustaining price competitiveness through direct-to-consumer positioning. Concept2 occupies a distinctive anchor position in the rowing ergometer segment, representing durability-focused product engineering that outlasts standard commercial warranty periods.
| Leading Market Players |
|---|
| Concept2 |
| REP Fitness |
| Rogue Fitness |
| Atlantis Strength |
| TRX |
| Life Fitness |
| Bowflex |
| Precor |
| Hammer Strength |
| Others |
Supply Flow & Price Mechanics
Captive foundry operations in Ohio concentrate kettlebell and bumper plate fabrication, anchoring margin capture in domestic supply chains while downstream distributors absorb logistics markups. Certification-grade equipment commands premium positioning as ASTM F1749 and ISO 20957 compliance costs filter through to end-user pricing.
Pricing Analysis
Certification level creates the primary spread between commercial-grade and consumer-tier equipment. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM F1749 structural testing, CE marking documentation, and powder-coat durability ratings. Cost compression in standard-tier imports is intensifying because Chinese fabrication capacity expands export volumes. Home users in suburban markets exhibit highest price sensitivity, while boutique studios in metropolitan clusters prioritize competition-grade specifications over unit economics.
Supply Chain Analysis
Extended payment terms from Ohio foundries and supply-chain finance facilities stabilize working capital for fabrication-heavy product lines. Raw material sourcing draws from domestic steel mills, Guangdong Province powder-coating facilities, and Malaysian rubber-composite suppliers. Commodity price volatility in steel inputs and logistics chokepoint exposure through West Coast port congestion present structural vulnerabilities. Distribution runs through direct-to-consumer channels, specialty retailer networks, and institutional procurement teams serving military and corporate wellness accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ASTM F1749 and ISO 20957 certification protocols creates durable defensive moats for incumbent manufacturers with established testing infrastructure. Switching costs escalate as commercial gym operators face mandatory equipment replacement cycles.
For Market Incumbents: Entrench certification advantage by accelerating EN ISO 20957 compliance documentation for modular rig configurations. Expand captive foundry capacity in Ohio to secure kettlebell and bumper plate supply chains against logistics disruption. Direct-to-consumer channel control and sensor-embedded product development represent critical defensive levers against connected-fitness entrants.
For New Entrants and Emerging Players: Establish a beachhead in home-user segments through virtual space-planning services and subscription-based equipment financing. Corporate wellness stipends and hybrid work patterns create underpenetrated demand for compact, multi-functional apparatus with remote coaching compatibility. Configuration guidance bundled with warranty support offers the most penetrable go-to-market angle against established distributor networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer brands lacking foundry integration. Long-term viability hinges on backward integration into powder-coated steel fabrication and sensor-technology licensing partnerships. Monitor HYROX affiliate network expansion velocity across Central Europe as an inflection indicator for premium equipment refresh demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | ASTM F1749 compliance accelerates replacement cycles for aging commercial gym inventories. |
| Foundry Capacity Expansion | Captive kettlebell and bumper plate production insulates margin from steel price volatility. |
| Sensor Technology Licensing | Force plate embedding in resistance bands digitizes workout data for remote coaching applications. |
| Direct-to-Consumer Channel Buildout | Virtual space-planning services bypass specialty retailer markups in suburban markets. |
| Corporate Wellness Partnership | Employer-funded fitness stipends redirect traditional gym membership subsidies toward home equipment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial gym procurement directors, boutique studio owners, equipment fabrication plant managers, and specialty retailer category buyers. Secondary validation incorporated ASTM International certification databases, EU Machinery Directive compliance registries, customs trade records for steel and rubber-composite inputs, and SEC filings from publicly listed fitness equipment distributors. Bottom-up equipment shipment data and top-down fitness facility construction permits were triangulated to anchor volume estimates.
Calibration against historical replacement cycles and affiliate network expansion patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and installation configuration alongside competition-grade specification tiers. CAGRs were derived from equipment refresh velocity and facility construction pipeline analysis. Forecast inputs incorporated HYROX affiliate standardization timelines and corporate wellness budget reallocation surveys.
Sensitivities concentrate around steel input cost trajectories, logistics disruption severity, and regulatory amendment timing for EN ISO 20957 standards. Forecasts reflect documented assumptions regarding hybrid work pattern persistence and boutique studio construction rates. Macroeconomic contraction, tariff regime changes, or connected-fitness technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Home Fitness Equipment Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Hydrotherapy Treadmills Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Weight Training Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
China Fitness Rings Market