
 Gym Ball Market | 2026-2036
Gym Ball Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Ball Market Analysis
Subscription-based digital workout programming bundled with physical equipment is consolidating how gym ball manufacturers monetize customer relationships. GoFit leverages its integrated content platform to extend brand stickiness beyond hardware sales. TheraBand anchors its market position through clinical-grade credibility and therapist channel control. URBNFit competes aggressively in direct-to-consumer channels with specialized sizing and color differentiation.
A gym ball is a pneumatic exercise device constructed from burst-resistant PVC, TPE, or rubber compounds, typically inflated to support static and dynamic load ranges for balance training, core activation, and physical rehabilitation protocols. Anti-burst ratings and latex-free material certifications determine clinical and commercial suitability across physiotherapy and fitness environments. Stability balls lead product type demand due to their versatility across professional and home settings, while TPE and EVA materials capture growing preference as phthalate-free alternatives displace conventional PVC in regulated European and North American markets. The 65 cm diameter segment dominates volume as the standard adult sizing, though 75 cm variants gain traction among taller user demographics and specialized rehabilitation applications.
FDA device classification guidance, REACH chemical restrictions, and ISO 20957 fitness equipment standards collectively govern material composition, load testing, and market access for gym ball suppliers across North America and Europe. These frameworks compel manufacturers to invest in certified anti-burst construction and documented supply chain transparency. Stakeholders must monitor evolving state-level chemical disclosure requirements and physiotherapy reimbursement policies that determine institutional purchasing eligibility.
Market Dynamics
REACH compliance deadlines and FDA device classification updates are compressing supplier margins while accelerating material substitution toward phthalate-free compounds. Anti-burst testing protocols now function as gatekeepers for institutional procurement channels.
Growth Catalysts
- Rehabilitation Protocol Standardization:Physical therapy reimbursement policies in Germany and the United States now mandate documented equipment safety ratings. This institutional requirement pulls certified gym ball volumes into clinical settings.
- ISO 20957 Fitness Equipment Standards:Harmonized load-testing and durability benchmarks reduce cross-border certification friction. Manufacturers achieving ISO certification gain accelerated market access across multiple jurisdictions.
- TPE Material Substitution:Thermoplastic elastomer compounds displace conventional PVC in European and North American markets. ECHA chemical restrictions drive formulation shifts that premium suppliers exploit for positioning.
Market Restraints
- Petrochemical Input Volatility:PVC and synthetic rubber feedstock costs fluctuate with crude oil derivatives. Margin compression hits mid-tier manufacturers lacking long-term supply contracts.
- Chinese Production Concentration:Burst-resistant PVC fabrication clusters in Zhejiang and Guangdong provinces. Geopolitical friction or shipping disruption threatens supply continuity for Western distributors.
- Resistance Band Substitution:Elastic resistance equipment competes for core-strengthening exercise budgets. Home fitness consumers sometimes prioritize compact storage over stability ball versatility.
Strategic Opportunities
- India Preventive Healthcare Expansion:Ayushman Bharat insurance coverage extends to physiotherapy interventions. Domestic manufacturers can capture institutional volume as clinical standards formalize.
- Digital-Physical Bundling:Subscription workout platforms seek hardware partnerships to reduce churn. Gym ball suppliers embedding QR-linked training content capture recurring revenue streams.
- EU Green Deal Procurement Incentives:Public sector tenders increasingly weight recycled content and carbon footprint. Suppliers with documented circular material flows access premium municipal and hospital contracts.
Industry Challenges
- Anti-Burst Certification Bottlenecks:Third-party testing laboratory capacity constraints extend product launch timelines. Manufacturers face 8-14 week queues for ISO-compliant validation reports.
- Multi-Jurisdiction Labeling Complexity:California Proposition 65, EU CLP, and state-level chemical disclosure laws demand variant packaging. SKU proliferation strains inventory management for cross-border sellers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Ball Market |
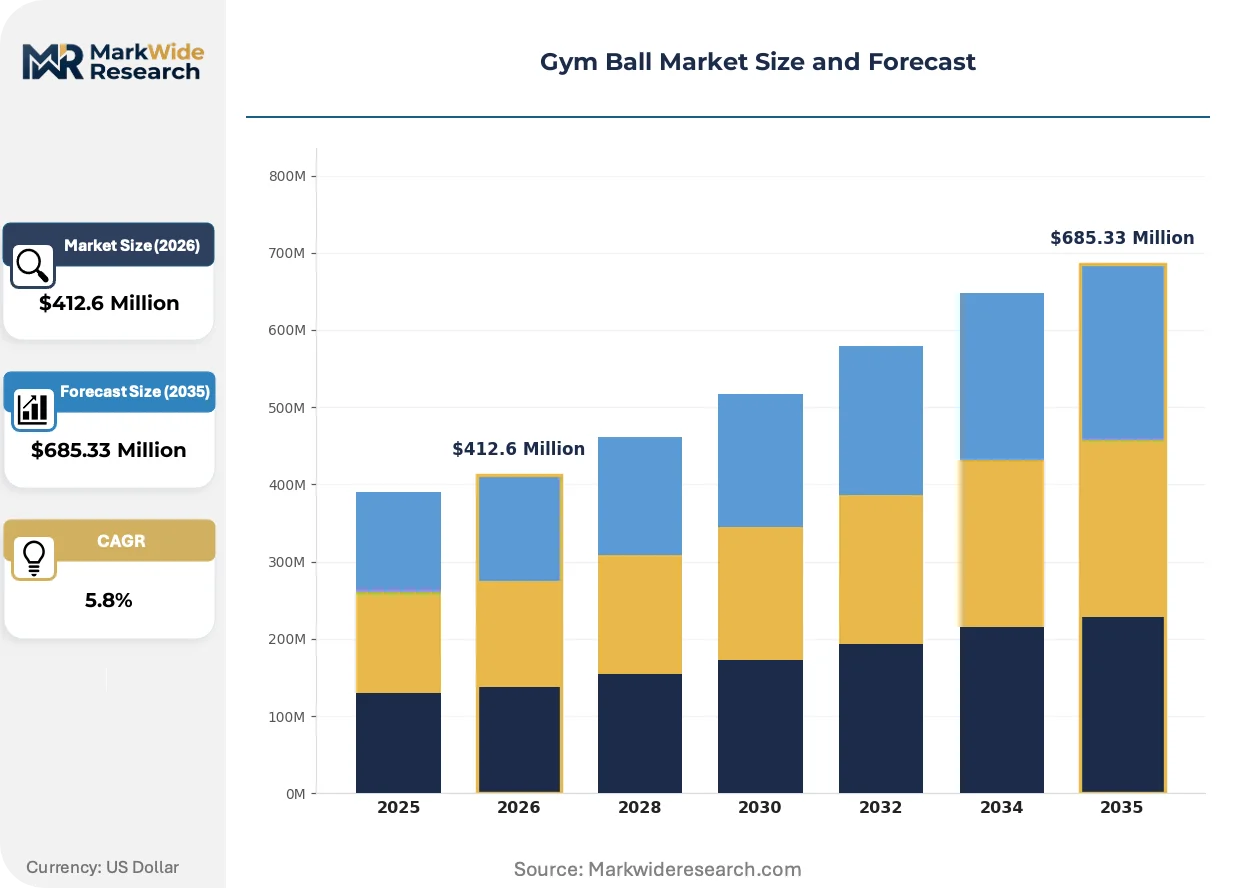
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Balls, Exercise Balls, Stability Balls, Massage Balls Material: PVC, Rubber, TPE, EVA Size: 55 cm, 65 cm, 75 cm, 85 cm End User: Gyms, Physiotherapy Centers, Home Users, Fitness Coaches |
| Companies Covered | GoFit, Vivora, Unisoul Inc., DHZ Fitness, Galsports, Black Mountain Products, URBNFit, YR Fitness, TheraBand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Ball Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine product specifications and channel economics. Suppliers must now engineer for simultaneous compliance, sustainability, and connected fitness integration.
Anti-burst TPE-EVA hybrid compounds are integrating into premium product lines to satisfy dual requirements of phthalate elimination and load-rated performance. Physiotherapy clinics and hospital rehabilitation departments in Germany and the United States are adopting these materials fastest. This chemistry shift is integrating supplier R&D budgets toward polymer compounding capabilities that were previously outsourced.
EU REACH Annex XVII restrictions on phthalate plasticizers now extend to imported fitness equipment. Manufacturers reformulating PVC alternatives face 18-24 month requalification cycles for existing retail partnerships. The 65 cm and 75 cm stability ball segments in European markets are absorbing compliance costs through certified product premiums.
Corporate wellness procurement departments now specify sustainability credentials alongside safety ratings. Direct-to-consumer brands with transparent supply chain documentation are displacing undifferentiated retail private-label alternatives. This specification tightening is most visible in United States technology sector headquarters and Nordic municipal workplace health programs.
Gym Ball Market Segmentation
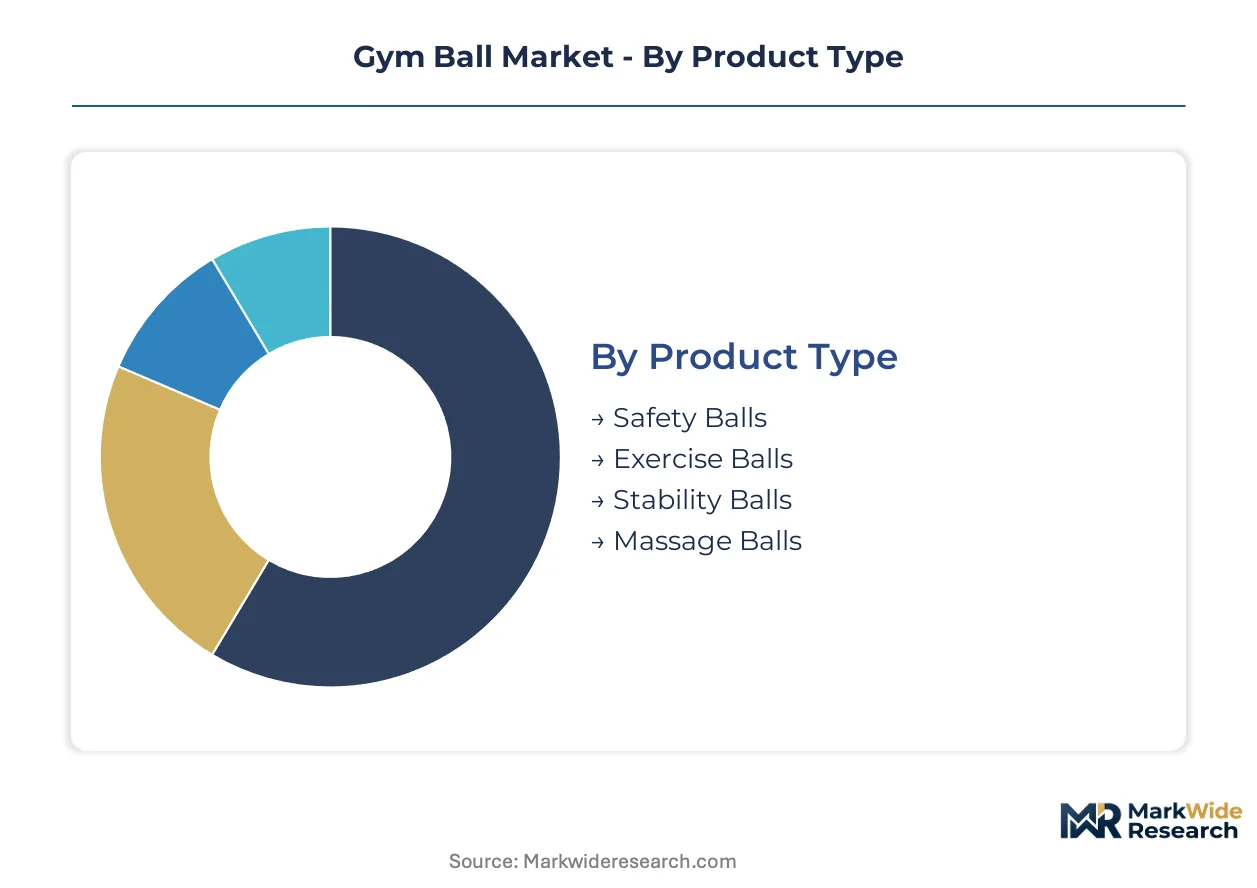
Gym ball manufacturers configure production lines around diameter specifications and material chemistry rather than end-use branding. Segmentation discipline separates high-margin clinical-grade products from commodity fitness equipment, determining which suppliers capture institutional procurement contracts versus direct-to-consumer volumes.
Product Type:
Capital intensity peaks with anti-burst safety certifications and load-rated construction protocols. Manufacturing investments concentrate where institutional liability requirements demand documented testing infrastructure.
- Stability Balls:Burst-resistant PVC or TPE construction supports static and dynamic load ranges for balance training and core activation. Demand concentrates in United States physiotherapy clinics and German rehabilitation centers where ISO 20957 certification determines reimbursement eligibility. TPE-EVA hybrid compounds displace conventional PVC as REACH Annex XVII restrictions tighten.
- Exercise Balls:Standard pneumatic construction targets home fitness and commercial gym environments. United States and Chinese consumers drive volume through direct-to-consumer channels, though margin compression intensifies as unbranded alternatives flood e-commerce platforms.
- Safety Balls:Anti-burst rated with reinforced seam construction for institutional liability protection. Compact description with named entity: German hospital procurement departments specify these for inpatient rehabilitation protocols.
- Massage Balls:High-density EVA or rubber compounds for myofascial release and trigger point therapy. Compact description with named entity: Compact diameter variants integrate into physical therapy toolkits across Japanese clinic networks.
Most installed capacity flows through Stability Balls. Expansion is steepest in Safety Balls.
Material:
Reformulation timelines and requalification costs segment suppliers by polymer compounding capabilities. Raw material sourcing strategies determine which manufacturers absorb ECHA restriction compliance without margin erosion.
- TPE:Thermoplastic elastomer compounds deliver phthalate-free performance with burst-resistant load ratings. European and North American markets absorb 18-24 month requalification cycles as REACH deadlines eliminate plasticizer alternatives. Premium positioning captures clinical-grade pricing.
- PVC:Conventional burst-resistant construction faces formulation pressure from chemical restrictions. Chinese manufacturers in Zhejiang province retain cost advantages for undifferentiated fitness segments, though export access to regulated markets narrows.
- Rubber:Natural and synthetic compounds for massage ball and specialty applications. Compact description with named entity: Latex-free certifications determine clinical suitability for allergy-sensitive physiotherapy environments.
- EVA:Ethylene-vinyl acetate foams for lightweight massage and recovery products. Compact description with named entity: Nordic corporate wellness programs specify recycled-content EVA for sustainability-weighted tenders.
TPE commands the steepest price premiums. PVC retains the largest production footprint.
Size:
Tooling investments scale with diameter, as mold cavity dimensions determine batch economics and inventory carrying costs. Diameter selection correlates directly with user anthropometrics and rehabilitation protocol specifications.
- 65 cm:Standard adult sizing dominates volume across fitness and clinical applications. United States and German markets standardize procurement around this diameter, with ISO 20957 load testing protocols calibrated to this specification. Inventory depth here determines distributor market access.
- 75 cm:Taller user demographics and specialized rehabilitation applications drive incremental demand. Compact description with named entity: Scandinavian workplace health programs specify these for ergonomic seating alternatives in technology sector headquarters.
- 55 cm:Compact diameter for shorter users and travel-oriented fitness equipment. Compact description with named entity: Japanese home fitness consumers prioritize storage efficiency in dense urban housing.
- 85 cm:Extended diameter for specialized balance training and athletic conditioning. Compact description with named entity: Professional sports team training facilities in Australia specify these for proprioceptive rehabilitation protocols.
65 cm absorbs the majority of mold capacity. 75 cm is climbing the fastest among diameter variants.
End User:
Channel economics diverge sharply between institutional procurement with extended payment terms and direct-to-consumer cash conversion. Customer type determines pricing power, certification requirements, and content bundling strategies.
- Physiotherapy Centers:Clinical-grade equipment with documented anti-burst ratings and latex-free certifications. German and United States reimbursement policies mandate specific safety ratings, pulling certified product volumes through therapist-controlled channels. Digital-physical bundling opportunities emerge as clinics prescribe home exercise protocols.
- Home Users:Price-sensitive demand through e-commerce and retail channels. Compact description with named entity: Chinese and Indian consumers drive volume growth as preventive healthcare awareness expands.
- Gyms:Commercial durability specifications with bulk procurement contracts. Compact description with named entity: United States franchise chains standardize equipment specifications across location networks.
- Fitness Coaches:Portable equipment for mobile training services and content creation. Compact description with named entity: Subscription workout platforms source branded equipment for influencer partnership programs.
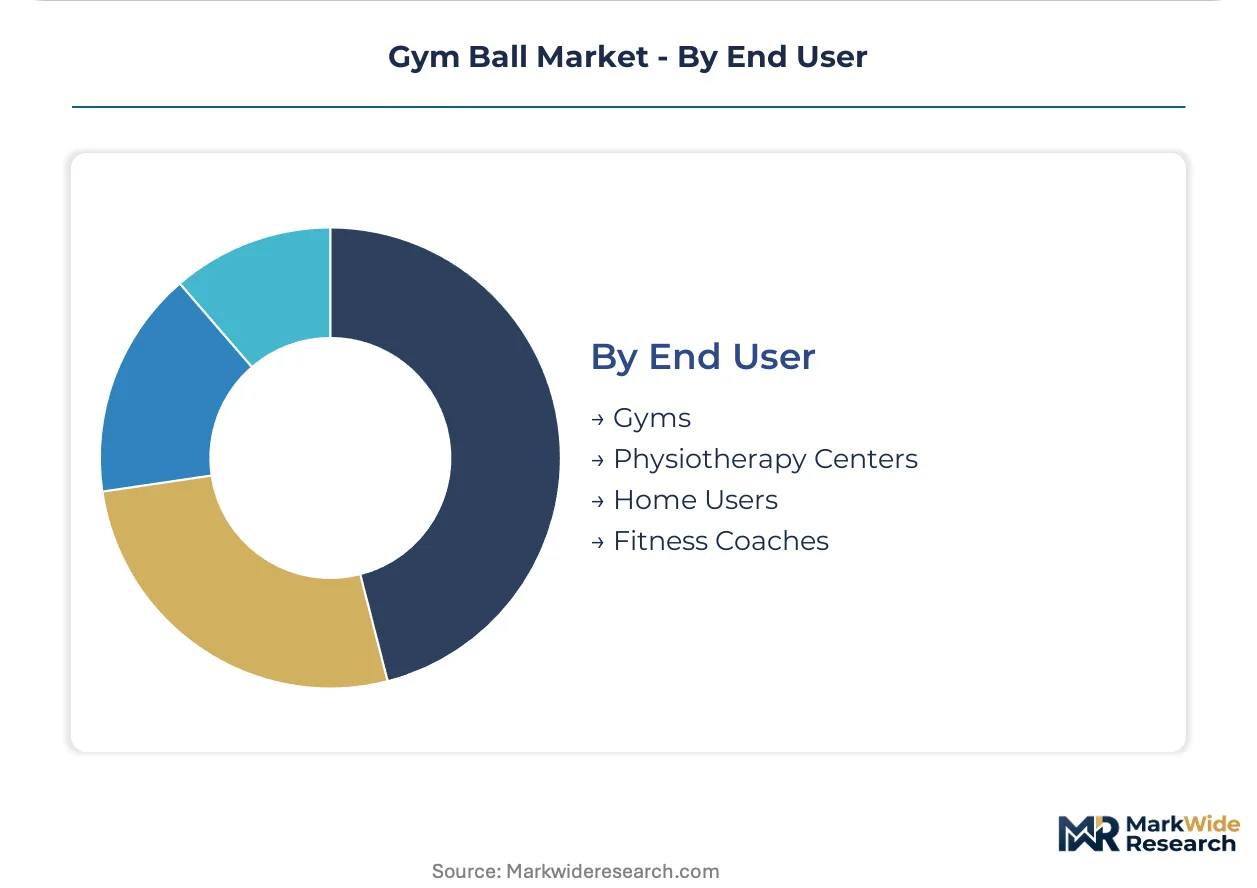
Physiotherapy Centers extract the highest per-unit margins. Home Users represent the largest addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration follows divergent compliance costs between regulated and unregulated markets. Chinese producers in Zhejiang province retain cost advantages for undifferentiated fitness equipment, while European and North American suppliers absorb REACH and FDA certification expenses to access premium clinical channels.
United States
Physiotherapy reimbursement policies mandate documented anti-burst ratings for equipment eligibility. FDA device classification guidance elevates testing protocols for institutional procurement. California's Proposition 65 chemical disclosure requirements add labeling complexity for cross-border sellers targeting the West Coast market.
Germany
Hospital rehabilitation departments specify ISO 20957 certified products for inpatient protocols. REACH Annex XVII restrictions on phthalate plasticizers accelerate TPE material substitution. Manufacturing clusters in North Rhine-Westphalia focus on polymer compounding capabilities for clinical-grade formulations.
China
Domestic preventive healthcare awareness drives home fitness equipment volume through e-commerce channels. GB standards for fitness equipment provide baseline safety benchmarks for local manufacturers. Production concentrates in Zhejiang and Guangdong provinces where burst-resistant PVC fabrication infrastructure is densest.
India
Ayushman Bharat insurance coverage expansion creates institutional demand for physiotherapy equipment. BIS certification requirements are formalizing for imported fitness devices. Domestic manufacturers in Maharashtra and Gujarat position to capture clinical volume as standards mature.
Japan
Compact diameter variants integrate into physical therapy toolkits across dense urban clinic networks. METI guidelines influence product safety expectations for home fitness equipment. Manufacturing in the Kanto region emphasizes high-density EVA compounds for myofascial release applications.
Gym Ball Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. Clinical-grade certification requirements concentrate premium positioning among suppliers with documented testing infrastructure, while undifferentiated fitness equipment faces margin compression from unbranded alternatives. Three archetypes dominate: content-integrated lifestyle brands, clinical-credibility specialists, and scale-driven OEM fabricators. Capacity expansion in TPE compounding and strategic partnerships with subscription workout platforms represent the dominant competitive moves.
Among North American branded specialists, GoFit exemplifies the content-integrated archetype through platform bundling strategies. TheraBand occupies a position within the clinical-credibility tier, leveraging therapist channel relationships. URBNFit represents the direct-to-consumer vector with specialized sizing differentiation. Chinese fabricators including YR Fitness and DHZ Fitness anchor the scale-driven OEM segment serving private-label and institutional contract volumes.
| Leading Market Players |
|---|
| GoFit |
| Vivora |
| Unisoul Inc. |
| DHZ Fitness |
| Galsports |
| Black Mountain Products |
| URBNFit |
| YR Fitness |
| TheraBand |
| Others |
Supply Flow & Price Mechanics
Crude oil derivative indices governing PVC and synthetic rubber feedstock costs cascade through three distinct pricing tiers in the gym ball market. Phthalate-free TPE compounds command clinical-grade premiums in German and United States physiotherapy channels, while undifferentiated PVC construction competes on landed cost from Zhejiang province fabricators. REACH compliance investments and anti-burst certification requirements stratify supplier margins more sharply than raw material differentials alone.
Pricing Analysis
Distributor markups spanning 35-50% separate institutional procurement channels from direct-to-consumer retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and material chemistry rather than brand equity alone. Price differentiation hinges on ISO 20957 load-testing documentation and latex-free material declarations. Cost compression in the standard tier intensifies as Chinese OEMs flood e-commerce platforms with unbranded alternatives. Home fitness consumers in India and China exhibit highest price sensitivity, while German hospital procurement departments prioritize liability-rated specifications over unit cost.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai to Rotterdam and Long Beach directly impacts landed cost competitiveness for European and North American distributors. Burst-resistant PVC fabrication concentrates in China's Zhejiang and Guangdong provinces, with secondary TPE compounding capacity emerging in Germany's North Rhine-Westphalia region. Raw material supply draws from petrochemical derivatives, specialized polymer additives, and anti-burst reinforcement fibers. Single-source vulnerability concentrates in Chinese production clusters exposed to geopolitical friction or port congestion. Distribution runs through physiotherapy equipment wholesalers, sporting goods retail chains, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in TPE material substitution and digital-physical bundling as cost-down drivers and premium-tier shifts converge. Phthalate-free formulation investments unlock clinical-grade pricing power while subscription content partnerships reduce customer acquisition costs.
For Market Incumbents: Anchor market position through backward integration into TPE compounding capabilities and therapist channel control. Resistance band substitution and unbranded Chinese OEMs threaten core volume in home fitness segments. Prioritize ISO 20957 certification maintenance and QR-linked digital content platforms to extend customer lifetime value beyond hardware transactions. For New Entrants and Emerging Players: The 40-60% price gap between premium clinical-grade and economy fitness-tier products creates white-space opportunity in mid-market TPE construction. Target Indian preventive healthcare expansion under Ayushman Bharat coverage as standards formalize. Pursue white-label partnerships with subscription workout platforms seeking differentiated hardware bundles for influencer marketing programs. For Investors and Strategic Acquirers: Asymmetric upside sits with European TPE compounders possessing REACH-compliant supply chains and documented anti-burst testing infrastructure. Long-term viability centers on clinical-channel penetration and sustainability credentialing for corporate wellness procurement. Monitor physiotherapy reimbursement policy shifts in Germany and the United States as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| TPE Material Compounding Investment | REACH Annex XVII compliance unlocks premium clinical-grade pricing in German and United States markets. |
| Digital Content Platform Partnership | Subscription workout bundling reduces churn and captures recurring revenue beyond hardware margins. |
| Anti-Burst Certification Infrastructure | ISO 20957 documentation determines reimbursement eligibility for German hospital procurement departments. |
| India Manufacturing Localization | BIS certification readiness positions capture institutional volume as Ayushman Bharat standards mature. |
| Recycled Content EVA Development | EU Green Deal procurement incentives weight circular material flows in municipal and hospital tenders. |
Methodological Framework
Multiple input streams — primary interviews with physiotherapy clinic directors, polymer compounding engineers, and sporting goods procurement managers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Regulatory filings from ECHA and FDA device classification guidance provided compliance timeline benchmarks. Trade customs data, fitness equipment distributor inventory records, and hospital GPO contract databases supplied volume and pricing calibration. Primary fieldwork encompassed 15 stakeholder categories across manufacturing, clinical, and retail channels.
Data-stream reconciliation across the projection horizon employed segment-level modeling by product type, material chemistry, diameter specification, and end-user channel. CAGRs were derived from installed base growth, replacement cycle analysis, and reimbursement policy elasticity. TPE substitution rates, anti-burst certification penetration, and digital bundling attach rates served as industry-specific forecast inputs throughout the modeling period.
The model assumes a particular technology adoption path; alternative pathways for phthalate-free polymer formulations would alter the outlook if REACH restrictions accelerate or relax. Forecasts reflect documented assumptions regarding physiotherapy reimbursement stability and petrochemical feedstock cost trajectories. A model refresh is warranted upon material change in EU chemical restriction timelines or FDA device reclassification decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
Yoga and Pilates Mats Market
Fitness Equipment
Ergometer Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Mexico Outdoor Fitness Equipment Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Exercise Bike Market