
 Aftershave Market | 2026-2036
Aftershave Market Size, Share, and Industry Trends Forecast 2026-2036
Aftershave Market Analysis
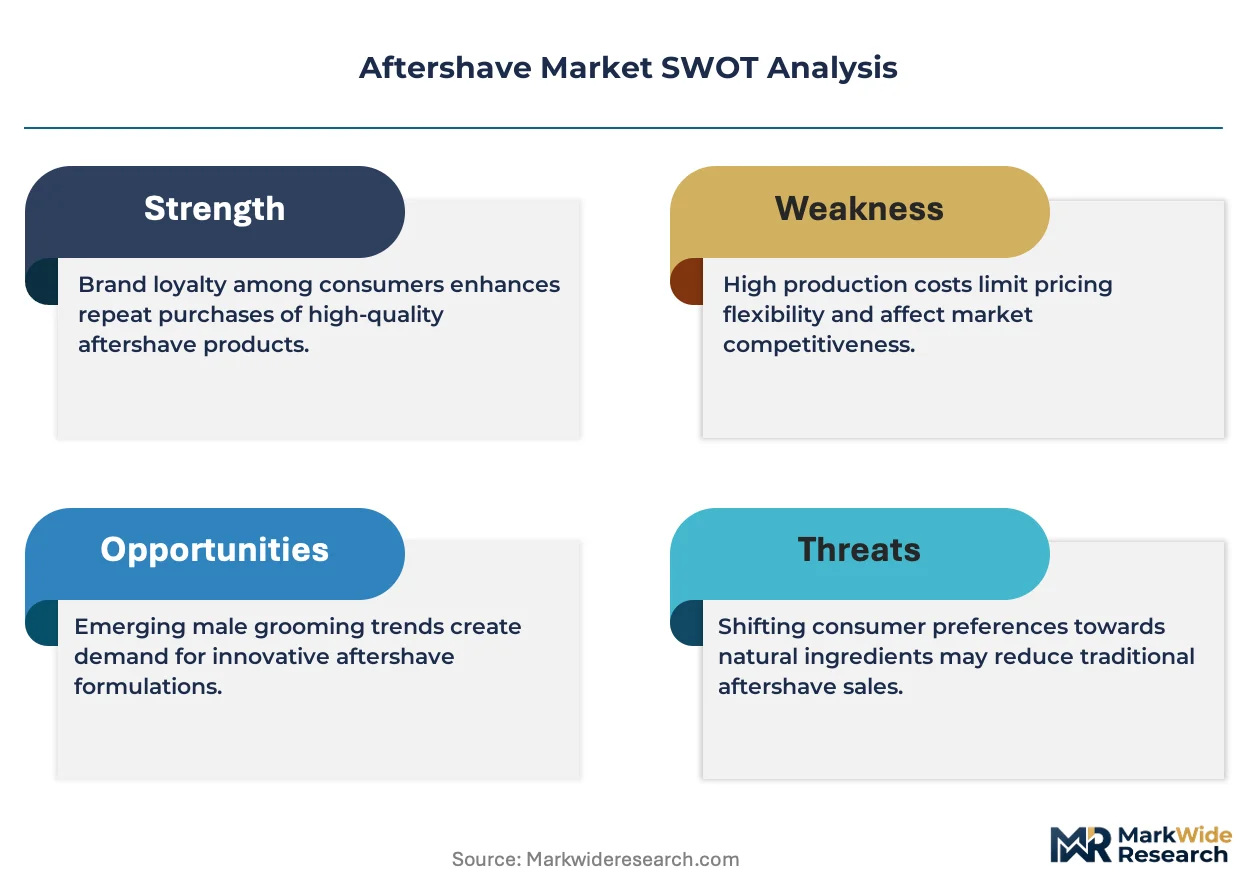
ISO 22716 certification for cosmetics Good Manufacturing Practice is unwinding competitive access for smaller formulators across the aftershave category. Procter & Gamble leverages captive fragrance compound capabilities to sustain cost discipline at scale. L'Oréal anchors its position through dedicated men's grooming R&D centers in Western Europe. Beiersdorf AG specializes in dermatologically tested balm formats that command shelf space in German pharmacy channels.
Aftershave denotes a post-shave cosmetic preparation containing astringent agents such as witch hazel or alcohol, emollients like glycerin or allantoin, and fragrance compounds, designed to disinfect micro-cuts, reduce inflammation, and restore skin pH after depilation. Balm formats now lead value contribution as consumers with sensitive skin trade up from alcohol-heavy lotions, while gel segments capture younger users through non-greasy, fast-absorbing textures. Online distribution channels are accelerating fastest, though supermarkets still dominate volume throughput in emerging markets where trial-and-repeat behavior favors physical inspection.
EU REACH restrictions on allergenic fragrance materials and FDA cosmetic labeling requirements in the United States are elevating compliance costs and forcing reformulation cycles across multinational portfolios. India's BIS standards for cosmetics safety are tightening import scrutiny, creating barriers for unregistered foreign brands. Stakeholders must monitor regulatory divergence between fragrance disclosure regimes and calibrate regional SKU strategies accordingly.
Market Dynamics
EU REACH restrictions on fragrance allergens are compressing formulation flexibility across the aftershave category, forcing manufacturers to rebuild compound libraries and recalibrate regional SKU portfolios.
Growth Catalysts
- Urban professional grooming depth:Post-pandemic return-to-office protocols in the United States and Germany are expanding daily aftershave use frequency among white-collar demographics.
- BIS import standardization:India's tightening cosmetics safety scrutiny is filtering out unregistered competitors, creating shelf space for compliant multinational entrants in pharmacy and modern trade channels.
- Alcohol-free emulsion chemistry:Advances in witch hazel and allantoin stabilization are enabling balm formats that satisfy sensitive-skin consumers previously excluded from alcohol-heavy traditional lotions.
Market Restraints
- Synthetic musk supply concentration:Three specialty chemical producers in Switzerland and Germany control bulk production of polycyclic musk substitutes, exposing formulators to input cost volatility.
- REACH compliance timeline friction:ECHA's extended fragrance allergen disclosure deadlines are stretching reformulation cycles to 18-24 months, freezing new product pipelines.
- Subscription box substitution:Curated grooming bundles are displacing standalone aftershave purchases among younger demographics in urban United States markets.
Strategic Opportunities
- Indian tier-two pharmacy penetration:Cities such as Pune and Jaipur remain underpenetrated by dermatologically tested balm formats, offering first-mover shelf space capture.
- ISO 16128 natural origin certification:The emerging natural and organic cosmetics standard creates premium positioning potential for plant-derived astringent formulations.
- Direct-to-consumer sampling integration:Micro-format trial units bundled with razor subscriptions are converting gel-curious users in German and United States metropolitan markets.
Industry Challenges
- Fragrance chemist talent scarcity:Formulation specialists capable of rebuilding compound libraries under REACH constraints command premium compensation in Western Europe.
- Multi-regulatory SKU proliferation:Divergent fragrance disclosure regimes between EU REACH and FDA labeling requirements are fragmenting production runs and elevating inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aftershave Market |
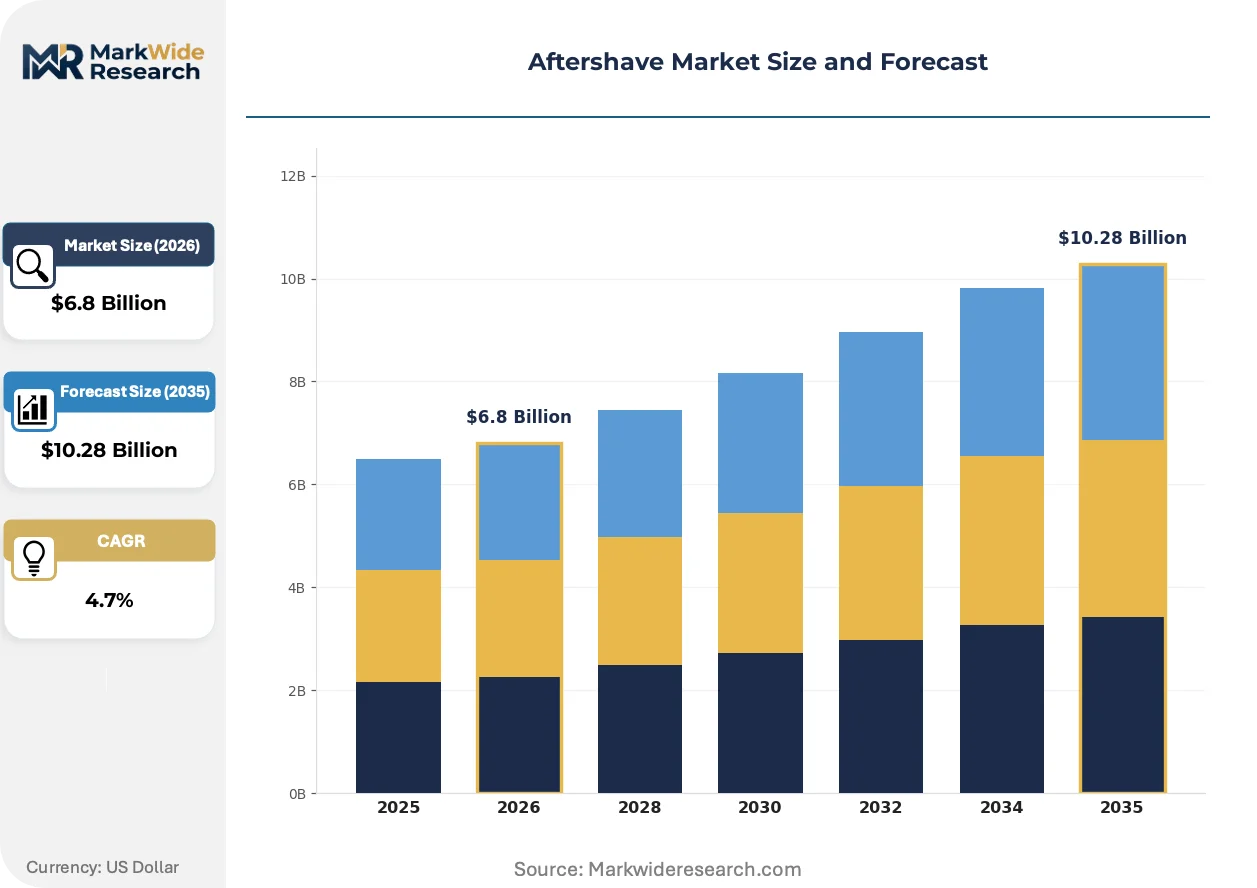
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balm, Lotion, Liquid, Gel Fragrance Type: Citrus, Woody, Spicy, Floral End User: Men, Women, Professionals, General Consumers Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Procter & Gamble, Unilever, L'Oréal, Beiersdorf AG, Estée Lauder Companies, Coty Inc., Shiseido Company, Colgate-Palmolive Company, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aftershave Market Emerging Trajectories
Reformulation chemistry, regulatory disclosure architecture, and distribution channel configuration are simultaneously restructuring how aftershave products reach and retain end users.
Microbiome-friendly preservation systems are fragmenting traditional alcohol-based sanitization approaches. These systems employ postbiotic ferments and mild organic acids to maintain skin flora balance. Sensitive-skin and dermatology-channel buyers in Germany and France are adopting them at accelerating rates. The technology is fragmenting the historical alcohol-versus-balm dichotomy, creating intermediate positioning for hybrid formats.
REACH Annex III fragrance allergen expansion is compressing permissible compound palettes for EU-market products. ECHA's 2023-2025 implementation schedule requires disclosure of over 80 additional substances at concentrations above 0.001% in leave-on cosmetics. Balm and splash formats with complex scent architectures face the steepest reformulation burden, with several German pharmacy brands accelerating simplified single-note alternatives.
Subscription bundling is displacing standalone aftershave purchasing among younger demographics. United States-based grooming boxes now routinely pair trial-format balms with razor cartridges, conditioning trial behavior outside traditional retail. Urban professionals aged 25-34 exhibit the highest conversion rates from bundled samples to full-size repurchase, compressing brand loyalty cycles and elevating packaging differentiation priorities.
Aftershave Market Segmentation
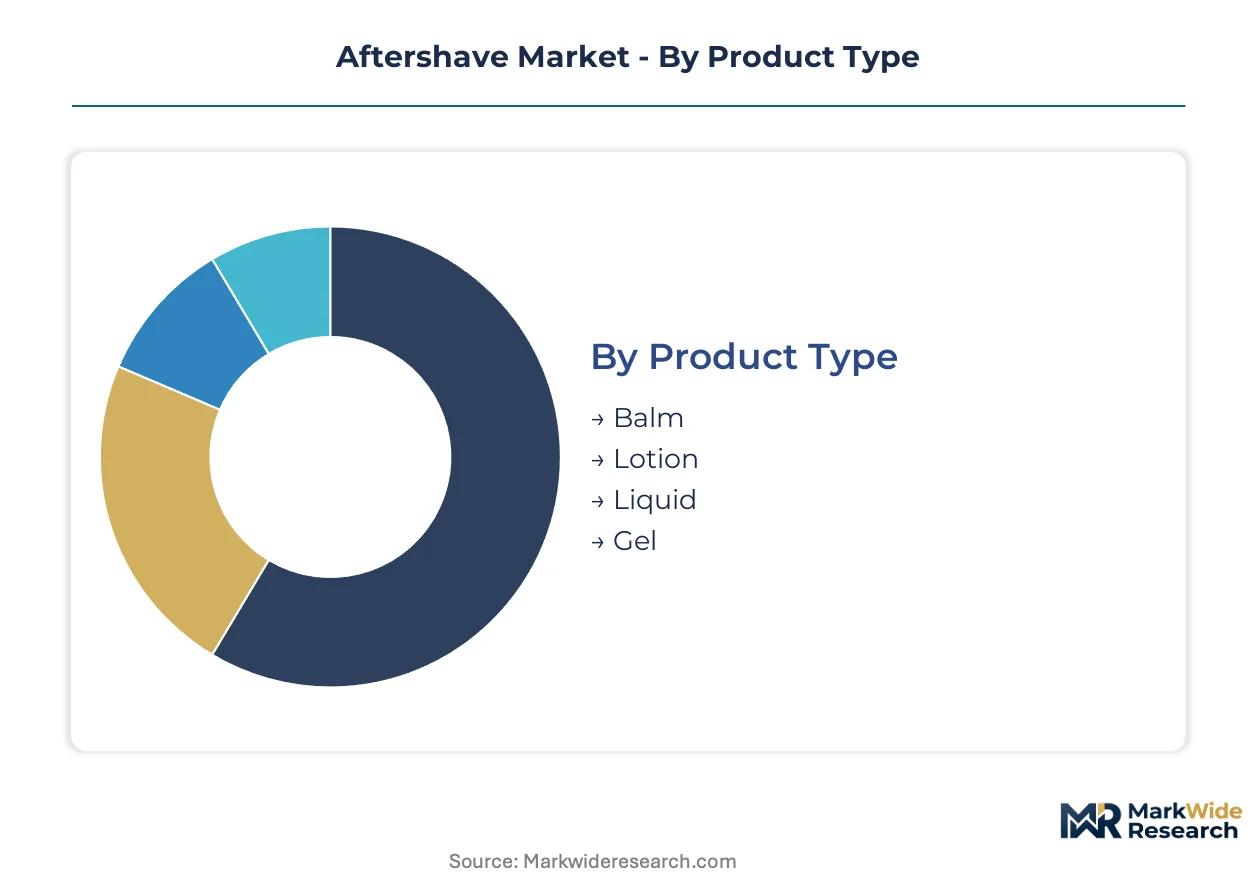
Aftershave segmentation reveals how formulation chemistry, sensory preferences, and channel economics partition demand across distinct user cohorts. Manufacturers calibrate SKU portfolios across these dimensions to capture premium positioning while managing regulatory complexity in multiple jurisdictions.
Product Type:
Balm and gel formulations concentrate in export-led markets with stringent dermatological standards, while lotion and liquid variants dominate domestic consumption in price-sensitive regions.
- Balm:Emulsion-based formats employing witch hazel and allantoin stabilization replace alcohol-heavy alternatives for sensitive-skin users. Demand concentrates in German pharmacy channels and United States dermatology clinics, driven by EU REACH compliance timelines that favor simplified, low-allergen formulations.
- Gel:Fast-absorbing, non-greasy textures capture younger demographics through convenience-oriented use occasions. United States metropolitan markets and Indian tier-one cities show strongest uptake, propelled by subscription box bundling with razor cartridges.
- Lotion:Traditional alcohol-based preparations retain volume leadership in emerging markets where price sensitivity outweighs formulation sophistication.
- Liquid:Splash formats with complex scent architectures face reformulation pressure under expanded fragrance allergen disclosure requirements.
Balm holds the largest share; momentum sits with gel.
Fragrance Type:
Cost tier stratification runs deepest in this category, with single-note formulations commanding manufacturing efficiency advantages over complex compound architectures.
- Citrus:Fresh, volatile top-note profiles dominate mass-market production due to lower raw material costs and simpler REACH compliance pathways. United States and German retail channels favor these formulations for their broad demographic acceptance.
- Woody:Sandalwood and cedar-based accords anchor premium positioning in Indian urban markets, where domestic sandalwood oil supplies confer cost advantages to local formulators.
- Spicy:Clove, nutmeg, and pepper notes concentrate in seasonal gifting assortments across European markets.
- Floral:Rose and lavender infusions capture women-oriented product lines in specialty retail channels.
Citrus generates highest volume throughput; woody accords climb the fastest on value per unit.
End User:
Application context determines frequency and format preferences, with professional use occasions demanding portable, quick-dry solutions distinct from at-home grooming rituals.
- Men:Core demographic driving category innovation, with demand fragmenting across age cohorts between alcohol-based tradition and balm-format skin health positioning.
- Women:Growing segment attracted to unisex fragrance profiles and skin-soothing formulations previously marketed exclusively to male users.
- Professionals:White-collar return-to-office protocols in United States and German cities expand daily use frequency, favoring travel-size formats and subtle scent profiles.
- General Consumers:Price-sensitive mass market concentrated in supermarket and convenience store channels across emerging economies.
Men retain dominant volume share; professionals exhibit steepest expansion trajectory.
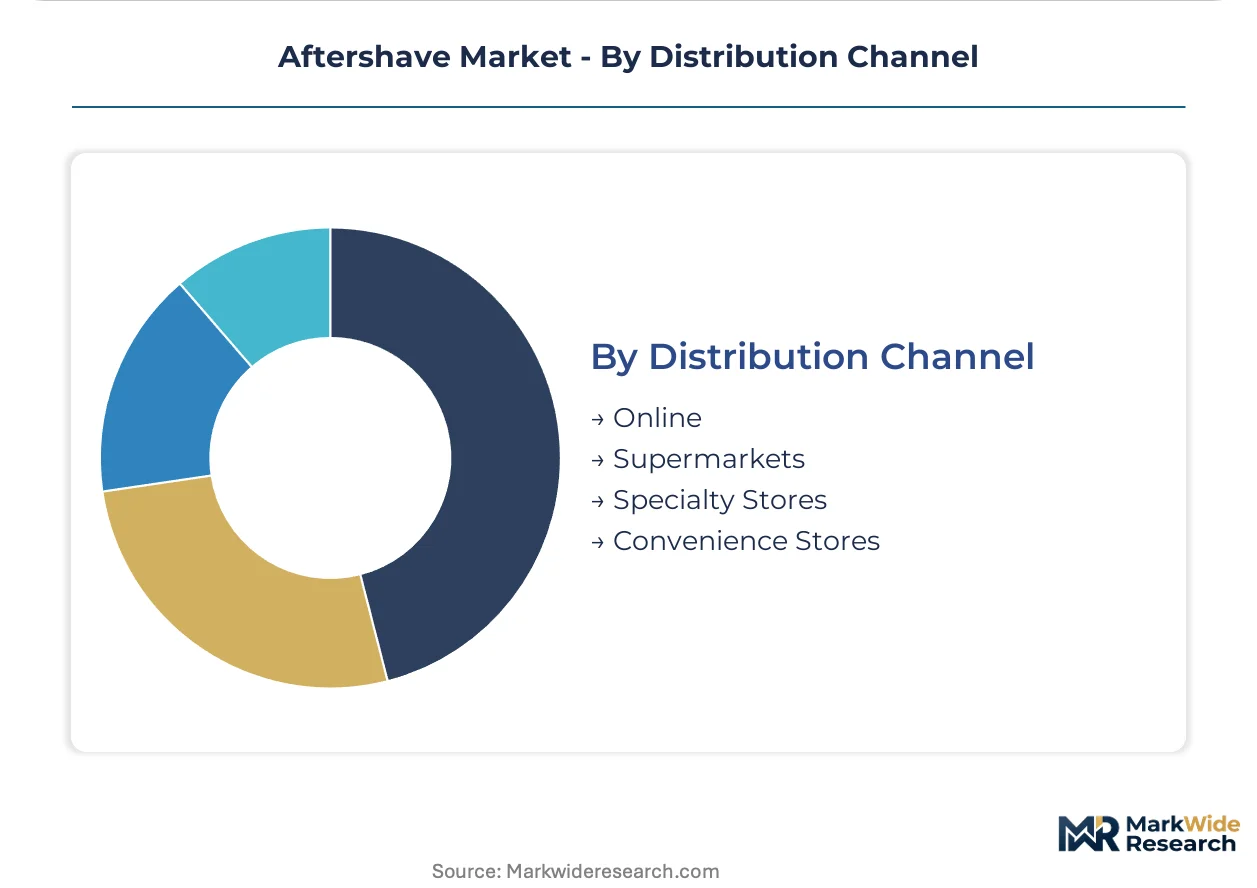
Distribution Channel:
Customer type and purchase behavior diverge sharply by channel, with trial-oriented users favoring physical inspection while replenishment buyers migrate to digital platforms.
- Online:Direct-to-consumer and marketplace platforms accelerate fastest in United States and German metropolitan areas, supported by micro-format sampling integration with subscription services.
- Supermarkets:Volume throughput remains dominant in India and other emerging markets where brand discovery depends on shelf visibility and promotional pricing.
- Specialty Stores:Pharmacy and beauty retail channels in Germany and France concentrate premium balm sales, leveraging dermatological endorsement and trained staff consultation.
- Convenience Stores:Impulse-driven purchases of travel-size formats capture urban commuter traffic in dense metropolitan zones.
Supermarkets maintain widest reach; online channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH fragrance allergen disclosure deadlines are restructuring formulation priorities across export-oriented manufacturing hubs. Fiscal incentives for domestic cosmetics production in India and Brazil are accelerating local capacity buildouts. Urban professional grooming intensity varies sharply by metropolitan density and return-to-office policy stringency.
United States
Return-to-office mandates in Manhattan and Chicago financial districts are expanding daily aftershave use frequency among white-collar professionals. FDA cosmetic labeling requirements are elevating compliance costs for imported fragrance compounds. Brooklyn and Austin clusters host emerging direct-to-consumer brands leveraging subscription bundling with razor cartridges.
Germany
Dermatologically tested balm formats command premium shelf positioning in Munich and Hamburg pharmacy channels. ECHA's extended REACH implementation timeline is stretching reformulation cycles to eighteen months. Cologne and Düsseldorf industrial zones concentrate captive fragrance compound production for integrated personal care manufacturers.
India
BIS cosmetics safety standardization is filtering out unregistered foreign competitors from Mumbai and Bangalore modern trade channels. The PLI scheme for domestic manufacturing is incentivizing local formulation facilities. Pune and Jaipur tier-two pharmacy networks remain underpenetrated by compliant multinational balm entrants.
Japan
Metropolitan Tokyo professional grooming rituals sustain demand for subtle, fast-absorbing gel formats. METI guidance on sustainable packaging is pressuring imported brand portfolios. Osaka and Nagoya industrial corridors concentrate precision fragrance compounding for sensitive-skin product lines.
Brazil
São Paulo urban consumer trial behavior favors supermarket brand discovery over digital channels. ANVISA cosmetics registration requirements are extending market entry timelines for unregistered imports. Rio de Janeiro and Belo Horizonte distribution networks prioritize volume-oriented lotion formats in price-sensitive retail segments.
Aftershave Market Vendor Landscape
Player mix skews toward integrated consumer goods conglomerates with captive fragrance capabilities and dedicated men's grooming divisions. Mid-tier specialists compete through dermatological certification and pharmacy channel access. Three strategic archetypes dominate: scale-driven multinationals with compound libraries, pharmacy-channel specialists with clinical positioning, and direct-to-consumer challengers with subscription integration. Competitive moves center on REACH-compliant reformulation acceleration and micro-format sampling bundled with adjacent grooming products.
Among scale-driven conglomerates, Procter & Gamble and L'Oréal occupy positions anchored by captive supply chains and dedicated men's grooming R&D infrastructure. Beiersdorf AG exemplifies the pharmacy-channel specialist archetype through dermatologically tested formats. These three entities represent distinct competitive vectors: integrated compound manufacturing, clinical endorsement leverage, and format innovation for sensitive-skin segments.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| L'Oréal |
| Beiersdorf AG |
| Estée Lauder Companies |
| Coty Inc. |
| Shiseido Company |
| Colgate-Palmolive Company |
| Kao Corporation |
| Others |
Supply Flow & Price Mechanics
Captive fragrance compound manufacturing at Procter & Gamble and L'Oréal generates scale economies that compress unit costs for alcohol-based lotions while elevating price floors for REACH-compliant balm formulations. Capacity utilization across Swiss and German polycyclic musk facilities directly determines input cost volatility for mid-tier formulators.
Pricing Analysis
Certification level creates the primary spread, with ISO 22716-compliant dermatological formats commanding premium positioning in German pharmacy channels against standard-grade supermarket lotions. Three-tier pricing structure separates premium balm, standard gel, and economy liquid segments. Cost compression in alcohol-heavy formulations is intensifying as polycyclic musk substitutes face supply bottlenecks. Mass-market Indian consumers exhibit highest price sensitivity; United States professionals in Manhattan and Chicago financial districts show lowest.
Supply Chain Analysis
Inventory lead times for polycyclic musk substitutes now stretch eighteen to twenty-four months as ECHA disclosure deadlines compress reformulation windows. Supply concentrates in Switzerland, Germany, and India for fragrance compounds, witch hazel extracts, and allantoin stabilization chemistry respectively. Formulation draws from alcohol denaturants, emulsifier systems, and preservative packages. Single-source vulnerability in Swiss-German musk production exposes cost volatility. Distribution runs through pharmacy channels in Germany, subscription bundling in the United States, and modern trade in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragrance chemist talent capable of rebuilding compound libraries under REACH constraints has become the scarcest capability in Western Europe, constraining reformulation velocity for multinational portfolios.
For Market Incumbents: Fortify captive supply positions in polycyclic musk alternatives through backward integration into Swiss-German specialty chemical partnerships. Accelerate ISO 16128 natural origin certification pipelines to preempt premium positioning erosion from clean beauty entrants. Threat substitution from microbiome-friendly preservation systems demands R&D redeployment toward postbiotic ferments. For New Entrants and Emerging Players: Differentiate on dermatologically tested balm formats for Indian tier-two pharmacy networks in Pune and Jaipur, where compliant multinational presence remains thin. Target subscription box bundling partnerships with razor cartridge providers in German and United States metropolitan markets. Go-to-market angle: micro-format trial units converting gel-curious users through direct-to-consumer sampling integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with subscription bundling infrastructure. Long-term viability over the next decade hinges on regulatory compliance agility rather than scale alone. Acquisition target archetype: mid-tier pharmacy-channel specialists with ISO 22716 certification and established German dermatology endorsements. Signal to watch: ECHA acceleration or delay of fragrance allergen disclosure deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Acceleration | ECHA disclosure deadlines force eighteen-month compound library rebuilds for EU market retention. |
| Micro-Format Sampling Integration | Trial units bundled with razor subscriptions convert gel-curious users in German metropolitan markets. |
| Indian Tier-Two Pharmacy Penetration | Pune and Jaipur networks remain underpenetrated by compliant multinational balm entrants. |
| ISO 16128 Natural Origin Certification | Plant-derived astringent formulations capture premium positioning in sensitive-skin segments. |
| Captive Fragrance Compound Manufacturing | In-house production of polycyclic musk substitutes insulates against Swiss-German supply volatility. |
Methodological Framework
A standing panel of fragrance chemists, pharmacy category managers, regulatory affairs specialists, and subscription box curators provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA regulatory filings, BIS cosmetics safety notifications, FDA cosmetic labeling guidance, Nielsen retail audit data, and customs import records. Bottom-up volume modeling triangulated against top-down expenditure benchmarks.
Consistency checks against external regulatory timelines and disclosed reformulation cycles validated output ranges across the projection horizon. Segmentation dimensions included product format, fragrance architecture, end-user application context, and distribution channel configuration. CAGRs were derived from fitted growth curves applied to calibrated base-year estimates, with inputs from urban professional grooming frequency surveys and REACH compliance cost disclosures.
Material uncertainties — ECHA deadline revisions, BIS enforcement intensity shifts, polycyclic musk supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and consumer format migration patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
North America Bath and Shower Products Market
Beauty & Personal Care
Eyelash Curler Market
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Makeup Brushes Market