
 Digital Coupons Market | 2026-2036
Digital Coupons Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Coupons Market Analysis
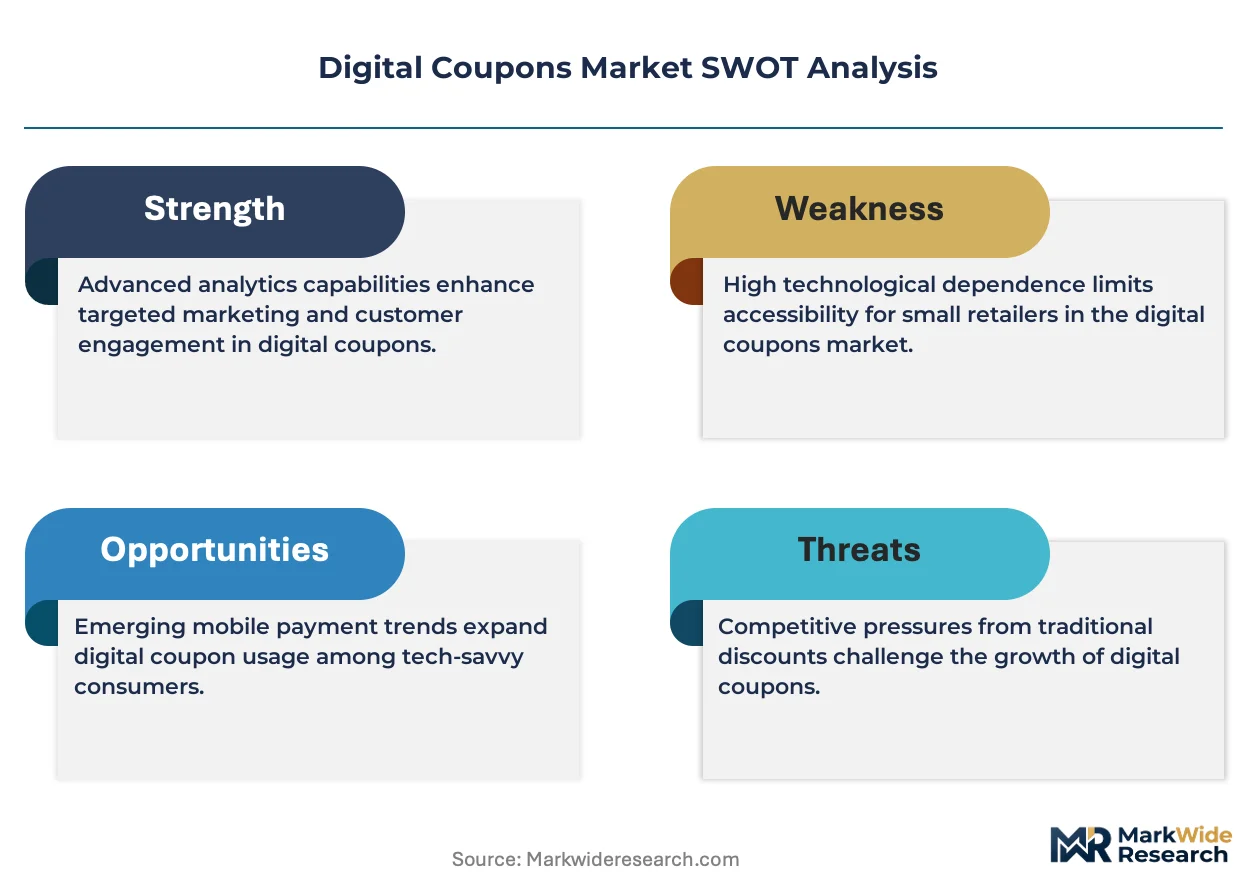
North America's digital coupon infrastructure is reshaping how brands connect with price-sensitive shoppers. Rakuten leverages its cashback model to sustain cross-border merchant partnerships across the Pacific. Honey Science Corporation anchors browser-based automatic coupon application, competing directly with Capital One Shopping's bank-integrated savings tools. RetailMeNot differentiates through publisher network scale, dominating affiliate-driven coupon distribution.
Digital coupons are machine-readable promotional codes delivered through software interfaces, typically encoded as alphanumeric strings or QR matrices redeemable at point-of-sale terminals or checkout gateways. Their primary commercial purpose is to lower customer acquisition costs while capturing first-party transaction data for merchant analytics. Cashback mechanisms now lead value transfer structures, while mobile apps represent the fastest-growing distribution channel as smartphone penetration deepens. Loyalty rewards integration captures the highest-margin engagement pools by binding repeat purchase behavior to identity-verified accounts.
The Federal Trade Commission monitors promotional transparency and data collection practices in the United States, while the EU Digital Services Act imposes algorithmic accountability on platform-delivered discounts. California's Consumer Privacy Act constrains how retailers may personalize coupon offers based on behavioral profiles. Stakeholders must monitor evolving state-level privacy legislation and platform gatekeeper designations to preserve targeting precision without triggering compliance penalties.
Market Dynamics
The EU Digital Services Act is forcing platform operators to restructure algorithmic discount delivery, while grocery retailers accelerate mobile-first coupon infrastructure to capture first-party transaction data and reduce customer acquisition costs.
Growth Catalysts
- EU Digital Services Act compliance:Platform operators are redesigning promotional targeting systems to meet algorithmic accountability requirements, creating standardized infrastructure for coupon distribution.
- Mobile wallet integration:Smartphone penetration is deepening across retail banking apps, embedding cashback mechanisms directly into payment flows at point-of-sale terminals.
- Grocery retail digitization:Supermarket chains are deploying QR matrix redemption systems to drive foot traffic and expand basket size through personalized offers.
Market Restraints
- California Consumer Privacy Act constraints:Behavioral profiling limitations restrict how retailers personalize coupon offers based on purchase history, compressing targeting precision.
- Platform gatekeeper concentration:Dependence on dominant mobile operating systems creates single-point vulnerability for coupon distribution channel access.
- First-party data infrastructure costs:Identity-verified account systems require substantial investment in loyalty rewards integration and fraud prevention layers.
Strategic Opportunities
- Browser-based automatic application:Extension tools that scan merchant checkout gateways for valid codes represent underpenetrated white space in desktop commerce.
- Cross-border merchant partnerships:Cashback models that span Pacific corridor economies enable arbitrage on regional price differentials.
- Affiliate network scale expansion:Publisher-driven coupon distribution channels offer lower customer acquisition costs than platform-dependent models.
Industry Challenges
- State-level privacy fragmentation:Retailers must maintain parallel compliance systems for California's Consumer Privacy Act and emerging legislation in Virginia, Colorado, and Connecticut.
- Legacy point-of-sale integration:Older terminal hardware at mid-tier merchants requires software bridge development to support QR matrix redemption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Coupons Market |
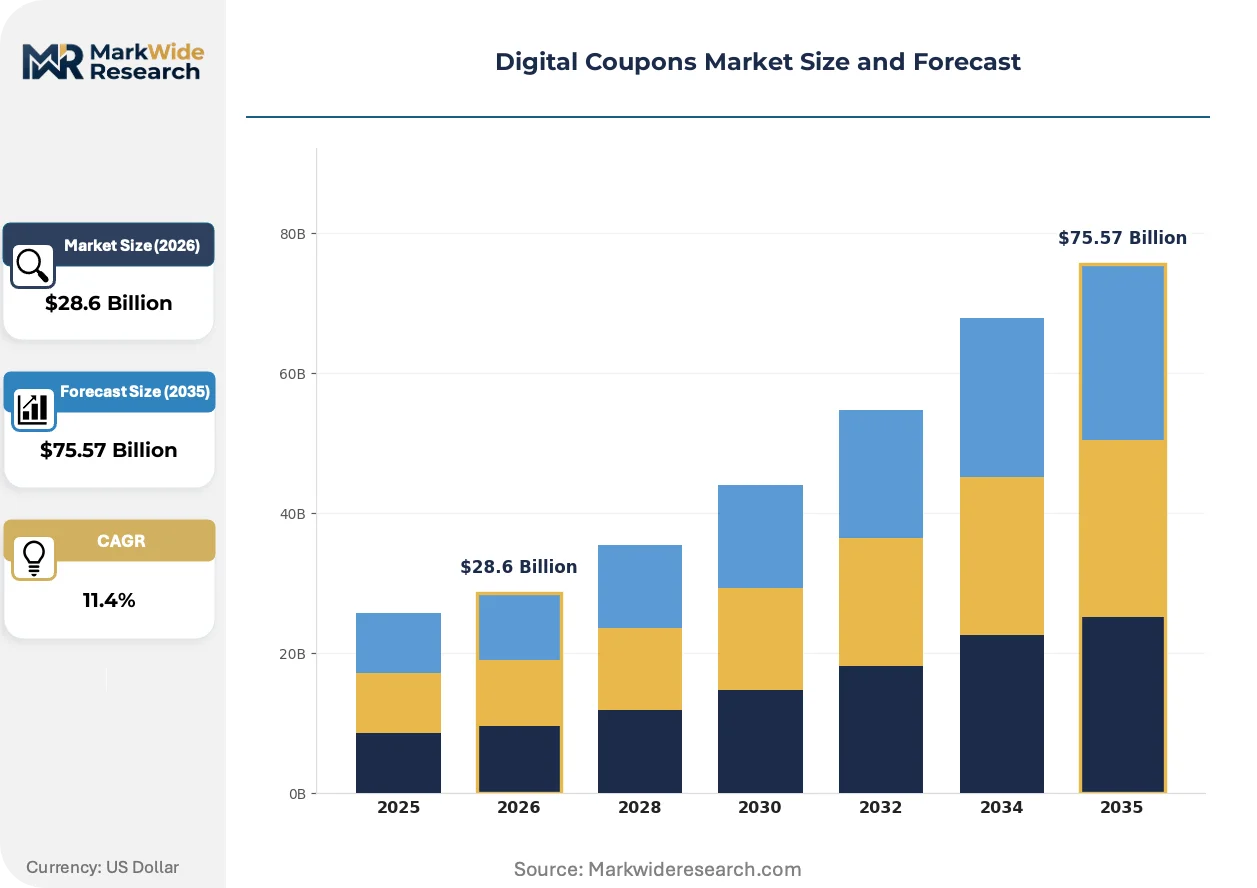
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cashback, Percentage Discount, Buy One Get One, Loyalty Rewards Distribution Channel: Mobile Apps, Email, Social Media, Retail Websites End User: Retailers, Consumers, Brands, E-commerce Platforms Application: Online Shopping, In-Store Purchases, Promotions, Seasonal Sales |
| Companies Covered | Honey Science Corporation, Snipp, Rakuten, Coupons.com, Fetch Rewards, Capital One Shopping, RetailMeNot, Slickdeals, Groupon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Coupons Market Emerging Trajectories
Machine-readable promotional encoding is replacing manual code entry, while regulatory pressure on algorithmic transparency is reshaping how platforms deliver personalized discounts to price-sensitive shoppers.
AI-powered predictive targeting engines analyze transaction velocity patterns to surface context-relevant offers before checkout initiation. Major grocery retailers are deploying these systems across their mobile app ecosystems. Browser-based automatic coupon application is rendering obsolete the manual search-and-test redemption model that dominated desktop commerce.
The EU Digital Services Act imposes documentation requirements on algorithmic systems that rank or recommend promotional content to users. Platform operators must now maintain audit trails for discount targeting decisions. Mid-sized affiliate networks face compliance cost compression as they adapt infrastructure to meet these accountability standards.
Price-sensitive shoppers are consolidating coupon discovery into bank-integrated savings tools rather than standalone applications. This behavior shift redirects traffic away from publisher networks toward financial institution ecosystems. The United States exhibits the clearest manifestation of this consolidation, where mobile-first couponing infrastructure binds repeat purchase behavior to identity-verified accounts.
Digital Coupons Market Segmentation
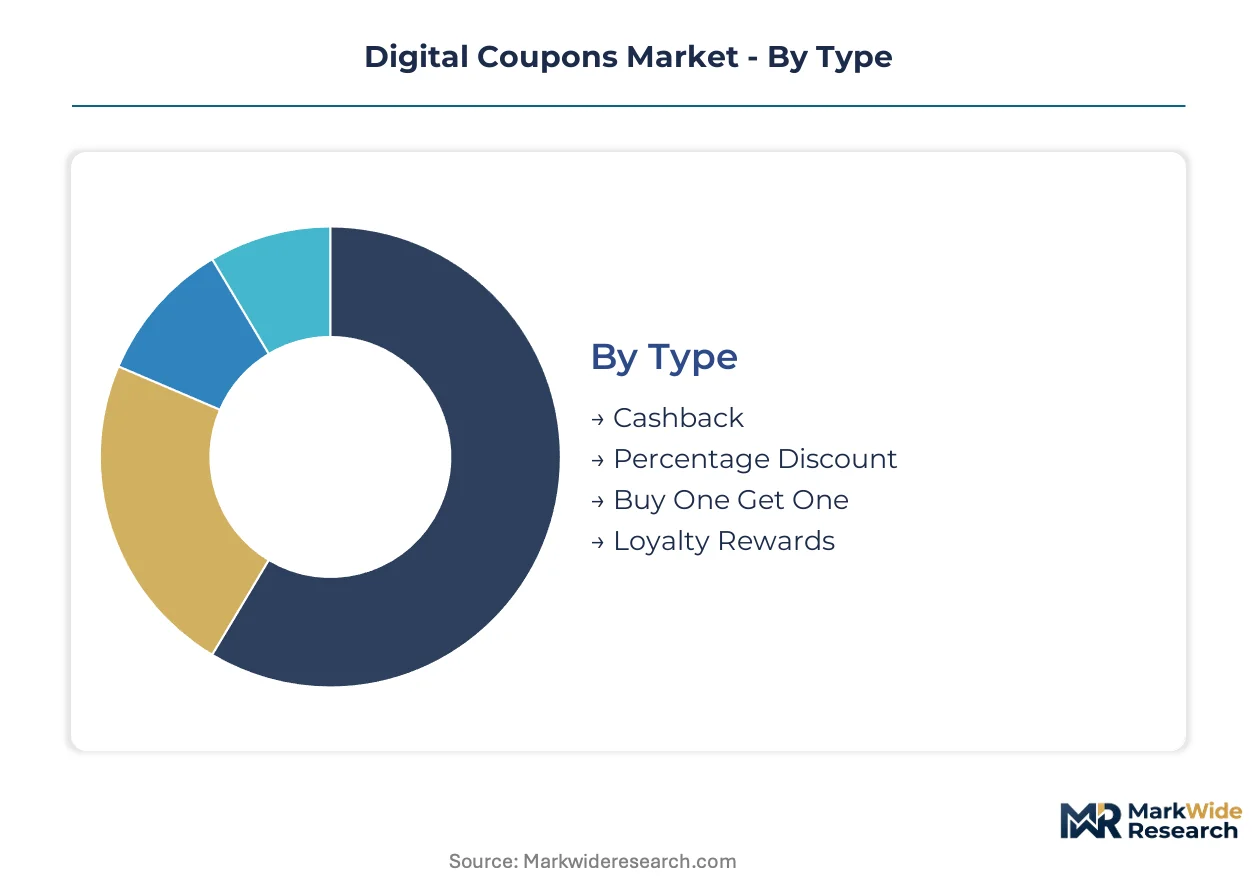
Digital coupon segmentation reveals how value transfer mechanisms and distribution infrastructure determine merchant acquisition economics. Understanding these dimensions exposes where first-party data capture and redemption friction intersect.
Type:
Mature promotional formats now compete with emerging value structures as retailers optimize for transaction data yield versus immediate conversion lift.
- Cashback:Post-transaction value rebates deposited into linked financial accounts or digital wallets. Demand concentrates among grocery retailers and bank-integrated savings tools in the United States, driven by consumer preference for tangible monetary returns over percentage abstractions.
- Percentage Discount:Proportional price reductions applied at checkout, typically ranging from single digits to half-off thresholds. Supermarket chains and mid-tier e-commerce platforms deploy these for inventory velocity acceleration, constrained by margin compression on low-consideration purchases.
- Buy One Get One:Unit-multiplication offers that inflate basket volume without direct price perception erosion. CPG brands favor this structure for trial generation and shelf-space defense.
- Loyalty Rewards:Points-based accumulation systems requiring identity-verified account binding. Highest-margin engagement pools for repeat purchase behavior, demanding substantial fraud prevention infrastructure investment.
Cashback retains volume leadership; loyalty rewards holds the steepest expansion curve.
Distribution Channel:
Cost tier differentiation separates capital-intensive proprietary infrastructure from lower-friction third-party platforms.
- Mobile Apps:Native smartphone applications with embedded wallet integration and geofenced offer triggering. United States retailers lead deployment, capitalizing on deep smartphone penetration and NFC-enabled point-of-sale terminals.
- Email:Direct-to-inbox promotional code delivery with tracking pixel attribution. Mature channel facing deliverability compression from inbox algorithmic filtering and privacy-preserving email clients.
- Social Media:Platform-embedded discount surfacing through feed algorithms and influencer affiliate structures. EU Digital Services Act compliance costs are reshaping targeting precision capabilities.
- Retail Websites:Merchant-owned digital properties with session-based personalized offer injection. Grocery chains prioritize this channel for first-party data sovereignty.
Mobile apps command the largest addressable audience; social media faces the sharpest regulatory headwinds.
End User:
Customer type fragmentation mirrors divergent technical capabilities and data sophistication levels across the value chain.
- Retailers:Brick-and-mortar and omnichannel merchants deploying coupons for foot traffic generation and basket size expansion. United States supermarket chains lead QR matrix redemption system investment.
- Consumers:Individual price-sensitive shoppers consolidating discovery into bank-integrated tools rather than standalone applications.
- Brands:CPG manufacturers using digital coupons for trial conversion and competitive positioning against private label encroachment.
- E-commerce Platforms:Marketplace operators balancing merchant promotional autonomy with platform-wide discount governance and algorithmic transparency requirements.
Retailers absorb the highest infrastructure investment burden; e-commerce platforms navigate the most complex regulatory compliance matrices.
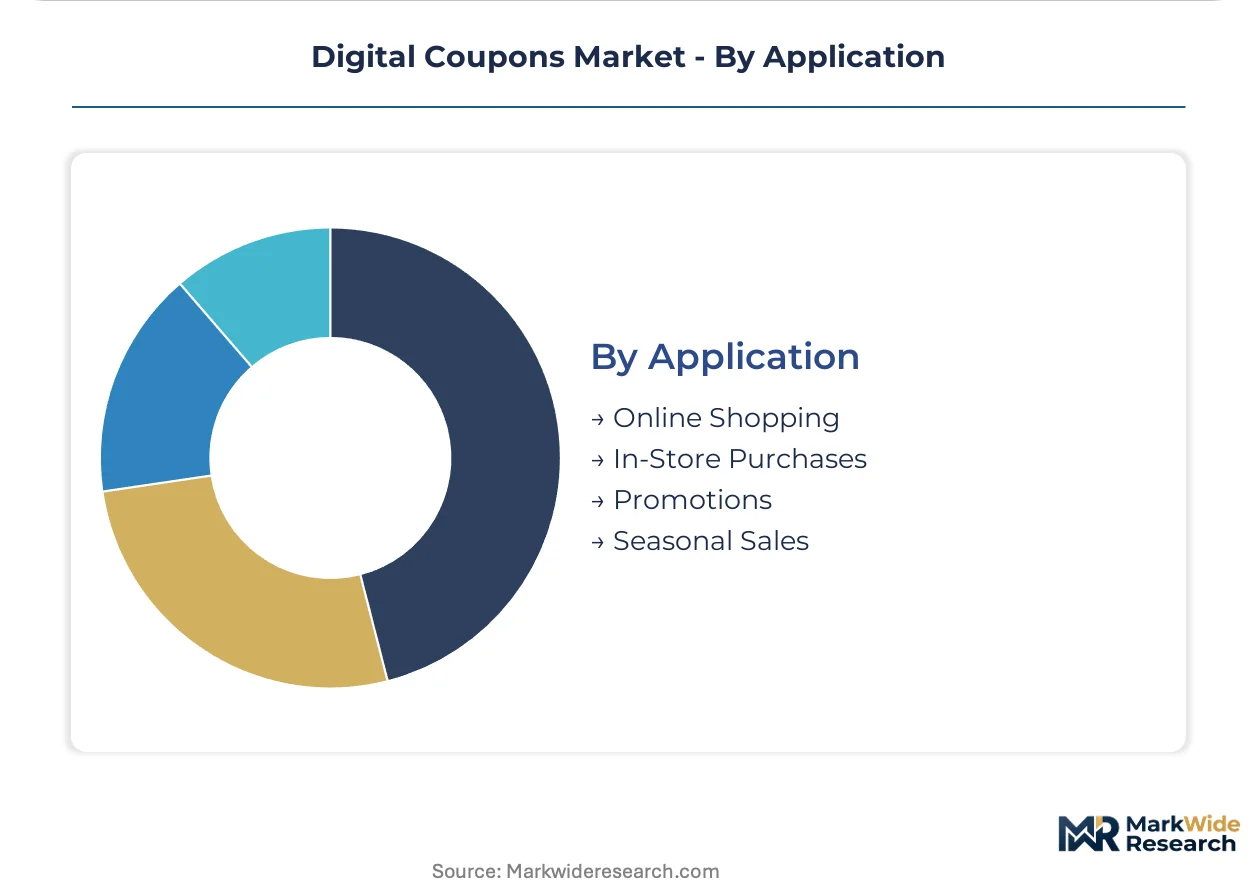
Application:
Volume concentration shifts between fulfillment modalities as legacy point-of-sale hardware upgrade cycles accelerate.
- Online Shopping:Browser-based and app-native checkout redemption with automatic code application. Honey Science Corporation and Capital One Shopping anchor this modality through extension-based infrastructure.
- In-Store Purchases:Physical retail redemption via QR matrix scanning or NFC tap-to-apply. Grocery retailers drive adoption, constrained by legacy terminal hardware at mid-tier merchants requiring software bridge development.
- Promotions:Event-triggered campaigns tied to inventory clearance or competitive response timelines.
- Seasonal Sales:Calendar-anchored discounting clusters around retail holidays and fiscal quarter-end velocity targets.
Online shopping maintains transaction volume dominance; in-store purchases are climbing the fastest as mobile wallet penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States shoppers favor bank-integrated cashback tools, while European users encounter algorithmic targeting restrictions under platform governance rules. Asian markets concentrate coupon discovery within super-app ecosystems rather than standalone applications.
United States
Mobile wallet penetration and NFC-enabled terminals drive QR matrix redemption at grocery chains. The FTC monitors promotional transparency and data collection practices, constraining behavioral profiling for personalized offers. California's Consumer Privacy Act compresses targeting precision, forcing retailers to maintain parallel compliance systems across state lines.
Germany
Retail banking apps embed savings tools directly into payment flows, displacing standalone coupon discovery. The EU Digital Services Act imposes algorithmic accountability on platform-delivered discounts, requiring audit trails for targeting decisions. Berlin and Munich anchor fintech-wallet partnerships that consolidate promotional content into identity-verified accounts.
United Kingdom
Publisher networks dominate affiliate-driven coupon distribution, competing with browser-based automatic application tools. The Information Commissioner's Office enforces GDPR constraints on behavioral profiling for promotional targeting. London's financial services cluster drives bank-integrated cashback model adoption among price-sensitive shoppers.
Japan
Super-app ecosystems concentrate coupon discovery within LINE and PayPay payment flows, reducing standalone application usage. METI guidelines on platform governance shape how merchants deploy algorithmic discount delivery. Tokyo and Osaka anchor mobile-first infrastructure investment by convenience store chains seeking foot traffic generation.
India
UPI-linked cashback mechanisms dominate value transfer structures as smartphone penetration deepens across tier-2 cities. RBI regulations on payment aggregator licensing constrain how foreign platforms deploy promotional wallet integrations. Bangalore and Mumbai anchor fintech-startup activity in browser-based automatic coupon application for e-commerce checkout.
Digital Coupons Market Vendor Landscape
Capability concentration sits with browser-extension specialists; scale advantage sits with bank-integrated platforms and affiliate networks. The market structures around three tiers: automatic application tools, cashback-anchored ecosystems, and publisher-driven distribution channels. Dominant competitive moves include mobile wallet integration partnerships and cross-border merchant network expansion.
Among browser-extension specialists, Honey Science Corporation and Capital One Shopping occupy positions defined by checkout-gateway integration. Rakuten exemplifies the cashback-anchored archetype through cross-border merchant partnerships spanning Pacific corridor economies. RetailMeNot sits within the publisher-network tier, where affiliate-driven distribution channels capture lower customer acquisition costs than platform-dependent models.
| Leading Market Players |
|---|
| Honey Science Corporation |
| Snipp |
| Rakuten |
| Coupons.com |
| Fetch Rewards |
| Capital One Shopping |
| RetailMeNot |
| Slickdeals |
| Groupon |
| Others |
Supply Flow & Price Mechanics
San Francisco's fintech corridor anchors the algorithmic infrastructure that powers cashback mechanism deployment, with its capacity concentration translating directly into pricing leverage over mid-tier affiliate networks seeking redemption technology access. Platform operators in this cluster extract premium licensing fees from retailers desperate for first-party data capture capabilities, while grocery chains absorb margin compression to secure mobile wallet integration.
Pricing Analysis
United States-European price spreads widen as California's Consumer Privacy Act compliance costs inflate domestic deployment expenses against algorithmically constrained European markets. Three-tier pricing structure across enterprise-grade API access, mid-market SaaS licensing, and self-serve browser extension tiers dominates, with certification level and volume scale driving differentiation. Pricing pressure stems from bank-integrated savings tools consolidating consumer discovery into single-platform ecosystems. Small and mid-tier affiliate networks exhibit acute price sensitivity; enterprise retailers with captive loyalty programs demonstrate inelastic demand.
Supply Chain Analysis
Upstream feedstock for digital coupon infrastructure draws from cloud computing capacity concentrated in the United States, Ireland, and Singapore, with API gateway services and fraud prevention algorithms as critical component inputs. Machine learning training data and identity verification systems represent specialized dependencies. Single-source vulnerability concentrates in dominant mobile operating system gatekeepers controlling distribution channel access. Distribution runs through direct enterprise sales teams for large retailers and self-serve marketplaces for mid-tier merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated sharply as grocery retailers and financial institutions merge coupon discovery into unified mobile wallet ecosystems, fragmenting standalone application providers into price-takers.
For Market Incumbents: Harden algorithmic accountability documentation to preempt EU Digital Services Act audit failures. Deepen mobile wallet integration partnerships with NFC-enabled terminal manufacturers to lock in redemption infrastructure control. Defensive patent accumulation around automatic coupon application technology blocks browser-extension challengers. For New Entrants and Emerging Players: Southeast Asian tier-2 cities present underpenetrated white space where UPI-equivalent payment systems lack embedded savings tools. Browser-based automatic application for desktop e-commerce checkout retains unclaimed share against mobile-first consolidation. White-label API licensing to regional retail banking apps offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a data-utility play because first-party transaction profiles become irreplaceable inputs for merchant analytics as third-party cookies deprecate. Acquisition targets should display identity-verified account scale above loyalty program thresholds. The signal to watch is grocery retailer consolidation into fewer mobile app ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Wallet Integration Partnership | NFC terminal manufacturers like Ingenico and Verifone control redemption infrastructure access for grocery chains. |
| Algorithmic Accountability Infrastructure | EU Digital Services Act audit trail systems preserve targeting precision for platform-delivered discounts. |
| Cross-Border Merchant Network Expansion | Rakuten's Pacific corridor model enables arbitrage on regional price differentials for cashback mechanisms. |
| Browser Extension Technology Acquisition | Honey Science Corporation's checkout-gateway integration anchors automatic code application market share. |
| First-Party Data Sovereignty Investment | Retail website personalization systems capture transaction data outside platform gatekeeper ecosystems. |
Methodological Framework
A standing panel of mobile product executives at grocery retailers, loyalty program directors at financial institutions, platform engineering leads at coupon aggregators, and affiliate network publishers provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against SEC filings of publicly traded fintech platforms, App Annie mobile engagement metrics, FTC promotional transparency enforcement records, and EU Digital Services Act implementation guidance. Bottom-up transaction volume estimates triangulated against top-down advertising spend allocation models.
Scenario-bracketing framed projections across regulatory stringency variations and mobile wallet penetration trajectories. Segmentation dimensions modeled include value transfer mechanism, distribution channel, end-user archetype, and redemption modality across the projection horizon. CAGRs derived from historical velocity patterns adjusted for platform gatekeeper policy shifts and state-level privacy legislation diffusion. Forecast inputs incorporated NFC terminal deployment schedules and smartphone replacement cycles.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by dominant mobile operating systems would shift outcomes substantially. Cross-checking against merchant acquiring processor transaction disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
Agricultural E-Commerce Market
E-Commerce Solutions
ASEAN E-Commerce Logistics Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
Singapore E-Commerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Belgium E-Commerce Market