
 Agricultural E-Commerce Market | 2026-2036
Agricultural E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural E-Commerce Market Analysis
Biodegradable packaging polymers are replacing conventional plastics in agricultural input shipments, and this shift is recalibrating last-mile delivery economics for perishable goods. Alibaba Group leverages its Cainiao logistics arm to control cold-chain infrastructure across Southeast Asian growing regions. JD.com anchors its rural expansion through drone delivery networks reaching township-level distribution points. Pinduoduo competes by aggregating smallholder orders into volume-based procurement pools that compress fertilizer pricing.
Agricultural e-commerce encompasses digital platforms facilitating the transaction of farm inputs, machinery, and fresh produce through online interfaces, typically integrating inventory management systems with GPS-tracked logistics modules and payment gateways optimized for rural connectivity. These platforms serve primary commercial purposes by collapsing intermediary layers between manufacturers and end-users while embedding credit scoring algorithms that unlock working capital for seasonal purchasing. Equipment and fertilizer categories within product type segmentation capture the dominant share of transaction value, reflecting high-ticket capital expenditure cycles tied to planting calendars. Subscription models under service type represent the fastest-expanding revenue stream as platforms bundle agronomic advisory with recurring input deliveries to lock in annual grower commitments.
The US Department of Agriculture and India's Food Safety and Standards Authority shape platform compliance through traceability mandates and pesticide residue disclosure rules that determine market access eligibility. China's Ministry of Agriculture and Rural Affairs enforces data localization requirements for agritech platforms handling farmer financial records, creating operational friction for cross-border operators. Stakeholders must weigh regulatory fragmentation against the margin compression inherent in pure marketplace models as they allocate capital between proprietary logistics and third-party fulfillment partnerships.
Market Dynamics
The agricultural e-commerce market is being fundamentally restructured by cooperative purchasing aggregation, which collapses traditional distributor margins by consolidating thousands of smallholder orders into single procurement events that manufacturers cannot ignore.
Growth Catalysts
- India's PLI scheme for digital infrastructure:The production-linked incentive accelerates rural broadband penetration, enabling real-time platform access for agritech procurement in previously disconnected districts.
- Biodegradable packaging polymers:These materials reduce cold-chain spoilage rates for perishable agricultural inputs, expanding the addressable product range beyond durable goods into temperature-sensitive biologicals.
- Brazil's Mato Grosso soybean belt:Cooperative purchasing through digital marketplaces in this concentrated production region demonstrates input cost compression that neighboring growing areas now seek to replicate.
Market Restraints
- Data localization mandates:China's Ministry of Agriculture and Rural Affairs requires domestic server storage for farmer financial records, creating operational friction for cross-border platform operators seeking unified technology stacks.
- Rural last-mile infrastructure gaps:Township-level distribution points in Southeast Asian growing regions lack reliable cold-chain continuity, limiting perishable input penetration regardless of platform sophistication.
- Intermediary resistance:Established agrochemical distributors in the US Corn Belt leverage existing credit relationships to delay grower migration toward direct manufacturer platforms.
Strategic Opportunities
- Drone delivery network saturation:Township-level distribution in rural China remains underpenetrated by autonomous logistics, creating first-mover advantages for platforms that achieve regulatory clearance from the FAA and CAAC simultaneously.
- Subscription agronomy bundling:Recurring input delivery combined with precision advisory services locks in annual grower commitments, converting transactional marketplaces into predictable revenue engines.
- EU Green Deal traceability requirements:Upcoming pesticide residue disclosure mandates will favor platforms with embedded compliance documentation, disadvantaging informal procurement channels.
Industry Challenges
- Legacy ERP integration complexity:Manufacturer inventory management systems require costly API development to synchronize with platform order flows, delaying onboarding timelines for mid-tier suppliers.
- Agronomic data science talent scarcity:Platforms struggle to hire sufficient precision agriculture specialists to validate the advisory content bundled with subscription services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural E-Commerce Market |
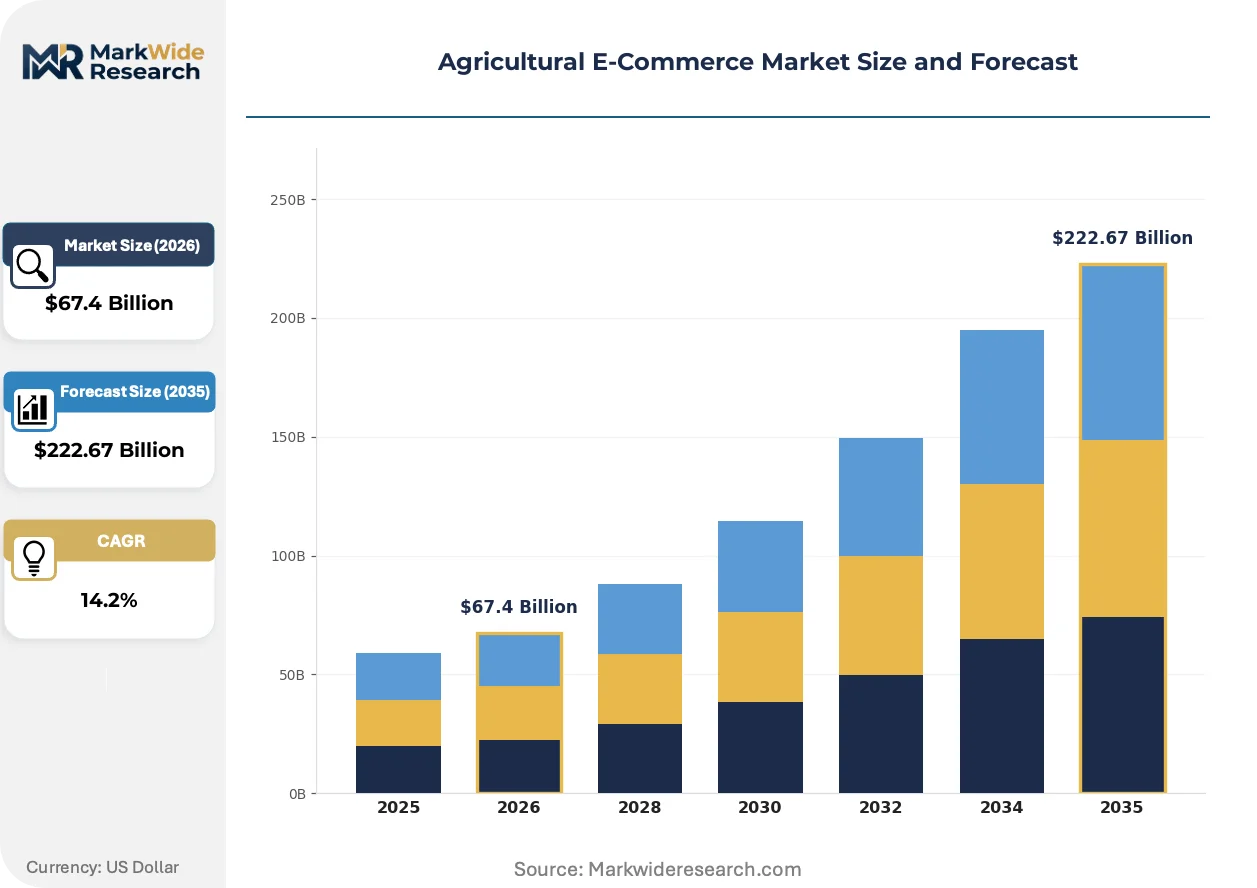
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $222.67 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeds, Fertilizers, Pesticides, Equipment Distribution Channel: Online Retail, Direct Sales, Marketplaces, Wholesale Customer Type: Farmers, Agricultural Cooperatives, Retailers, Distributors Service Type: Delivery Services, Subscription Models, Consulting, Financing |
| Companies Covered | Alibaba Group, Amazon.com, JD.com, Walmart Inc., Farmers Business Network, Pinduoduo, IndiaMART InterMESH, Tractor Supply Company, ProducePay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural E-Commerce Market Emerging Trajectories
Digital procurement interfaces are actively displacing phone-and-fax ordering systems across agricultural input distribution, compressing decision cycles from weeks to hours while embedding predictive analytics that anticipate seasonal demand spikes.
Blockchain-enabled provenance tracking is rewriting trust architectures in specialty crop input sourcing. California Central Valley almond and pistachio growers now demand immutable seed-to-spray documentation for export compliance. Platforms that deploy distributed ledger verification capture premium positioning in high-value crop segments where traceability commands price premiums.
The EU's CSRD sustainability disclosure requirements are forcing agricultural input manufacturers to quantify scope-three emissions from distributor networks. Platforms serving European growers must now embed carbon accounting modules that calculate fertilizer production footprints. German and Dutch cooperative purchasing groups are selecting marketplace partners based on ESG data granularity rather than price alone.
Aggregated smallholder purchasing is consolidating bargaining power in India's fragmented farm sector. Pinduoduo's volume-pooling model demonstrates that ten thousand marginal growers negotiating as a single bloc extract manufacturer concessions previously reserved for industrial-scale operations. This behavioral shift is most visible in Bihar and Uttar Pradesh, where fertilizer price compression through collective digital procurement now exceeds fifteen percent against individual spot purchases.
Agricultural E-Commerce Market Segmentation
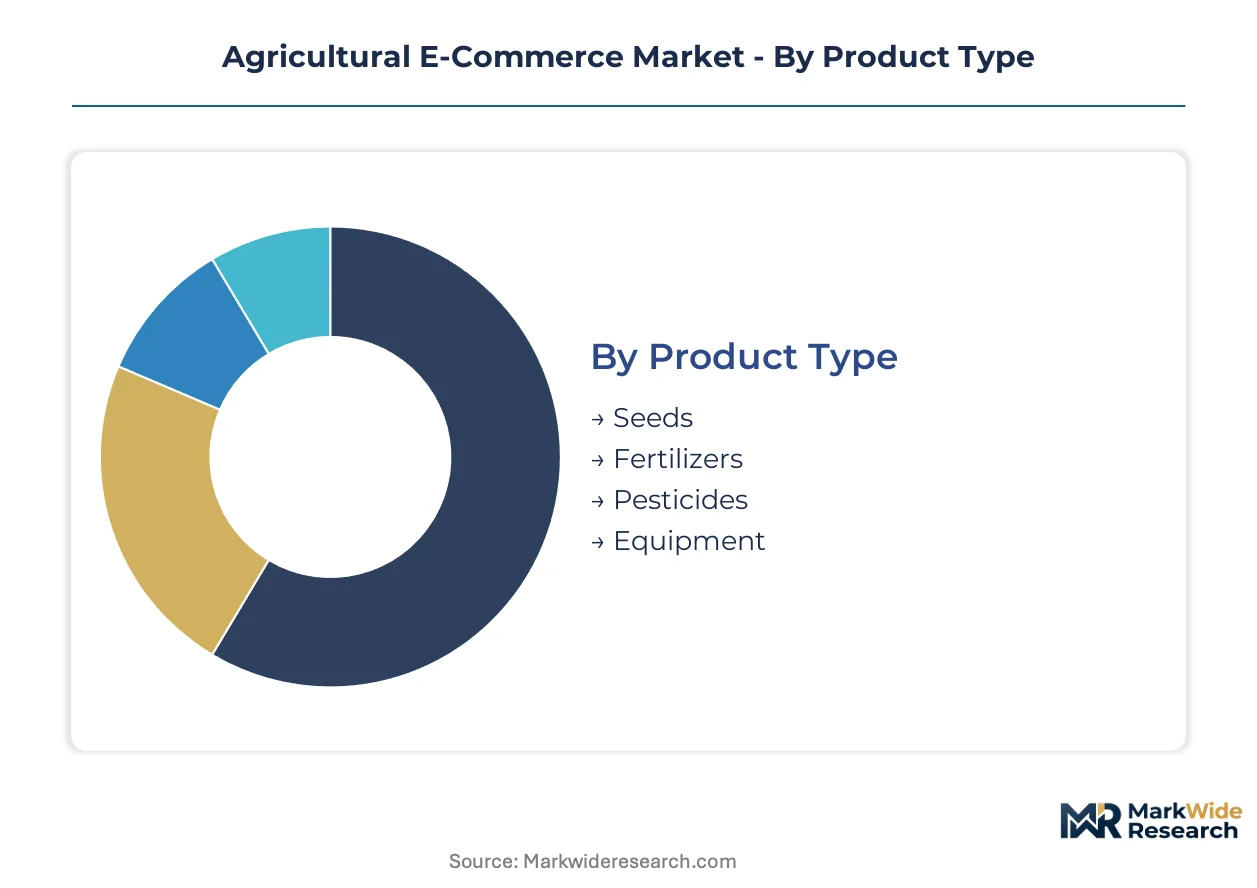
Agricultural e-commerce platforms must align product categories with distinct regulatory pathways and logistics requirements. Segmentation reveals where certification burdens concentrate and which customer interfaces demand specialized fulfillment infrastructure.
Product Type:
Equipment and Fertilizers carry the heaviest compliance obligations under EPA and state-level pesticide regulatory frameworks, while Seeds face phytosanitary certification requirements that vary by destination state.
- Equipment:Precision irrigation systems and GPS-enabled machinery dominate transaction values. California Central Valley specialty crop growers source these through platforms like Farmers Business Network, drawn by streamlined logistics and manufacturer-direct pricing that collapses traditional dealer margins.
- Fertilizers:Nitrogen-based and specialty blends require temperature-controlled storage and residue documentation under EU Green Deal traceability mandates. Demand concentrates in Brazil's Mato Grosso soybean belt, where cooperative purchasing through digital marketplaces reduces input costs through volume aggregation.
- Seeds:Genetically modified and heirloom varieties demand phytosanitary certificates and germination testing documentation.
- Pesticides:Restricted-use chemicals require applicator license verification and EPA-compliant labeling at point of sale.
Equipment sits at the top of the volume ranking, with Fertilizers climbing the fastest as cooperative purchasing models expand beyond Brazil into neighboring South American growing regions.
Distribution Channel:
Cost tier differentiation separates premium full-service platforms from economy-oriented aggregator models, with margin structure determining technology investment capacity.
- Marketplaces:Alibaba Group and JD.com anchor multi-vendor platforms integrating payment gateways with logistics arms. These capture the dominant share of transaction value by collapsing intermediary layers between manufacturers and end-users across Southeast Asian and Chinese growing regions.
- Direct Sales:Manufacturer-owned platforms embed credit scoring algorithms that unlock working capital for seasonal purchasing. Pinduoduo competes by aggregating smallholder orders into volume-based procurement pools that compress fertilizer pricing in India's Bihar and Uttar Pradesh states.
- Online Retail:Curated catalogs with standardized fulfillment serve mid-tier growers seeking convenience over customization.
- Wholesale:Bulk procurement interfaces target agricultural cooperatives with minimum order thresholds and extended payment terms.
Marketplaces command the highest transaction volumes, with Direct Sales gaining share fastest as manufacturers invest in proprietary platform development to capture margin previously allocated to distributors.
Customer Type:
Application complexity varies sharply across customer segments, with cooperatives demanding API integration for inventory synchronization while individual farmers prioritize mobile-optimized interfaces.
- Agricultural Cooperatives:Consolidated purchasing entities in Brazil's Mato Grosso and India's cooperative networks negotiate manufacturer concessions previously reserved for industrial-scale operations. These customers require ERP integration and aggregated billing systems that platforms struggle to deploy without costly custom development.
- Farmers:Smallholder aggregation through digital interfaces now exceeds fifteen percent price compression against individual spot purchases in fragmented farm sectors. India's PLI scheme for digital infrastructure accelerates rural broadband penetration, enabling real-time platform access in previously disconnected districts.
- Distributors:Legacy agrochemical distributors in the US Corn Belt leverage existing credit relationships to delay grower migration toward direct manufacturer platforms.
- Retailers:Brick-and-mortar input suppliers adopt white-label platform solutions to maintain customer relationships against pure-play digital entrants.
Farmers generate the highest order frequency, with Agricultural Cooperatives expanding most quickly as collective bargaining models demonstrate input cost compression that neighboring growing areas seek to replicate.
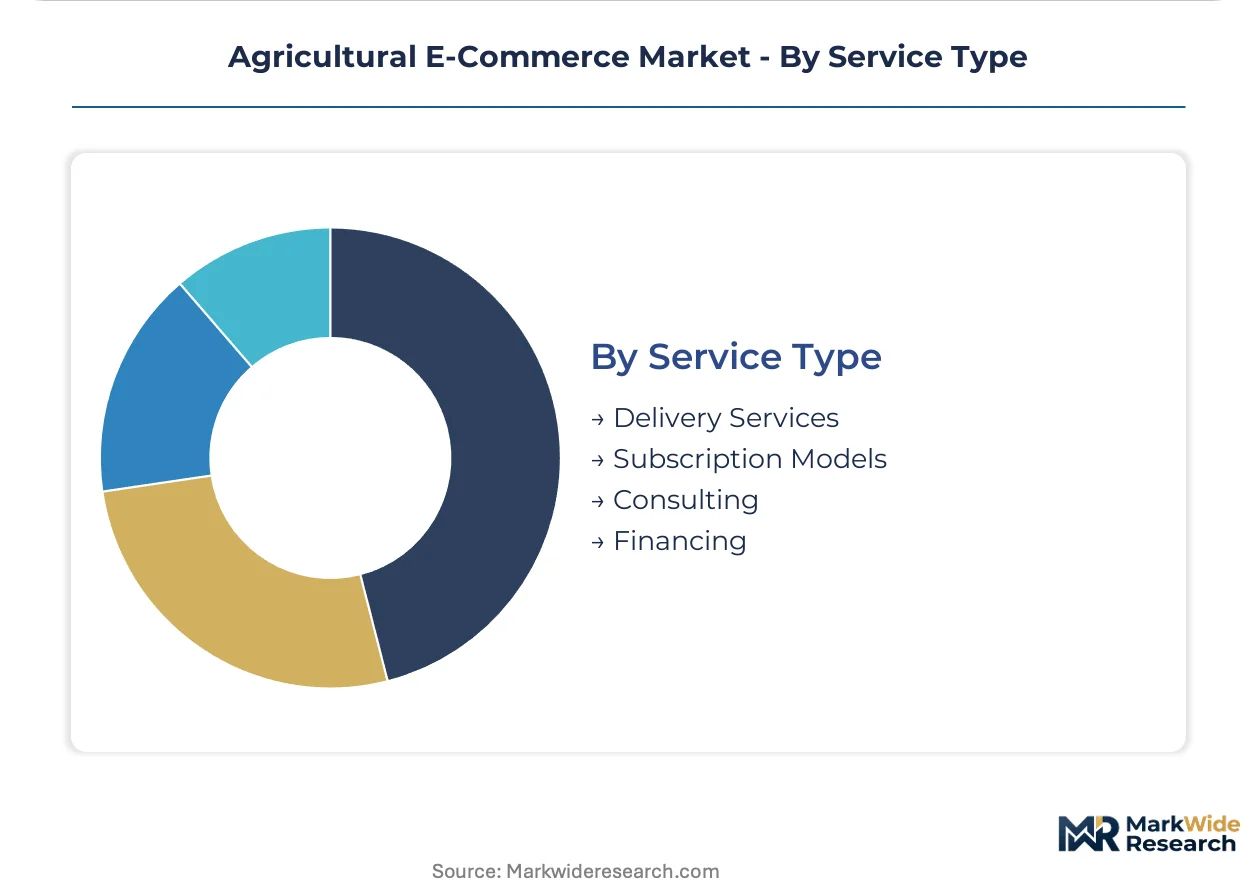
Service Type:
Maturity stage separates established logistics services from emerging advisory bundles, with revenue predictability driving platform investment priorities.
- Subscription Models:Recurring input delivery combined with precision advisory services locks in annual grower commitments. Platforms bundle agronomic advisory with seasonal input deliveries, converting transactional marketplaces into predictable revenue engines despite talent scarcity in precision agriculture data science.
- Delivery Services:JD.com anchors rural expansion through drone delivery networks reaching township-level distribution points. Biodegradable packaging polymers reduce cold-chain spoilage rates for perishable agricultural inputs, expanding the addressable product range beyond durable goods.
- Consulting:Precision agriculture advisory requires validated agronomic content that platforms struggle to staff sufficiently.
- Financing:Embedded credit scoring algorithms unlock working capital for seasonal purchasing, particularly in markets with limited traditional banking infrastructure.
Delivery Services account for the highest service attachment rates, with Subscription Models climbing the fastest as platforms seek to deepen annual grower relationships beyond single-transaction interactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso soybean belt anchors agricultural e-commerce adoption through cooperative purchasing models that demonstrate input cost compression manufacturers cannot ignore.
United States
California Central Valley specialty crop growers source precision irrigation equipment through digital platforms, drawn by streamlined logistics and manufacturer-direct pricing. The USDA enforces traceability mandates and pesticide residue disclosure rules that determine market access eligibility. Established agrochemical distributors in the US Corn Belt leverage existing credit relationships to delay grower migration toward direct manufacturer platforms.
China
JD.com anchors rural expansion through drone delivery networks reaching township-level distribution points in previously underpenetrated townships. The Ministry of Agriculture and Rural Affairs enforces data localization requirements for agritech platforms handling farmer financial records, creating operational friction for cross-border operators. Alibaba Group leverages its Cainiao logistics arm to control cold-chain infrastructure across Southeast Asian growing regions from its base.
India
Pinduoduo's volume-pooling model demonstrates that aggregated smallholder orders extract manufacturer concessions previously reserved for industrial-scale operations. The PLI scheme for digital infrastructure accelerates rural broadband penetration, enabling real-time platform access in previously disconnected districts. Fertilizer price compression through collective digital procurement in Bihar and Uttar Pradesh now exceeds fifteen percent against individual spot purchases.
Brazil
Cooperative purchasing through digital marketplaces in the Mato Grosso soybean belt reduces input costs through volume aggregation that neighboring growing areas now seek to replicate. ANVISA regulates agricultural input compliance through traceability requirements that platforms must embed for market access. Demand concentrates in this region where cooperative purchasing models demonstrate cost compression that drives platform adoption across South American growing regions.
Germany
German cooperative purchasing groups select marketplace partners based on ESG data granularity rather than price alone under EU Green Deal requirements. The CSRD sustainability disclosure requirements force agricultural input manufacturers to quantify scope-three emissions from distributor networks. Platforms serving European growers embed carbon accounting modules that calculate fertilizer production footprints to meet these mandates.
Agricultural E-Commerce Market Vendor Landscape
Global majors compete with regional champions across logistics infrastructure and farmer credit access, creating a tiered structure where scale-driven platforms battle specialized cooperatives. Consolidation pressures mount as subscription bundling and cold-chain control emerge as differentiation vectors. Three archetypes dominate: integrated logistics platforms, cooperative purchasing aggregators, and manufacturer-direct portals. Strategic moves concentrate on proprietary drone delivery networks and backward integration into biodegradable packaging supply.
Among Asia-Pacific-based platform operators, Alibaba Group, JD.com, and Pinduoduo exemplify divergent rural penetration strategies. Alibaba Group represents the integrated logistics archetype through its Cainiao-controlled cold-chain infrastructure. JD.com anchors the autonomous delivery vector with regulatory clearance-seeking drone networks. Pinduoduo occupies the cooperative aggregation position, converting smallholder volume-pooling into manufacturer pricing leverage. These three illustrate how geographic origin and structural approach determine competitive positioning in agricultural e-commerce.
| Leading Market Players |
|---|
| Alibaba Group |
| Amazon.com |
| JD.com |
| Walmart Inc. |
| Farmers Business Network |
| Pinduoduo |
| IndiaMART InterMESH |
| Tractor Supply Company |
| ProducePay |
| Others |
Supply Flow & Price Mechanics
Platform-backed logistics networks and cooperative purchasing aggregators anchor pricing discipline in agricultural e-commerce, compressing distributor margins while passing input cost volatility through to end-users via subscription-indexed contracts and volume-tiered procurement pools.
Pricing Analysis
Input-cost pass-through dominates agricultural e-commerce pricing, with fertilizer and equipment manufacturers adjusting platform-listed prices seasonally based on ammonia and steel indices. Subscription models index recurring deliveries to commodity benchmarks, insulating growers from spot volatility while locking in platform revenue predictability. Price differentiation rests on volume scale and cold-chain service tier, with cooperative purchasers in Brazil's Mato Grosso extracting steeper discounts than individual spot buyers. Pricing pressure stems from cooperative aggregation compressing legacy distributor markups, with smallholder collectives in India's Bihar and Uttar Pradesh achieving the highest price sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from agricultural cooperatives and large-scale growers mandate that platforms qualify multiple fertilizer and equipment suppliers to mitigate single-source disruption risks. Supply concentration centers on China for precision irrigation components, India for generic agrochemical intermediates, and Germany for specialized machinery controls. Raw material dependencies include nitrogen feedstocks, rare-earth magnets for GPS-enabled equipment, and biodegradable polymer resins for cold-chain packaging. Tariff exposure on Chinese-manufactured precision agriculture hardware creates supply chain risk as platforms seek alternative qualified suppliers. Distribution runs through manufacturer-direct portals, cooperative purchasing aggregators, and integrated logistics platforms with captive cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
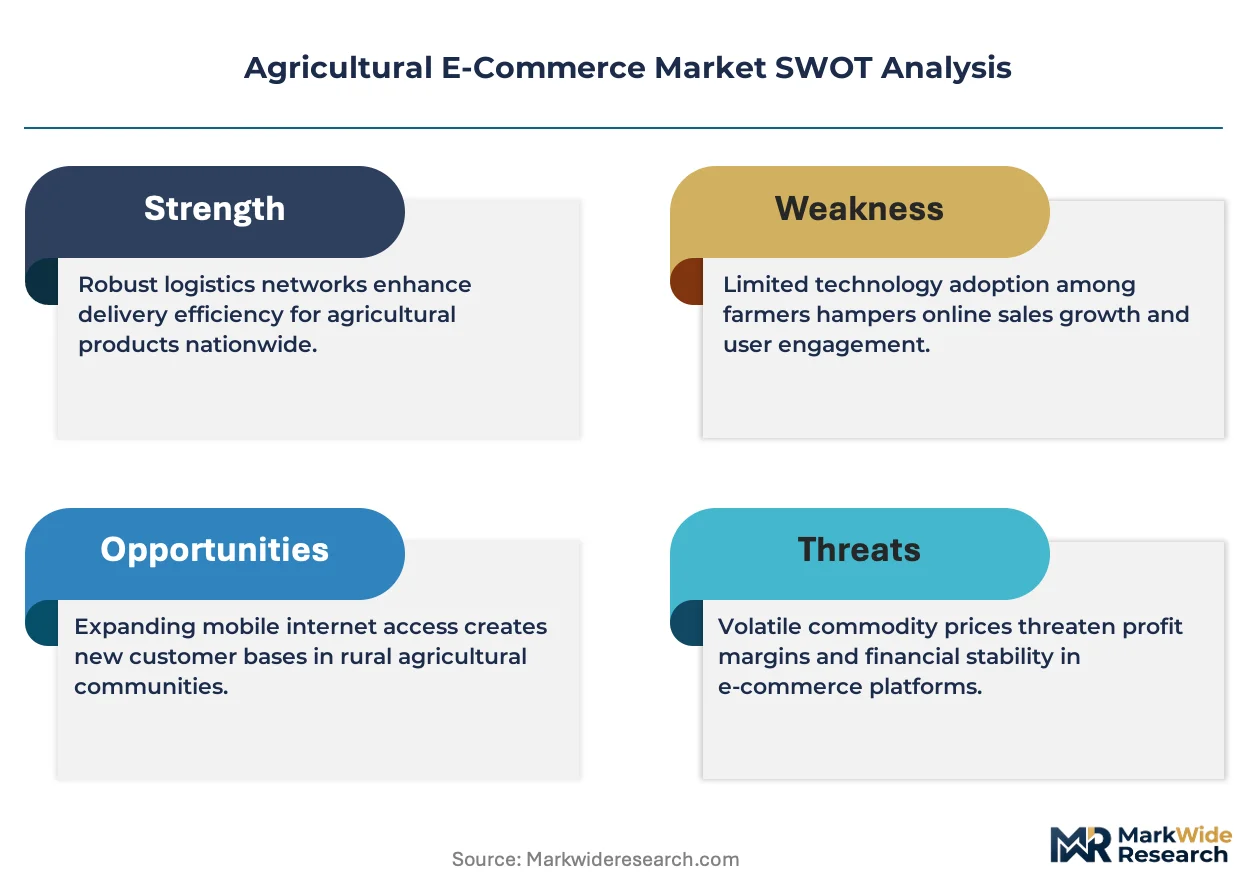
Agricultural e-commerce functions as a geographic-arbitrage play where platforms exploit regulatory divergence between China's data localization mandates and India's PLI-enabled digital infrastructure subsidies to optimize technology stack deployment costs.
For Market Incumbents: To counter cooperative purchasing aggregators eroding distributor relationships, embed proprietary drone delivery networks with simultaneous FAA and CAAC regulatory clearance to secure township-level distribution exclusivity. Backward integration into biodegradable packaging supply secures cold-chain cost control against polymer resin volatility. For New Entrants and Emerging Players: Direct-to-cooperative sales channels offer the most penetrable entry vector, targeting agricultural cooperatives in Southeast Asian growing regions lacking ERP-integrated platform options. White-label platform solutions for legacy distributors seeking digital transformation provide a low-friction go-to-market angle with minimal customer acquisition cost. For Investors and Strategic Acquirers: Valuations sit cheapest among regional logistics specialists with underutilized cold-chain assets and dormant cooperative relationships. Long-term viability hinges on subscription agronomy bundling converting transactional marketplaces into predictable revenue engines. Monitor drone delivery regulatory clearance velocity as the primary inflection signal for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Drone Delivery Network | Regulatory clearance from FAA and CAAC unlocks township-level distribution in underpenetrated rural China. |
| Backward Integration into Biodegradable Packaging | Captive supply of cold-chain polymers reduces spoilage rates for temperature-sensitive biological inputs. |
| Subscription Agronomy Bundling | Recurring input delivery combined with precision advisory locks in annual grower commitments beyond single transactions. |
| Cooperative ERP Integration | API development for agricultural cooperative inventory synchronization accelerates manufacturer onboarding timelines. |
| Carbon Accounting Module Deployment | Embedded fertilizer footprint calculation meets EU Green Deal traceability mandates for German and Dutch cooperative purchasing groups. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform operations executives, agricultural cooperative procurement managers, precision agriculture data scientists, and cold-chain logistics directors with secondary validation against customs and trade data, SEC filings from listed platform operators, USDA traceability mandate documentation, and EU CSRD sustainability disclosure requirements. Bottom-up grower demand modeling and top-down platform revenue triangulation anchored volume and value estimates.
Segment-weighting approaches distributed growth projections across product type categories, distribution channel structures, customer archetypes, and service model tiers, with equipment and fertilizer transaction values calibrated separately from subscription revenue streams. CAGRs were derived from trend extrapolation of cooperative purchasing penetration rates and rural broadband deployment curves under India's PLI scheme. Drone delivery network saturation assumptions and biodegradable packaging adoption timelines informed logistics cost trajectory inputs.
The model assumes a particular technology adoption path; alternative pathways for autonomous last-mile delivery would alter the outlook if regulatory clearance timelines diverge from baseline assumptions. Deviation in rural broadband penetration rates or cooperative purchasing aggregation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Fulfillment Services Market
E-Commerce Solutions
ASEAN E-Commerce Logistics Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
Latin America E-Commerce Logistics Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
FMCG B2B E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
E-Commerce Household Appliances Market
E-Commerce Solutions
Malta E-Commerce Market
E-Commerce Solutions
Indonesia Alcohol E-Commerce Market