
 Flavored Cigar Market | 2026-2036
Flavored Cigar Market Size, Share, and Industry Trends Forecast 2026-2036
Flavored Cigar Market Analysis
Master blender talent is rotating away from traditional hand-rolling centers toward mechanized flavor-infusion facilities, constraining artisan output while unlocking mass-market scale. Swisher International leverages its vertically integrated supply chain to dominate the cigarillo segment. Imperial Brands sustains broad retail penetration across convenience channels. Scandinavian Tobacco Group anchors European distribution through specialized tobacconist relationships.
Flavored cigars are machine-made or hand-rolled tobacco products infused with aromatic agents such as propylene glycol carriers, fruit essences, or menthol crystals during the casing or top-dressing process, designed to mask tobacco harshness and attract novice smokers. Cigarillos occupy the largest volume tier due to their accessible price point and single-serve packaging, while fruit flavor profiles command the fastest expansion as younger demographics reject unflavored alternatives. Bulk packaging retains dominance in club and duty-free channels, though pouches are gaining traction in convenience retail for their portability and resealability.
The US FDA regulates flavored cigars under the Family Smoking Prevention and Tobacco Control Act, with ongoing litigation over premium cigar exemptions creating compliance uncertainty for manufacturers. The EU Tobacco Products Directive mandates graphic health warnings and restricts characterizing flavors, forcing reformulation efforts across export-oriented producers. Stakeholders must monitor regulatory divergence between the US and European frameworks while evaluating flavor innovation strategies that satisfy divergent compliance thresholds.
Market Dynamics
Master blender migration from hand-rolling centers to mechanized flavor-infusion facilities is constraining artisan output while unlocking mass-market scale, fundamentally restructuring how flavored cigars reach consumers.
Growth Catalysts
- Fruit flavor profiles:Young adult consumers in social and lounge settings are expanding purchases of fruit and menthol profiles, rejecting unflavored alternatives and broadening the addressable consumer base.
- Brazil and Dominican Republic sourcing clusters:Demand concentrates in these countries as they deepen their role in tobacco sourcing and flavored cigar production, creating regional manufacturing gravity.
- US FDA deeming rule litigation:Ongoing litigation over premium cigar exemptions continues to reshape product classification and compliance costs, creating regulatory clarity pathways for compliant manufacturers.
Market Restraints
- Tobacco leaf input volatility:Weather-driven yield fluctuations in major growing regions create raw material cost instability that compresses margin predictability across production tiers.
- EU Tobacco Products Directive flavor restrictions:Mandates forcing graphic health warnings and restricting characterizing flavors create reformulation burdens for export-oriented producers serving European markets.
- E-cigarette and heat-not-burn substitution:Alternative nicotine delivery systems capture novice smoker trial that historically flowed to flavored cigars as entry products.
Strategic Opportunities
- Duty-free and travel retail channel expansion:Bulk packaging dominance in club and duty-free channels creates white space for pouch-format innovation targeting portability and resealability.
- Propylene glycol carrier technology convergence:Advances in flavor-infusion casing processes enable more precise aromatic agent distribution and extended shelf stability.
- Convenience retail pouch traction:Single-serve packaging formats are gaining traction in convenience retail, unlocking impulse purchase occasions beyond traditional tobacconist channels.
Industry Challenges
- Artisan hand-rolling skill attrition:Master blender talent rotation toward mechanized facilities constrains premium segment output capacity and extends training timelines for replacement craft workers.
- Dual-jurisdiction compliance complexity:Divergent US FDA and EU Tobacco Products Directive frameworks force manufacturers to maintain parallel product formulations and labeling systems.
- Flavor reformulation timeline compression:Regulatory deadline pressures accelerate R&D cycles while requiring validation of sensory equivalence and consumer acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavored Cigar Market |
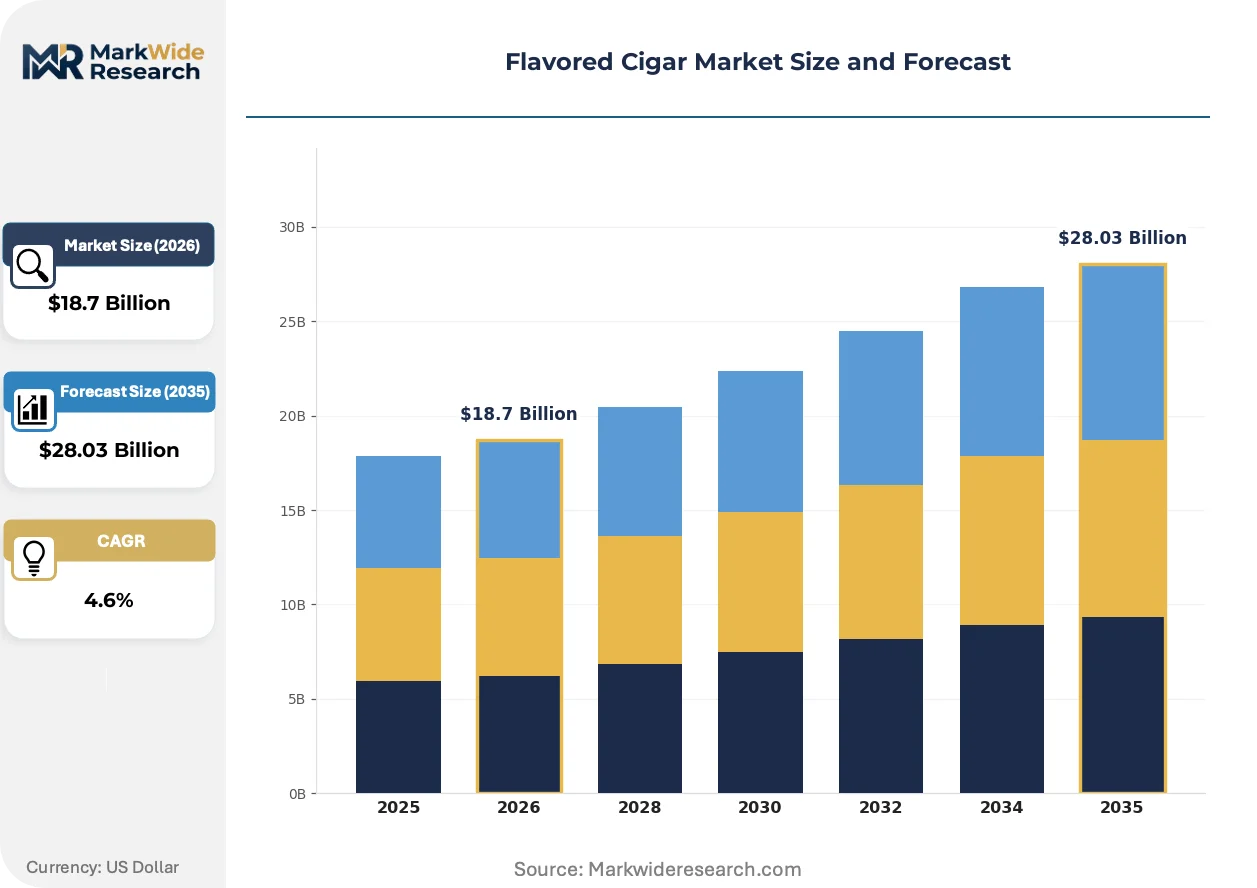
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigars, Cigarillos, Blunts, Flavored Tips Flavor Profile: Fruit, Menthol, Chocolate, Vanilla Packaging Type: Boxes, Pouches, Tins, Bulk Distribution Channel: Online, Retail Stores, Convenience Stores, Tobacco Shops |
| Companies Covered | Swisher International Inc., Imperial Brands Plc, Scandinavian Tobacco Group AS, Arnold Andre GmbH and Co. KG, Japan Tobacco Inc., DANNEMANN EL NOBLE CIGARRO GmbH, Rocky Patel Premium Cigars LLC, Gurkha Cigar Group, Drew Estate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavored Cigar Market Emerging Trajectories
Flavor-infusion automation and regulatory fragmentation are actively reshaping competitive capabilities, forcing manufacturers to choose between artisan heritage and mass-market scalability while navigating divergent compliance frameworks.
Mechanized casing and top-dressing systems are displacing traditional hand-application methods in mid-market production tiers. Large-scale manufacturers are adopting continuous-process flavor-infusion lines that reduce batch variation and labor dependency. This automation is displacing artisan-dominated competitive positioning in the cigarillo segment, compressing price premiums for hand-finished alternatives.
The EU Tobacco Products Directive's characterizing flavor restrictions are forcing reformulation toward tobacco-derived aromatic compounds that evade regulatory classification. Export-oriented producers in Brazil and the Dominican Republic are rebuilding flavor libraries using compliant botanical extracts. Machine-made cigar manufacturers serving European markets face the steepest adaptation costs as they reformulate entire product lines.
Young adult consumers are fragmenting purchase occasions across social lounges, convenience retail, and duty-free channels rather than consolidating loyalty at traditional tobacconists. This channel fragmentation is compressing brand equity accumulation and forcing portfolio diversification across price tiers and packaging formats. Brazil and urban US markets exhibit the most pronounced behavioral divergence from historical consumption patterns.
Flavored Cigar Market Segmentation
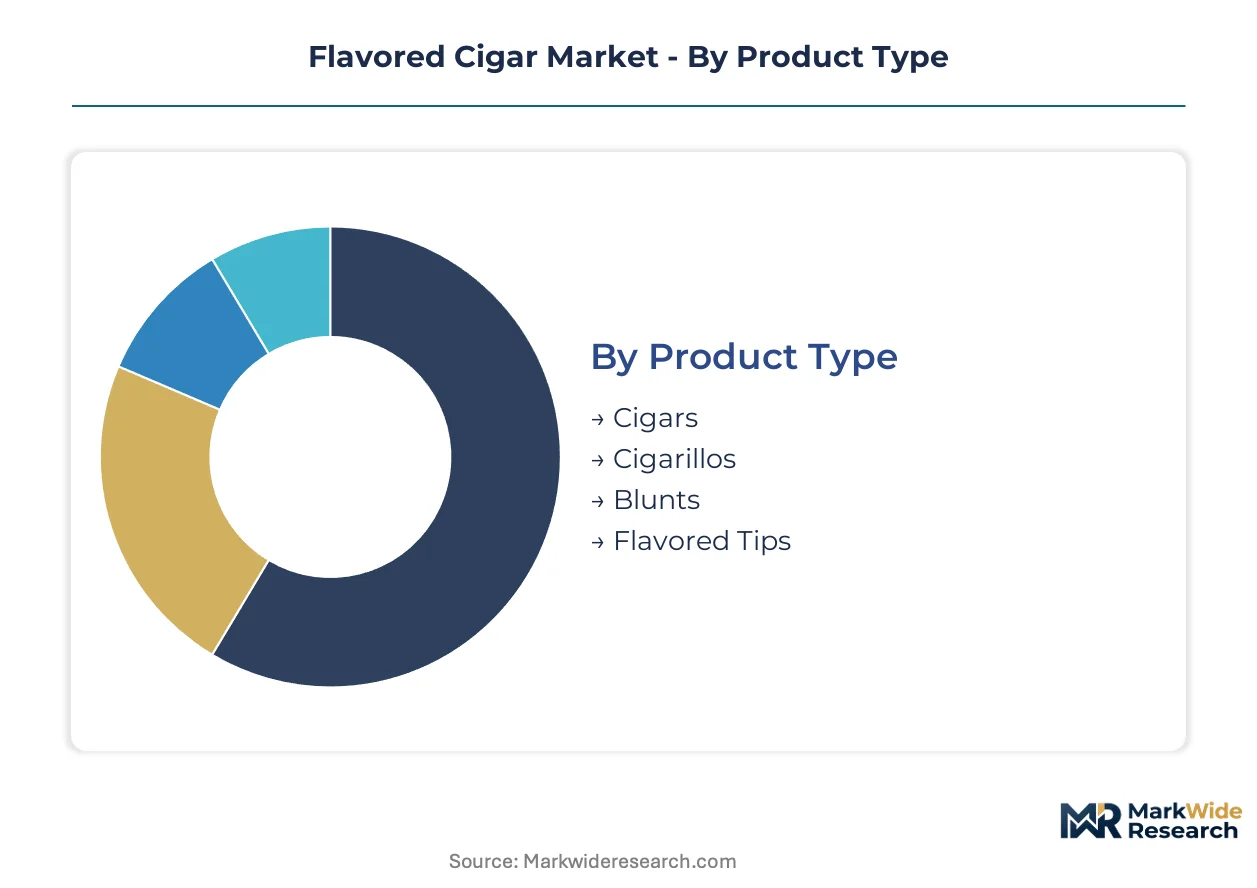
Segmentation in the flavored cigar market reveals how manufacturers balance artisan heritage against mass-market mechanization. Product architecture, flavor chemistry, and channel economics create distinct competitive arenas with divergent margin profiles and regulatory exposure.
Product Type:
Domestic US demand concentrates in machine-made formats, while export-led growth flows from hand-rolled specialty production in the Dominican Republic and Brazil.
- Cigars:Hand-rolled or machine-made formats with full-length tobacco filler, binder, and wrapper construction. Dominican Republic master blenders supply US lounge channels where consumers pay premiums for provenance documentation. FDA deeming rule litigation over premium exemptions creates compliance uncertainty for this tier.
- Cigarillos:Short, narrow formats with homogenized tobacco leaf wrappers and rapid flavor-infusion compatibility. Brazil's vertically integrated producers dominate export volume to European convenience channels facing EU Tobacco Products Directive reformulation deadlines. This segment captures the broadest price-accessible consumer base.
- Blunts:Tobacco leaf wraps designed for cannabis pairing, produced primarily for North American urban markets.
- Flavored Tips:Filter or mouthpiece modifications with embedded aromatic compounds, concentrated in novelty-driven trial purchases.
Cigarillos hold the largest share; momentum sits with cigar formats as lounge culture deepens in US metropolitan markets.
Flavor Profile:
Cost tier stratification separates commodity menthol from premium fruit extraction technologies, with chocolate and vanilla occupying mid-market positioning.
- Fruit:Propylene glycol carrier systems distribute berry, citrus, and tropical essences through casing or top-dressing processes. Young adult consumers in US social settings reject unflavored alternatives, driving fastest expansion across all profiles. Brazilian producers rebuild flavor libraries using botanical extracts to evade EU characterizing flavor restrictions.
- Menthol:Crystalline menthol or synthetic analogs applied via alcohol-based solutions for cooling sensation. Established demand in traditional convenience channels sustains volume despite regulatory scrutiny from FDA flavor prohibition proposals.
- Chocolate:Cocoa-derived and synthetic chocolate aromatic compounds targeting female demographic segments in European duty-free channels.
- Vanilla:Vanillin and ethyl vanillin formulations dominating entry-price cigarillo lines in US gas station retail.
Menthol holds the largest share; fruit profiles are climbing the fastest as novice smoker preferences fragment away from traditional tobacco taste.
Packaging Type:
Volume concentration in duty-free and club channels favors bulk formats, while customer-type fragmentation toward impulse purchasers drives pouch innovation.
- Boxes:Rigid cardboard or wood constructions housing 20-25 units for gift and collector markets. Dominican Republic exporters prioritize box formats for US tobacconist channels where presentation quality supports price premiums. Extended shelf stability requirements favor boxes for aged tobacco inventory.
- Pouches:Flexible laminated films with resealable closures containing 2-5 units. Convenience retail traction accelerates as Brazilian manufacturers adapt European-format pouches for US gas station distribution. Portability matches fragmented purchase occasions across social lounges and travel.
- Tins:Metal containers with humidity control for premium short-run releases in specialized retail.
- Bulk:Unpackaged or minimal-wrap formats for casino, nightclub, and duty-free volume accounts.
Bulk holds the largest share; pouches are gaining share fastest as channel fragmentation compresses traditional brand loyalty patterns.
Distribution Channel:
Supply concentration in manufacturer-direct relationships shapes online and tobacco shop economics, while margin compression defines convenience store and retail store dynamics.
- Online:Direct-to-consumer platforms and third-party marketplaces bypassing traditional wholesale markups. US FDA age verification requirements and state-specific shipping prohibitions create operational complexity for cross-border sellers. Dominican Republic producers leverage online channels to reach diaspora consumers in Florida and New York.
- Convenience Stores:High-velocity, single-serve purchase environments with limited SKU depth. Imperial Brands and Scandinavian Tobacco Group sustain broad penetration through dedicated cooler placement and promotional allowances. Brazilian cigarillo exports concentrate here for price-sensitive trial conversion.
- Retail Stores:Mass-market outlets with tobacco sections competing against e-cigarette and nicotine pouch alternatives.
- Tobacco Shops:Specialist retailers with humidor storage and staff expertise supporting premium hand-rolled sales.
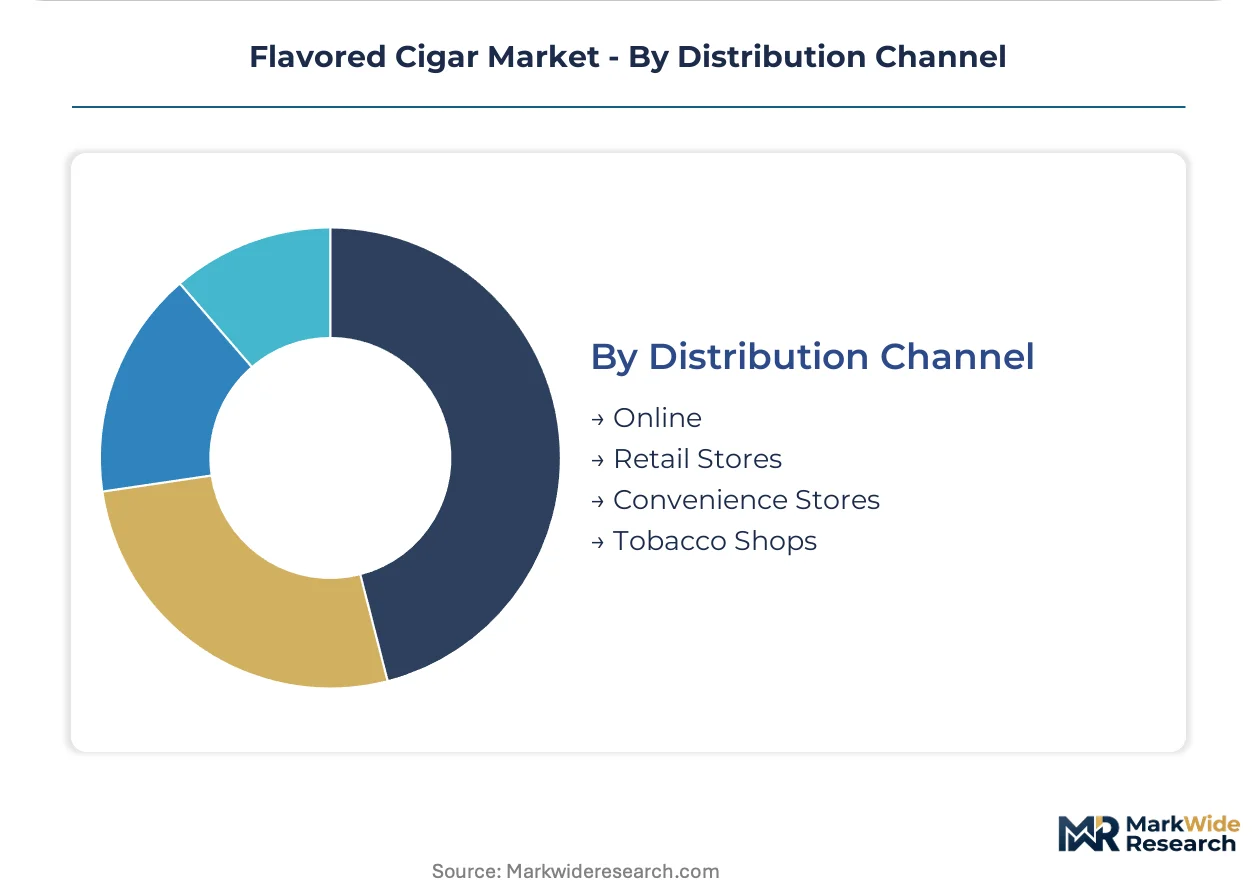
Convenience stores hold the largest share; online channels show steepest expansion trajectory as direct manufacturer relationships bypass traditional wholesale structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature lounge cultures and emerging convenience-driven trial markets, with the United States favoring social-occasion formats while Brazil and European markets emphasize single-serve accessibility.
United States
Social lounge expansion in Miami, New York, and Los Angeles drives demand for fruit-profile cigarillos and premium hand-rolled formats. FDA deeming rule litigation over premium cigar exemptions creates compliance uncertainty that favors mechanized producers with regulatory affairs capacity. Dominican Republic master blenders supply Florida and Northeast corridors where provenance documentation commands price premiums.
Brazil
Vertically integrated tobacco sourcing clusters in Bahia and Minas Gerais anchor export-oriented flavored cigarillo production for European convenience channels. ANVISA tobacco product regulations align with Mercosur trade frameworks, enabling streamlined cross-border distribution. São Paulo-based manufacturers rebuild flavor libraries using botanical extracts to evade EU characterizing flavor restrictions.
Dominican Republic
Tobacco-growing regions around Santiago and La Romana deepen their role in hand-rolled specialty production for US lounge channels. The national tobacco regulator maintains quality certification programs that support export market access. Santiago master blenders face talent rotation pressures as mechanized facilities absorb skilled labor.
Germany
DANNEMANN EL NOBLE CIGARRO GmbH anchors European distribution through specialized tobacconist relationships and duty-free channel penetration. BfArM tobacco product regulations implement EU Tobacco Products Directive flavor restrictions, forcing reformulation toward tobacco-derived aromatic compounds. North Rhine-Westphalia logistics hubs facilitate redistribution across continental European markets.
Japan
JT Group distribution networks sustain flavored cigarillo presence in convenience retail despite heat-not-burn substitution pressures. PMDA tobacco regulations maintain distinct flavor classification frameworks from Western jurisdictions. Tokyo and Osaka metropolitan areas concentrate lounge-format experimentation among young adult consumers.
Flavored Cigar Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding supply chain control and the latter competing on artisan differentiation. Mechanized flavor-infusion capabilities separate scale players from craft-oriented competitors. Two archetypes dominate: vertically integrated mass-market manufacturers and heritage-focused hand-rolling specialists. Competitive moves concentrate on backward integration into tobacco sourcing and portfolio diversification across flavor profiles and packaging formats.
Among US-based mass-market manufacturers, Swisher International Inc. exemplifies scale-driven mechanized production, while Imperial Brands Plc anchors broad retail penetration across convenience channels. Scandinavian Tobacco Group AS represents the European distribution-focused archetype through specialized tobacconist relationships.
| Leading Market Players |
|---|
| Swisher International Inc. |
| Imperial Brands Plc |
| Scandinavian Tobacco Group AS |
| Arnold Andre GmbH and Co. KG |
| Japan Tobacco Inc. |
| DANNEMANN EL NOBLE CIGARRO GmbH |
| Rocky Patel Premium Cigars LLC |
| Gurkha Cigar Group |
| Drew Estate |
| Others |
Supply Flow & Price Mechanics
Ninety-day tobacco leaf aging cycles in Dominican Republic warehouses compress working capital buffers while concentrating pricing power among vertically integrated manufacturers with captive curing facilities. This inventory-to-pricing dynamic favors scale players who internalize leaf procurement against artisan competitors exposed to spot-market wrapper volatility.
Pricing Analysis
Long-term offtake contracts dominate premium hand-rolled procurement, while spot-market transactions govern machine-made cigarillo filler sourcing. Three-tier pricing structure across premium, standard, and economy levels separates Dominican master-blender provenance from Brazilian mechanized output and commodity homogenized leaf alternatives. Pricing pressure stems from EU Tobacco Products Directive reformulation costs forcing flavor-library rebuilds. Convenience retail buyers exhibit highest price sensitivity; lounge-channel consumers demonstrate lowest sensitivity to per-unit differentials.
Supply Chain Analysis
Strategic stockpiling of wrapper-grade Connecticut Shade and Cameroon leaf anchors inventory strategy against weather-driven yield volatility in major growing regions. Supply concentrates in Brazil, the Dominican Republic, and Nicaragua for filler and binder grades. Raw material dependencies include crystalline menthol carriers, propylene glycol flavor solvents, and homogenized tobacco leaf substrates. Tariff exposure on Brazilian cigarillo exports to European markets represents the dominant structural risk. Distribution runs through manufacturer-direct relationships with convenience store chains and duty-free operators, bypassing traditional wholesale tobacco distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master blender attrition from hand-rolling centers to mechanized facilities has created acute capability scarcity in artisan cigar construction, compressing premium segment output capacity and extending replacement training timelines for heritage craft skills.
For Market Incumbents: Shield core lounge-channel positioning by locking exclusive multi-year contracts with Dominican Republic master blenders before talent rotation accelerates. Fortify regulatory affairs capacity to navigate FDA deeming rule litigation outcomes and EU Tobacco Products Directive flavor restriction enforcement, using compliance infrastructure as a competitive moat against smaller mechanized competitors. For New Entrants and Emerging Players: Anchor in Brazilian cigarillo export production for European convenience channels facing reformulation deadlines, where botanical extract flavor libraries offer first-mover advantage over incumbents with legacy synthetic portfolios. Target duty-free pouch-format white space with resealable laminated film innovations that match fragmented travel and social lounge purchase occasions. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mechanized flavor-infusion scale economics will displace artisan-dominated competitive positioning in the cigarillo segment. Monitor master blender employment contract renewal rates at Dominican Republic heritage producers as the inflection signal for premium segment supply constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Master Blender Talent Lock-In | Exclusive multi-year contracts with Dominican Republic heritage producers secure scarce artisan capacity against mechanized facility poaching. |
| Botanical Extract Flavor Library Build | EU Tobacco Products Directive-compliant reformulation using tobacco-derived aromatic compounds enables continued European market access. |
| Resealable Pouch Format Expansion | Laminated film packaging with humidity control captures impulse purchase occasions in convenience retail and travel channels. |
| Backward Integration into Curing Facilities | Captive tobacco leaf aging infrastructure in Brazil and the Dominican Republic insulates margin from spot-market wrapper volatility. |
| Regulatory Affairs Capacity Investment | Dedicated FDA and EU compliance teams navigate deeming rule litigation and flavor restriction enforcement timelines. |
Methodological Framework
A standing panel of master blenders, convenience store category buyers, duty-free procurement managers, and regulatory affairs directors at major manufacturers provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with these stakeholders and trade data triangulation against customs records, FDA tobacco product registrations, and EU TPD compliance filings. Bottom-up volume modeling across product type, flavor profile, packaging format, and distribution channel segments was cross-checked against top-down macroeconomic consumption indicators.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. The analytical framework segmented by machine-made versus hand-rolled production tier, fruit versus menthol versus chocolate flavor chemistry, and convenience retail versus tobacconist versus duty-free channel economics. CAGRs were derived from segment-level growth trajectory analysis incorporating tobacco leaf input cost indices, regulatory deadline schedules, and substitution elasticity estimates for heat-not-burn alternatives.
Decision-makers should treat outputs as directional under assumptions of stable FDA litigation timelines and EU flavor restriction enforcement schedules; material deviation would warrant model refresh. Revision becomes warranted when master blender attrition rates or botanical extract flavor equivalency validation crosses thresholds that alter premium segment supply elasticity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
North America E-Cigarette Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
GCC E-Cigarette Market