
 Europe E-Cigarettes Market | 2026-2036
Europe E-Cigarettes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Cigarettes Market Intelligence
The capital-intensity divergence between large tobacco conglomerates and independent hardware manufacturers is unwinding competitive dynamics across Europe. Philip Morris International leverages its heated-tobacco infrastructure to cross-subsidize e-cigarette R&D spending. Geekvape anchors its position through Shenzhen-based manufacturing scale that undercuts European assembly costs. British American Tobacco navigates retail channel complexity by controlling shelf placement in British and German convenience networks.
An e-cigarette is an electronic inhaler device that vaporizes a liquid solution—typically containing propylene glycol, vegetable glycerin, flavoring compounds, and nicotine—through battery-powered heating of a metal coil or ceramic element, producing an aerosol for user inhalation as a combustible-tobacco alternative. Pod systems now lead European volume due to their compact form factor and prefilled cartridge convenience, while box mods retain a premium margin pool among enthusiast subcultures who customize wattage and coil resistance. Salt nicotine formulations are displacing freebase liquids in retail channels because they deliver higher nicotine absorption at lower vapor temperatures, reducing device bulk.
The European Medicines Agency and national regulators under the EU Tobacco Products Directive enforce notification requirements, ingredient disclosure, and advertising restrictions that shape product formulation and market access across member states. REACH compliance for chemical substances in e-liquids adds testing burdens that favor larger manufacturers with dedicated toxicology departments. Stakeholders must monitor pending flavor prohibition proposals in multiple member states and decide whether to accelerate portfolio diversification toward nicotine-free botanical inhalers or double down on regulatory defense of existing product architectures.
Market Dynamics
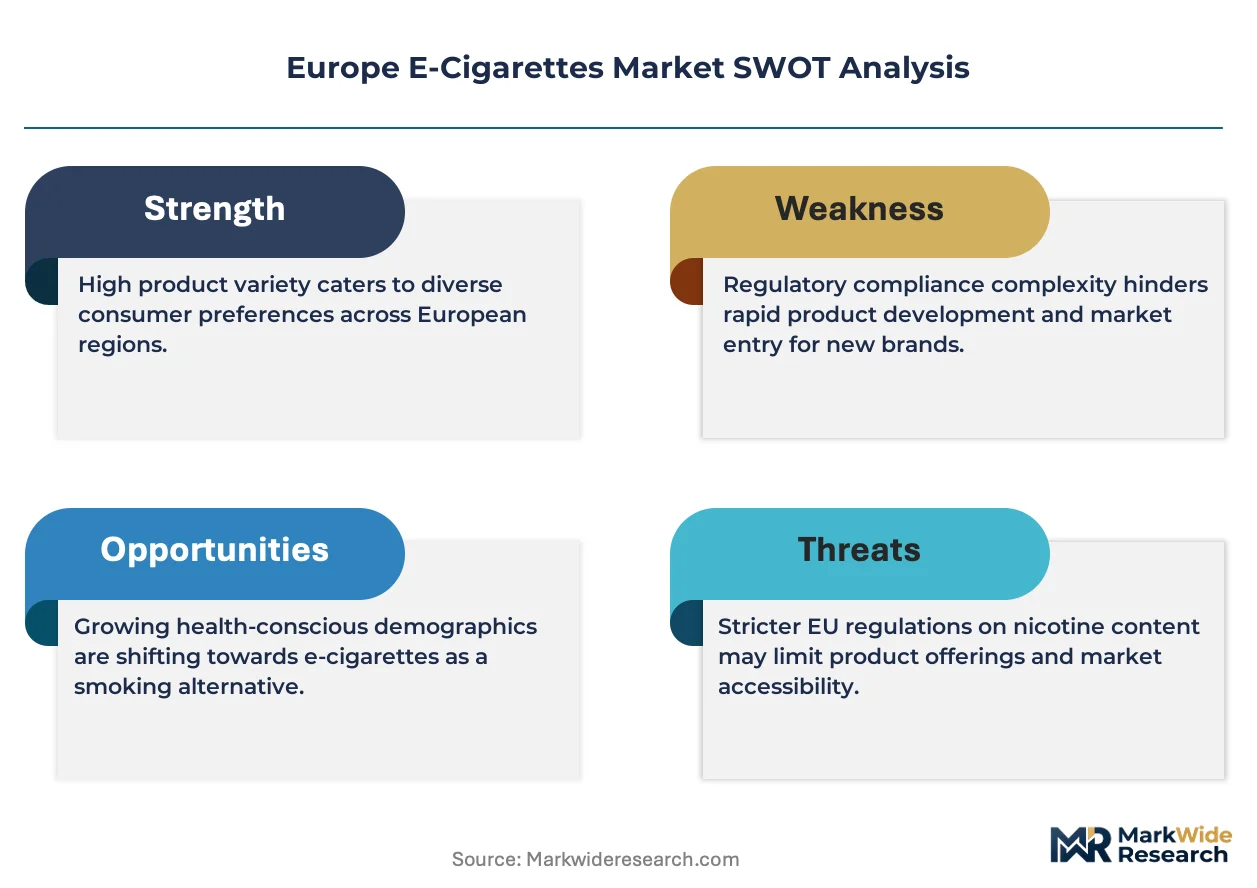
The EU Tobacco Products Directive revision is compressing nicotine concentration ceilings and flavor portfolios, forcing manufacturers to rebuild formulation pipelines around restricted ingredient lists while urban consumers accelerate migration toward rechargeable pod systems.
Growth Catalysts
- TPD Notification Streamlining:Centralized EU-wide product registration reduces duplicate national filings, cutting time-to-market for compliant e-liquid portfolios across Germany, France, and Poland.
- Urban Consumer Migration:Young adult smokers in London, Berlin, and Paris metropolitan zones are abandoning combustible tobacco for closed-system pods that minimize odor and device maintenance.
- Ceramic Coil Adoption:Porous ceramic heating elements eliminate metallic aftertaste and extend coil lifespan, driving replacement demand among enthusiast subcultures.
Market Restraints
- REACH Compliance Burden:E-liquid manufacturers face toxicology testing costs for propylene glycol and flavoring compounds that disproportionately burden small-batch producers without dedicated regulatory departments.
- Battery Supply Concentration:Lithium-ion cell procurement depends heavily on East Asian suppliers, exposing European assembly operations to shipping volatility and raw material price swings.
- Flavor Prohibition Momentum:Pending bans on sweet and fruit flavor profiles in the Netherlands and Belgium threaten the margin structure of prefilled cartridge segments.
Strategic Opportunities
- Nordic Market Underpenetration:Sweden and Norway maintain higher snus prevalence than e-cigarette adoption, creating whitespace for hybrid nicotine product positioning.
- Nicotine-Free Botanical Inhalers:Regulatory pressure on nicotine-containing products is opening formulation R&D toward herbal vaporizers that fall outside TPD jurisdiction.
- Pharmacy Channel Expansion:Boots and Alliance Healthcare in the United Kingdom are piloting medically-positioned vaping products adjacent to smoking cessation aids.
Industry Challenges
- Toxicology Talent Scarcity:REACH-compliant safety assessment requires specialized chemists familiar with inhalation toxicology, a skill pool concentrated in Basel and Frankfurt.
- Coil Standardization Delays:Incompatible threading and wattage protocols between pod systems create inventory fragmentation for retailers stocking multiple hardware brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Cigarettes Market |
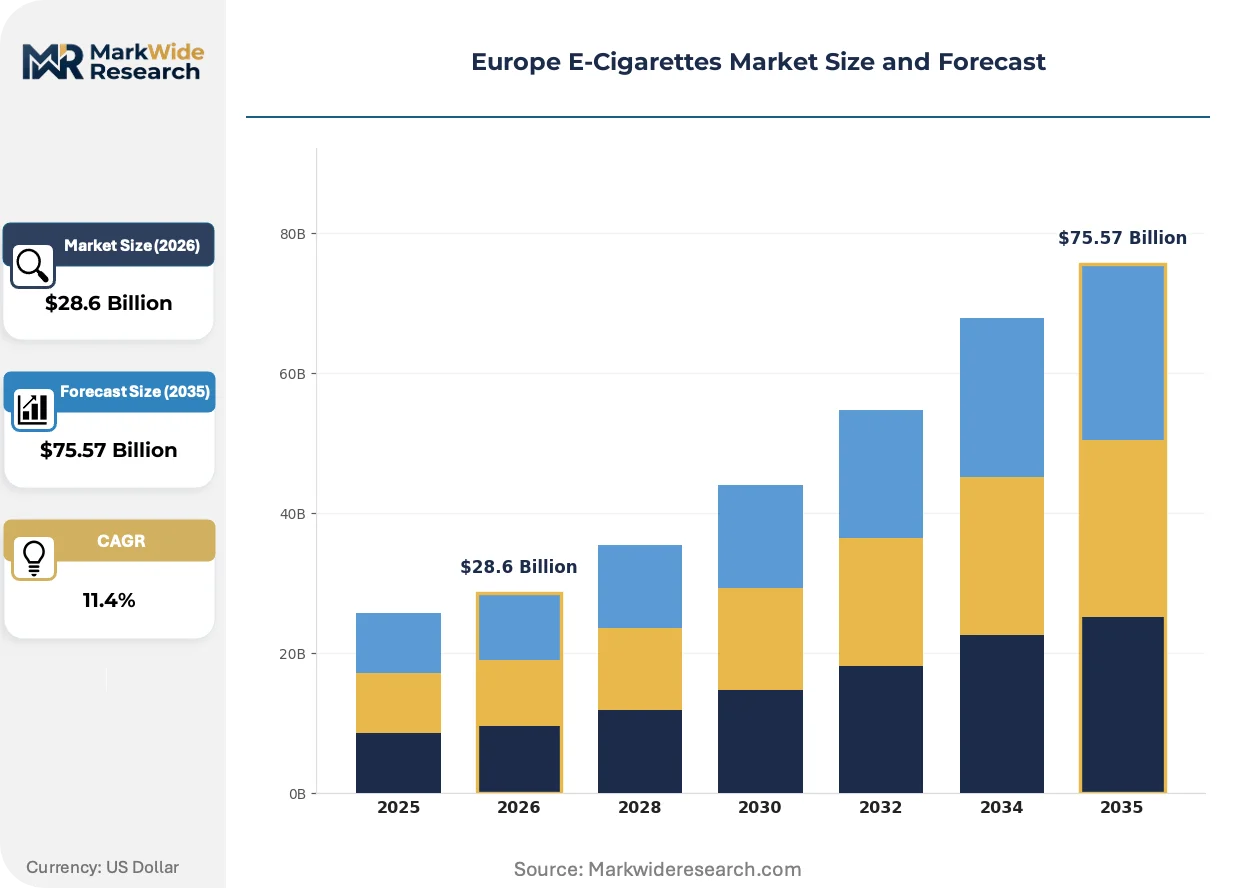
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cig-a-likes, Vapes, Pod Systems, Box Mods Customer Type: Retail Consumers, Wholesalers, Online Sellers, Convenience Stores Flavor Profile: Tobacco, Menthol, Fruit, Dessert Nicotine Level: Freebase, Salt Nicotine, High Nicotine, Low Nicotine |
| Companies Covered | Imperial Brands, Innokin Technology, British American Tobacco, Vaporesso, Joyetech Group, Philip Morris International, Japan Tobacco International, Geekvape, Altria Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Cigarettes Market Strategic Shifts & Innovations
Salt nicotine chemistry, regulatory disclosure mandates, and channel consolidation are restructuring how products reach European consumers and how manufacturers defend shelf position.
Ceramic heating elements with precise temperature control are displacing traditional metal coils in premium device tiers. Enthusiast vapers in Barcelona and Milan are adopting these systems for cleaner flavor delivery. The shift is compressing replacement part margins for legacy kanthal and nichrome suppliers while elevating ceramic substrate manufacturers.
EMA-coordinated ingredient disclosure requirements under the EU Tobacco Products Directive now mandate six-month advance notification for new e-liquid formulations. This regulatory friction is extending product development cycles and freezing smaller flavor houses out of rapid innovation pipelines. German and French manufacturers are responding by consolidating formulation portfolios around proven, pre-cleared recipes.
Convenience store chains in the United Kingdom and Ireland are displacing independent vape shops as the primary retail channel for pod system refills. Tesco and Sainsbury's expanded dedicated vaping fixtures in 2023, capturing impulse purchases from combustible tobacco buyers. This channel rotation is squeezing specialist retailers in Manchester and Birmingham who lack procurement scale for competitive unit economics.
Europe E-Cigarettes Market Segmentation
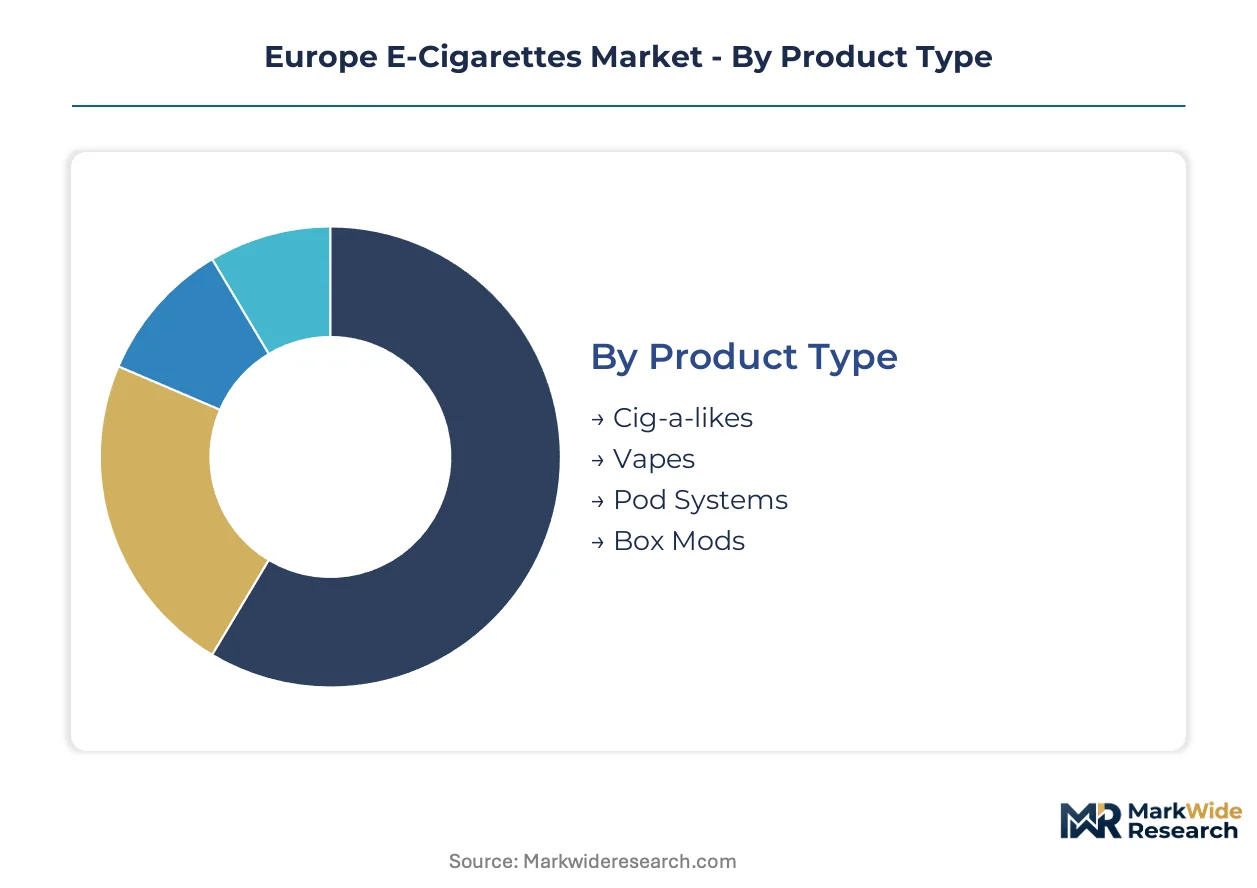
European e-cigarette segmentation reflects divergent regulatory exposure across product architectures and distribution channels. Manufacturers calibrate portfolio depth against TPD notification burdens and flavor prohibition risks in specific member states.
Product Type:
TPD compliance costs vary sharply by device complexity, with refillable systems facing stricter ingredient disclosure than sealed cartridges.
- Pod Systems:Closed and open pod configurations dominate urban retail channels across London, Berlin, and Paris. Salt nicotine compatibility and minimal maintenance requirements drive adoption among former combustible smokers seeking discrete form factors. REACH testing obligations for e-liquid ingredients concentrate procurement among manufacturers with dedicated toxicology departments.
- Box Mods:Customizable wattage control and rebuildable atomizer support sustain enthusiast demand in Barcelona and Milan specialty retailers. Ceramic coil compatibility and temperature precision command premium pricing tiers. Coil standardization fragmentation between manufacturers complicates inventory management for multi-brand retailers.
- Cig-a-likes:First-generation devices resembling combustible cigarettes retain niche positioning among older demographic transitions.
- Vapes:Pen-style devices occupy mid-market positioning between pod convenience and mod customization.
Established volume favors pod systems; emerging adoption favors box mods with ceramic heating elements.
Customer Type:
Channel consolidation toward convenience retail is compressing margin structures for independent specialists.
- Convenience Stores:Tesco and Sainsbury's in the United Kingdom expanded dedicated vaping fixtures, capturing impulse purchases from tobacco buyers. Shelf placement fees and volume procurement requirements disadvantage smaller hardware brands.
- Online Sellers:E-commerce platforms navigate divergent national advertising restrictions under TPD Article 20, with France and Germany enforcing distinct promotional limitations. Age verification infrastructure costs favor established marketplace operators over direct-to-consumer startups.
- Retail Consumers:Direct purchases concentrate in urban centers with specialist vape shop density.
- Wholesalers:Distribution intermediaries manage cross-border compliance complexity for multi-national e-liquid portfolios.
Volume concentration sits with convenience stores; margin defense sits with online sellers leveraging regulatory arbitrage.
Flavor Profile:
Pending prohibition timelines in the Netherlands and Belgium are forcing accelerated portfolio rebalancing toward tobacco-menthol core ranges.
- Fruit:Sweet and tropical profiles drive prefilled cartridge volume in United Kingdom convenience channels. Regulatory risk concentration in Benelux markets threatens long-term revenue visibility for dedicated flavor houses.
- Tobacco:Classic profiles align with smoking cessation positioning and face lower prohibition probability across EU member states. Pharmacy channel pilots by Boots position tobacco-flavored devices adjacent to nicotine replacement therapies.
- Menthol:Cooling sensations retain regulatory tolerance in most jurisdictions while satisfying sensory expectations of transitioning smokers.
- Dessert:Bakery and confectionery profiles concentrate in enthusiast-directed e-liquid segments with higher formulation complexity.
Defensive positioning favors tobacco; growth vulnerability concentrates in fruit.
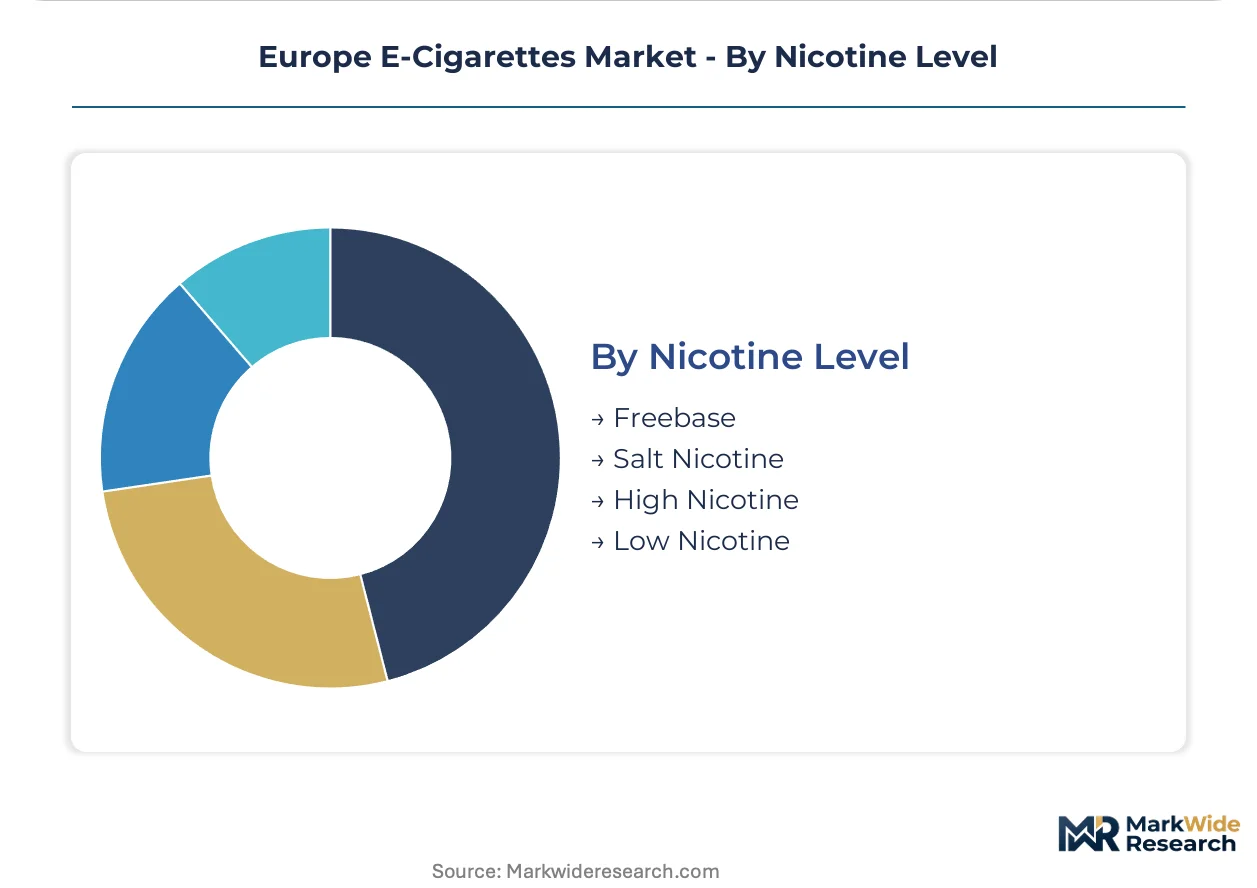
Nicotine Level:
Absorption efficiency and throat hit characteristics differentiate formulation strategies across consumer transition stages.
- Salt Nicotine:Benzoic acid formulations enable higher concentration delivery at reduced vapor temperatures, permitting compact pod device design. United Kingdom and German retail channels show accelerating displacement of freebase alternatives.
- Freebase:Traditional alkaline nicotine retains enthusiast preference for customizable throat hit intensity in open tank systems. pH-dependent harshness limits viable concentration ceilings in smaller form factors.
- High Nicotine:Concentrations approaching TPD ceilings serve heavy smoker transition segments.
- Low Nicotine:Graduated reduction profiles support step-down cessation protocols and nicotine-free botanical migration.
Formulation momentum favors salt nicotine; freebase retains mod enthusiast loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European markets. German and French consumers demonstrate lower sensitivity to device premiums, while Italian and Spanish buyers gravitate toward budget pod systems. This demand divergence shapes manufacturer portfolio strategies and channel investment priorities.
United Kingdom
London and Manchester metropolitan areas drive closed-system pod adoption among young adult smokers switching from combustibles. The Medicines and Healthcare products Regulatory Agency enforces TPD notification requirements with stricter age-verification protocols than continental counterparts. Boots pharmacy pilots position medically-framed vaping products adjacent to nicotine replacement therapies in Greater London retail clusters.
Germany
Berlin and Hamburg concentrate demand for premium box mods with ceramic heating elements among enthusiast subcultures. The Federal Institute for Drugs and Medical Devices maintains rigorous e-liquid ingredient disclosure standards that extend product development timelines. North Rhine-Westphalia hosts multiple compliance consulting firms serving manufacturers navigating REACH toxicology requirements.
France
Parisian convenience networks capture impulse pod system purchases from combustible tobacco buyers in dense urban retail. ANSM coordinates with EU agencies on flavor restriction enforcement while permitting pharmacy distribution experiments. Lyon and Marseille specialist retailers maintain enthusiast customer bases for customizable open-tank configurations.
Italy
Milan and Rome consumers prioritize cost-efficient pod systems over premium device tiers, compressing manufacturer margin structures. The Italian Ministry of Health implements TPD provisions with stricter advertising limitations than northern European neighbors. Lombardy-based distributors manage cross-border e-liquid procurement for southern European markets.
Netherlands
Amsterdam and Rotterdam retail channels face imminent flavor prohibition timelines that threaten fruit-profile cartridge revenue. The National Institute for Public Health and the Environment advances sweet and tropical flavor ban proposals ahead of broader EU harmonization. Eindhoven manufacturing consultants advise hardware brands on nicotine-free botanical inhaler diversification.
Europe E-Cigarettes Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European e-cigarette sector. Large tobacco conglomerates leverage heated-tobacco infrastructure and retail channel control to defend premium positioning, while Shenzhen-based hardware specialists undercut assembly costs through manufacturing scale. Three strategic archetypes dominate: integrated tobacco multinationals with cross-subsidized R&D, independent Chinese manufacturers with supply chain cost advantages, and European compliance specialists with toxicology expertise. Competitive dynamics center on portfolio diversification toward nicotine-free alternatives and regulatory defense of existing flavor architectures.
Among integrated tobacco conglomerates, Philip Morris International and British American Tobacco exemplify archetypes combining heated-tobacco infrastructure with e-cigarette portfolio expansion. Geekvape represents the Shenzhen-based manufacturing scale archetype that undercuts European assembly economics. Imperial Brands occupies a position bridging tobacco legacy distribution with independent hardware procurement strategies.
| Leading Market Players |
|---|
| Imperial Brands |
| Innokin Technology |
| British American Tobacco |
| Vaporesso |
| Joyetech Group |
| Philip Morris International |
| Japan Tobacco International |
| Geekvape |
| Altria Group |
| Others |
Cost & Logistics Intelligence
REACH compliance for chemical substances in e-liquids gates both supplier qualification and price differentiation simultaneously, concentrating procurement among manufacturers with dedicated toxicology departments while forcing smaller flavor houses toward commodity positioning or exit.
Pricing Analysis
Replacement coil and pod cartridge revenue drives lifetime value across European channels. Three-tier pricing structure across premium ceramic systems, standard metal-coil devices, and economy cig-a-likes segments the market by heating technology and durability. Price differentiation hinges on CE marking tier and after-sales service bundling with specialist retailers. Cost compression in prefilled cartridge segments is intensifying because convenience chains extract volume discounts through centralized procurement. Italian and Spanish retail consumers exhibit highest price sensitivity; German enthusiast buyers accept premium positioning for temperature precision.
Supply Chain Analysis
Port congestion on Shenzhen-Rotterdam lanes elevates inbound logistics costs for lithium-ion cells and ceramic heating substrates. Manufacturing concentrates in China, Malaysia, and Poland for device assembly; e-liquid formulation clusters in Germany, France, and the United Kingdom. Raw material dependencies span lithium carbonate from Chile, nickel-chromium alloys from Finland, and flavoring compounds from Switzerland. Single-source vulnerability around East Asian battery suppliers exposes European assembly to shipping volatility. Distribution runs through convenience store chains displacing independent vape shops in United Kingdom and Ireland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU member states creates fragmentation opportunity, as divergent flavor prohibition timelines and nicotine concentration enforcement open niche positioning for agile formulators.
For Market Incumbents: Shield core revenue by accelerating portfolio diversification toward nicotine-free botanical inhalers ahead of pending TPD flavor restrictions in Benelux markets. Deepen upstream control over ceramic substrate supply through captive manufacturing partnerships in Poland. Fortify pharmacy channel positioning through Boots and Alliance Healthcare pilot expansions to preempt commoditization in convenience retail.
For New Entrants and Emerging Players: Differentiate on compliance velocity by building REACH-ready toxicology capabilities that bypass six-month EMA notification delays freezing smaller competitors. Target Nordic whitespace in Sweden and Norway where snus prevalence exceeds e-cigarette adoption. Pursue hybrid nicotine product positioning through pharmacy distribution experiments in France and the United Kingdom.
For Investors and Strategic Acquirers: Carve-out targets emerge from tobacco conglomerates divesting non-core vaping assets amid heated-tobacco prioritization. Long-term viability over the coming decade rests on regulatory arbitrage capabilities and channel control in consolidating retail. Monitor flavor prohibition implementation velocity in the Netherlands as inflection indicator for portfolio rebalancing urgency across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Defense Investment | Dedicated toxicology departments enable faster EMA notification cycles than competitors. |
| Pharmacy Channel Expansion | Boots pilots position vaping adjacent to nicotine replacement therapies in Greater London. |
| Ceramic Coil Manufacturing Scale-Up | Porous substrate production captures replacement demand from Barcelona enthusiast clusters. |
| Botanical Inhaler R&D Pivot | Nicotine-free formulations fall outside TPD jurisdiction as regulatory pressure intensifies. |
| Supply Chain Regionalization | Polish assembly reduces dependency on Shenzhen-Rotterdam shipping lanes. |
Research Approach
A standing panel of e-liquid formulation chemists, convenience store category buyers, regulatory affairs specialists at notified bodies, and ceramic heating element engineers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against EMA notification databases, REACH compliance filings, customs trade records for lithium-ion cell imports, and retail audit data from Nielsen. Bottom-up volume modeling triangulated against top-down manufacturer revenue estimates across the analysis window.
Consistency checks validated outputs against external benchmarks including toxicology testing expenditure patterns and ceramic substrate pricing indices. The analytical framework modeled segmentation across device architecture, distribution channel, flavor profile, and nicotine chemistry throughout the forecast period. CAGRs derived from year-over-year growth rate convergence across independent demand-side and supply-side estimates. Industry-specific inputs included TPD notification timelines and flavor prohibition probability assessments.
Forecasts assume regulatory continuity in EU Tobacco Products Directive enforcement and REACH chemical compliance; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Europe Cigarette Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Luxury Cigarette Market