
 Global Blockchain Supply Chain Market | 2026-2036
Global Blockchain Supply Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain Supply Chain Market Foresight
Pharmaceutical manufacturers is rotating toward blockchain-enabled provenance systems as counterfeit drug risks intensify regulatory scrutiny. IBM Corporation leverages extensive enterprise relationships to anchor large-scale distributed ledger deployments across multinational supply chains. Microsoft Corporation competes through cloud-native blockchain services integrated with Azure IoT platforms for real-time shipment monitoring.
Blockchain supply chain systems employ cryptographically linked distributed ledgers, consensus mechanisms, and smart contract automation to create tamper-evident transaction records across multi-party logistics networks. These systems achieve data immutability through hash-chained blocks validated by network nodes, primarily serving industries requiring end-to-end traceability and automated compliance enforcement. Smart contracts and provenance tracking applications command disproportionate investment as enterprises prioritize automated supplier verification and origin authentication over legacy inventory digitization. Private and consortium network deployments dominate current implementations, though hybrid architectures are gaining traction among organizations balancing transparency requirements with competitive data protection needs.
The EU AI Act and REACH frameworks in Europe, alongside FDA track-and-trace mandates in the United States, are reshaping compliance architectures by mandating granular product lineage documentation that legacy databases cannot support. China's SAMR and NMPA are advancing dual carbon goals through blockchain-verified emissions tracking in cross-border manufacturing supply chains. Stakeholders must evaluate whether their current data infrastructure can support the cryptographic key management and node governance models that regulatory bodies are progressively embedding into supply chain compliance standards.
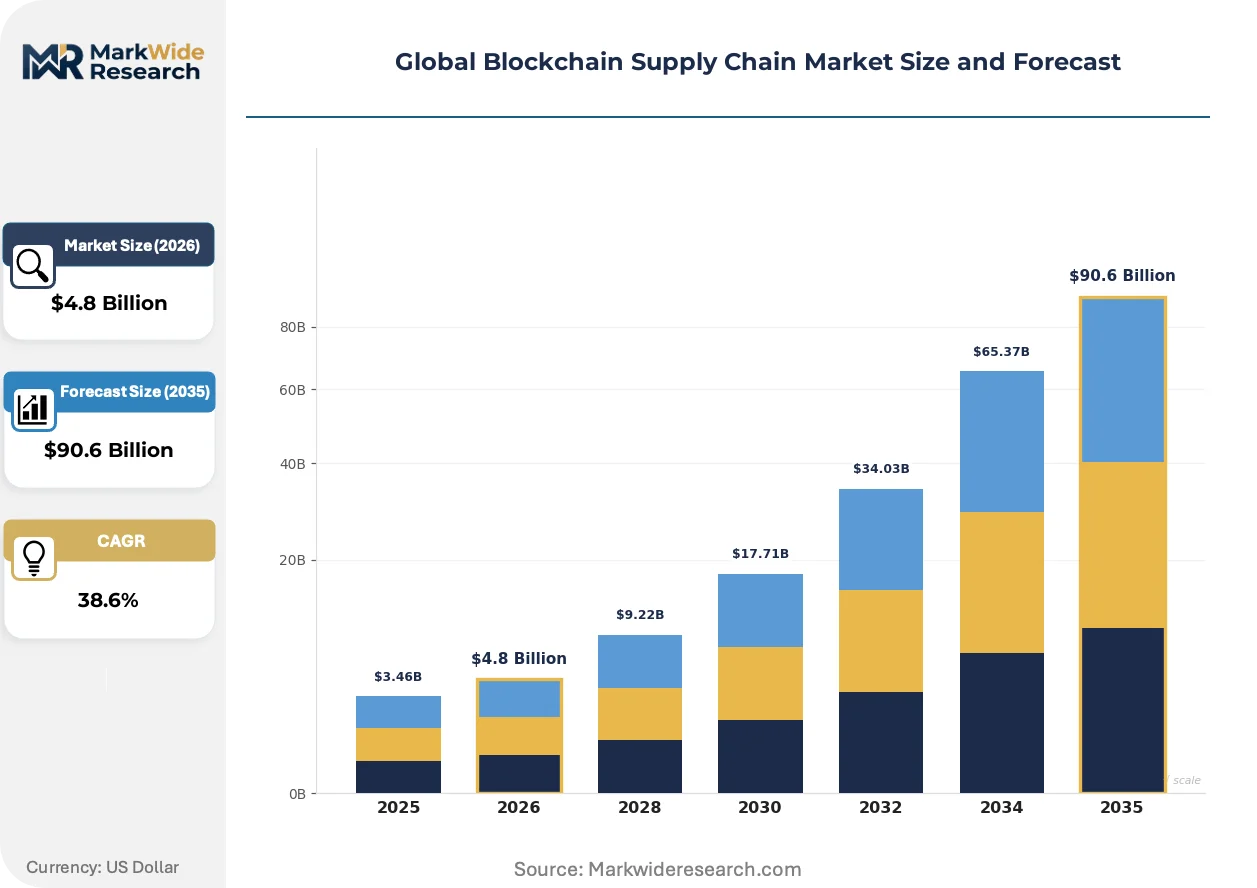
Market Dynamics
Enterprise blockchain deployments are accelerating as pharmaceutical cold-chain mandates and carbon-tracking requirements force supply chain digitization across multinational networks. Regulatory sandboxes in Germany, Singapore, and the United States are concentrating pilot investments while legacy ERP integration costs delay mid-market adoption.
Growth Catalysts
- FDA track-and-trace mandates:The United States pharmaceutical sector faces serialization deadlines that blockchain provenance systems uniquely satisfy. Cold-chain integrity documentation now requires immutable ledger verification for biologics distribution.
- EU AI Act compliance frameworks:European enterprises deploy distributed ledgers to automate audit trails for algorithmic supply chain decisions. REACH chemical documentation requirements further accelerate immutable record-keeping adoption.
- China's dual carbon goals:SAMR and NMPA emissions-tracking mandates drive blockchain-verified carbon accounting across cross-border manufacturing supply chains. Verified emissions data now gates market access for exporters.
Market Restraints
- Enterprise integration costs:Legacy SAP and Oracle ERP systems require expensive middleware development for blockchain node connectivity. Mid-market manufacturers lack capital for multi-year digitization programs.
- Consortium governance fragmentation:Competing standards bodies in the United States and Europe delay interoperable protocol adoption. Network effects fail to materialize when trading partners join incompatible ledgers.
- Quantum computing threat horizon:Cryptographic hash algorithms face theoretical vulnerability to decryption by fault-tolerant quantum systems. Long-term data integrity guarantees require expensive lattice-based encryption upgrades.
Strategic Opportunities
- India PLI scheme alignment:Electronics and pharmaceutical manufacturers can integrate blockchain traceability into production-linked incentive compliance. DGFT export documentation requirements favor immutable origin verification.
- Convergence of IoT sensors and smart contracts:Temperature and humidity oracles now trigger automatic payment settlement upon delivery confirmation. Pharmaceutical 3PL providers pilot autonomous cold-chain financing.
- Brazil ANVISA serialization roadmap:Latin American pharmaceutical track-and-trace mandates create first-mover advantages for provenance platform providers. Local regulatory capacity gaps favor turnkey blockchain-as-a-service offerings.
Industry Challenges
- Distributed systems engineering talent scarcity:Cryptographic key management and Byzantine fault tolerance expertise concentrates in fintech hubs. Industrial supply chain organizations compete for limited smart contract developers.
- Multi-party data governance complexity:Competing confidentiality requirements among consortium members delay network launch. Antitrust counsel in Germany and the United States block information-sharing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain Supply Chain Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $90.6 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Distributed Ledger, Smart Contracts, Identity Management, Asset Tokenization, Payment Processing Application: Provenance Tracking, Inventory Management, Fraud Prevention, Supplier Verification, Shipment Monitoring Industry Vertical: Consumer Goods, Pharmaceuticals, Automotive OEMs, Electronics, Food & Beverage Deployment Mode: Public Network, Private Network, Consortium Network, Hybrid Network |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Amazon Web Services, Inc., Accenture PLC, Huawei, TIBCO Software, Guardtime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain Supply Chain Market Shifts & Advancements
Edge computing architectures are compressing blockchain validation latency for real-time shipment monitoring. Three technology and behavioral shifts are restructuring competitive positioning across pharmaceutical, electronics, and automotive supply chains.
Zero-knowledge proof protocols are miniaturizing the computational footprint required for private transaction verification on public-permissioned hybrid networks. Pharmaceutical manufacturers in Switzerland and Singapore adopt these lightweight cryptographic methods to satisfy competitive data protection requirements while maintaining regulatory transparency. The technology is miniaturizing infrastructure costs for mid-market enterprises previously excluded from consortium participation.
REACH and EU AI Act documentation requirements are mandating granular product lineage records that relational databases cannot auditably maintain. European chemical and medical device manufacturers face dual compliance deadlines that accelerate migration from paper-based chain-of-custody systems. German automotive suppliers lead implementation, embedding cryptographic verification into component passports for circular economy traceability.
Buyer organizations now demand API-first provenance verification rather than periodic certificate exchange. Procurement teams at United States hospital systems and Japanese automotive OEMs integrate direct ledger queries into supplier scorecards. This behavioral shift compresses vendor onboarding cycles from quarters to weeks in Singapore's electronics manufacturing corridor.
Global Blockchain Supply Chain Market Segmentation
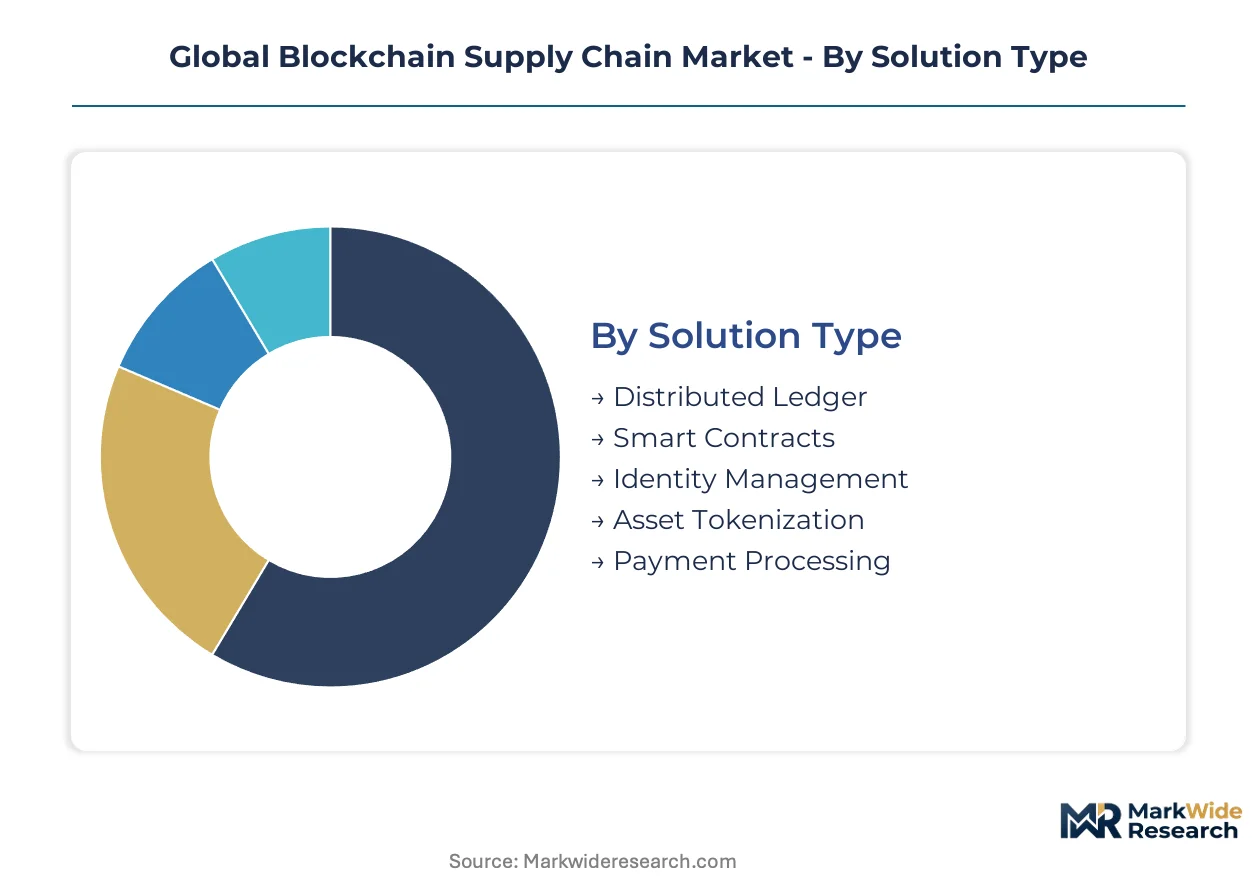
Blockchain supply chain architectures fragment across solution types, deployment modes, and industry verticals with divergent compliance pressures and integration requirements. Pharmaceutical cold-chain mandates and carbon-tracking imperatives reshape segment prioritization across enterprise procurement cycles.
Solution Type:
Distributed ledger infrastructure faces substitution pressure from centralized database vendors offering immutable audit logs without cryptographic overhead. Smart contract platforms compete against traditional EDI networks for automated settlement workflows.
- Distributed Ledger:Hash-chained block structures with Byzantine fault tolerance deliver tamper-evident transaction records across multi-party networks. Pharmaceutical manufacturers in Germany deploy these systems for FDA track-and-trace compliance, though middleware costs constrain mid-market adoption.
- Smart Contracts:Self-executing code automates supplier payments upon IoT-triggered delivery confirmation. Singapore electronics 3PL providers pilot autonomous cold-chain financing, compressing settlement cycles from weeks to hours.
- Identity Management:Decentralized identifiers enable cryptographic supplier verification without centralized credential stores.
- Asset Tokenization:Digital twin representations track component provenance through manufacturing and logistics stages.
- Payment Processing:Cross-border settlement rails reduce correspondent banking delays for international procurement.
Distributed Ledger retains volume leadership; Smart Contracts holds the steepest expansion curve.
Application:
Cost tier differentiation separates enterprise-grade provenance systems from lightweight inventory digitization tools serving mid-market manufacturers.
- Provenance Tracking:End-to-end origin authentication with cryptographic chain-of-custody documentation. EU AI Act and REACH mandates in Europe accelerate adoption among chemical and medical device manufacturers facing dual compliance deadlines.
- Inventory Management:Real-time stock visibility through distributed ledger synchronization with ERP systems. United States automotive suppliers embed these capabilities for just-in-sequence manufacturing coordination.
- Fraud Prevention:Tamper-evident documentation blocks counterfeit product infiltration.
- Supplier Verification:Automated credential validation reduces onboarding cycle times.
- Shipment Monitoring:IoT oracle integration triggers exception alerts for temperature excursions.
Provenance Tracking commands the premium pricing tier; Inventory Management penetrates fastest among cost-sensitive buyers.
Industry Vertical:
Application maturity varies sharply, with Pharmaceuticals and Automotive OEMs leading deployment sophistication while Food & Beverage lags in cryptographic infrastructure investment.
- Pharmaceuticals:Cold-chain integrity documentation with immutable biologics distribution records. FDA serialization mandates and China's NMPA emissions-tracking requirements drive dual-mandate compliance architectures.
- Automotive OEMs:Component passports for circular economy traceability with embedded cryptographic verification. German suppliers lead implementation, pressured by EU Green Deal material sourcing disclosures.
- Consumer Goods:Luxury authentication and anti-counterfeiting documentation.
- Electronics:Conflict mineral provenance and India PLI scheme compliance integration.
- Food & Beverage:Farm-to-fork traceability for contamination response and organic certification.
Pharmaceuticals dominates current deployment value; Electronics is expanding most quickly through Asia-Pacific manufacturing corridors.
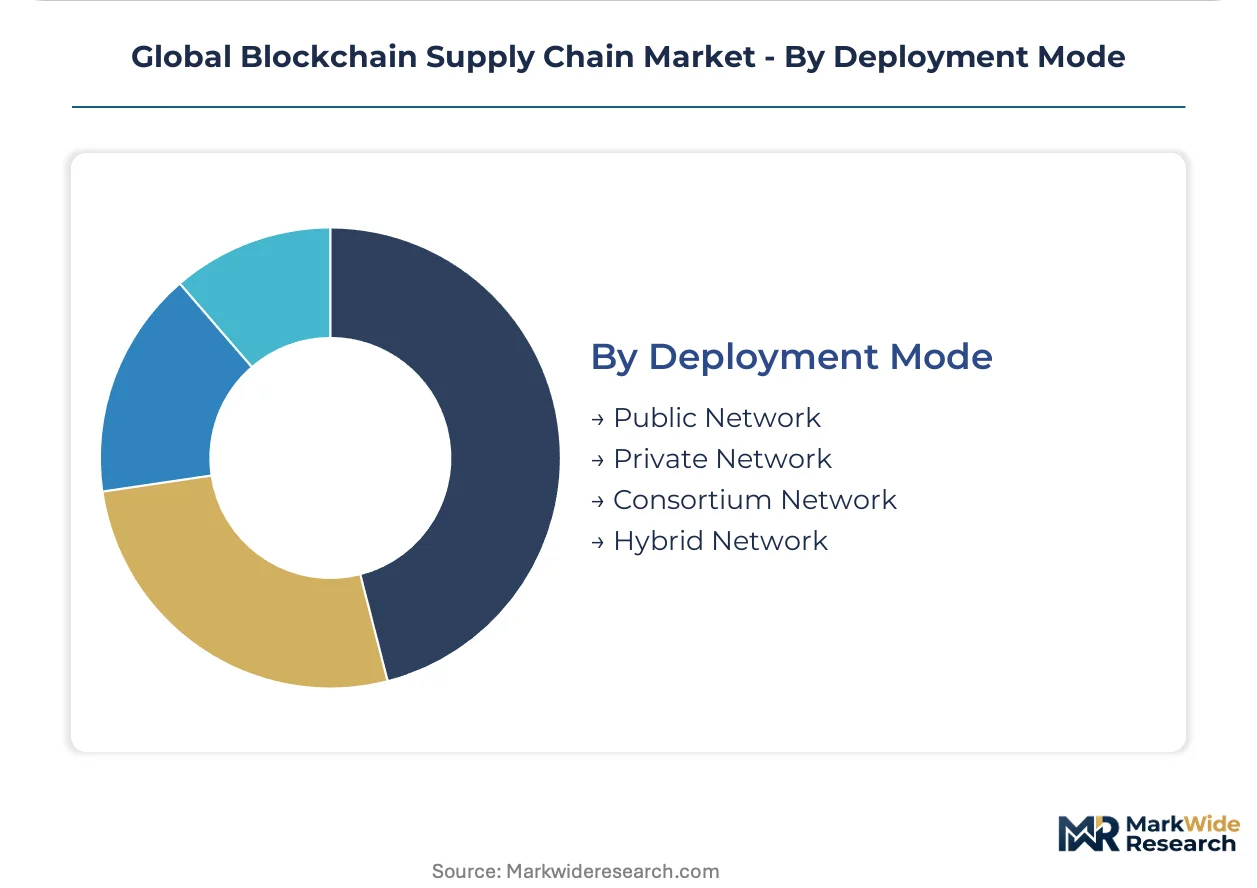
Deployment Mode:
Customer type segmentation separates enterprise consortium participants from mid-market organizations requiring turnkey blockchain-as-a-service offerings.
- Consortium Network:Multi-party governance with shared infrastructure costs and standardized protocols. Singapore and Germany regulatory sandboxes concentrate pilot investments, though competing standards bodies delay interoperable adoption.
- Private Network:Single-organization control over node governance and data residency. United States hospital systems prefer these architectures for HIPAA-sensitive procurement records.
- Public Network:Permissionless validation with native cryptocurrency settlement.
- Hybrid Network:Public-permissioned architectures balancing transparency with competitive data protection.
Consortium Network anchors enterprise adoption; Hybrid Network is gaining share fastest among organizations navigating multi-party confidentiality requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision automotive components and pharmaceutical intermediates to United States hospital systems and Chinese biologics manufacturers, creating cross-border demand for blockchain-verified chain-of-custody documentation.
United States
Hospital procurement networks and pharmaceutical 3PL providers drive enterprise blockchain adoption. FDA track-and-trace mandates for serialization and cold-chain biologics distribution force immutable ledger deployment. The Boston-Cambridge biotech corridor pilots temperature-oracle smart contracts for autonomous settlement.
Germany
Automotive OEMs and chemical manufacturers anchor demand for component passports and REACH compliance documentation. EU AI Act audit trail requirements accelerate migration from paper-based systems. The Stuttgart industrial cluster embeds cryptographic verification into circular economy traceability platforms.
Singapore
Electronics contract manufacturers and pharmaceutical distributors concentrate investment in regulatory sandbox environments. The Monetary Authority of Singapore pilots blockchain-verified trade finance for cross-border procurement. The Tuas biomedical park hosts cold-chain provenance networks serving ASEAN export markets.
China
SAMR emissions-tracking mandates and NMPA pharmaceutical serialization requirements drive dual-compliance architectures. Cross-border manufacturers blockchain-verify carbon data for market access gating. The Yangtze River Delta integrates ledger systems into export documentation for EU-bound electronics.
India
Electronics and pharmaceutical producers align traceability systems with PLI scheme compliance and DGFT export documentation requirements. DGFT origin verification favors immutable ledger adoption for incentive eligibility. The Hyderabad-Visakhapatnam pharmaceutical corridor deploys provenance tracking for FDA-regulated API exports.
Global Blockchain Supply Chain Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and enterprise software domains, creating a tiered structure where scale advantages concentrate in platform vendors while vertical expertise fragments among niche providers. Three archetypes dominate: hyperscale cloud providers with integrated IoT stacks, legacy enterprise software vendors with ERP-embedded ledger modules, and cybersecurity-native specialists with cryptographic infrastructure roots. Competitive moves center on strategic partnerships for consortium network governance and geographic expansion through regulatory sandbox participation.
Within the hyperscale tier, IBM Corporation and Microsoft Corporation anchor enterprise distributed ledger deployments through extensive multinational relationships and cloud-native service integration. Oracle Corporation represents the legacy ERP-embedded archetype, leveraging existing database relationships for middleware-light deployments. These three exemplify the strategic tension between greenfield cloud architectures and brownfield enterprise system integration that shapes procurement decisions across pharmaceutical and automotive verticals.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Amazon Web Services, Inc. |
| Accenture PLC |
| Huawei |
| TIBCO Software |
| Guardtime |
| Others |
Supply & Pricing Matrix
Long-term consortium participation contracts lock pharmaceutical manufacturers and automotive OEMs into predictable infrastructure costs while securing node governance rights across multi-party networks. These arrangements bind German chemical suppliers and Singapore electronics distributors to shared protocol standards, insulating committed participants from spot-market volatility in middleware development services.
Pricing Analysis
Next-generation zero-knowledge proof deployments command substantial premiums over legacy hash-chained ledger implementations that mid-market manufacturers still deploy. Three-tier pricing structure across enterprise consortium, private network, and blockchain-as-a-service levels stratifies according to cryptographic complexity and node governance control. Cost compression in the mid-market tier is intensifying because hyperscale cloud providers bundle IoT integration at marginal incremental pricing. Hospital procurement networks exhibit the sharpest price sensitivity, while pharmaceutical cold-chain operators absorb premium pricing for FDA-compliant provenance documentation.
Supply Chain Analysis
Cryptographic hardware security module manufacturing concentrates in Taiwan, Germany, and the United States, creating single-source vulnerability for enterprises deploying air-gapped key management. Blockchain node infrastructure draws from specialized semiconductor foundries, enterprise server assembly in Mexico, and cooling systems sourced from Japanese precision manufacturers. Tariff exposure runs through cross-border cloud service provisioning between European data residency zones and Asian processing centers. Distribution runs through hyperscale cloud marketplaces and direct enterprise software licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
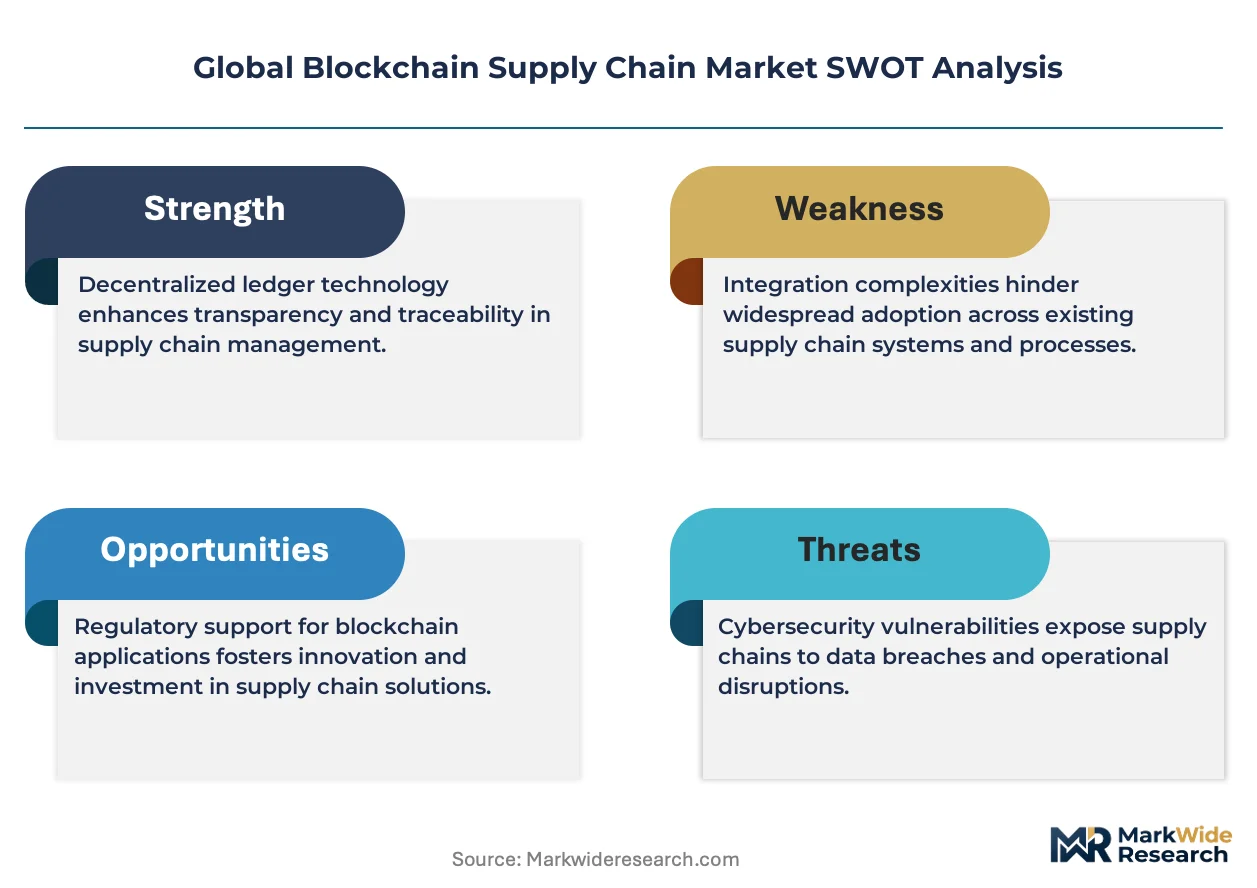
The Global Blockchain Supply Chain Market represents a high-growth disruption as FDA track-and-trace mandates and EU AI Act compliance deadlines force immutable ledger adoption across pharmaceutical and automotive verticals simultaneously.
For Market Incumbents: Shield enterprise relationships by embedding zero-knowledge proof capabilities before mid-market competitors achieve feature parity. Vertical integration into cryptographic hardware security module provisioning addresses the Taiwan concentration risk that threatens long-term node governance contracts. Certification investment in EU AI Act audit trail automation locks out challengers lacking regulatory sandbox experience.
For New Entrants and Emerging Players: Mid-market pharmaceutical manufacturers underserved by legacy ERP-embedded solutions present immediate white-space opportunity. Brazil's ANVISA serialization roadmap offers the most penetrable regulatory entry point for turnkey blockchain-as-a-service offerings. Direct channel partnerships with regional 3PL providers bypass incumbent cloud marketplace gatekeeping.
For Investors and Strategic Acquirers: Capital is best deployed toward cybersecurity-native specialists with cryptographic infrastructure roots rather than generalized cloud platform vendors. The long-term viability window favors acquisition targets possessing Byzantine fault tolerance engineering depth and established consortium governance frameworks. Watch FDA enforcement acceleration on biologics cold-chain documentation as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Proof Integration | Swiss pharmaceutical manufacturers adopt lightweight protocols for competitive data protection compliance. |
| Consortium Network Expansion | Singapore regulatory sandbox participation anchors ASEAN electronics manufacturing corridor adoption. |
| IoT Oracle Partnership | Temperature-triggered smart contracts compress pharmaceutical 3PL settlement cycles dramatically. |
| Regulatory Sandbox Entry | Germany's Stuttgart cluster embeds cryptographic verification into circular economy platforms. |
| Hybrid Architecture Development | United States hospital systems balance HIPAA-sensitive records with transparency mandates. |
Research Methodology
A standing panel of supply chain technology officers, pharmaceutical regulatory affairs leads, automotive procurement directors, and cloud platform engineers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against FDA guidance documents, EMA submission databases, EU AI Act regulatory texts, and hyperscaler blockchain service disclosures. Bottom-up deployment tracking across Germany, Singapore, and the United States triangulated against top-down enterprise software spending estimates.
Consistency checks validated volume and value outputs against external benchmarks from customs trade data, consortium network membership disclosures, and ERP vendor embedded module revenue reporting. The analytical framework modeled solution type, deployment mode, industry vertical, and geographic regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level adoption curves weighted by compliance deadline proximity and middleware integration cost trajectories. Smart contract automation penetration and zero-knowledge proof miniaturization timelines served as primary industry-specific forecast inputs.
Underlying assumptions cover sustained regulatory enforcement of pharmaceutical serialization mandates and stable cryptographic algorithm security horizons, with deviation risk concentrated in quantum computing threat acceleration and consortium governance fragmentation. Practitioners should keep alternative scenarios live as EU AI Act audit trail specifications and China's dual carbon verification protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Industrial Blockchain Technology Market
Blockchain Technology
Global Blockchain IoT Market
Blockchain Technology
Blockchain Identity Management Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Bitcoin Technology Market