
 Blockchain Technology in Energy Market | 2026-2036
Blockchain Technology in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Technology in Energy Market Insights
Enterprise-grade cryptographic verification is reorganizing how energy transactions settle across distributed networks. IBM Corporation leverages its Hyperledger Fabric deployments to anchor utility back-office modernization across North American and European operators. Power Ledger specializes in peer-to-peer trading architectures that compete with traditional retail energy channels in deregulated markets.
Blockchain technology in energy deploys cryptographically linked distributed ledgers with consensus mechanisms to record generation, transmission, and settlement data without centralized intermediaries. The architecture uses immutable hash chains and smart contract automation to verify renewable energy certificates, execute grid-balancing transactions, and authenticate carbon offset claims in real time. Public blockchain protocols dominate experimental deployments where transparency and permissionless access outweigh throughput constraints, while private and consortium variants capture commercial traction among utility consortia requiring controlled participant governance and higher transaction throughput. Grid management and peer-to-peer energy trading applications concentrate current implementation spending, whereas carbon credit tracking represents the fastest-growing segment as compliance markets expand verification requirements.
The EU Green Deal and F-Gas Regulation shape European deployment timelines by mandating traceable emissions accounting that blockchain systems authenticate. In the United States, FERC Order 2222 and state-level net metering reforms create jurisdictional complexity that distributed ledger platforms navigate for aggregated distributed energy resource participation. Stakeholders must weigh interoperability standards against regulatory fragmentation when selecting protocol architectures for multi-territory operations.
Market Dynamics
EU Green Deal mandates for traceable emissions accounting are forcing utilities to replace paper-based renewable certificate registries with cryptographic verification systems that authenticate carbon claims in real time.
Growth Catalysts
- EU Green Deal:Mandatory emissions tracking across European energy grids accelerates enterprise blockchain deployments for carbon offset verification.
- Peer-to-peer architectures:Distributed trading platforms attract utility investment as operators seek operational transparency beyond centralized settlement systems.
- Germany:Municipal utilities pilot distributed ledger systems for renewable certificate verification, concentrating regional demand for cryptographic infrastructure.
Market Restraints
- Throughput constraints:Public blockchain protocols face technical limitations in transaction volume that restrict real-time grid-balancing applications.
- Regulatory fragmentation:FERC Order 2222 and divergent state-level net metering reforms in the United States create jurisdictional complexity for multi-territory platform operators.
- Consortium governance:Private ledger deployments require negotiated participant access rules that slow commercialization timelines among utility collectives.
Strategic Opportunities
- Carbon credit tracking:Expanding compliance markets create the fastest-growing application segment as verification requirements intensify.
- Smart contract automation:Convergence of distributed ledger technology with IoT metering infrastructure enables automated settlement for distributed energy resources.
- Grid-balancing transactions:Aggregated distributed energy resource participation opens new revenue channels for platform providers in deregulated markets.
Industry Challenges
- Cryptographic talent scarcity:Utilities lack internal expertise in consensus mechanism design and zero-knowledge proof implementation for privacy-preserving verification.
- Legacy system integration:Back-office modernization requires bridging decades-old SCADA infrastructure with immutable hash chain architectures.
- Interoperability standards:Competing protocol specifications delay multi-platform settlement compatibility across national grid operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Technology in Energy Market |
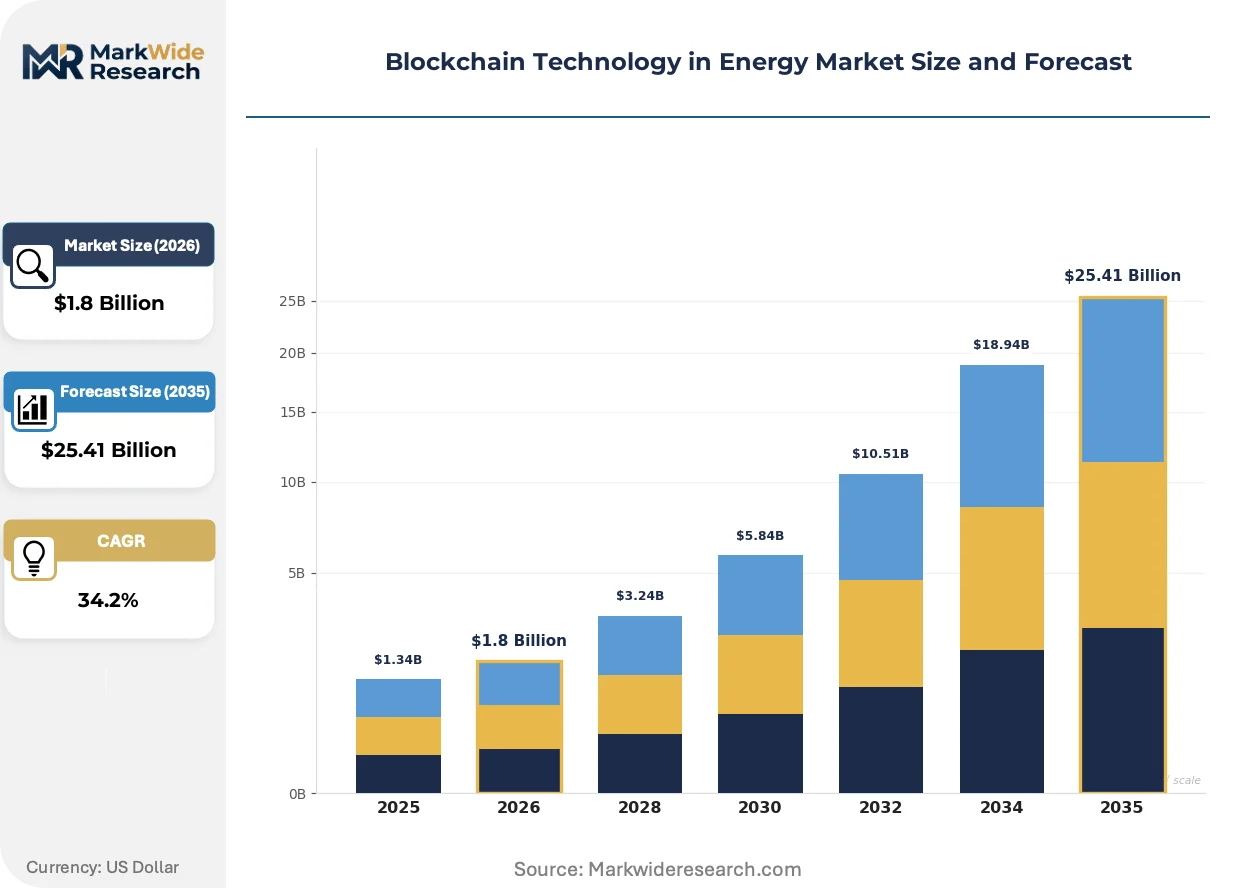
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $25.41 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Contracts, Decentralized Applications, Digital Tokens, Identity Management End User: Utilities, Renewable Energy Producers, Consumers, Blockchain Developers Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Application: Grid Management, Peer-to-Peer Energy Trading, Carbon Credit Tracking, Energy Payments |
| Companies Covered | IBM Corporation, SAP SE, Accenture PLC, LO3 Energy Inc., Power Ledger, Oracle Corporation, Microsoft Corporation, Infosys Limited, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Technology in Energy Market Trends and Innovations
Consensus mechanism design is splitting between energy-intensive proof-of-work and efficient proof-of-stake variants as grid operators weigh transparency against sustainability targets. Protocol selection now determines which use cases utilities can commercialize.
Permissioned Hyperledger Fabric deployments are bifurcating from public Ethereum variants as North American and European operators prioritize controlled governance over permissionless access. Utility consortia favor Fabric's higher transaction throughput for back-office settlement, while experimental microgrid projects test public chain transparency. This split is compressing vendor specialization as platform providers choose architectural camps.
The F-Gas Regulation in Europe mandates granular refrigerant tracking that blockchain systems authenticate through immutable lifecycle records. Industrial cooling operators must document every transfer and disposal event, creating compliance-driven demand for distributed ledger verification. Chemical manufacturers in Germany and France are deploying consortium networks to satisfy these traceability requirements.
Buyer procurement of energy attribute certificates is rotating from annual bulk purchases to continuous automated settlement through smart contract execution. Retail energy platforms in deregulated markets disintermediate traditional certificate brokers by offering real-time origin verification. This pattern is most visible in Australia and the Netherlands where peer-to-peer trading architectures compete with incumbent retail channels.
Blockchain Technology in Energy Market Segmentation
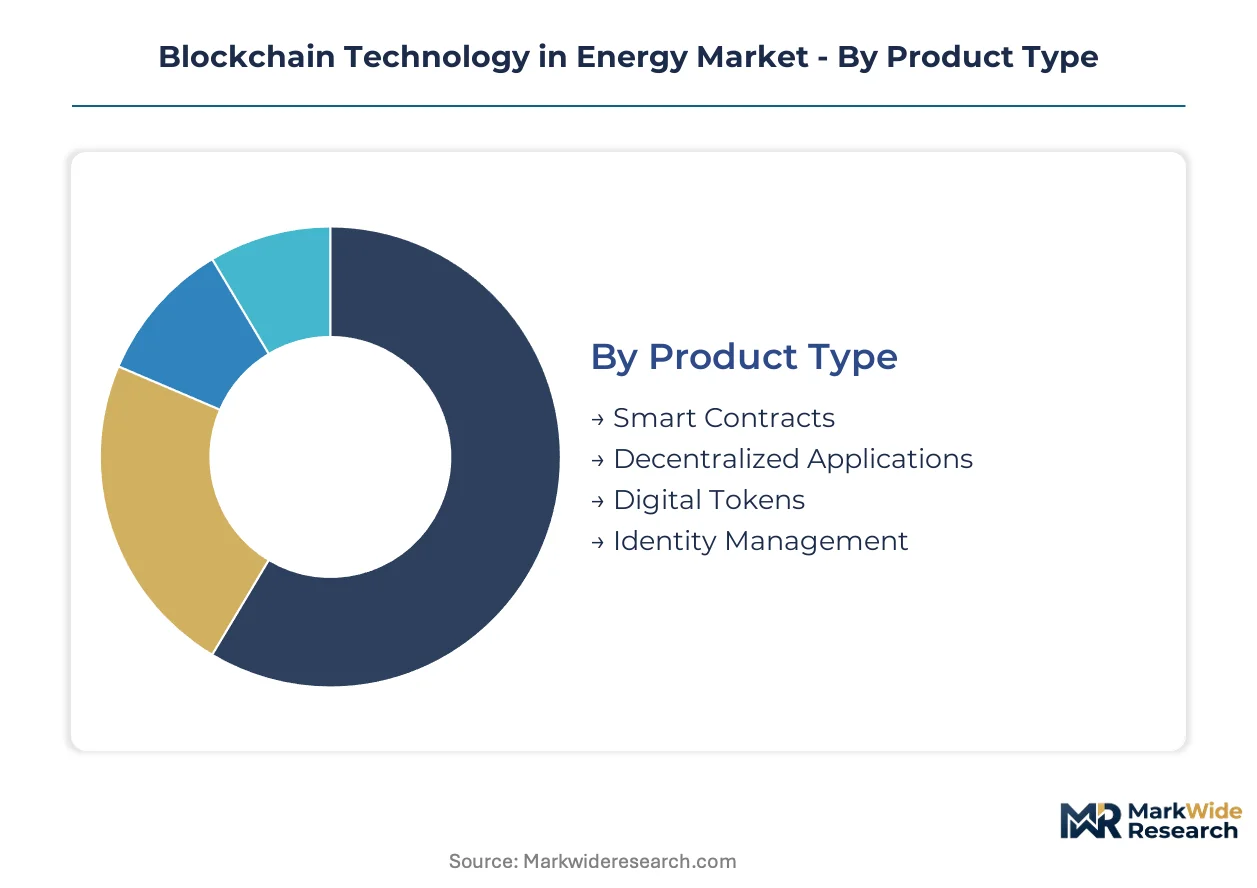
Blockchain deployments in energy markets fragment across four intersecting dimensions that determine architectural fit. Product types govern automation depth, while technology choices trade transparency against throughput. End users and applications together dictate whether platforms serve wholesale grid operations or retail consumer markets.
Product Type:
Smart contracts and digital tokens flow primarily through utility procurement channels, whereas decentralized applications reach renewable producers via developer marketplaces. Identity management solutions concentrate in enterprise direct sales to grid operators.
- Smart Contracts:Self-executing code automates settlement logic for energy transactions without intermediary validation. German municipal utilities deploy these for real-time renewable certificate verification, driven by EU Green Deal compliance timelines. By volume, smart contracts lead. By growth pace, digital tokens are ahead.
- Decentralized Applications:End-user interfaces enable peer-to-peer trading and grid participation through distributed ledger backends. Australian and Dutch retail platforms disintermediate traditional energy brokers using these architectures, attracted by deregulated market access rules.
- Digital Tokens:Cryptographic assets represent energy units or carbon credits for fractional ownership and trading.
- Identity Management:Decentralized identifiers authenticate grid participants and device ownership across distributed networks.
Smart contracts dominate current deployment volumes through utility procurement. Tokenized instruments are expanding most quickly as compliance markets mature.
End User:
Cost tier stratification separates enterprise-grade utility deployments from lightweight consumer-facing tools. Utilities absorb premium pricing for high-throughput private ledgers, while renewable producers and developers favor modular, pay-per-use architectures.
- Utilities:Grid operators require enterprise-scale consensus infrastructure for back-office settlement and regulatory reporting. North American operators under FERC Order 2222 pilot aggregated distributed energy resource participation, navigating state-level jurisdictional fragmentation that complicates platform selection.
- Renewable Energy Producers:Wind and solar farms leverage blockchain for automated certificate issuance and carbon claim authentication. French and German industrial cooling operators deploy these systems to satisfy F-Gas Regulation traceability mandates for refrigerant lifecycle documentation.
- Consumers:Residential prosumers access peer-to-peer trading platforms and real-time origin verification.
- Blockchain Developers:Technical specialists build and maintain consensus infrastructure for energy-specific use cases.
Utilities account for the largest share of current platform spending. Consumer-facing applications are climbing the fastest as retail deregulation spreads.
Technology:
Application requirements determine protocol selection, with public chains serving transparency-heavy carbon tracking and private variants handling settlement-intensive grid balancing. Hybrid architectures emerge where both properties matter.
- Public Blockchain:Permissionless protocols provide complete transparency for experimental microgrid projects and carbon credit registries. Transaction throughput constraints limit real-time grid-balancing deployments, restricting these to non-time-critical verification use cases.
- Private Blockchain:Controlled-access ledgers deliver higher transaction speeds for utility back-office modernization. IBM's Hyperledger Fabric captures commercial traction among North American and European operators prioritizing participant governance over permissionless access.
- Consortium Blockchain:Multi-party governed networks balance transparency with controlled participation for industry collectives.
- Hybrid Blockchain:Architectures combine public verification with private settlement layers for complex multi-stakeholder workflows.
Private deployments dominate commercial revenue. Consortium models are gaining share fastest as utility collectives formalize governance frameworks.
Application:
Customer type and operational maturity segment demand, with wholesale grid applications reaching established utilities and peer-to-peer trading attracting new market entrants in deregulated jurisdictions.
- Grid Management:Real-time balancing and distributed energy resource coordination require sub-second settlement latency. Technical limitations of public protocols push these deployments toward private Hyperledger Fabric implementations among European and North American grid operators.
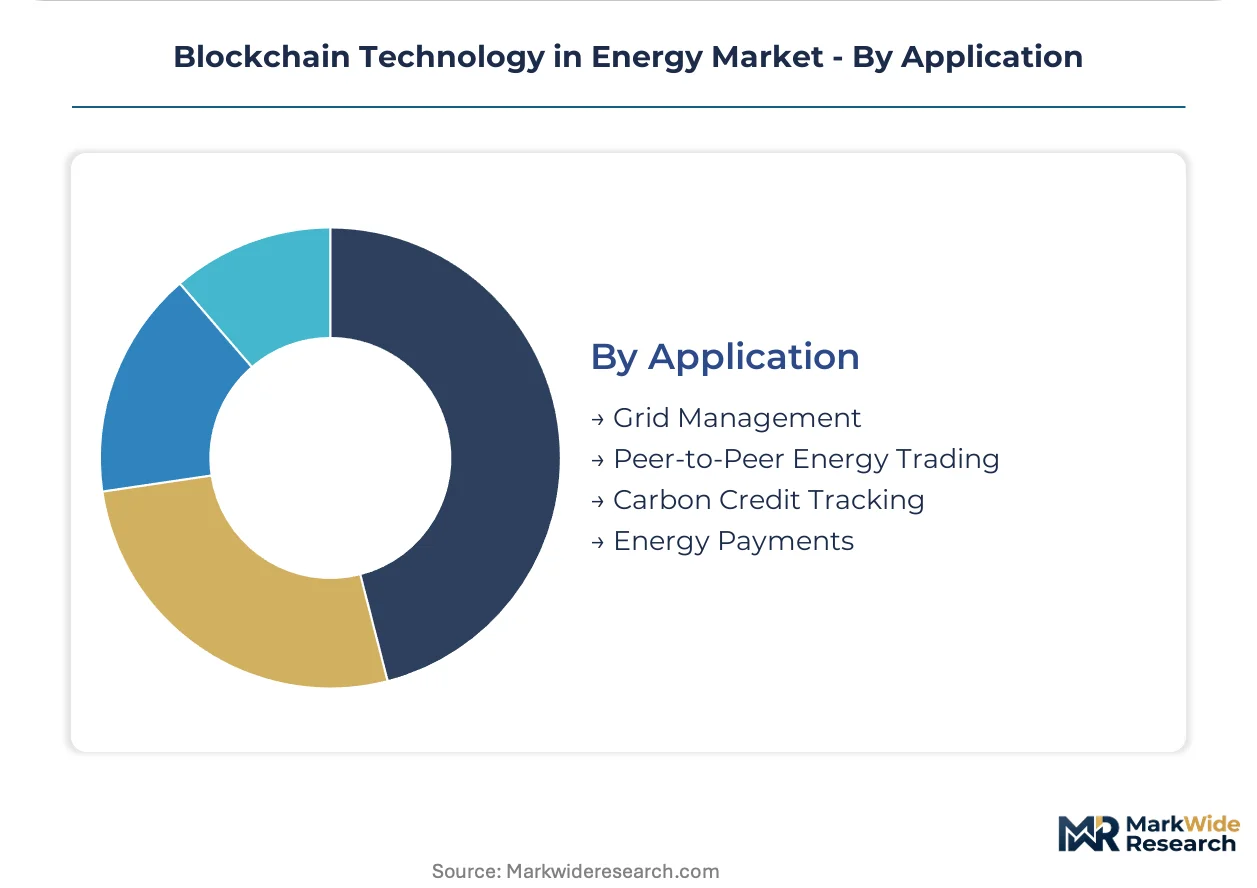
- Carbon Credit Tracking:Immutable lifecycle records authenticate emissions claims for regulatory compliance. The EU Green Deal and F-Gas Regulation mandate granular traceability that blockchain systems satisfy, making this the steepest expansion trajectory across all application segments.
- Peer-to-Peer Energy Trading:Direct consumer-to-consumer transactions bypass traditional retail channels.
- Energy Payments:Cryptographic settlement rails enable automated micropayments for distributed generation.
Grid management commands the largest implementation budgets. Carbon tracking is expanding most quickly as compliance markets harden verification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for blockchain energy infrastructure favor technology-exporting economies with advanced utility digitization programs. Germany and the United States anchor outbound platform licensing, while Australia and the Netherlands concentrate peer-to-peer trading innovation. Import-dependent jurisdictions in Southeast Asia and Latin America source consortium governance frameworks from European vendors.
United States
FERC Order 2222 and divergent state-level net metering reforms create jurisdictional complexity that distributed ledger platforms navigate for aggregated distributed energy resource participation. The Federal Energy Regulatory Commission's market access rules push grid operators toward cryptographic settlement systems. Texas and California utilities pilot private Hyperledger Fabric deployments for wholesale market modernization.
Germany
Municipal utilities pilot distributed ledger systems for renewable certificate verification, concentrating regional demand for cryptographic infrastructure. The EU Green Deal and F-Gas Regulation mandate granular emissions traceability that blockchain systems authenticate. Industrial cooling operators in Baden-Württemberg deploy consortium networks to satisfy refrigerant lifecycle documentation requirements.
Australia
Retail energy platforms in deregulated markets disintermediate traditional certificate brokers by offering real-time origin verification through smart contract execution. The national electricity market's open access rules enable peer-to-peer trading architectures to compete with incumbent retail channels. Melbourne and Sydney host concentrated developer activity for consumer-facing distributed applications.
Netherlands
Buyer procurement of energy attribute certificates rotates from annual bulk purchases to continuous automated settlement. The country's advanced metering infrastructure and retail deregulation create favorable conditions for blockchain-based origin tracking. Amsterdam's energy exchange pilots cryptographic verification for renewable power imports from North Sea offshore wind.
China
Dual carbon goals and provincial emissions trading pilots drive enterprise blockchain deployments for carbon offset verification. The Ministry of Ecology and Environment mandates traceable accounting for compliance market participants. Yangtze River Delta utilities test hybrid architectures combining public verification with private settlement layers for multi-stakeholder workflows.
Blockchain Technology in Energy Market Competitive Landscape
Concentration sits with technology conglomerates offering enterprise-grade consensus infrastructure. The vendor base splits between diversified IT platforms and specialized energy-focused developers. Strategic archetypes include: full-stack enterprise providers with existing utility relationships, and niche protocol specialists targeting peer-to-peer trading architectures. Competitive moves center on consortium governance partnerships and smart contract interoperability licensing.
Within the enterprise infrastructure tier, IBM Corporation and Microsoft Corporation anchor platform provision for North American and European grid operators. SAP SE represents the European enterprise software archetype with utility back-office integration capabilities. Power Ledger exemplifies the specialized peer-to-peer trading developer camp with deregulated market focus. LO3 Energy Inc. occupies a position among early-mover distributed energy resource platform builders.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Accenture PLC |
| LO3 Energy Inc. |
| Power Ledger |
| Oracle Corporation |
| Microsoft Corporation |
| Infosys Limited |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Permissioned Hyperledger Fabric deployments replacing public Ethereum variants as the consensus infrastructure of choice simultaneously shift supply geography toward IBM-dominated North American vendor networks and compress pricing premiums for controlled-governance solutions. This substitution dynamic redirects procurement budgets away from experimental public-chain pilots toward enterprise-grade consortium architectures with negotiated throughput guarantees.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in blockchain energy deployments. Premium tiers command certification-grade guarantees for EU Green Deal compliance, while standard offerings target municipal utilities with modular smart contract libraries. Pricing pressure stems from open-source protocol commoditization eroding proprietary platform margins. Renewable producers exhibit highest price sensitivity due to thin project margins, whereas integrated utilities absorb premium pricing for regulatory risk mitigation.
Supply Chain Analysis
Inventory lead times for cryptographic hardware security modules stretch 12-16 weeks, constraining rapid scaling of validator node deployments. Supply concentrates in Germany, the United States, and Australia for enterprise consensus infrastructure, with specialized semiconductor components drawing from Taiwan and South Korea fabrication. Raw material dependencies span silicon wafers, secure enclave processors, and specialized cooling systems for data center operations. Tariff exposure on Chinese-manufactured IoT metering hardware creates supply chain vulnerability. Distribution runs through direct enterprise sales teams for utility consortia and developer marketplaces for decentralized application components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform providers face substitution pressure from open-source protocol commoditization that erodes proprietary licensing revenue. Defense requires strategic consolidation around defensible integration layers rather than consensus mechanism competition.
For Market Incumbents: Consolidate around Hyperledger Fabric governance partnerships that lock in utility consortia through customized compliance modules for EU Green Deal and F-Gas Regulation mandates. Deepen backward integration into IoT metering hardware to capture settlement infrastructure margins threatened by specialized device manufacturers. Prioritize certification investment for carbon credit tracking workflows where verification requirements intensify fastest.
For New Entrants and Emerging Players: Lead with carbon credit tracking automation as the most penetrable application segment, where compliance market expansion outpaces incumbent platform capacity. Target Australian and Dutch retail energy markets with peer-to-peer trading architectures that exploit deregulated access rules and advanced metering infrastructure density. Deploy through API-first go-to-market models that embed into existing utility billing systems rather than displacing core settlement platforms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed enterprise software vendors holding stranded utility relationships but lacking blockchain-native technical capabilities. Long-term viability hinges on convergence with IoT infrastructure and automated settlement workflows rather than standalone ledger provision. Watch FERC Order 2222 implementation timelines as the signal for aggregated distributed energy resource participation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Governance Formalization | Structured participant access rules accelerate commercialization among German municipal utility collectives. |
| Smart Contract Interoperability Licensing | Cross-platform settlement compatibility unlocks multi-territory operations under fragmented regulatory frameworks. |
| IoT Metering Infrastructure Integration | Automated settlement convergence enables real-time distributed energy resource participation in deregulated markets. |
| Carbon Credit Tracking Specialization | EU Green Deal and F-Gas Regulation compliance mandates drive fastest-growing application segment demand. |
| Zero-Knowledge Proof Implementation | Privacy-preserving verification addresses cryptographic talent scarcity in utility back-office operations. |
Research Methodology
Cross-validation between primary utility executive interviews and secondary FERC filings anchors the qualitative findings on regulatory fragmentation impacts. Utility planning officers, IPP project developers, EPC contractors, and grid operators provided deployment timeline and procurement intention data. Secondary sources include EIA generation statistics, IEA technology roadmaps, EU Green Deal implementation documents, and project development databases tracking pilot deployments. Bottom-up platform revenue estimates triangulate against top-down addressable market calculations across the analysis window.
Sensitivity analysis around consensus mechanism adoption rates and compliance market expansion trajectories shapes the analytical framework. Segmentation dimensions modeled include technology type, application use case, end-user category, and regional regulatory cluster. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion patterns. Key forecast inputs span EU Green Deal implementation pace and FERC Order 2222 state-level adoption variance.
Forecasts assume regulatory continuity in EU emissions trading and US federal market access regimes; material policy shifts would require re-modeling. Technology disruption from quantum-resistant cryptography or alternative distributed ledger architectures presents revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Global Blockchain IoT Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Tokenization Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Blockchain Technology Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Global Blockchain Software Market