
 Global Blockchain IoT Market | 2026-2036
Global Blockchain IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain IoT Market Foresight
A shortage of distributed systems engineers is reorganizing how vendors build blockchain IoT platforms, stretching development timelines and inflating compensation costs across the sector. IBM Corporation leverages its enterprise blockchain expertise to anchor large-scale supply chain deployments for Fortune 500 manufacturers. Amazon.com, Inc. sustains cloud-native IoT dominance through AWS IoT Core integrations with managed ledger services. Intel Corporation differentiates at the silicon layer, embedding hardware-based security modules that protect edge device identities.
Blockchain IoT fuses distributed ledger consensus mechanisms with sensor networks to create tamper-evident data pipelines between physical assets and digital records. The architecture typically employs lightweight proof-of-authority or Byzantine fault-tolerant protocols optimized for resource-constrained devices with sub-watt power budgets and intermittent connectivity. Supply chain traceability solutions occupy the largest value pool today, as pharmaceutical and food safety mandates require immutable provenance logging from origin to endpoint. Smart contracts are accelerating fastest among energy management use cases, where automated grid settlements between distributed solar assets and utility operators eliminate reconciliation delays. Data monetization remains nascent but carries the highest margin potential, enabling device owners to sell verified telemetry streams to insurers and predictive maintenance platforms.
The EU AI Act and GDPR impose strict data sovereignty and algorithmic transparency requirements that reshape how European deployments handle cross-border device telemetry. The U.S. FCC and NIST frameworks influence spectrum allocation and cybersecurity baseline standards for connected infrastructure, while Singapore's IMDA guidelines promote interoperable digital trust architectures across ASEAN trade corridors. Stakeholders must monitor how diverging national data localization statutes fragment platform architectures and inflate compliance engineering costs.
Market Dynamics
A scarcity of distributed systems engineers is compressing development timelines and inflating compensation costs across blockchain IoT platform vendors, forcing architectural trade-offs between decentralization and delivery speed.
Growth Catalysts
- EU AI Act Compliance:Pharmaceutical and food safety mandates under the EU AI Act and GDPR are accelerating immutable provenance logging requirements across European supply chains.
- Hardware Security Modules:Silicon-layer security integration at the edge is enabling tamper-evident device identity verification for resource-constrained sensors.
- Singapore IMDA Guidelines:ASEAN trade corridor interoperability standards are driving digital trust architecture investments among logistics providers headquartered in Singapore.
Market Restraints
- Engineering Talent Concentration:Distributed systems expertise clusters in Germany, Singapore, and the United States, creating recruitment bottlenecks for vendors elsewhere.
- Cross-Border Data Friction:Diverging national data localization statutes fragment platform architectures and inflate compliance engineering costs for multi-territory deployments.
- Edge Power Constraints:Sub-watt power budgets and intermittent connectivity limit consensus protocol options, excluding proof-of-work mechanisms from most IoT sensor networks.
Strategic Opportunities
- Energy Grid Automation:Automated settlement contracts between distributed solar assets and utility operators are displacing manual reconciliation processes in deregulated electricity markets.
- Verified Telemetry Monetization:Device owners in Germany and Singapore are piloting sales of authenticated sensor streams to insurers and predictive maintenance platforms.
- Smart City Infrastructure:Municipal investments in tamper-evident public asset tracking are creating demand for lightweight Byzantine fault-tolerant protocols in urban deployments.
Industry Challenges
- Legacy System Integration:Enterprise ERP and WMS platforms lack native ledger compatibility, requiring expensive middleware development for supply chain traceability deployments.
- Consensus Latency Trade-offs:Proof-of-authority protocols sacrifice decentralization for transaction speed, creating governance disputes among consortium participants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain IoT Market |
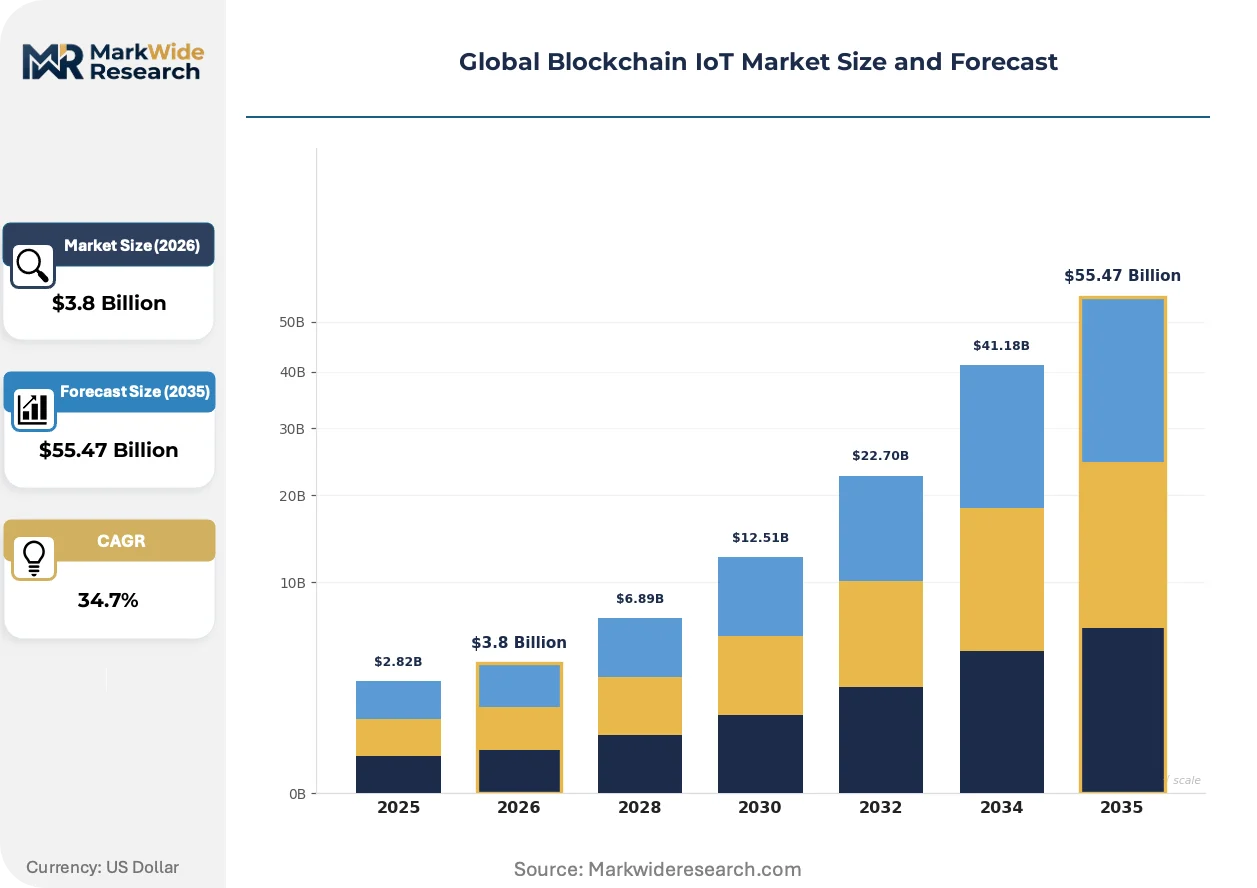
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $55.47 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises Solution Offering: Identity Management, Supply Chain Traceability, Smart Contracts, Data Monetization, Asset Tracking Use Case: Smart Cities, Connected Vehicles, Energy Management, Agriculture Automation, Asset Monitoring End User: Telecommunications, Manufacturing, Logistics Providers, Utility Operators, Government Agencies |
| Companies Covered | IBM Corporation, Amazon.com, Inc., Intel Corporation, Microsoft Corporation, Cisco Systems, Inc., The Linux Foundation, IoTeX, KrypC Technologies, R3 LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain IoT Market Shifts & Advancements
Architectural choices around consensus mechanisms and data sovereignty are fragmenting platform roadmaps, with vendors diverging toward either permissioned enterprise ledgers or open interoperability standards.
Lightweight Byzantine fault-tolerant protocols are fragmenting the edge computing layer, replacing heavier consensus mechanisms in sensor networks with sub-watt power budgets. Pharmaceutical cold-chain monitors and agricultural soil sensors are adopting these protocols fastest. The shift is fragmenting vendor specialization, separating silicon-optimized protocol designers from cloud-native platform builders.
The EU AI Act's algorithmic transparency requirements are mandating explainable audit trails for automated decision systems processing device telemetry. European deployments must now implement decentralized data architectures that prevent cross-border inference model training without explicit consent. Germany's federal data protection authority is interpreting these provisions most strictly, forcing platform redesigns for manufacturers serving EU markets.
Buyers are unbundling hardware procurement from ongoing attestation services, treating device identity verification as a subscription rather than a capital expenditure. Industrial asset operators in Singapore are leading this shift, demanding per-transaction pricing for ledger notarization rather than perpetual licenses. The model is compressing vendor revenue recognition timelines while expanding total contract values for high-frequency telemetry use cases.
Global Blockchain IoT Market Segmentation
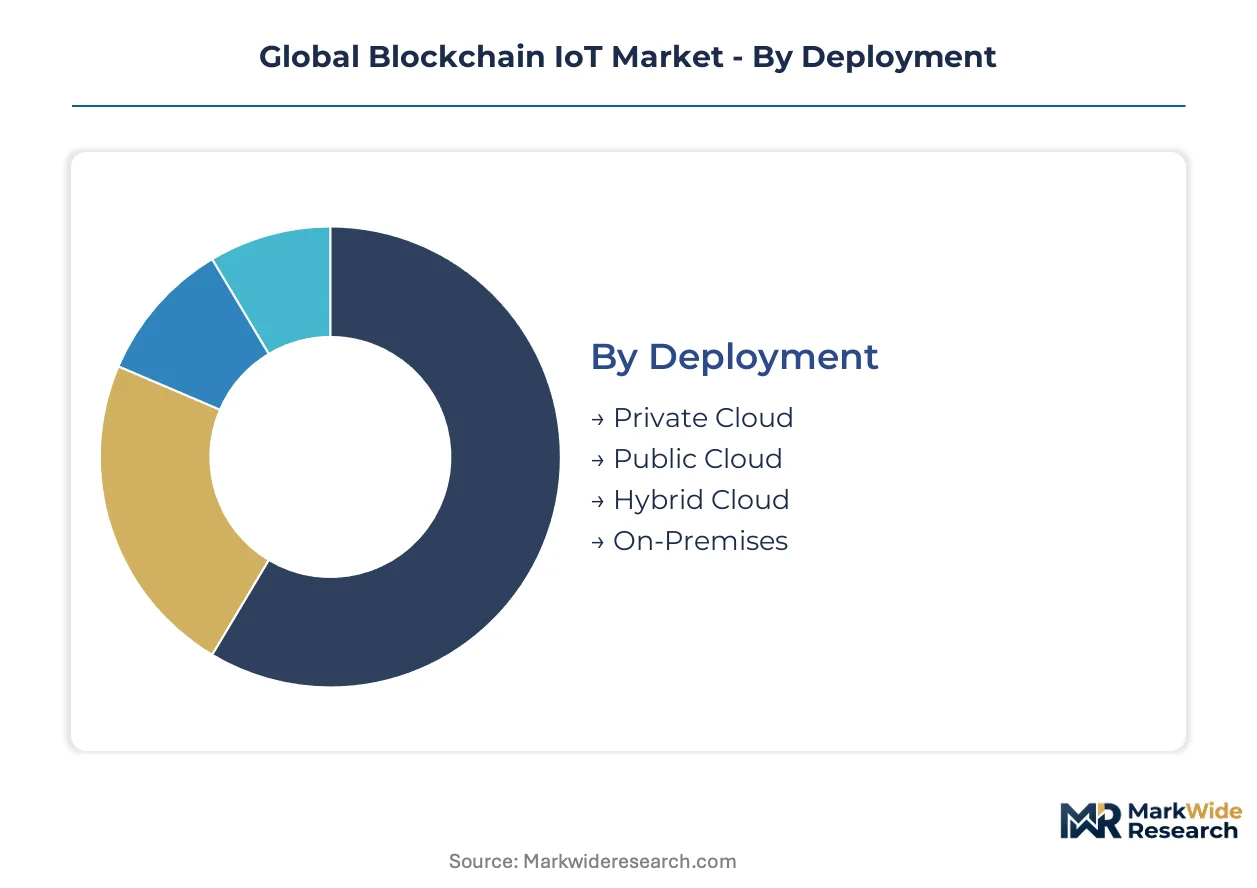
Segmentation in blockchain IoT reveals how architectural choices around data sovereignty, consensus latency, and hardware constraints split demand across deployment models and solution types. Each dimension carries distinct substitution pressures from conventional cloud databases, centralized ERP systems, and legacy SCADA infrastructure.
Deployment:
Substitution pressure from traditional cloud architectures weighs heaviest on public deployments, while sovereign data requirements protect private and on-premises alternatives from displacement.
- Private Cloud:Dedicated infrastructure environments isolate ledger nodes within single-tenant boundaries, satisfying GDPR data localization mandates for German automotive manufacturers and French pharmaceutical distributors. Demand concentrates among EU-regulated enterprises where cross-border data transfer restrictions eliminate public cloud alternatives.
- Public Cloud:Multi-tenant managed ledger services from hyperscale providers deliver elastic compute for proof-of-concept deployments and startup telemetry platforms. Singapore-based logistics aggregators favor this model for rapid ASEAN corridor prototyping before compliance-driven migration to hybrid architectures.
- Hybrid Cloud:Split architectures anchor sensitive consensus operations on-premises while offloading analytics to elastic cloud tiers. US utility operators deploying grid settlement systems adopt this pattern to satisfy NERC CIP cybersecurity standards without sacrificing computational scalability.
- On-Premises:Fully air-gapped ledger deployments serve defense contractors and critical infrastructure operators in Switzerland and Israel with zero external connectivity requirements. Compact edge server clusters run lightweight Byzantine fault-tolerant protocols for submarine cable landing stations and nuclear facility sensor networks.
Private cloud retains volume leadership among regulated European manufacturers; public cloud holds the steepest expansion curve among Asia-Pacific digital-native entrants.
Solution Offering:
Margin concentration follows data uniqueness—solutions generating irreplaceable attestations command premium pricing against commodity identity or tracking layers.
- Supply Chain Traceability:Immutable provenance logging from origin to endpoint satisfies EU AI Act algorithmic transparency requirements and FDA food safety mandates. German cold-chain pharmaceutical distributors and Dutch flower auction cooperatives drive deployment volume for multi-party consortium ledgers with automated compliance reporting.
- Data Monetization:Verified telemetry marketplaces enable device owners to sell authenticated sensor streams to insurers and predictive maintenance platforms under per-transaction licensing. Early pilots in Singapore industrial estates and Stuttgart manufacturing clusters demonstrate the highest margin potential across all solution categories.
- Identity Management:Hardware-anchored device credentials using embedded secure elements protect edge sensor networks against spoofing attacks. Intel SGX and ARM TrustZone implementations dominate silicon-layer deployments for US critical infrastructure and Japanese automotive telematics.
- Smart Contracts:Automated settlement logic eliminates reconciliation delays in energy trading and logistics escrow applications. Australian distributed solar aggregators and Texas grid operators deploy these most aggressively for real-time kilowatt-hour pricing and carbon credit verification.
- Asset Tracking:Continuous location and condition monitoring for high-value equipment leverages combined GPS, accelerometer, and environmental sensor fusion. Mining operators in Chile and construction fleets in the UAE represent concentrated demand for tamper-evident custody chains.
Supply chain traceability captures the largest revenue pool today; data monetization is climbing the fastest toward mainstream adoption.
Use Case:
Application maturity diverges sharply—energy and asset monitoring deploy at production scale while agriculture and connected vehicles remain pilot-constrained by hardware cost and connectivity gaps.
- Energy Management:Automated grid settlements between distributed solar assets, battery storage systems, and utility operators displace manual reconciliation processes. Germany's EEX and California's CAISO markets drive protocol standardization for sub-second settlement finality.
- Asset Monitoring:Continuous condition-based maintenance for industrial equipment generates immutable audit trails for warranty claims and insurance underwriting. Singapore's port authority and Rotterdam's container terminals anchor maritime deployment volume.
- Smart Cities:Tamper-evident public infrastructure tracking spans street lighting, waste management, and traffic signal networks. Barcelona and Dubai municipal investments prioritize lightweight proof-of-authority protocols for sub-watt sensor power budgets.
- Connected Vehicles:Vehicle-to-vehicle and vehicle-to-infrastructure attestation for autonomous driving safety remains experimental. NHTSA regulatory uncertainty and liability fragmentation stall US deployment beyond controlled geofenced zones.
- Agriculture Automation:Soil moisture, crop health, and supply chain provenance tracking for organic certification deploy in fragmented pilot configurations. Dutch greenhouse cooperatives and Israeli drip-irrigation technology providers lead limited commercial rollout.
Asset monitoring sustains the broadest cross-industry penetration; energy management is gaining share fastest as electricity market deregulation spreads.
End User:
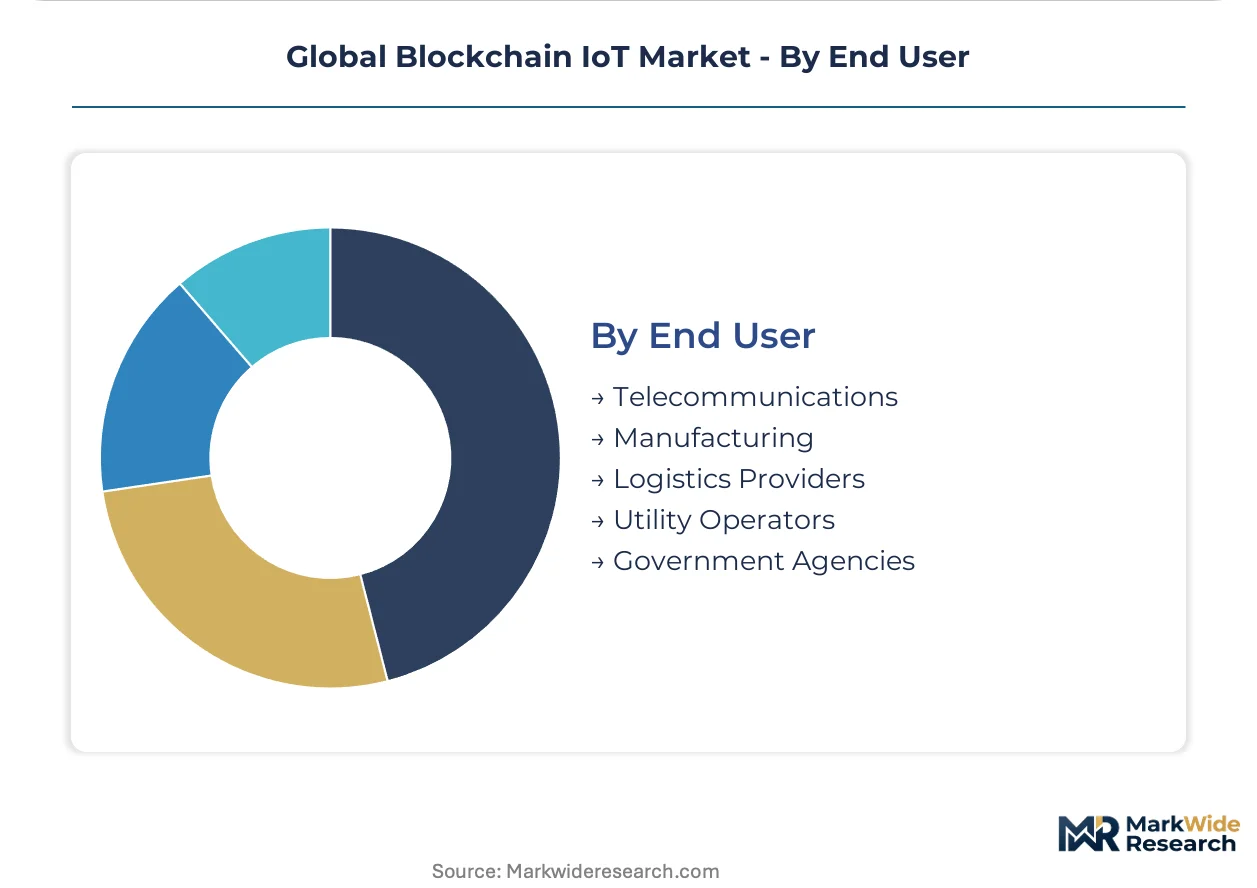
Procurement authority and technical sophistication split the customer base—telecommunications and manufacturing wield large capital budgets while government agencies lag in implementation velocity.
- Logistics Providers:Multi-modal freight tracking across maritime, air, and land corridors demands interoperable ledger standards for customs clearance and insurance verification. DHL and Maersk consortium deployments anchor enterprise-scale investment in the segment.
- Manufacturing:Shop-floor-to-warehouse traceability for quality control and recall management integrates with existing MES and ERP systems through expensive middleware layers. German automotive OEMs and Japanese electronics assemblers drive integration spending.
- Telecommunications:5G network slicing and edge computing infrastructure providers embed ledger nodes for subscriber identity and service-level agreement verification. South Korean operators and Nordic tower companies deploy most aggressively for Open RAN interoperability.
- Utility Operators:Grid modernization investments pair distributed energy resource management with automated settlement systems. US municipal utilities and UK distribution network operators concentrate procurement for net-metering and peer-to-peer trading pilots.
- Government Agencies:Public sector procurement cycles and cybersecurity certification requirements stretch deployment timelines. Estonia's digital residency infrastructure and Singapore's IMDA sandbox programs represent exceptions with accelerated procurement pathways.
Manufacturing commands the largest absolute spending; logistics providers are expanding most quickly as supply chain resilience investments intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany treats blockchain IoT primarily as a compliance infrastructure layer, whereas Singapore and the United States emphasize revenue-generating data monetization and grid automation respectively. This consumption-mix differential shapes divergent procurement priorities across major deployment zones.
Germany
Federal data protection authority interpretations of the EU AI Act force platform redesigns for algorithmic transparency in automated decision systems. GDPR cross-border data transfer restrictions eliminate public cloud alternatives for automotive manufacturers. Stuttgart manufacturing clusters and Bavarian pharmaceutical distributors drive private cloud ledger investments for immutable provenance logging.
Singapore
IMDA guidelines promote interoperable digital trust architectures across ASEAN trade corridors, accelerating logistics provider adoption. Per-transaction pricing models for ledger notarization are compressing vendor revenue recognition timelines. Industrial estates in Jurong and port authority deployments anchor maritime blockchain IoT volume for customs clearance automation.
United States
NIST cybersecurity baseline standards and FCC spectrum allocation frameworks shape connected infrastructure deployment patterns. NERC CIP requirements push utility operators toward hybrid cloud architectures for grid settlement systems. Texas grid operators and California distributed solar aggregators deploy automated smart contract settlements most aggressively.
United Kingdom
Post-Brexit data adequacy negotiations with the EU create uncertainty for cross-border device telemetry flows. The Information Commissioner's Office enforces GDPR-aligned accountability mechanisms for automated processing of sensor data. London-based financial services firms pilot verified telemetry marketplaces for insurance underwriting applications.
Japan
METI industrial digitalization programs subsidize edge computing infrastructure for manufacturing quality control. JIS standards for IoT device security influence hardware procurement specifications across automotive telematics. Toyota City and Nagoya industrial corridors concentrate demand for silicon-layer identity verification in connected supply chains.
Global Blockchain IoT Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers and enterprise technology conglomerates commanding consortium deployment opportunities while protocol-native startups capture edge-optimized niches. The structure rewards vertical integration across hardware security, managed ledger services, and industry-specific compliance expertise. Three archetypes dominate: cloud-native platform builders, silicon-layer security integrators, and open-source protocol stewards. Competitive intensity concentrates on strategic partnerships with logistics operators and utility regulators, plus middleware development capabilities for ERP system integration.
Within the enterprise technology tier, IBM Corporation exemplifies the vertically integrated archetype through its established blockchain consulting practice. Amazon.com, Inc. occupies a position as the cloud-native platform anchor, while Intel Corporation represents silicon-layer security specialization. These three entities collectively illustrate how vendor positioning stratifies between infrastructure ownership and protocol governance roles.
| Leading Market Players |
|---|
| IBM Corporation |
| Amazon.com, Inc. |
| Intel Corporation |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| The Linux Foundation |
| IoTeX |
| KrypC Technologies |
| R3 LLC |
| Others |
Supply & Pricing Matrix
Project-based consortium ledger contracts lock in multi-year middleware development commitments for German automotive manufacturers, anchoring price visibility while constraining vendor flexibility to absorb silicon cost swings. These structures tether platform providers to fixed deliverables across proof-of-authority protocol deployments, compressing margin buffers when secure element procurement costs fluctuate.
Pricing Analysis
Long-term offtake agreements dominate enterprise blockchain IoT procurement, with German pharmaceutical distributors and Singapore port operators locking in five-year middleware development contracts. Price differentiation hinges on GDPR certification tier and hardware security module integration depth, with EU AI Act-compliant deployments commanding substantial premiums over baseline traceability layers. Cost compression in public cloud managed ledger tiers is intensifying because hyperscale providers are absorbing consensus infrastructure overhead to capture logistics provider volume. Startup digital-native entrants in ASEAN corridors exhibit the highest price sensitivity, while Swiss defense contractors and Israeli critical infrastructure operators show minimal elasticity for air-gapped on-premises deployments.
Supply Chain Analysis
Port congestion on the Rotterdam-Singapore maritime corridor and container availability constraints on Asia-Europe trade lanes are inflating lead times for edge server clusters and hardware security modules. Silicon-layer component manufacturing concentrates in Taiwan, South Korea, and the United States, with Intel SGX and ARM TrustZone implementations drawing from specialized foundry capacity. Supply chain risk centers on single-source vulnerability for Byzantine fault-tolerant protocol-optimized chipsets. Distribution runs through hyperscale cloud provider marketplaces for public deployments and direct OEM relationships for sovereign private cloud installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform architecture fragmentation across consensus mechanism choices and data sovereignty requirements is carving out specialist niches for protocol-native vendors unburdened by legacy ERP integration obligations.
For Market Incumbents: Shield consortium leadership positions by deepening backward integration into hardware security module design partnerships, neutralizing silicon supply bottlenecks that threaten delivery timelines. Invest aggressively in GDPR and EU AI Act certification maintenance as regulatory divergence between German federal interpretations and Singapore IMDA guidelines fragments compliance engineering requirements. For New Entrants and Emerging Players: Middleware integration services for legacy MES and ERP systems represent a service-layer gap where incumbents under-serve, creating entry points for boutique systems integrators with automotive and pharmaceutical vertical expertise. Target German manufacturing clusters and Dutch agricultural cooperatives with per-transaction pricing models that compress incumbent revenue recognition timelines while expanding total contract values for high-frequency telemetry use cases. For Investors and Strategic Acquirers: Protocol-native startups with lightweight Byzantine fault-tolerant implementations and edge-optimized power budgets offer the most compelling acquisition target archetype for filling capability gaps in hyperscale cloud portfolios. Monitor NHTSA regulatory clarity on vehicle-to-infrastructure attestation as the critical inflection signal for connected vehicle segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Development Partnership | Bridges legacy ERP systems with consortium ledgers for German automotive OEMs. |
| Hardware Security Integration | Embeds Intel SGX modules into edge sensors for US critical infrastructure deployments. |
| Per-Transaction Pricing Launch | Compresses revenue recognition timelines while expanding contract values in Singapore logistics. |
| GDPR Compliance Certification | Satisfies German federal data protection authority requirements for cross-border telemetry. |
| Energy Grid Settlement Pilot | Automates kilowatt-hour pricing between Texas solar aggregators and utility operators. |
Research Methodology
Initial hypotheses were tested against primary input from distributed systems engineers, logistics provider CTOs, utility grid operators, and semiconductor procurement leads, then refined through secondary validation against SEC 10-K filings, EEA blockchain deployment registries, hyperscaler capex disclosures, and EU AI Act implementation guidance documents. Bottom-up telemetry platform deployment counts were triangulated with top-down infrastructure spending estimates across the analysis window.
Variance-decomposition across deployment models, solution offerings, end-user industries, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory synthesis, incorporating edge device power constraint curves, consensus protocol latency benchmarks, and data localization statute expansion patterns as blockchain IoT-specific forecast inputs.
Underlying assumptions cover sustained EU AI Act enforcement stringency and stable semiconductor foundry capacity allocation, with deviation risk concentrated in NHTSA regulatory timeline shifts and ASEAN data corridor interoperability standard fragmentation. Practitioners should keep alternative scenarios live as German federal data protection authority interpretations and Singapore IMDA guideline revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Identity Management Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Tokenization Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Bitcoin Technology Market