
 Smart Connected Speaker Market | 2026-2036
Smart Connected Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Connected Speaker Market Insights
Subscription-based hardware financing and ecosystem bundling is tilting competitive dynamics toward platform-scale operators rather than standalone audio brands. Amazon.com, Inc. leverages its Prime membership infrastructure to embed speaker hardware into recurring revenue streams. Apple Inc. sustains premium positioning through proprietary silicon and closed-system integration. Xiaomi Corporation competes on manufacturing scale to occupy price-sensitive segments across Asia.
Smart connected speakers integrate far-field microphone arrays, cloud-based natural language processing, and wireless connectivity protocols to deliver voice-activated media control and home automation command interfaces. Wi-Fi-enabled devices dominate volume shipments while AI Integration capabilities command the strongest margin pools as differentiation shifts from audio fidelity to assistant intelligence. Smart Displays represent the fastest-expanding product type as visual interfaces complement voice interaction in household and retail settings.
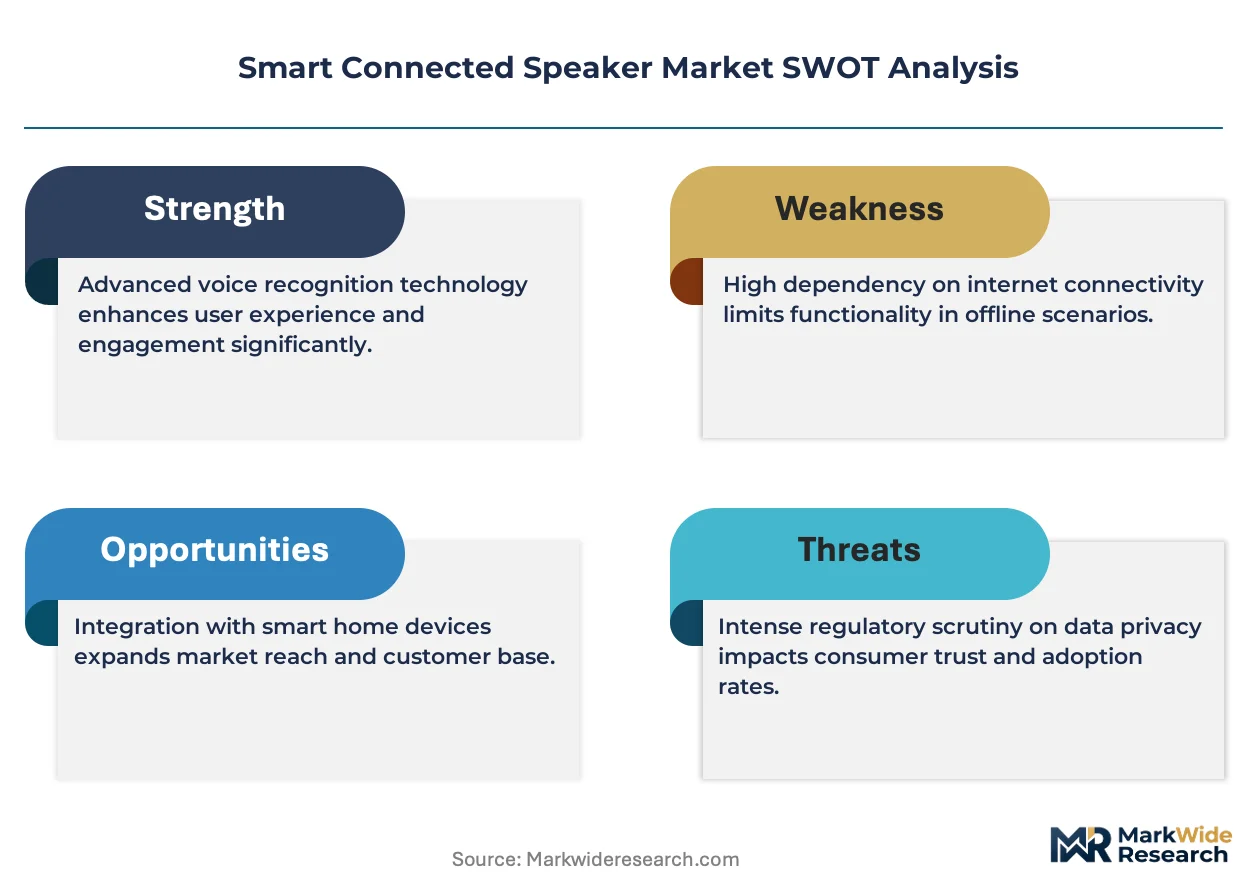
FCC equipment authorization governs radio frequency emissions for US market entry while GDPR and the EU AI Act impose stringent voice data retention and algorithmic transparency obligations across European jurisdictions. These frameworks elevate compliance costs for new entrants and favor incumbents with established legal infrastructure. Stakeholders must weigh ecosystem lock-in risks against the defensibility of proprietary voice platforms as interoperability mandates gain legislative traction.
Market Dynamics
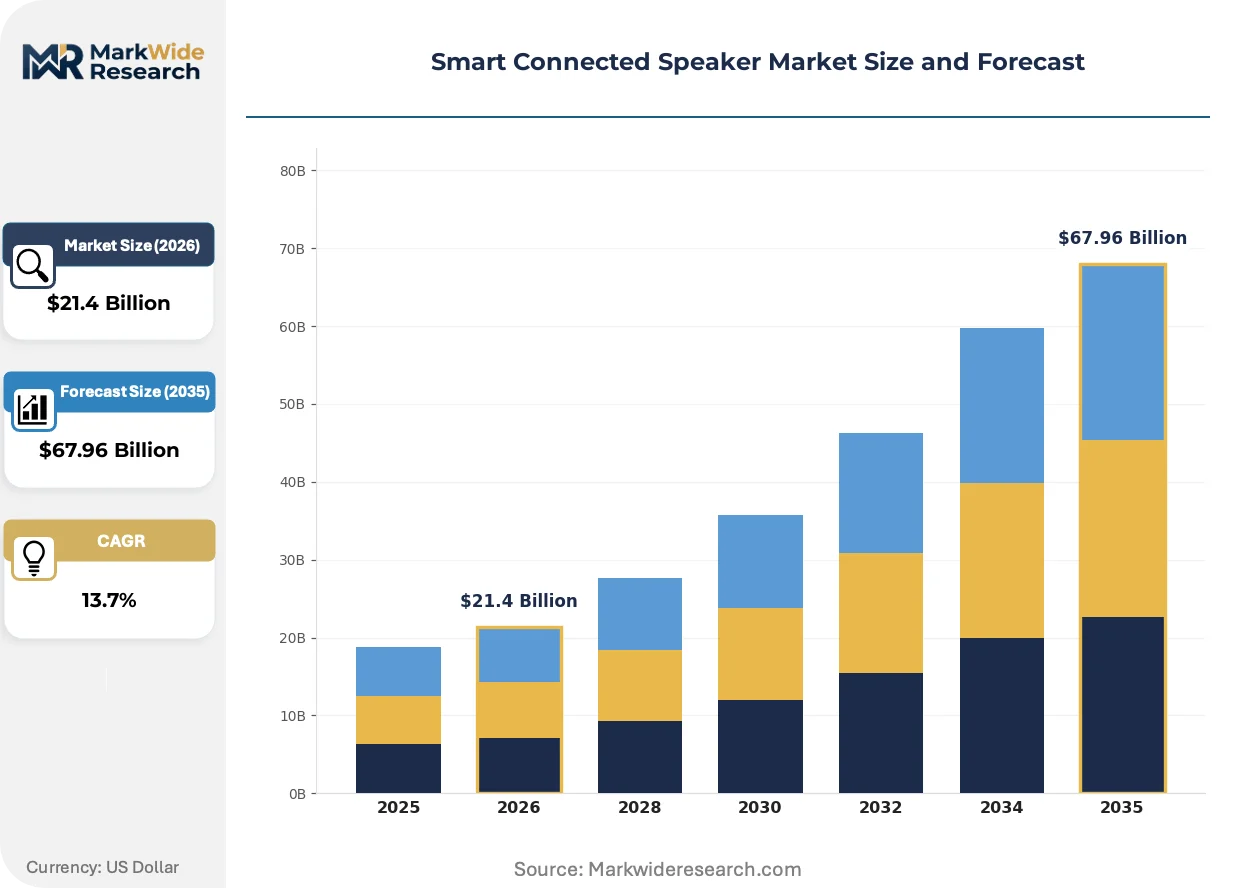
Ecosystem bundling is compressing standalone hardware margins as voice platforms consolidate around recurring revenue models rather than one-time device sales.
Growth Catalysts
- GDPR and EU AI Act compliance:Regulatory clarity in Europe is accelerating enterprise voice deployment by establishing uniform data handling standards across member states.
- Smart home infrastructure buildout:Residential broadband upgrades and mesh Wi-Fi adoption in Germany, China, and the United States are expanding addressable households for voice-activated control systems.
- Edge AI inference chips:On-device natural language processing is reducing cloud latency and enabling offline command execution in bandwidth-constrained environments.
Market Restraints
- Semiconductor supply concentration:Far-field microphone array controllers and neural processing units depend on Taiwan and South Korea fabrication capacity, creating single-source vulnerability.
- FCC equipment authorization timelines:Radio frequency certification for Wi-Fi and Bluetooth modules extends US market entry by four to eight months for new entrants.
- Smartphone voice assistant substitution:Native iOS and Android assistants reduce household willingness to purchase dedicated hardware for basic media control.
Strategic Opportunities
- India smart city deployments:Municipal voice-enabled public service kiosks and transit information systems represent untapped institutional demand outside residential segments.
- Healthcare ambient monitoring:Fall detection and medication reminder applications in aging populations are driving clinical pilot programs for speaker-based wellness platforms.
- EU Green Deal circular economy mandates:Repairability and recyclability requirements favor modular hardware designs that extend product lifecycles and reduce replacement frequency.
Industry Challenges
- Acoustic engineering talent scarcity:Far-field audio processing and noise cancellation algorithm development requires specialized signal processing expertise concentrated in limited geographic clusters.
- Multi-assistant interoperability certification:Matter protocol compliance and cross-platform voice service integration create testing complexity for hardware manufacturers targeting fragmented smart home ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Connected Speaker Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $67.96 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Speakers, Smart Displays, Soundbars, Home Hubs Technology: Wi-Fi, Bluetooth, Voice Recognition, AI Integration End User: Households, Offices, Retail Outlets, Educational Institutions Sales Channel: Online Retail, Offline Retail, Direct Sales, Third-party Distributors |
| Companies Covered | Amazon.com, Inc., Alphabet Inc., Apple Inc., Sonos, Inc., Bose Corporation, Samsung Electronics, Harman International, Sony Corporation, Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Connected Speaker Market Trends and Innovations
Voice interface technology is migrating from passive command-response systems toward proactive ambient intelligence that anticipates user needs through contextual pattern recognition.
Multimodal interaction is hybridizing speaker functionality as visual displays integrate with voice control. Smart displays combine touchscreen interfaces with far-field microphones, enabling video calling, recipe visualization, and security camera monitoring. Hospitality and retail buyers in Japan and South Korea are deploying these hybrid units for guest services and inventory lookup, compressing demand for audio-only hardware in commercial settings.
The EU AI Act algorithmic transparency requirements are reshaping voice data governance across European deployments. Providers must document training data provenance and enable user audit rights for automated decision-making. Enterprise voice assistants in Germany and France face the steepest compliance burden, with legal infrastructure investments becoming a competitive differentiator against smaller platform operators.
Enterprise procurement is consolidating voice platform decisions at the IT architecture level rather than departmental silos. Facility managers in US healthcare and education verticals are specifying ecosystem-wide assistant standards to reduce integration fragmentation. This centralization favors vendors with established identity management and security compliance credentials, displacing point solutions that lack enterprise-grade administrative controls.
Smart Connected Speaker Market Segmentation
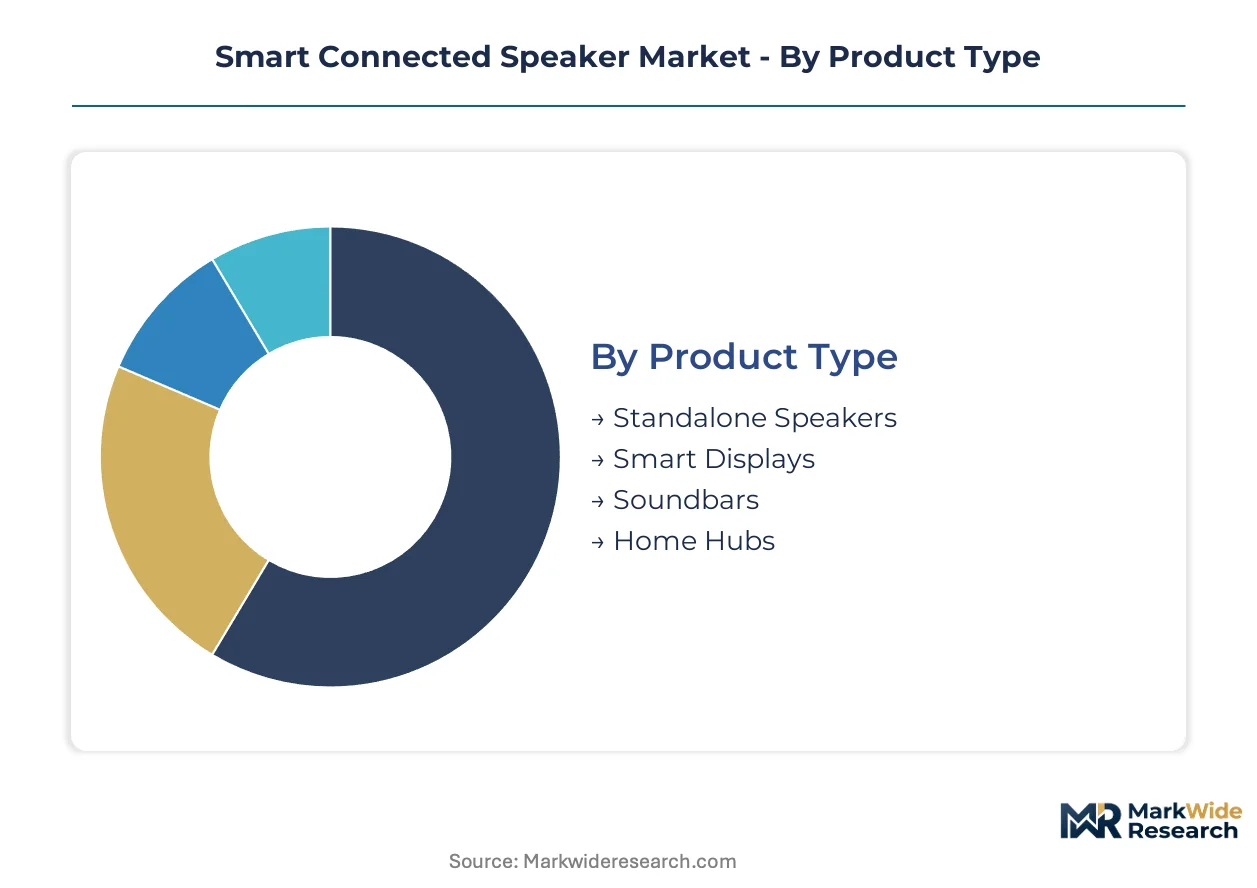
Segmentation reveals how hardware economics, connectivity protocols, and procurement channels fragment the Smart Connected Speaker Market into distinct competitive arenas. Each dimension carries different margin profiles, technical requirements, and customer acquisition costs that shape vendor positioning.
Product Type:
After-sales-service intensity varies sharply across form factors, with complex multi-sensor devices requiring firmware update infrastructure and acoustic calibration support that simpler audio-only units do not demand.
- Standalone Speakers:Single-purpose audio devices with far-field microphone arrays and cloud voice processing. Demand concentrates in US and German households seeking entry-level smart home entry points, constrained by smartphone voice assistant substitution limiting replacement cycles.
- Smart Displays:Hybrid touchscreen and voice units enabling video calling, security camera monitoring, and visual recipe assistance. Hospitality and retail buyers in Japan and South Korea are deploying these for guest services and inventory lookup, compressing audio-only hardware demand in commercial settings.
- Soundbars:TV audio integration with embedded voice assistants for home theater control. Living room entertainment centers in China and the United States drive volume.
- Home Hubs:Centralized smart home controllers bridging multiple device protocols. Proliferation of Matter-certified ecosystems in Germany and France supports adoption.
By volume, Standalone Speakers leads. By growth pace, Smart Displays is ahead.
Technology:
Cost tier stratification separates premium on-device processing from value-oriented cloud-dependent architectures, with silicon choices directly determining bill-of-materials spread.
- Wi-Fi:High-bandwidth connectivity enabling streaming media and cloud voice processing. Residential broadband upgrades in Germany, China, and the United States expand addressable households for these installations.
- Bluetooth:Lower-power protocol for portable and secondary speaker pairing. Mobile-first users in India and Southeast Asia favor these for cost and simplicity.
- Voice Recognition:Natural language understanding engines processing acoustic signals. Edge deployment in bandwidth-constrained environments is gaining traction.
- AI Integration:On-device neural processing enabling offline command execution and contextual pattern recognition. Enterprise healthcare pilots in the United States and Japan specify these for privacy-sensitive ambient monitoring applications.
By installed base, Wi-Fi dominates. By margin expansion, AI Integration is climbing the fastest.
End User:
Customer type determines procurement authority, with enterprise IT departments imposing security and identity management standards that consumer channels bypass entirely.
- Households:Residential consumers purchasing through retail and online channels. Smart home infrastructure buildout across multiple continents accelerates uptake.
- Offices:Corporate workspaces specifying ecosystem-wide assistant standards. US healthcare and education verticals are consolidating voice platform decisions at the IT architecture level.
- Retail Outlets:Commercial establishments deploying hybrid display units for customer service. Japanese and South Korean hospitality buyers lead this segment.
- Educational Institutions:Schools and universities integrating voice control for accessibility and administrative efficiency. Facility managers prioritize vendors with established security compliance credentials.
By unit shipments, Households leads. By specification complexity, Offices is expanding most quickly.
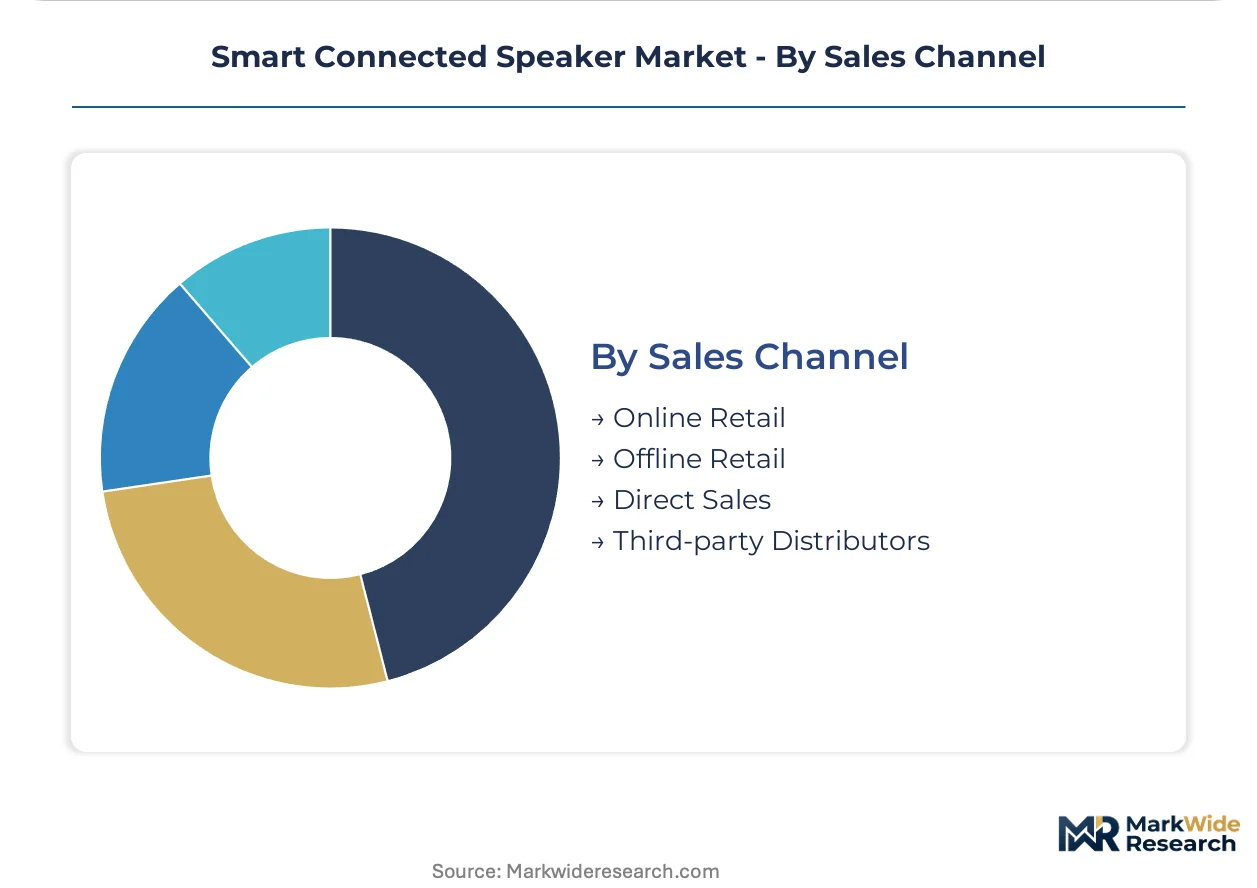
Sales Channel:
Supply concentration in platform-scale operators tilts channel economics toward ecosystem bundling and recurring revenue models rather than transactional hardware sales.
- Online Retail:E-commerce platforms offering subscription-based hardware financing. Prime membership infrastructure embeds speaker hardware into recurring revenue streams.
- Offline Retail:Physical stores enabling acoustic demonstration and immediate fulfillment. German and US electronics retailers maintain significant foot traffic for premium positioning.
- Direct Sales:Manufacturer-owned channels capturing full margin and customer data. Proprietary silicon vendors favor this route for closed-system integration.
- Third-party Distributors:Wholesale intermediaries serving regional markets and institutional buyers. Indian smart city deployments and municipal voice-enabled kiosks flow through these channels.
By transaction volume, Online Retail leads. By account value, Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States imports substantial volumes of Wi-Fi modules and far-field microphone arrays from Taiwan and South Korea while exporting voice platform software and cloud infrastructure services. Germany and China maintain near-balanced trade in speaker hardware components. India represents a net importer of finished devices but is building domestic assembly capacity through municipal smart city procurement.
United States
Residential broadband upgrades and mesh Wi-Fi adoption expand addressable households for voice-activated control systems. FCC equipment authorization governs radio frequency emissions for market entry, extending certification timelines for new entrants. Silicon Valley and Seattle host cloud voice processing infrastructure development while Austin emerging as a hub for edge AI chip design.
Germany
Matter-certified ecosystem proliferation drives smart home hub adoption among residential households. GDPR and the EU AI Act impose stringent voice data retention and algorithmic transparency obligations, elevating compliance costs. Berlin and Munich concentrate enterprise voice assistant development for healthcare and automotive verticals.
China
Manufacturing scale advantages enable cost-competitive production for price-sensitive Asian segments. MIIT certification requirements and GB standards regulate wireless transmission protocols for domestic market entry. Shenzhen and Dongguan anchor global speaker assembly capacity while Beijing focuses on natural language processing algorithm development.
Japan
Hospitality and retail buyers deploy hybrid smart display units for guest services and inventory lookup applications. METI promotes IoT security certification frameworks for connected home devices. Tokyo and Osaka concentrate acoustic engineering talent for far-field audio processing and noise cancellation algorithm development.
South Korea
Neural processing unit fabrication capacity supplies global demand for on-device AI inference chips. MFDS medical device regulations shape clinical pilot programs for speaker-based wellness platforms. Seoul anchors semiconductor design while Busan-Ulsan region hosts memory chip production critical for edge AI deployment.
Smart Connected Speaker Market Competitive Landscape
On the supply side, the industry is consolidating around platform-scale operators with established cloud infrastructure and recurring revenue ecosystems rather than standalone audio specialists. Three archetypes dominate: e-commerce platform operators leveraging membership infrastructure, consumer electronics conglomerates with proprietary silicon advantages, and manufacturing-scale challengers competing on cost. Competitive moves center on ecosystem bundling to compress standalone hardware margins and strategic partnerships to secure semiconductor supply.
Among platform-scale operators, Amazon.com, Inc. exemplifies the membership-embedded hardware model while Apple Inc. occupies a position defined by proprietary silicon and closed-system integration. Xiaomi Corporation represents the manufacturing-scale archetype competing on cost to serve price-sensitive segments across Asia. These three anchors illustrate how voice platform economics favor players with existing cloud infrastructure, captive distribution, or component supply advantages over pure-play audio brands.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Alphabet Inc. |
| Apple Inc. |
| Sonos, Inc. |
| Bose Corporation |
| Samsung Electronics |
| Harman International |
| Sony Corporation |
| Xiaomi Corporation |
| Others |
Pricing and Supply Chain Analysis
Taiwan semiconductor fabrication concentration creates single-source vulnerability that compresses hardware margins at the economy tier while amplifying premium pricing power for AI-integrated devices with on-device neural processing. This geographic chokepoint simultaneously widens the spread between cloud-dependent and edge-capable product lines and forces vendors toward modular designs that accommodate supply disruptions.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with AI Integration capabilities commanding the strongest margin pools while Wi-Fi-enabled volume units face cost compression. Price differentiation hinges on certification grade for GDPR and EU AI Act compliance plus vertical integration into proprietary silicon. Pricing pressure stems from ecosystem bundling as Amazon and Apple embed hardware into recurring revenue streams. Household consumers in India and Southeast Asia exhibit the highest price sensitivity, while enterprise IT departments in US healthcare tolerate premium positioning for security-compliant administrative controls.
Supply Chain Analysis
Far-field microphone array controllers and neural processing units draw from Taiwan, South Korea, and China fabrication capacity, with Shenzhen and Dongguan anchoring final speaker assembly. Raw material dependencies include silicon wafers, rare earth magnets for speaker drivers, and lithium-ion cells for portable units. Single-source vulnerability in Taiwan semiconductor foundries creates exposure to geopolitical disruption and capacity constraints. Distribution runs through platform-scale operators with captive e-commerce infrastructure rather than traditional electronics wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart connected speakers sit in early-cycle expansion as smart home infrastructure buildout across Germany, China, and the United States accelerates household penetration beyond voice-early-adopter cohorts.
For Market Incumbents: Build ecosystem lock-in moats through Matter-certified hub integration and proprietary voice platform defensibility. Deepen backward integration into edge AI chip design to reduce Taiwan foundry exposure. Consolidate enterprise voice platform decisions at the IT architecture level to displace point solutions lacking identity management credentials. Counter smartphone voice assistant substitution by embedding speakers into healthcare ambient monitoring and hospitality guest service workflows. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given limited platform-scale operator presence and price-sensitive procurement patterns. Municipal voice-enabled public service kiosks in Indian smart city deployments offer institutional demand outside residential segments where Amazon and Xiaomi dominate. Target healthcare ambient monitoring pilots in aging populations where clinical validation requirements create barrier-to-entry protection. Pursue third-party distributor relationships for regional market access rather than direct platform competition. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency requirements reshape the acquisition landscape by elevating legal infrastructure investments into competitive differentiators against smaller platform operators. Five-to-ten year viability favors vendors with established cloud infrastructure, captive distribution, or component supply advantages over pure-play audio brands. Acquisition target archetype: modular hardware designers with repairability credentials aligned to EU Green Deal circular economy mandates. Signal to watch: Matter protocol compliance certification velocity as interoperability mandates gain legislative traction.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Integration | On-device natural language processing reduces cloud latency for bandwidth-constrained German and Japanese deployments. |
| Matter Protocol Certification | Cross-platform interoperability compliance enables smart home hub positioning in EU and US retail channels. |
| Healthcare Partnership Development | Fall detection and medication reminder pilots with US hospital systems validate clinical wellness platform applications. |
| Subscription Hardware Financing | Prime membership infrastructure embeds speaker devices into recurring revenue streams beyond transactional sales. |
| EU Regulatory Compliance Investment | GDPR and EU AI Act legal infrastructure becomes competitive moat against undercapitalized platform entrants. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with smart home platform executives, acoustic engineering directors, enterprise IT procurement officers, and semiconductor supply chain managers; and secondary validation through FCC equipment authorization filings, MIIT certification records, EU AI Act implementation guidance, SEC 10-K hyperscaler disclosures, and customs trade data for Wi-Fi module imports. Bottom-up triangulation across product type, connectivity protocol, and end-user segmentation was cross-checked against top-down macroeconomic indicators for smart home adoption rates.
Forecast inputs considered residential broadband penetration curves, mesh Wi-Fi deployment trajectories, and edge AI inference chip availability across the projection horizon. Segmentation dimensions modeled include product form factor, technology tier, procurement channel, and geographic regulatory cluster. CAGRs were derived from installed base growth rates adjusted for replacement cycle compression and smartphone voice assistant substitution effects. Healthcare ambient monitoring pilot conversions and hospitality smart display deployments served as industry-specific demand inflection inputs.
Macroeconomic conditions sit as an overlay; deviation in residential construction activity, consumer electronics discretionary spending, and Taiwan semiconductor foundry utilization would shift the trajectory. Forecasts embed assumptions regarding GDPR enforcement consistency and EU AI Act implementation timelines that regulatory discretion could revise. Cross-checking against smart home device shipment benchmarks from established industry trackers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
PC Accessories Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Ereader Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Shoe Shining Machine Market