
 Armenia Consumer Goods Market | 2026-2036
Armenia Consumer Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Armenia Consumer Goods Market Insights
Young urban professionals are unwinding the historical dominance of rural household bulk purchasing in Armenia's consumer goods landscape. Procter & Gamble leverages its multinational supply chain to maintain shelf presence across Yerevan's modern retail channels. Grand Candy anchors local confectionery demand through domestic manufacturing scale and brand recognition. Kotayk Brewery competes in beverages by occupying the premium beer segment with differentiated regional recipes.
Armenia consumer goods encompass packaged food, beverages, personal care, household supplies, electronics, apparel, and toys distributed through supermarkets, online retailers, specialty stores, convenience outlets, direct sales, and local markets. Technical specifications for packaged foods emphasize shelf stability, local labeling in Armenian per national standards, and cold-chain integrity for dairy and fresh categories. Food and Beverages leads volume due to essential consumption patterns, while Online Retailers represents the fastest-growing distribution channel as digital infrastructure expands. Personal Care commands margin concentration through premium international brands and import-dependent positioning.
The country's national standards body enforces product safety and labeling requirements that shape import compliance costs for foreign suppliers. Eurasian Economic Union technical regulations harmonize certain standards with Russia, Belarus, and Kazakhstan, creating cross-border certification obligations for manufacturers. Stakeholders must monitor regulatory alignment between domestic Armenian standards and evolving EAEU frameworks to anticipate compliance burdens and market access conditions.
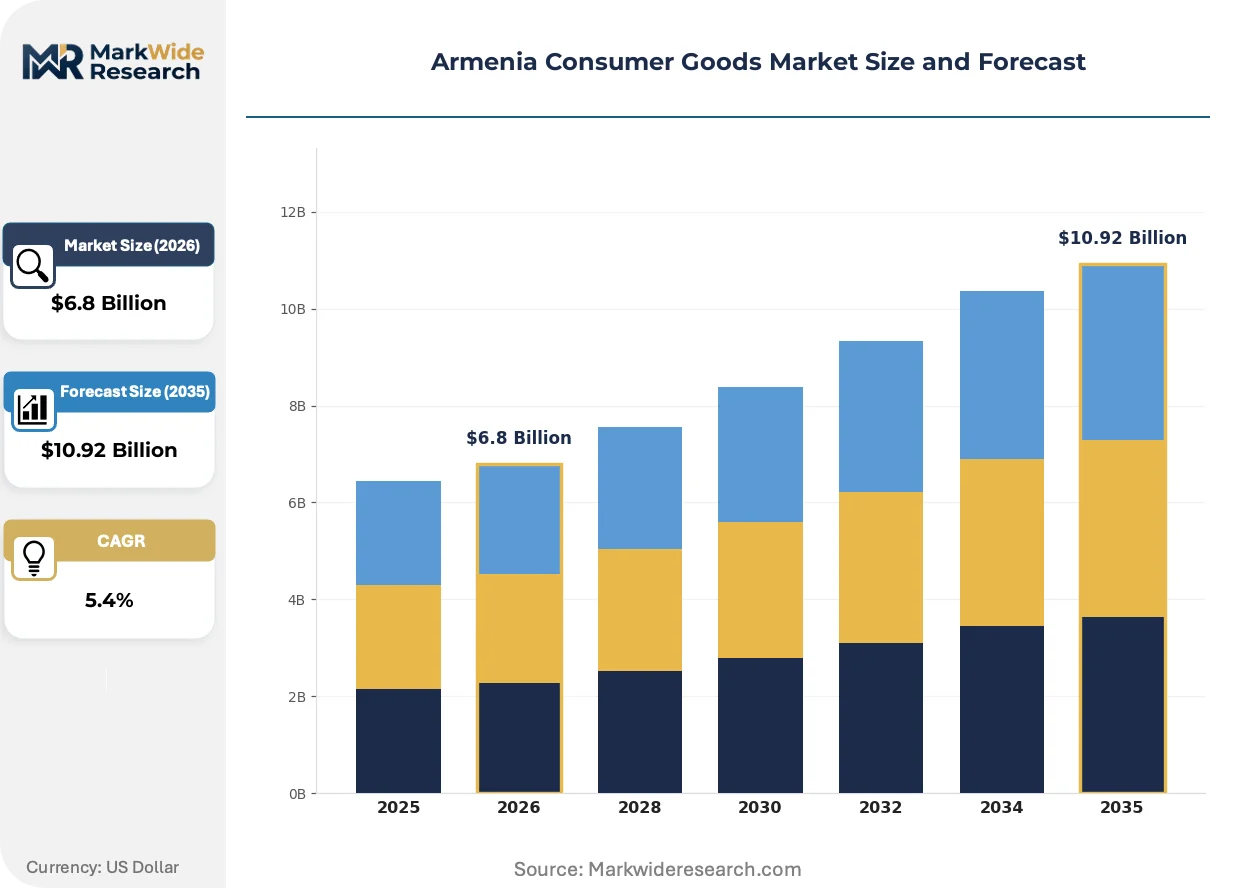
Market Dynamics
E-commerce platform penetration and mobile payment adoption are compressing traditional retail margins while fragmenting purchasing power across digital touchpoints in Greater Yerevan and secondary cities.
Growth Catalysts
- Mobile wallet infrastructure:QR-code payment systems from ArmSoft and Ameriabank are accelerating checkout velocity in convenience retail, reducing cash-handling costs for merchants.
- Eurasian Economic Union tariff harmonization:Cross-border certification alignment with Russia and Kazakhstan is lowering import compliance burdens for packaged food suppliers entering Armenian distribution.
- Urban household formation:Young professionals relocating to Yerevan's Kentron and Arabkir districts are driving demand for single-serve packaged food formats and premium personal care assortments.
Market Restraints
- Dram appreciation volatility:Import-dependent categories including electronics and premium cosmetics face margin compression when the national currency strengthens against the dollar.
- Geographic supply concentration:Over 70% of cold-chain logistics capacity clusters in Yerevan, constraining fresh category expansion to Gyumri, Vanadzor, and rural marzes.
- EAEU technical regulation lag:Armenian national standards bodies trail Moscow and Minsk in issuing harmonized conformity assessment protocols, delaying product registrations.
Strategic Opportunities
- Direct-to-consumer fulfillment:Last-mile delivery networks targeting apartment complexes in Yerevan's Ajapnyak and Davtashen districts can bypass supermarket slotting fees.
- Armenian-language digital content:Localized product discovery platforms and influencer commerce in Western Armenian dialects can capture diaspora remittance-driven purchasing.
- Subsidized SME digitization:Enterprise Armenia grants for inventory management software adoption are enabling smaller retailers to integrate with marketplace platforms.
Industry Challenges
- Specialized logistics talent scarcity:Cold-chain operations and reverse logistics for e-commerce returns require skills absent from vocational training curricula in Shirak and Lori marzes.
- Legacy POS integration friction:Independent grocers in secondary cities face technical barriers connecting Soviet-era accounting systems to modern payment aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armenia Consumer Goods Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Food & Beverages, Personal Care, Household Supplies, Electronics, Apparel, Toys Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Outlets, Direct Sales, Local Markets Customer Demographic: Millennials, Generation X, Baby Boomers, Families, Singles, Students Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Procter & Gamble, The Coca-Cola Company, PepsiCo, Nestlé, Unilever, Grand Candy, K-Town, Alex Holding, Kotayk Brewery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armenia Consumer Goods Market Trends and Innovations
Digital infrastructure deployment and regulatory harmonization are converging to restructure how Armenian households discover, evaluate, and receive consumer goods across income tiers.
Smart packaging with NFC-enabled freshness indicators is miniaturizing quality verification costs for dairy and meat suppliers serving Yerevan's supermarket chains. Premium segment buyers are adopting these tags to validate cold-chain integrity without laboratory testing. The technology is miniaturizing the role of traditional quality inspectors while shifting liability upstream to packaging converters.
EAEU technical regulations on food labeling are mandating bilingual Armenian-Russian nutritional panels and QR-linked traceability databases. Importers of European packaged goods must reformulate packaging designs or establish local repackaging partnerships. Personal care and household chemical segments face the steepest redesign costs due to ingredient disclosure requirements.
Subscription replenishment models for diapers, pet food, and household cleaners are displacing periodic supermarket stock-up trips among dual-income households in Kentron and Arabkir. Local marketplace platforms are piloting predictive algorithms based on consumption velocity rather than calendar scheduling. This behavioral pivot concentrates purchasing power with platforms offering flexible pause-and-resume functionality.
Armenia Consumer Goods Market Segmentation
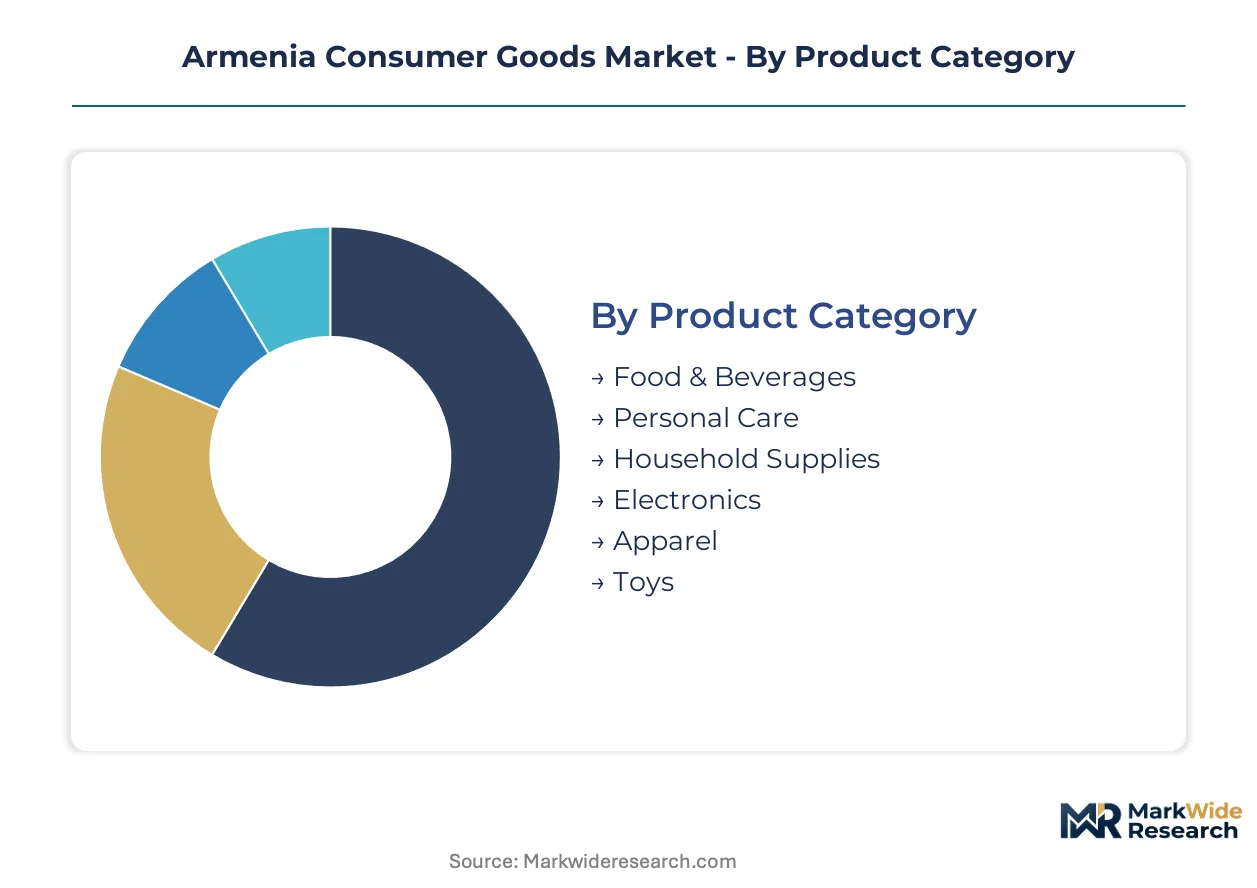
Armenia's consumer goods market fragments across product, channel, demographic, and price dimensions that each carry distinct regulatory and infrastructure requirements. EAEU technical regulations and domestic labeling standards create compliance cost differentials that reshape competitive positioning across these boundaries.
Product Category:
EAEU technical regulations impose divergent conformity assessment burdens: food and beverages face bilingual labeling mandates and traceability databases, while electronics confront electromagnetic compatibility certification.
- Food & Beverages:Shelf-stable and cold-chain-dependent formats dominate volume. Essential consumption patterns concentrate demand in Greater Yerevan and Gyumri, where modern retail infrastructure supports temperature-controlled distribution. EAEU sanitary-epidemiological requirements add registration complexity for imported dairy and meat.
- Personal Care:Premium international brands command margin concentration through import-dependent positioning. Ingredient disclosure requirements under EAEU chemical regulations force packaging redesigns for European suppliers. Demand clusters among young urban professionals in Kentron and Arabkir districts.
- Household Supplies:Surface cleaners and laundry products face steep reformulation costs from EAEU ingredient transparency rules.
- Electronics:Dram appreciation volatility compresses margins for dollar-denominated imports.
- Apparel:Local tailoring traditions compete with fast-fashion imports through price differentiation.
- Toys:Safety certification alignment with EAEU child protection standards delays product launches.
Established volume favors Food & Beverages; emerging adoption favors Personal Care.
Distribution Channel:
Channel economics diverge sharply: fixed slotting fees and cold-chain investments favor capitalized players in supermarkets, while variable commission structures enable marketplace entry for smaller suppliers.
- Supermarkets:Modern retail chains in Yerevan impose standardized supplier terms and centralized procurement. Cold-chain integrity requirements and EAEU traceability mandates favor scaled operators with compliance departments. Shelf space scarcity in Kentron districts drives promotional spending concentration.
- Online Retailers:Mobile wallet integration and last-mile delivery networks are climbing the fastest. QR-code payment systems from ArmSoft and Ameriabank reduce merchant cash-handling costs. Predictive replenishment algorithms target dual-income households in Ajapnyak and Davtashen.
- Specialty Stores:Beauty and electronics niches depend on trained staff for technical specification explanation.
- Convenience Outlets:High-frequency, low-basket formats serve transit corridors and residential peripheries.
- Direct Sales:Catalog and social-commerce models persist in diaspora-linked communities.
- Local Markets:Informal channels dominate fresh produce in rural marzes with limited cold-chain reach.
Procurement concentration favors Supermarkets; platform adoption favors Online Retailers.
Customer Demographic:
Life-stage and income trajectories segment purchasing behavior: household formation drives durable goods demand, while single-person urbanization expands convenience-oriented formats.
- Millennials:Digital-native cohorts in Yerevan's tech sector drive mobile payment adoption and subscription replenishment for diapers and pet food. Platform loyalty programs capture recurring revenue through predictive algorithms.
- Generation X:Peak earning years concentrate premium personal care and household electronics spending. Brand stickiness from Soviet-era consumption patterns moderates format switching.
- Baby Boomers:Price sensitivity and cash preference sustain local market participation in secondary cities.
- Families:Bulk purchasing and private-label acceptance maximize household budget efficiency.
- Singles:Single-serve packaged food formats gain share in Kentron apartment complexes.
- Students:Budget-tier concentration with high digital engagement for peer-influenced discovery.
Volume depth favors Families; behavioral innovation favors Millennials.
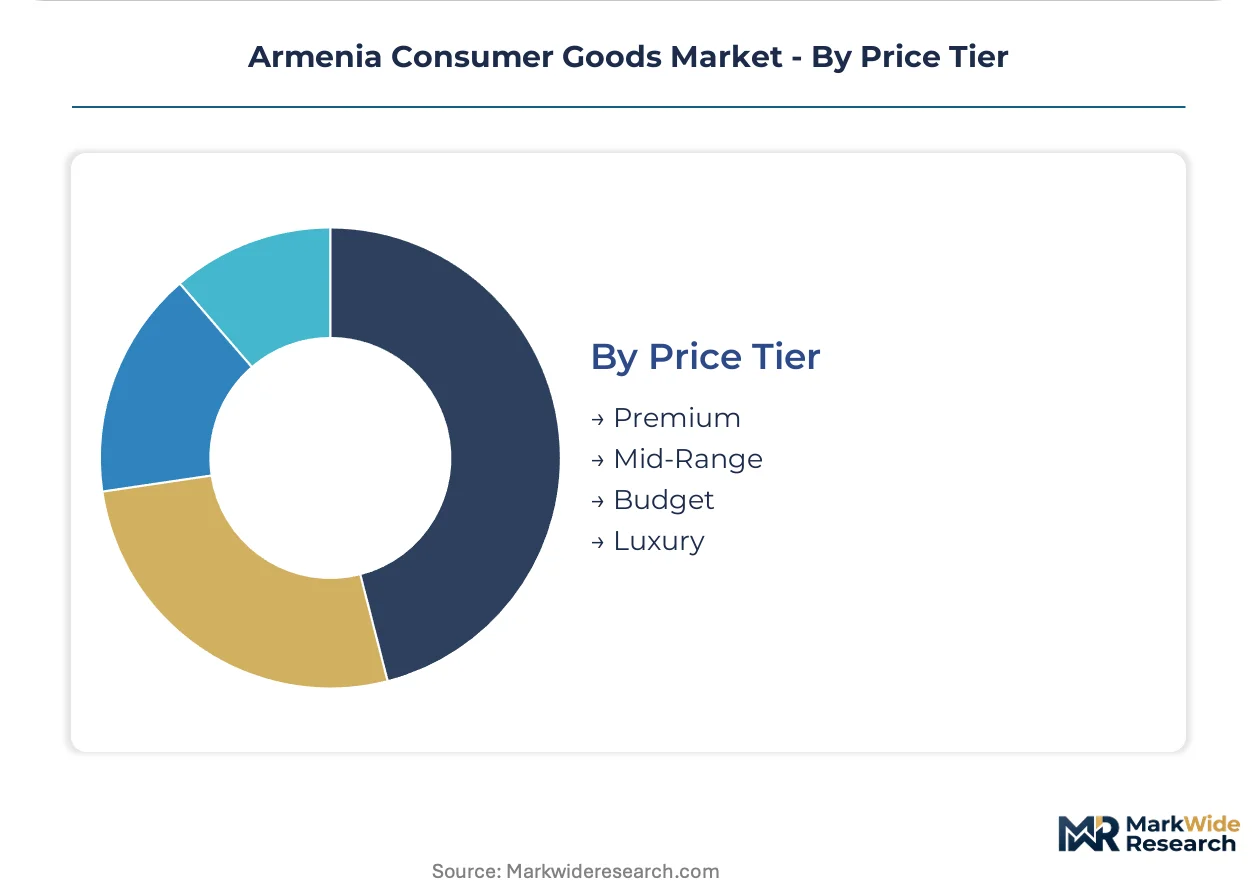
Price Tier:
Price positioning correlates with import dependency and currency exposure: premium tiers absorb dram volatility through dollar pricing, while budget tiers compete on local sourcing efficiency.
- Premium:International cosmetics and electronics brands occupy modern retail flagship locations. EAEU regulatory compliance costs are amortized across higher unit margins. Demand concentrates in Yerevan's affluent districts with diaspora remittance inflows.
- Mid-Range:Domestic manufacturers like Grand Candy and Kotayk Brewery anchor this tier through brand recognition and regional recipe differentiation. Price-quality tradeoffs attract Generation X loyalty.
- Budget:Private-label expansion in supermarket chains pressures local producers on cost efficiency.
- Luxury:Ultra-premium imports serve narrow diplomatic and expatriate segments with specialized distribution.
Margin concentration favors Premium; volume accessibility favors Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North-South Highway corridor anchors domestic distribution efficiency, connecting Yerevan's retail infrastructure to secondary urban centers and enabling cold-chain logistics penetration beyond the capital.
Greater Yerevan
Young urban professionals in Kentron and Arabkir districts drive single-serve packaged food demand and premium personal care adoption. Enterprise Armenia's SME digitization grants accelerate inventory management software uptake among local retailers. The Ajapnyak and Davtashen apartment complexes concentrate last-mile delivery network investments from emerging marketplace platforms.
Shirak Marz
Gyumri's retail infrastructure density supports the second-highest consumption per capita outside the capital, with cold-chain dependent categories gaining shelf space. The national standards body's regional office coordinates EAEU technical regulation compliance for local food processors. Vanadzor-bound distribution routes from Yerevan pass through Shirak, creating transit corridor convenience retail opportunities.
Lori Marz
Vanadzor functions as the northern logistics node where dram appreciation volatility most acutely compresses import-dependent electronics and cosmetics margins. The country's national vocational training curricula lack specialized cold-chain and reverse logistics programs, constraining e-commerce operational quality. Local market channels dominate fresh produce where refrigerated transport coverage remains sparse.
Kotayk Marz
Abovyan and surrounding settlements absorb commuter-driven demand from Yerevan's expanding labor pool, with household formation patterns mirroring capital consumption trends. Kotayk Brewery's regional recipe differentiation anchors premium beer positioning in this corridor. The marz's proximity to Yerevan enables same-day fulfillment pilots from central distribution centers.
Syunik Marz
Kapan and Meghri serve as transshipment points for cross-border trade with Iran, where informal channels compete with formal retail for household budget share. The Eurasian Economic Union's tariff harmonization with Russia and Kazakhstan creates compliance cost advantages for packaged goods routed through northern corridors versus southern alternatives. Local market infrastructure remains underdeveloped relative to northern marzes.
Armenia Consumer Goods Market Competitive Landscape
Concentration sits with multinational FMCG conglomerates that leverage EAEU-wide supply chains to amortize compliance costs across regional volumes. Domestic manufacturers occupy mid-tier positioning through brand recognition and localized production scale. Strategic moves center on portfolio diversification into premium personal care and direct-to-consumer fulfillment infrastructure.
Among multinational anchors, Procter & Gamble exemplifies import-dependent premium positioning, while Grand Candy and Kotayk Brewery represent domestic manufacturing scale and regional recipe differentiation. These three occupy positions across the price-tier spectrum, with the multinationals commanding margin concentration and the domestic players anchoring volume accessibility through localized supply chains.
| Leading Market Players |
|---|
| Procter & Gamble |
| The Coca-Cola Company |
| PepsiCo |
| Nestlé |
| Unilever |
| Grand Candy |
| K-Town |
| Alex Holding |
| Kotayk Brewery |
| Others |
Pricing and Supply Chain Analysis
EAEU technical regulation harmonization gates both supplier qualification and price tier access simultaneously, forcing importers to absorb conformity assessment costs that stratify final shelf pricing across Yerevan's retail channels. Armenian national standards alignment with Moscow and Minsk creates dual compliance burdens that concentrate pricing power among scaled operators capable of amortizing certification overhead across larger volumes.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between supermarket chains and packaged food suppliers, with Kentron district retailers extracting promotional allowances that compress net realized prices for domestic manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects import dependency gradients: premium tiers absorb dram appreciation through dollar-denominated sourcing, while budget tiers compete on local manufacturing efficiency. Cost compression in mid-range categories is intensifying as private-label expansion pressures Grand Candy and Kotayk Brewery margins. Families exhibit highest price sensitivity through bulk purchasing optimization, while diaspora-linked millennials in Arabkir show lowest sensitivity to unit pricing for convenience-oriented formats.
Supply Chain Analysis
The North-South Highway corridor functions as the critical logistics chokepoint, with over 70% of cold-chain capacity clustering in Yerevan and constraining fresh category distribution to Gyumri and Vanadzor. Russia, Kazakhstan, and Belarus anchor upstream supply through EAEU tariff harmonization, while Georgia and Iran provide alternative routing for non-EAEU goods facing technical regulation delays. Raw material dependencies center on wheat flour for confectionery, malted barley for brewing, and petrochemical feedstocks for personal care packaging. Single-source vulnerability concentrates in refrigerated transport equipment, where European chassis suppliers dominate fleet renewals. Distribution runs through centralized Yerevan distribution centers serving supermarket chains, with last-mile fragmentation accelerating among Ajapnyak apartment complex delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile payment adoption and subscription replenishment models are fragmenting purchasing power across digital touchpoints, creating niche entry points for specialized fulfillment operators outside traditional supermarket dominance.
For Market Incumbents: Shield market share by securing exclusive slotting arrangements in Kentron and Arabkir supermarket chains before direct-to-consumer platforms achieve critical mass. Invest in backward integration into cold-chain logistics to reduce third-party transport dependency that constrains Gyumri expansion. EAEU technical regulation lag poses regulatory threat requiring dedicated compliance staffing in Yerevan. For New Entrants and Emerging Players: Last-mile delivery service gaps in Davtashen and Ajapnyak apartment complexes offer immediate white-space penetration where incumbents under-serve. Target Shirak Marz convenience retail corridors along Vanadzor-bound transit routes for geographic expansion. Deploy Armenian-language influencer commerce platforms to capture diaspora remittance-driven purchasing with localized Western Armenian content. For Investors and Strategic Acquirers: EAEU technical regulation alignment completion reshapes the acquisition landscape by elevating compliance-capable domestic manufacturers above import-dependent competitors. Five-to-ten year viability favors vertically integrated food processors with captive cold-chain assets over pure brand licensors. Monitor Enterprise Armenia SME digitization grant uptake rates as inflection signal for platform integration readiness among acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Launch | Bypasses supermarket slotting fees in Yerevan's Ajapnyak and Davtashen districts. |
| Premium Tier Introduction | Captures diaspora remittance inflows through international brand positioning in Kentron. |
| Distribution Channel Expansion | Extends cold-chain reach to Gyumri and Vanadzor beyond Yerevan concentration. |
| Sustainability Repositioning | Aligns packaging with EAEU ingredient disclosure mandates ahead of competitor compliance. |
| Brand Extension | Leverages Grand Candy and Kotayk Brewery recognition into adjacent personal care categories. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, Nielsen retail audit data, and EAEU regulatory filings to construct market size estimates. Primary interviews engaged brand managers at multinational FMCG operations, category buyers at Yerevan supermarket chains, channel sales heads managing Gyumri distribution, and supply planners coordinating cold-chain logistics. Secondary validation drew from Armenian national standards body protocols, Enterprise Armenia grant disbursement records, and mobile payment platform transaction disclosures. Bottom-up SKU-level demand aggregation triangulates against top-down retail channel revenue analysis.
Segmentation dimensions modeled span product category, distribution channel, customer demographic, and price tier across the projection horizon. Food and beverage volume trajectories incorporate cold-chain infrastructure expansion rates and urban household formation patterns in Kentron and Arabkir. Personal care margin projections hinge on dram appreciation volatility assumptions and EAEU ingredient disclosure implementation timing. CAGRs derive from historical consumption velocity analysis adjusted for mobile payment adoption curves and subscription replenishment model penetration.
Forecasts assume regulatory continuity in EAEU technical regulation alignment and Armenian national standards enforcement; material policy shifts would require re-modeling. Revision becomes warranted when cold-chain logistics capacity expansion in Shirak and Lori marzes crosses thresholds enabling fresh category distribution comparable to Yerevan coverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Soft Support Products Market
Consumer Electronics
UAE Consumer Electronics Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market
Consumer Electronics
Keycap Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Consumer Electronics Retail Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Handheld Device Accessories Market