
 Instant Camera Market | 2026-2036
Instant Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Camera Market Outlook
Film-plus-camera bundling is realigning buyer choice across entry-level and enthusiast tiers. Fujifilm leverages its proprietary Instax film ecosystem to sustain recurring revenue streams. Polaroid competes through vertical control over film chemistry and hardware design. MiNT Camera specializes in premium mechanical modifications that occupy a narrow luxury niche.
An instant camera is a self-contained photographic device that exposes and develops an image through integrated chemical processing, typically producing a physical print within seconds of capture via dye diffusion thermal transfer or silver halide emulsion layers. The primary commercial purpose spans personal memory archiving, event documentation, and creative art applications where tangible output carries experiential value. Analog instant film anchors volume sales across mass-market channels, while hybrid digital-instant models lead growth by merging physical output with digital storage and social sharing workflows. Premium and luxury price tiers concentrate margin pools where Leica and specialty manufacturers command collector and professional photographer loyalty.
FCC equipment authorization governs electromagnetic compliance for instant cameras sold in the United States, while EU RoHS and REACH frameworks restrict hazardous substances across batteries, circuit boards, and chemical pods entering European markets. Japan's METI enforces electrical appliance safety standards that shape product certification pathways for domestic and export-bound manufacturers. Stakeholders must monitor evolving battery transport regulations and chemical disclosure mandates that could alter film pod composition and cross-border logistics costs.
Market Dynamics
Film chemistry supply concentration and hybrid digital-analog convergence are restructuring competitive advantage, forcing manufacturers to secure captive emulsion production while integrating CMOS sensors into legacy instant formats.
Growth Catalysts
- Wedding and event photography demand:Tangible photo favors and guest-book integrations drive recurring hardware and film purchases across mid-tier and premium product lines.
- EU RoHS material compliance:Restrictions on lead and cadmium in circuit boards and battery contacts are accelerating substitution to compliant chemistries, opening certification advantages for early adopters.
- Japan's heritage retail networks:Specialty camera shops and department store concessions sustain premium positioning through experiential merchandising and limited-edition collaborations.
Market Restraints
- Silver halide emulsion cost volatility:Fluctuations in silver commodity pricing and gelatin supply from leather processing directly compress film margin structures.
- Single-source dye diffusion thermal transfer chemistry:Concentration of pod manufacturing expertise in Japanese chemical suppliers creates geographic supply risk.
- Smartphone camera substitution:Computational photography and instant digital sharing displace casual snapshot use cases that anchored mass-market instant camera volume.
Strategic Opportunities
- India's underpenetrated gifting culture:Wedding and festival photography traditions present white space for entry-tier film-plus-camera bundles through modern retail expansion.
- Hybrid instant-digital convergence:Bluetooth-enabled printers and SD card slots in instant bodies merge physical output with cloud archiving workflows.
- EU Green Deal circular economy incentives:Battery take-back mandates and repairability scoring favor modular designs with replaceable components.
Industry Challenges
- Chemical process engineering talent scarcity:Expertise in emulsion coating and pod assembly is concentrating among retiring specialists without sufficient knowledge transfer pipelines.
- FCC and METI electromagnetic certification timelines:Radio-enabled hybrid models face extended approval cycles for Bluetooth and Wi-Fi modules that delay regional launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Camera Market |
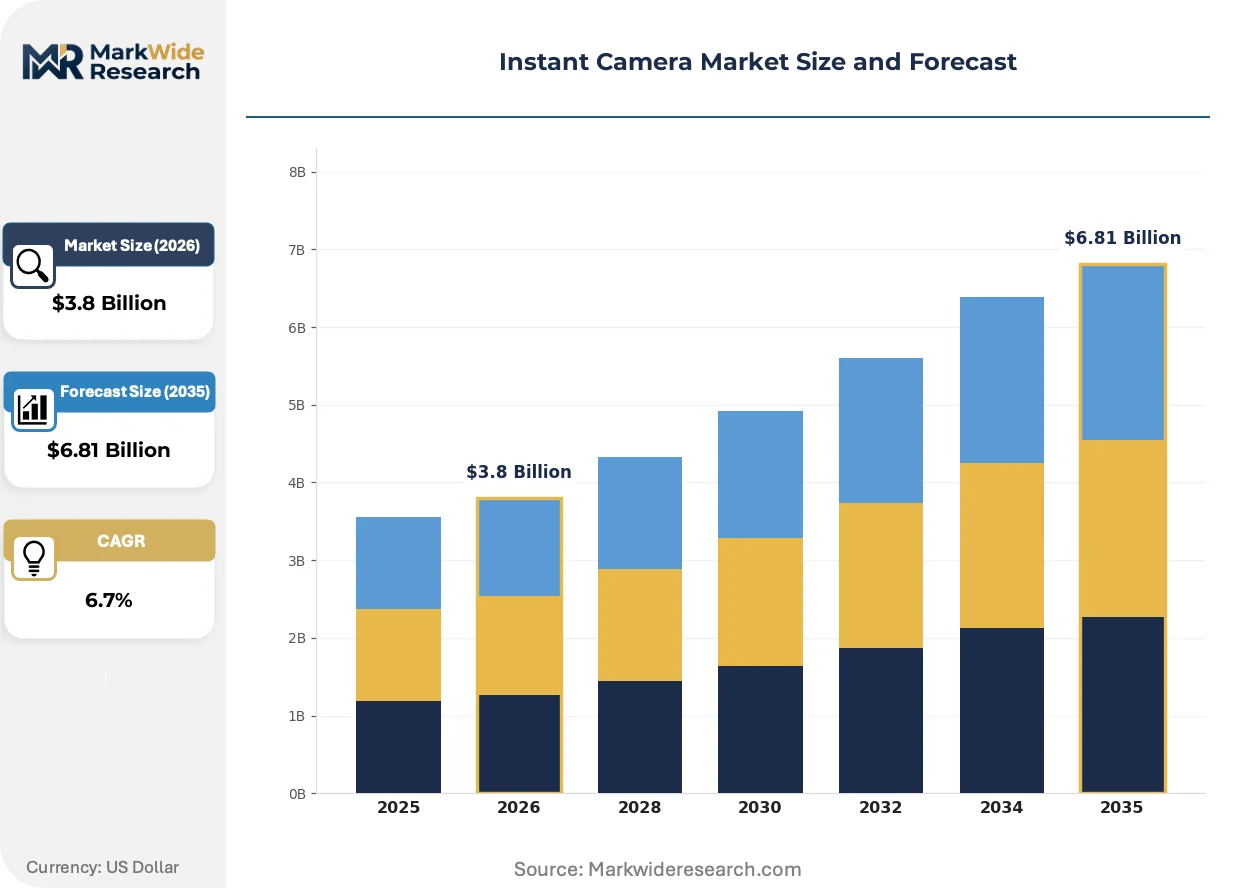
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Hybrid, Instant Film End User: Consumers, Professional Photographers, Event Planners, Businesses Distribution Channel: Online Retail, Specialty Stores, Electronics Retail, Supermarkets Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Lomography, HelloBaby, Fujifilm, Canon, Leica, Polaroid, MiNT Camera, Xiaomi, Kodak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Camera Market Strategic Shifts
Physical-digital workflow integration and regulatory chemistry restrictions are forcing simultaneous innovation in hardware architecture and film pod composition, compressing development cycles across the supplier base.
Hybrid instant-digital capture technology is converging with mobile connectivity standards to enable seamless physical printing from smartphone camera rolls. Event photographers and content creators are adopting these bridge devices at accelerating rates. This convergence is compressing the boundary between dedicated instant cameras and portable photo printers, forcing manufacturers to defend hardware differentiation through lens optics and film chemistry exclusivity.
EU REACH substance disclosure mandates now require full chemical composition reporting for film pods and thermal transfer ribbons entering European markets. Manufacturers must reformulate developer and dye carrier layers to eliminate restricted phthalates and heavy metal stabilizers. Wedding and event rental services operating across Germany and France face the steepest compliance costs, driving consolidation toward suppliers with established European regulatory affairs capabilities.
Subscription-based film replenishment models are displacing transactional retail purchasing among enthusiast segments. Direct-to-consumer auto-ship programs now capture recurring revenue from heavy users who previously bought opportunistically through Amazon and specialty retailers. Japan and South Korea exhibit the highest adoption of these locked-in supply relationships, where urban density supports reliable last-mile delivery of temperature-sensitive film stock.
Instant Camera Market Segmentation
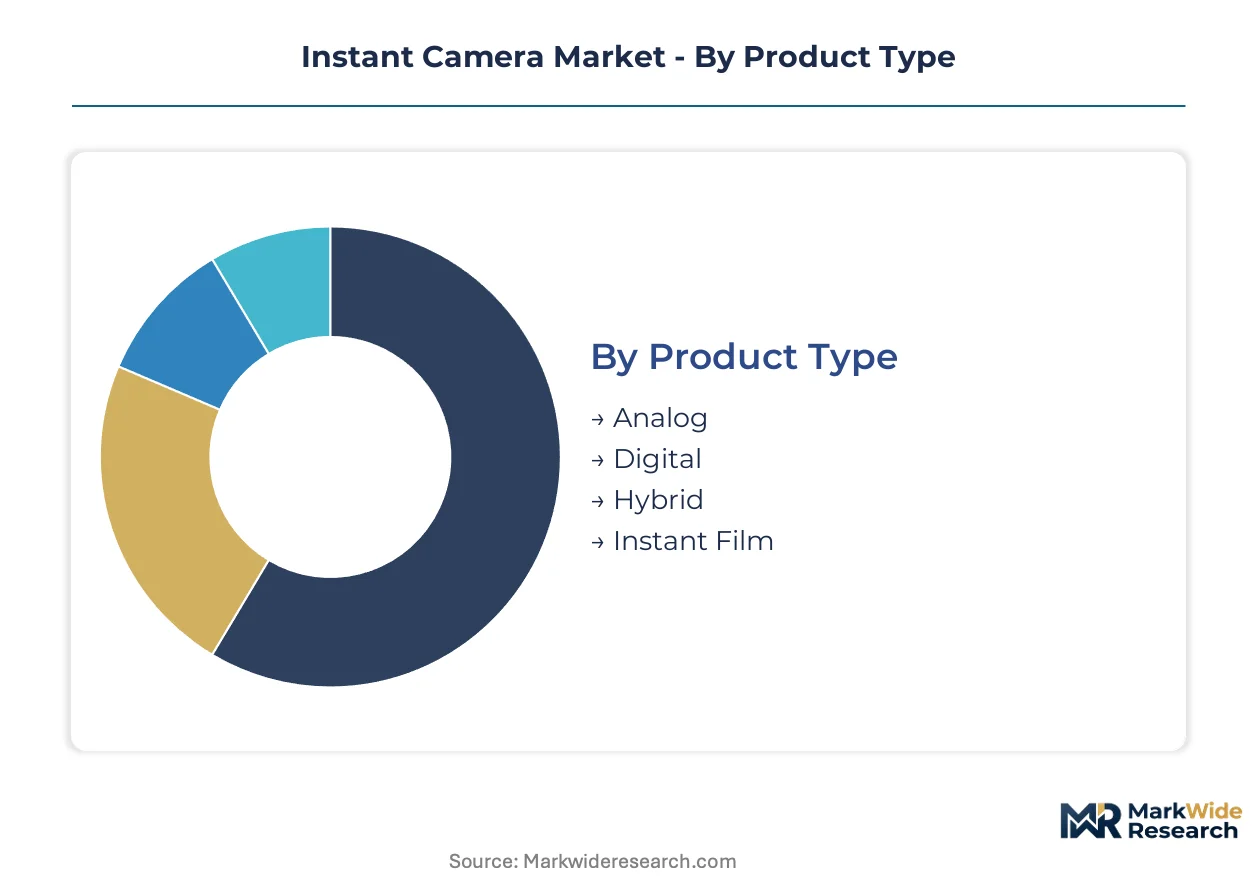
Instant camera segmentation reveals divergent margin structures across hardware and consumable categories. Product architecture and end-use application create distinct competitive arenas where film chemistry bundling and professional service integration reshape profitability.
Product Type:
Volume concentrates in analog film bodies while hybrid architectures command expanding share through digital workflow integration.
- Analog:Mechanical shutter bodies using silver halide emulsion pods with fixed-focus optics dominate unit shipments. Wedding guest-book stations and festival photography in Japan and India sustain recurring film purchases through heritage retail networks.
- Digital:CMOS-sensor bodies with LCD preview screens and SD card storage target casual users seeking retake capability. Demand concentrates in South Korea's gifting culture where Bluetooth printer pairing extends utility beyond single-shot capture.
- Hybrid:Dual-path capture enabling both physical print and digital file output.
- Instant Film:Dye diffusion thermal transfer pods and silver halide sheets sold separately from hardware bodies.
Today's leader: Analog. Tomorrow's challenger: Hybrid.
End User:
Professional service integration separates high-margin recurring revenue from transactional consumer purchases.
- Consumers:Personal memory archiving and social gifting applications.
- Professional Photographers:Event specialists deploying instant output for on-site client delivery. Portrait studios in Germany and France face EU REACH compliance costs for chemical pod composition disclosure, favoring suppliers with established regulatory affairs capabilities.
- Event Planners:Corporate and wedding coordinators sourcing hardware-plus-film bundles for guest experiences. Japan's METI electrical safety certification requirements shape procurement specifications for rental fleet operators.
- Businesses:Brand activations and retail loyalty programs using instant photo marketing.
Event planners extract premium pricing through bundled service models. Consumer segments face steepest smartphone substitution pressure.
Distribution Channel:
Channel selection determines access to temperature-controlled film logistics and experiential merchandising capabilities.
- Online Retail:Amazon and direct-to-consumer platforms capture subscription auto-ship adoption among heavy users. Japan and South Korea exhibit highest lock-in rates where urban density supports reliable last-mile delivery of heat-sensitive stock.
- Specialty Stores:Camera shops and department store concessions sustain premium positioning through limited-edition collaborations and hands-on demonstration. Japan's heritage retail networks anchor this channel's global relevance.
- Electronics Retail:Big-box chains targeting gift purchasers through seasonal promotions.
- Supermarkets:Mass-market impulse placement for entry-tier film refills.
Specialty stores defend margin through experiential differentiation. Online retail scales fastest via subscription mechanics.
Price Tier:
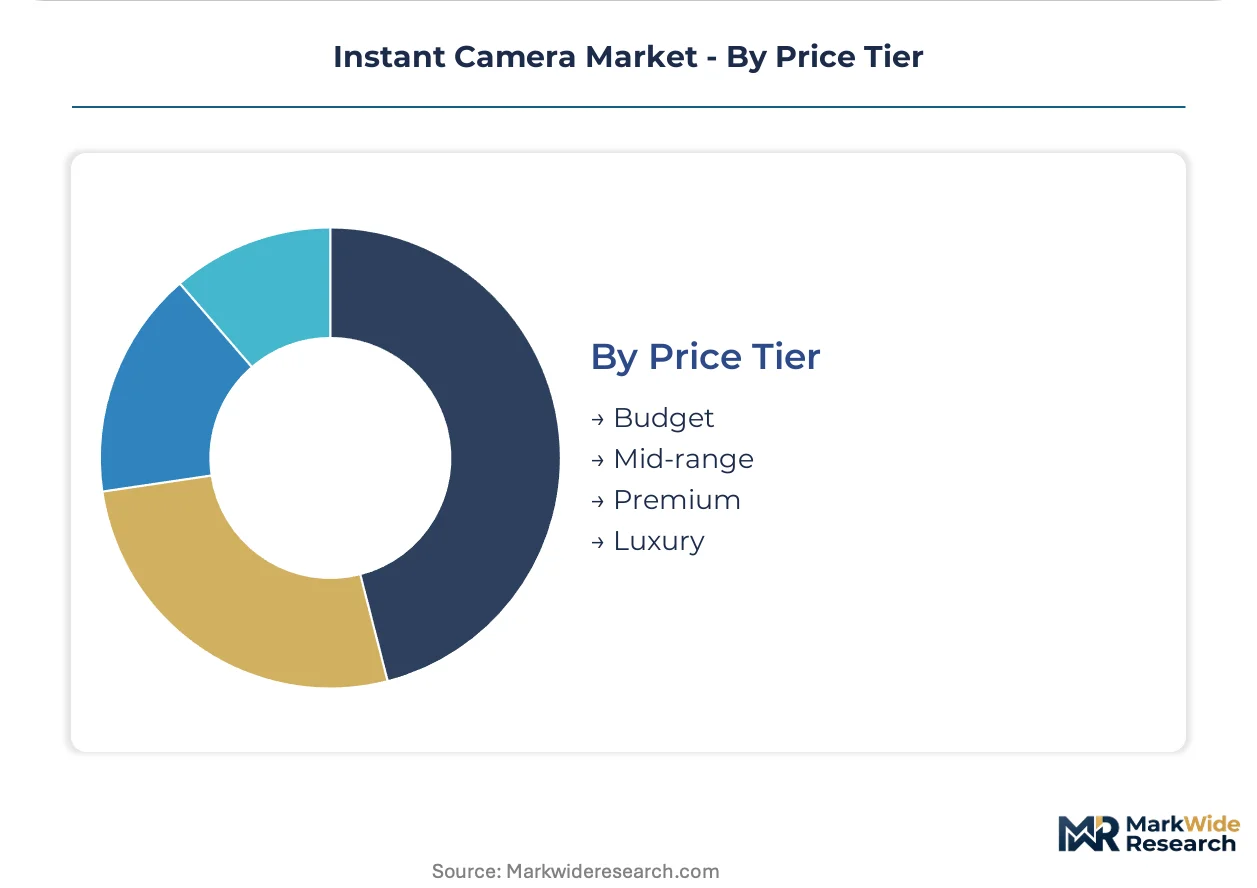
Three-tier pricing structure across premium, standard, and economy levels reflects lens optics, film chemistry exclusivity, and build material differentiation.
- Budget:Fixed-focus plastic bodies with basic flash units targeting first-time purchasers and children's gifting segments in India's expanding modern retail footprint.
- Mid-range:Variable focus and exposure control for enthusiast users.
- Premium:Glass lens optics and advanced metering systems. Leica and mechanical modification specialists command collector loyalty through German and Japanese precision engineering heritage.
- Luxury:Limited-edition collaborations and precious material finishes.
Premium tier concentrates margin pools. Budget tier faces steepest smartphone displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instant photography traces its commercial origins to American innovation in the mid-20th century, with subsequent manufacturing scale and brand heritage consolidating in Japan. Demand geography now reflects divergent retail infrastructures, regulatory exposure, and cultural attachment to tangible media formats.
United States
Wedding photography services and corporate event activations sustain hardware procurement through rental fleet operators and direct-to-consumer channels. FCC equipment authorization governs electromagnetic compliance for Bluetooth-enabled hybrid models entering the market. Los Angeles and New York anchor experiential marketing demand where brand activations deploy instant output for social media amplification.
Japan
Specialty camera retail networks and department store concessions sustain premium positioning through limited-edition collaborations and hands-on demonstration culture. METI electrical appliance safety standards shape product certification pathways for domestic and export-bound manufacturers. Tokyo and Osaka concentrate heritage brand headquarters and emulsion coating expertise that feeds global film supply.
Germany
Professional portrait studios and event photography specialists drive mid-tier and premium hardware adoption for on-site client delivery. EU REACH substance disclosure mandates require full chemical composition reporting for film pods entering European markets. Berlin and Munich host rental service operators facing steepest compliance costs, favoring suppliers with established regulatory affairs capabilities.
India
Wedding and festival photography traditions present expansion opportunity for entry-tier film-plus-camera bundles through modern retail footprint growth. BIS certification requirements apply to electronic components in hybrid digital-instant models. Mumbai and Delhi-NCR concentrate gifting culture demand where urban density supports emerging subscription replenishment models.
South Korea
Gifting culture and social media content creation drive hybrid model adoption with Bluetooth printer pairing extending utility beyond single-shot capture. MFDS-equivalent electrical safety frameworks align with export certification standards for regional distribution. Seoul anchors highest subscription auto-ship adoption rates where reliable last-mile delivery supports temperature-sensitive film logistics.
Instant Camera Market Competitive Environment
Premium-margin players sit above commodity-margin players across film chemistry exclusivity and optical component differentiation. The vendor base stratifies into heritage imaging conglomerates, specialty mechanical modifiers, and consumer electronics diversifiers. Three archetypes dominate: vertically integrated film-plus-hardware bundlers, precision optics specialists commanding collector loyalty, and electronics brands leveraging distribution scale. Competitive moves concentrate on securing captive emulsion production and integrating CMOS sensors into legacy instant formats.
Within the heritage imaging tier, Fujifilm and Polaroid exemplify vertically integrated control over film chemistry and hardware design. Leica occupies a position in the precision optics archetype where German engineering heritage commands professional and collector segments. MiNT Camera represents the specialty mechanical modification niche serving luxury demand for premium component upgrades.
| Leading Market Players |
|---|
| Lomography |
| HelloBaby |
| Fujifilm |
| Canon |
| Leica |
| Polaroid |
| MiNT Camera |
| Xiaomi |
| Kodak |
| Others |
Value Chain & Pricing Dynamics
Silver commodity pricing volatility cascades through instant camera manufacturing into tiered hardware and consumable pricing structures, compressing film margin pools while elevating premium optical differentiation as a defensive hedge against raw material cost swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes by lens quality and film chemistry exclusivity. Price differentiation hinges on glass versus plastic optics and METI electrical safety certification tiers for hybrid models. Pricing pressure intensifies in entry tiers as smartphone substitution erodes casual snapshot demand. Event planners and professional photographers exhibit lowest price sensitivity, while gift purchasers in emerging markets show highest elasticity.
Supply Chain Analysis
Retiring emulsion coating specialists in Japan and Germany constrain pod manufacturing expansion without adequate knowledge transfer pipelines. Silver halide chemistry draws from Argentine and Mexican mining supply, while gelatin feeds from leather processing in Brazil and India. Single-source concentration of dye diffusion thermal transfer expertise among Japanese chemical suppliers creates geographic vulnerability. Distribution runs through temperature-controlled specialty retail networks and direct-to-consumer subscription platforms with cold-chain last-mile requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The instant camera market represents a late-cycle quality story where hybrid digital-analog convergence and EU REACH compliance burdens favor incumbents with captive film production and established regulatory affairs capabilities.
For Market Incumbents: Anchor competitive position through backward integration into emulsion coating capacity and METI/FCC certification pre-positioning for Bluetooth-enabled hybrid launches. Smartphone substitution in casual segments and emerging Chinese electronics diversifiers threaten mass-market volume. Prioritize lens optics exclusivity and limited-edition collaboration pipelines to defend collector loyalty. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to entry for building recurring film replenishment relationships without legacy retail infrastructure. India's wedding gifting culture and South Korea's Bluetooth printer pairing ecosystems present the most penetrable white spaces. Pursue entry-tier film-plus-camera bundle positioning through modern retail partnerships in underpenetrated Indian metros. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty mechanical modification houses possessing transferable precision engineering expertise across optical and chemical process domains. Long-term viability depends on securing irreplaceable emulsion coating talent pools and hybrid architecture patent positions. Monitor EU Green Deal circular economy scoring implementation as inflection signal for modular design premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Emulsion Coating Capacity Expansion | Captive silver halide production insulates Fujifilm and Polaroid from commodity volatility and supply disruption. |
| Hybrid Digital-Analog Platform Launch | Bluetooth-enabled CMOS integration merges physical output with cloud workflows for content creator adoption. |
| EU REACH Compliance Repositioning | Phthalate-free developer reformulation opens certification advantages for early adopters in German and French markets. |
| Direct-to-Consumer Subscription Buildout | Auto-ship film replenishment locks in recurring revenue from heavy users in Japan and South Korea's dense urban corridors. |
| Limited-Edition Collaboration Pipeline | Heritage retail network exclusivity sustains premium positioning through Tokyo and Osaka department store concessions. |
Study Parameters
Direct dialogue with film chemists, specialty camera retail buyers, event photography fleet operators, and regulatory affairs directors at heritage imaging conglomerates grounded qualitative insights. Secondary validation drew from METI electrical safety filings, EU REACH substance disclosure registries, FCC equipment authorization databases, and Japanese customs trade data. Bottom-up film volume modeling and top-down hardware value aggregation enabled cross-verification.
Segmentation outputs across analog, digital, hybrid, and instant film product architectures combined with end-user stratification by professional service integration depth. Wedding photography demand curves, silver commodity price trajectories, and hybrid model adoption rates fed CAGR derivation across the projection horizon. Regional clustering reflected regulatory framework exposure and retail infrastructure maturity.
The model assumes a particular technology adoption path; alternative pathways for computational photography substitution would alter the outlook. Forecasts embed assumptions regarding emulsion coating talent pipeline continuity and EU chemical disclosure mandate implementation timelines. Material deviation in silver commodity pricing or REACH enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market
Consumer Electronics
Headset Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Mouse Pad Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Earbuds Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Middle East Radio Headset Market