
 Global Self-Paced E-Learning Market | 2026-2036
Global Self-Paced E-Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self-Paced E-Learning Market Outlook
Subscription-based revenue financing is rewriting competitive entry economics in self-paced digital education. Coursera leverages its university partnership network to sustain premium certification pricing. Udemy competes through marketplace breadth that anchors volume across consumer and enterprise tiers. Skillshare differentiates via creative-category specialization that occupies a defensible niche against generalist platforms.
Self-paced e-learning denotes asynchronous digital instruction where learners control progression speed through modular content, typically delivered via HTML5-compliant streaming video, SCORM- or xAPI-tracked assessments, and cloud-hosted Learning Management Systems with sub-200ms latency targets. The primary commercial purpose centers on scalable workforce credentialing and consumer skill acquisition without instructor scheduling constraints. Online courses and certification programs lead revenue contribution as enterprises prioritize verifiable outcomes over informal content consumption. Interactive modules and gamification technology represent the fastest-expanding structural segment as engagement metrics directly correlate with completion rates and renewal pricing power.
The European Union's GDPR and Digital Services Act impose data localization and algorithmic transparency obligations on platform operators storing learner behavioral data. India's Digital Personal Data Protection Act and BIS guidelines for educational technology content quality create parallel compliance architectures for multinational providers. China's NMPA and SAMR frameworks govern cross-border data flows for platforms serving professional certification markets. Stakeholders must monitor regulatory divergence across these jurisdictions when architecting centralized versus federated infrastructure strategies.
Market Dynamics
Corporate learning and development departments are compressing deployment timelines from months to weeks by mandating cloud-native Learning Management Systems with sub-200ms latency guarantees, forcing legacy on-premise vendors to rearchitect or exit.
Growth Catalysts
- Workforce Reskilling Mandates:Germany's Qualifizierungschancengesetz subsidizes employee upskilling, directly expanding enterprise subscription volumes for credentialing platforms serving automotive and industrial manufacturing sectors.
- GDPR Compliance Architecture:The European Union's data localization requirements for learner behavioral analytics are accelerating investment in EU-sovereign cloud infrastructure by platform operators seeking to serve multinational corporate clients.
- Mobile-First Delivery:HTML5-compliant streaming video with offline sync capabilities is penetrating rural India where fixed broadband remains sparse, opening addressable learner populations previously excluded from synchronous instruction.
Market Restraints
- Content Production Cost Concentration:Professional-grade instructional design and motion graphics talent clusters in San Francisco, London, and Bangalore, creating wage arbitrage pressures for platforms outside these hubs.
- SCORM Interoperability Friction:Legacy enterprise LMS installations running pre-2004 SCORM 1.2 specifications resist xAPI migration, fragmenting analytics architectures and inflating integration service costs.
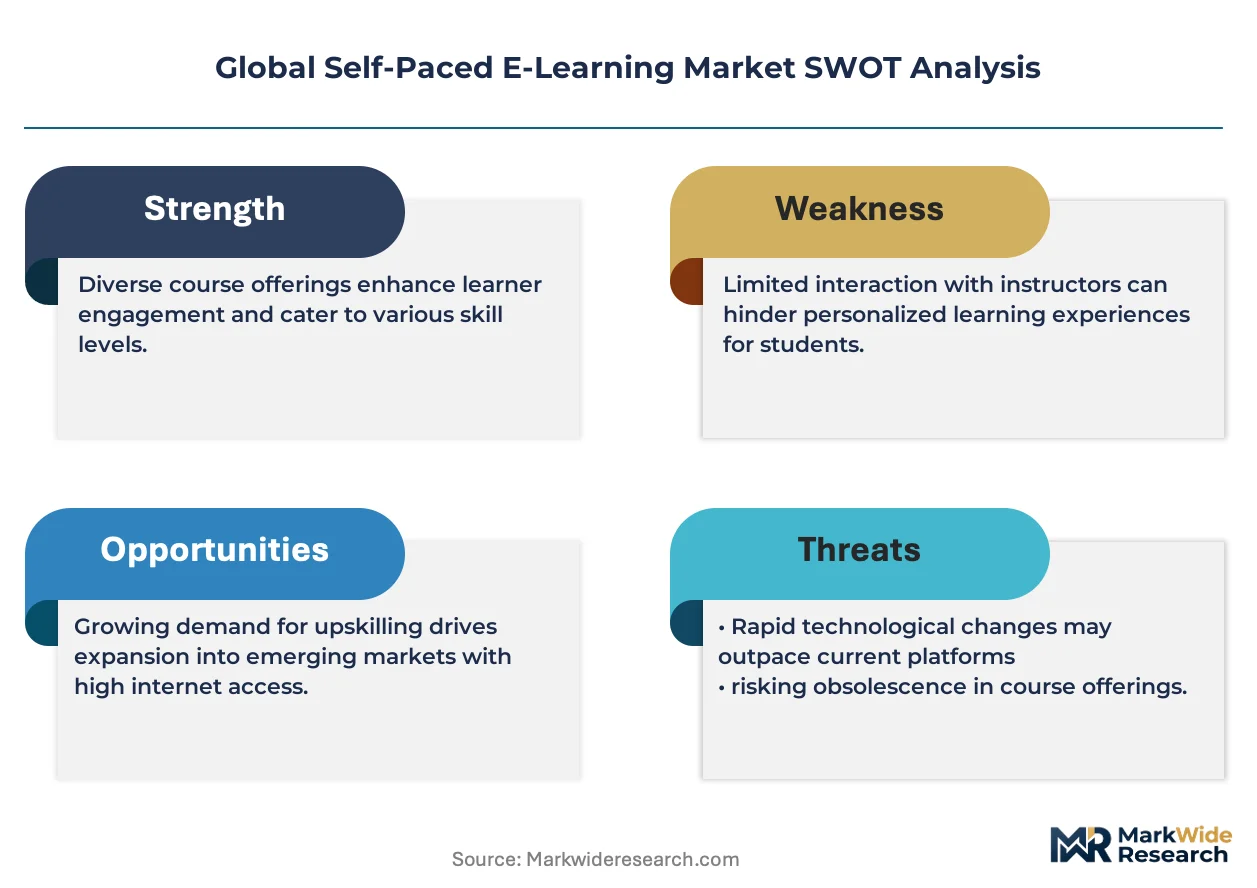
- Credential Dilution Risk:Low-barrier marketplace models enabling unvetted instructor uploads are compressing price realization for premium certification tiers as employer trust differentiates unevenly.
Strategic Opportunities
- Brazil's Professional Certification Gap:ANVISA-regulated healthcare continuing education requirements remain underserved by localized Portuguese content, creating first-mover advantage for platforms investing in regional production studios.
- AI-Assisted Personalization:Convergence of large language models with xAPI learning record stores is enabling real-time competency gap analysis that tailors module sequencing to individual proficiency trajectories.
- Saudi Arabia's Vision 2030:The Human Resources Development Fund's Tamheer program subsidizes private-sector training for Saudi nationals, redirecting platform localization investment toward Arabic content and gender-segregated delivery modes.
Industry Challenges
- Instructional Design Talent Scarcity:Competency in evidence-based learning science and data-driven iteration cycles remains concentrated among specialists trained at established university programs, constraining content quality at scale.
- Cross-Border Data Architecture Complexity:China's SAMR cross-border data flow restrictions for professional certification platforms require federated infrastructure that fragments learner analytics and complicates enterprise reporting consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self-Paced E-Learning Market |
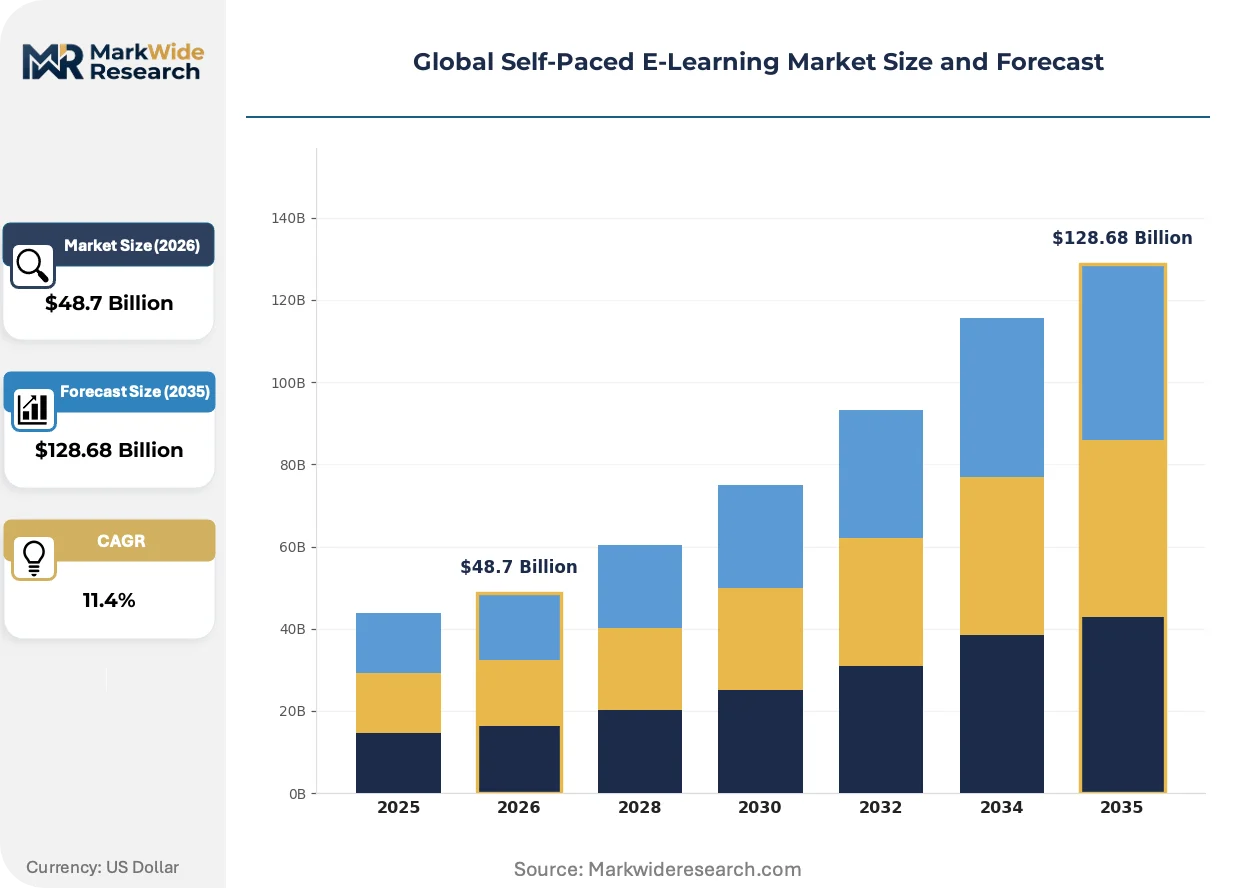
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Online Courses, Video Tutorials, Interactive Modules, E-Books Target Audience: Students, Professionals, Corporations, Lifelong Learners Content Type: Certification Programs, Skill Development, Language Learning, Personal Development Technology: Learning Management Systems, Mobile Applications, Multimedia, Gamification |
| Companies Covered | LinkedIn Learning, Thinkific, Udemy, Kajabi, Teachable, Coursera, Skillshare, iSpring LMS, edX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self-Paced E-Learning Market Strategic Shifts
Artificial intelligence is penetrating content creation pipelines and learner assessment engines, compressing production economics while raising questions about credential integrity and pedagogical efficacy.
Adaptive learning engines powered by reinforcement algorithms are hybridizing static course structures into dynamic competency pathways. Enterprise buyers in financial services and technology sectors are piloting these systems for role-specific credentialing. The technology is hybridizing seat-time-based pricing models toward verified-skill-outcome contracts that tie vendor compensation to learner demonstrated proficiency.
India's Digital Personal Data Protection Act imposes purpose limitation and storage limitation obligations on educational technology platforms processing learner behavioral data. Multinational operators must implement consent-layer architectures that segment data processing by jurisdictional boundaries. Platforms serving India's IT and business process outsourcing sectors are responding by deploying domestic cloud infrastructure and appointing resident data protection officers.
Employer-sponsored tuition reimbursement is displacing direct-to-consumer subscription models as the dominant procurement channel for professional upskilling. Human resources departments are consolidating vendor relationships through preferred provider arrangements that exchange volume commitments for discounted enterprise pricing. This concentration is most visible in the United States where Fortune 500 learning and development budgets exceed direct consumer expenditure on credentialing platforms.
Global Self-Paced E-Learning Market Segmentation
Self-paced e-learning platforms architect their commercial strategies around four distinct segmentation axes. Delivery mode determines infrastructure investment and latency requirements. Target audience shapes pricing architecture and content curation depth. Content type governs credential value and employer recognition. Technology selection constrains engagement mechanics and completion rate optimization.
Delivery Mode:
Cost tier differentiation in delivery infrastructure separates premium synchronous-capable platforms from lightweight asynchronous alternatives.
- Online Courses:Modular curricula delivered through SCORM-compliant Learning Management Systems with xAPI tracking for competency verification. Corporate procurement in Germany concentrates here as Qualifizierungschancengesetz subsidies require documented skill progression for reimbursement eligibility.
- Interactive Modules:Branching scenarios and simulation-based assessments using HTML5-compliant rendering engines with sub-200ms response latency. Financial services and healthcare sectors in the United States deploy these for compliance training where audit trails are mandatory.
- Video Tutorials:Streaming video with adaptive bitrate delivery optimized for mobile consumption in bandwidth-constrained environments.
- E-Books:Downloadable PDF and EPUB formats with offline annotation capabilities serving rural India where intermittent connectivity limits streaming reliability.
Online courses command the established base. The steepest expansion runs through interactive modules.
Target Audience:
Application focus varies sharply across learner segments, with procurement authority and budget source as the primary structuring variables.
- Corporations:Enterprise learning and development departments purchasing seat-based subscriptions with SSO integration and consolidated analytics dashboards. United States Fortune 500 procurement is displacing direct-to-consumer models as the dominant revenue channel.
- Professionals:Individual credential-seekers optimizing for employer-reimbursable certifications in project management, cloud architecture, and data analytics.
- Students:University-affiliated learners accessing platform content through institutional site licenses, particularly in India where engineering curriculum gaps drive supplementary skill acquisition.
- Lifelong Learners:Hobbyist and personal enrichment segments with price-sensitive willingness-to-pay and high churn propensity.
Corporations anchor procurement volume. Professionals are climbing the fastest as tuition reimbursement programs expand.
Content Type:
Customer type and credential value separate monetizable B2B offerings from discretionary consumer purchases.
- Certification Programs:Vendor-branded or university-partnered credentials with proctored assessments and blockchain-verified completion records. India's IT and business process outsourcing sectors prioritize these for client-facing role placement.
- Skill Development:Technical competency tracks in software development, cybersecurity, and digital marketing with portfolio-project deliverables.
- Language Learning:Structured curricula with speech recognition assessment targeting corporate globalization needs and individual immigration requirements.
- Personal Development:Soft skills, wellness, and creative content with lower completion rates and subscription pricing rather than one-time credential fees.
Certification programs hold the revenue concentration. Skill development is gaining share fastest as workforce reskilling mandates intensify.
Technology:
Supply concentration in cloud infrastructure and mobile development talent shapes platform competitive positioning.
- Learning Management Systems:Cloud-native architectures with EU-sovereign data residency options to satisfy GDPR localization requirements for European corporate clients.
- Mobile Applications:iOS and Android native development with offline sync capabilities penetrating India's rural markets where fixed broadband remains sparse.
- Multimedia:Motion graphics and instructional video production requiring specialized talent clusters in San Francisco, London, and Bangalore.
- Gamification:Points, badges, and leaderboard mechanics integrated with xAPI learning record stores to correlate engagement metrics with completion outcomes.
Learning Management Systems dominate enterprise procurement. Gamification is expanding most quickly as completion rate optimization becomes a pricing power determinant.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Qualifizierungschancengesetz subsidizes employee upskilling, directly channeling corporate training budgets toward credentialing platforms. India's Digital Personal Data Protection Act imposes localization mandates that reshape infrastructure deployment for multinational operators. The United States concentrates employer-sponsored tuition reimbursement procurement through Fortune 500 learning and development departments.
United States
Fortune 500 learning and development budgets exceed direct consumer expenditure on credentialing platforms, consolidating vendor relationships through preferred provider arrangements. Employer-sponsored tuition reimbursement is displacing direct-to-consumer subscription models as the dominant procurement channel. Silicon Valley and Boston harbor specialized instructional design talent clusters that constrain content quality scaling for platforms outside these hubs.
Germany
Automotive and industrial manufacturing sectors drive enterprise subscription volumes for credentialing platforms serving workforce reskilling mandates. The Qualifizierungschancengesetz subsidizes employee upskilling, requiring documented skill progression for reimbursement eligibility. GDPR data localization requirements for learner behavioral analytics accelerate investment in EU-sovereign cloud infrastructure by platform operators serving multinational corporate clients.
India
Engineering curriculum gaps at universities drive supplementary skill acquisition through institutional site licenses. The Digital Personal Data Protection Act imposes purpose limitation and storage limitation obligations on educational technology platforms processing learner behavioral data. Bangalore's IT and business process outsourcing sectors prioritize vendor-branded or university-partnered credentials with blockchain-verified completion records for client-facing role placement.
China
SAMR cross-border data flow restrictions for professional certification platforms require federated infrastructure that fragments learner analytics. NMPA frameworks govern data residency requirements for platforms serving professional certification markets. Shanghai and Beijing concentrate demand for compliance training where audit trails are mandatory in financial services and healthcare sectors.
Saudi Arabia
The Human Resources Development Fund's Tamheer program subsidizes private-sector training for Saudi nationals, redirecting platform localization investment. Vision 2030 workforce transformation objectives prioritize Arabic content development and gender-segregated delivery modes. Riyadh anchors procurement concentration for employer-sponsored credentialing programs in banking and telecommunications sectors.
Global Self-Paced E-Learning Market Competitive Environment
On the supply side, the industry is consolidating around three distinct competitive tiers. University-partnered credentialing platforms, horizontal marketplace operators, and creative-category specialists each occupy defensible positioning against generalist alternatives. Market participants execute competitive moves through M&A activity targeting regional content studios and strategic partnerships with enterprise learning and development departments.
Within the university-partnered tier, Coursera and edX exemplify premium certification pricing sustained through institutional affiliation. Udemy anchors the horizontal marketplace archetype with volume-driven positioning across consumer and enterprise tiers. Skillshare occupies a defensible niche in creative-category specialization that differentiates against generalist platforms. These three company structures illustrate the segmentation logic governing competitive positioning in asynchronous digital education.
| Leading Market Players |
|---|
| LinkedIn Learning |
| Thinkific |
| Udemy |
| Kajabi |
| Teachable |
| Coursera |
| Skillshare |
| iSpring LMS |
| edX |
| Others |
Value Chain & Pricing Dynamics
GDPR data localization requirements function as a regulatory chokepoint that simultaneously widens pricing spreads between EU-sovereign and standard cloud tiers while forcing supply chain reconfiguration toward Frankfurt and Dublin data centers. This regulatory friction compresses margins for platforms maintaining unified global infrastructure while rewarding those with preemptive regional deployment.
Pricing Analysis
Certification level creates the primary spread between premium university-partnered credentials and unvetted marketplace content. Three-tier pricing structure across premium, standard, and economy levels aligns with proctoring rigor and employer recognition depth. Cost compression in the economy tier intensifies as low-barrier instructor uploads flood supply. Corporate learning and development departments exhibit lowest price sensitivity due to tuition reimbursement structures, while individual lifelong learners demonstrate highest elasticity.
Supply Chain Analysis
Cloud infrastructure provisioning concentrates among hyperscale providers operating EU-sovereign, US-standard, and India-domestic availability zones. Instructional video production draws from specialized talent clusters in San Francisco, London, and Bangalore. Single-source vulnerability in motion graphics and learning science expertise elevates wage arbitrage risk. Distribution runs through direct enterprise sales teams and self-serve marketplace platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise reskilling mandates across Germany, India, and the United States are driving a cyclical recovery in corporate training expenditure, with procurement authority consolidating through Fortune 500 learning and development departments.
For Market Incumbents: Pre-empt credential dilution risk by tightening instructor vetting protocols and investing in blockchain-verified completion records. Vertical integration into regional production studios in São Paulo and Riyadh secures first-mover positioning in underpenetrated markets. Channel control through preferred provider arrangements with human resources departments locks in volume commitments. For New Entrants and Emerging Players: Brazil's ANVISA-regulated healthcare continuing education gap offers immediate white-space access with localized Portuguese content. Saudi Arabia's Tamheer program subsidies redirect procurement toward Arabic-language platforms with gender-segregated delivery modes. A direct-to-enterprise sales motion targeting midsize automotive suppliers in Germany bypasses saturated consumer acquisition channels. For Investors and Strategic Acquirers: India's Digital Personal Data Protection Act reshapes the acquisition landscape by elevating platforms with domestic cloud infrastructure and resident data protection officers. Long-term viability favors regional content studios with proven localization capabilities and established enterprise relationships. The signal to watch is enforcement patterns around cross-border data flow restrictions in China's SAMR framework.| Strategic Initiative | Industry Significance |
|---|---|
| EU-Sovereign Cloud Deployment | GDPR localization mandates in Germany and France require Frankfurt-resident infrastructure for enterprise procurement eligibility. |
| Regional Content Studio Acquisition | Brazil's ANVISA healthcare certification gap rewards Portuguese-language production capabilities in São Paulo. |
| Blockchain Verification Integration | India's IT outsourcing sector prioritizes immutable credential records for client-facing role placement. |
| Enterprise SSO Partnership | Fortune 500 learning and development departments mandate consolidated analytics dashboards for vendor consolidation. |
| AI-Assisted Personalization Launch | Large language model convergence with xAPI learning records enables real-time competency gap analysis for financial services pilots. |
Study Parameters
Desk research of regulatory filings, hyperscaler infrastructure disclosures, and enterprise procurement databases preceded structured interviews with chief learning officers, instructional design directors, cloud architects, and data protection officers. Primary fieldwork across Germany, India, and the United States validated secondary estimates of corporate training budget allocation. Bottom-up platform revenue triangulation against top-down enterprise expenditure surveys anchored volume estimates.
Assumptions held fixed include prevailing GDPR enforcement intensity, continuation of Germany's Qualifizierungschancengesetz subsidy mechanisms, and sustained Fortune 500 tuition reimbursement prevalence. Variables tested across the projection horizon encompass India's Digital Personal Data Protection Act implementation rigor, SAMR cross-border data flow restrictiveness, and Saudi Vision 2030 localization investment velocity. Segmentation modeling incorporated delivery mode, target audience, content type, and technology stack dimensions. CAGRs derived from logistic adoption curve fitting against historical corporate learning management system deployment patterns.
Practitioners should monitor regulatory enforcement divergence across EU, India, and China jurisdictions for early signals of infrastructure reconfiguration necessity. Forecasts reflect assumptions about sustained employer-sponsored procurement channel dominance and stable content production cost structures. Quarterly review of GDPR fine issuance patterns, India's data localization compliance deadlines, and SAMR professional certification platform registration requirements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Digital Marketing Courses Market