
 Highway Crash Cushion Market | 2026-2036
Highway Crash Cushion Market Size, Share, and Industry Trends Forecast 2026-2036
Highway Crash Cushion Market Insights
Aftermarket service revenue is reshaping competitive dynamics in the highway crash cushion sector. Trinity Highway Products leverages its captive installation network to sustain recurring maintenance contracts across state DOT portfolios. Energy Absorption Systems anchors its position through specialized MASH-compliant product lines that dominate high-speed freeway deployments. Hill & Smith Holdings extends its geographic footprint through controlled distribution channels in North American municipal markets.
Highway crash cushions are engineered kinetic energy management devices constructed from steel, aluminum, composite, or water-filled assemblies designed to decelerate errant vehicles through controlled deformation or momentum transfer. These systems undergo rigorous impact testing under NCHRP 350 or MASH criteria to validate occupant risk thresholds and structural performance at designated design speeds. The energy-absorbing type commands premium positioning due to reusable cartridge systems that reduce lifecycle replacement costs for transportation authorities. Steel and aluminum materials retain volume leadership, though composite formulations gain traction where corrosion resistance and reduced dead load prove critical for bridge-mounted or salt-exposure applications.
The Federal Highway Administration coordinates with state DOTs to enforce MASH compliance timelines, while AASHTO publishes design specifications that directly influence procurement criteria and product qualification pathways. The National Cooperative Highway Research Program continuously revises test protocols, forcing manufacturers to recertify legacy designs and absorb development overhead. Stakeholders must monitor pending infrastructure appropriations and evolving state-level Buy America waivers that could alter domestic sourcing requirements and competitive access.
Market Dynamics
Federal MASH compliance deadlines are compressing replacement cycles for legacy NCHRP 350-certified systems, forcing state DOTs to accelerate procurement timelines and manufacturers to absorb recertification costs.
Growth Catalysts
- MASH Testing Mandates:The Federal Highway Administration's full MASH implementation timeline requires state transportation departments to replace non-compliant end terminals, generating sustained replacement demand through federally coordinated infrastructure programs.
- Steel Price Stabilization:Moderating domestic steel input costs are restoring margin visibility for manufacturers of steel-reinforced crash cushion assemblies, enabling volume commitments from price-sensitive municipal buyers.
- Composite Material Advances:Pultruded fiberglass formulations with salt-spray resistance exceeding aluminum specifications are capturing specification share in coastal highway corridors and bridge-mounted applications.
Market Restraints
- Aluminum Tariff Exposure:Section 232 import duties on primary aluminum ingot continue pressuring cost structures for manufacturers dependent on extruded aluminum energy-absorbing cartridges.
- Testing Facility Bottlenecks:MASH certification queue times at Texas A&M Transportation Institute and other approved facilities extend product launch timelines by eight to fourteen months.
- Water-Filled System Substitution:Temporary water-filled barrier systems compete for work-zone protection contracts, displacing permanent crash cushion installations in short-duration construction projects.
Strategic Opportunities
- Midwest Interstate Expansion:Ohio and Indiana DOT five-year capital programs include systematic median crossover protection upgrades, creating concentrated deployment windows for TL-3 compliant systems.
- Connected Infrastructure Integration:Embedded impact sensors with real-time structural health monitoring are enabling predictive maintenance contracts that extend beyond hardware supply into recurring service revenue.
- Buy America Waiver Optimization:Strategic positioning against pending FHWA domestic content requirement adjustments could unlock competitive access for manufacturers with flexible North American supply configurations.
Industry Challenges
- Specialized Installation Labor Scarcity:Certified crash cushion deployment crews with MASH-compliant anchoring expertise command premium wages, constraining contractor capacity during peak construction seasons.
- Legacy Inventory Stranding:State DOT warehouse systems hold pre-MASH certified units that must be written down or retrofitted, complicating procurement planning and budget allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Highway Crash Cushion Market |
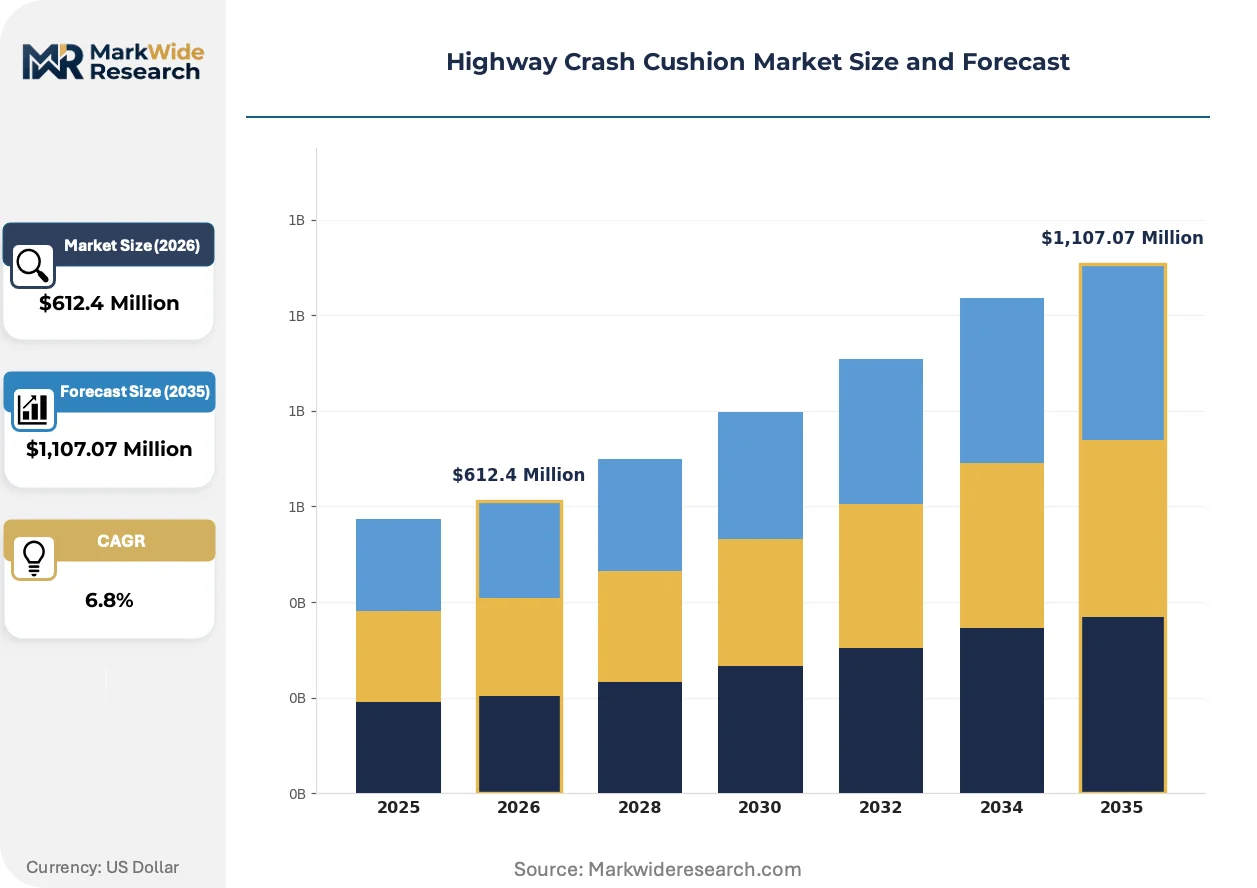
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Rigid, Flexible, Water-Filled, Energy-Absorbing Material: Polycarbonate, Steel, Aluminum, Composite Application: Highways, Freeways, Urban Roads, Construction Sites End User: Transportation Authorities, Contractors, Engineering Firms, Municipalities |
| Companies Covered | Trinity Highway Products, Barrier Systems, Energy Absorption Systems, Road Systems, Lindsay Corporation, Valmont Industries, Hill & Smith Holdings, Valtir, Shindo Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Highway Crash Cushion Market Trends and Innovations
Modular cartridge architectures and embedded sensing capabilities are redefining product value propositions away from passive hardware toward performance-guaranteed service models.
Tension-based cable redirective systems are collapsing the traditional trade-off between reusability and occupant risk metrics. State DOTs in hurricane-prone corridors are specifying these systems for high-frequency impact locations where cartridge replacement logistics prove prohibitive. The technology is collapsing service-interval requirements from quarterly inspection cycles to continuous remote monitoring.
MASH 2016 updates with revised occupant risk criteria are forcing manufacturers to redesign end terminal geometries. The Federal Highway Administration coordinates enforcement timelines with state DOTs, compressing grandfathering periods for legacy NCHRP 350 products. High-speed freeway applications face the most acute compliance pressure, with several states advancing procurement deadlines by eighteen months.
Performance-based contracting is displacing traditional unit-price procurement at state DOTs with mature asset management programs. Texas and Florida transportation departments now specify impact-absorption guarantees over fixed hardware replacement schedules. This shift concentrates vendor selection on lifecycle cost modeling rather than upfront capital expenditure.
Highway Crash Cushion Market Segmentation
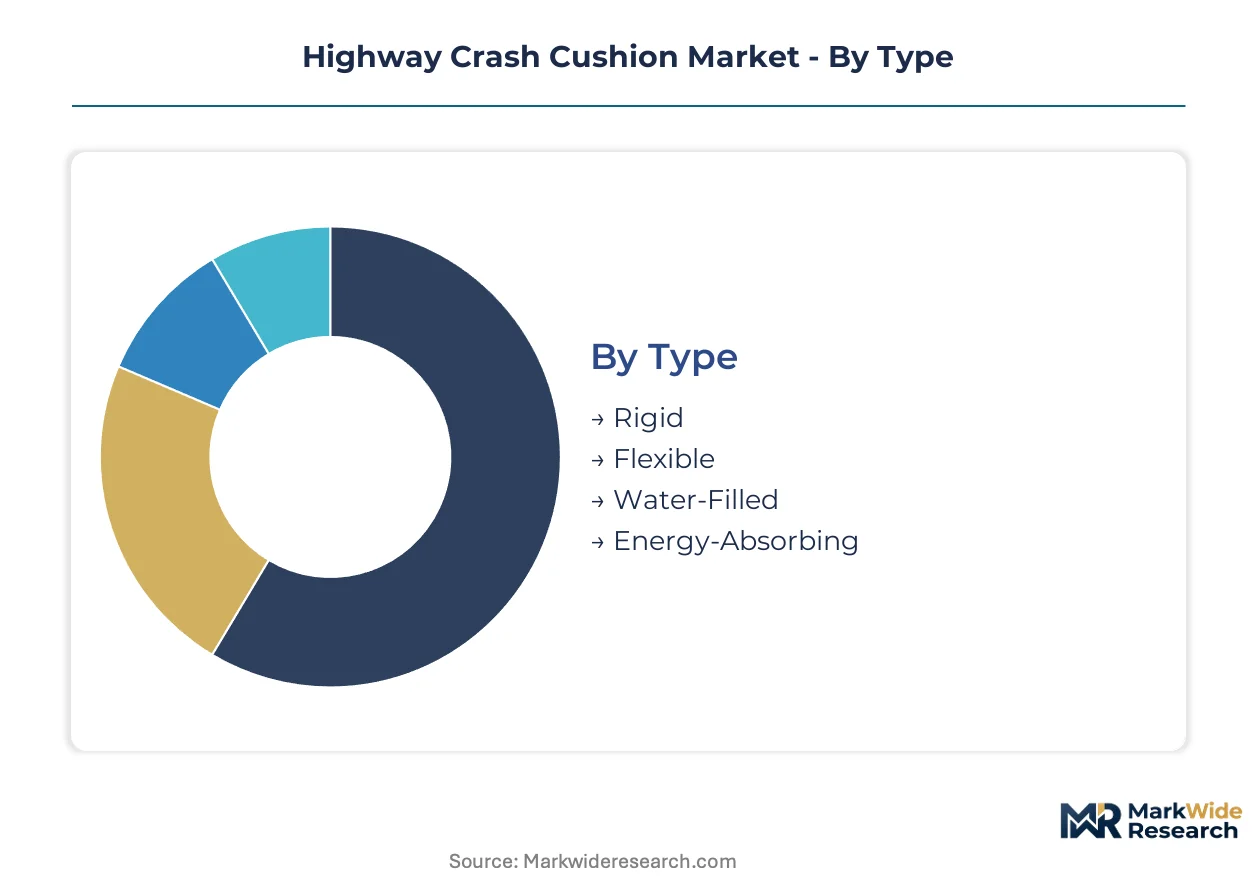
Segmentation in the highway crash cushion market reveals distinct replacement cycles and specification requirements that shape procurement patterns across state transportation departments. Understanding these divisions enables manufacturers to align product development with the divergent priorities of high-speed freeway deployments versus temporary work-zone installations.
Type:
Replacement cycles vary dramatically by type, with rigid systems offering decades of service life while water-filled units turn over within single construction seasons.
- Energy-Absorbing:Reusable cartridge systems with controlled deformation mechanisms dominate high-speed freeway applications. State DOTs in Texas and Florida specify these for median crossover protection where frequent impacts demand rapid restoration capability. MASH compliance mandates are compressing procurement timelines for these systems.
- Rigid:Concrete or steel monolithic assemblies provide permanent protection at fixed hazard locations. These systems anchor volume in bridge abutment and toll plaza applications where deflection space is constrained and maintenance access is limited.
- Flexible:Tension-based cable redirective systems collapse on impact and rebound without component replacement. Hurricane-prone southeastern corridors specify these for high-frequency impact zones where cartridge logistics prove prohibitive.
- Water-Filled:Temporary barrier systems deploy for short-duration construction projects. These units compete directly with permanent crash cushions on work-zone contracts and displace fixed installations where project timelines run under 180 days.
Rigid systems anchor the volume base while energy-absorbing configurations gain share at the steepest rate.
Material:
Cost tiers separate material selection, with steel and aluminum commanding premium positioning against emerging composite alternatives.
- Steel:Reinforced steel assemblies retain specification dominance in high-impact freeway applications. Moderating domestic input costs are restoring margin visibility for manufacturers serving price-sensitive municipal buyers in the Midwest.
- Composite:Pultruded fiberglass formulations with salt-spray resistance exceeding aluminum specifications capture share in coastal highway corridors. Bridge-mounted applications favor these materials where reduced dead load and corrosion immunity justify procurement premiums.
- Aluminum:Extruded aluminum energy-absorbing cartridges face Section 232 tariff pressure on primary ingot imports. Manufacturers dependent on aluminum inputs are absorbing cost volatility or reformulating around hybrid material architectures.
- Polycarbonate:Transparent or translucent barrier components serve specialized visibility applications. These materials occupy niche positioning where aesthetic integration or sightline preservation drives specification decisions.
Steel anchors the volume base while composite formulations climb the fastest among material categories.
Application:
Application segmentation tracks speed-tier requirements and regulatory jurisdiction, with freeway deployments facing the most stringent MASH compliance pressure.
- Freeways:Designated high-speed corridors with posted limits exceeding 55 mph require TL-3 compliant systems with validated occupant risk thresholds. Ohio and Indiana DOT capital programs are driving concentrated deployment windows for median protection upgrades.
- Highways:Interstate and primary arterial routes with mixed traffic volumes represent the core installed base. Federal MASH implementation timelines are forcing systematic replacement of legacy NCHRP 350-certified end terminals across state portfolios.
- Construction Sites:Temporary work-zone protection contracts favor rapid-deployment systems with minimal anchoring requirements. Water-filled and portable energy-absorbing units compete aggressively for these project-based procurements.
- Urban Roads:Lower-speed municipal applications with constrained right-of-way favor compact redirective systems. City transportation departments prioritize systems with reduced foundation footprints and simplified maintenance protocols.
Highway applications anchor the volume base while freeway specifications expand most quickly under compliance pressure.
End User:
Customer type determines procurement method, with transportation authorities employing centralized bidding versus contractor-driven spot purchasing.
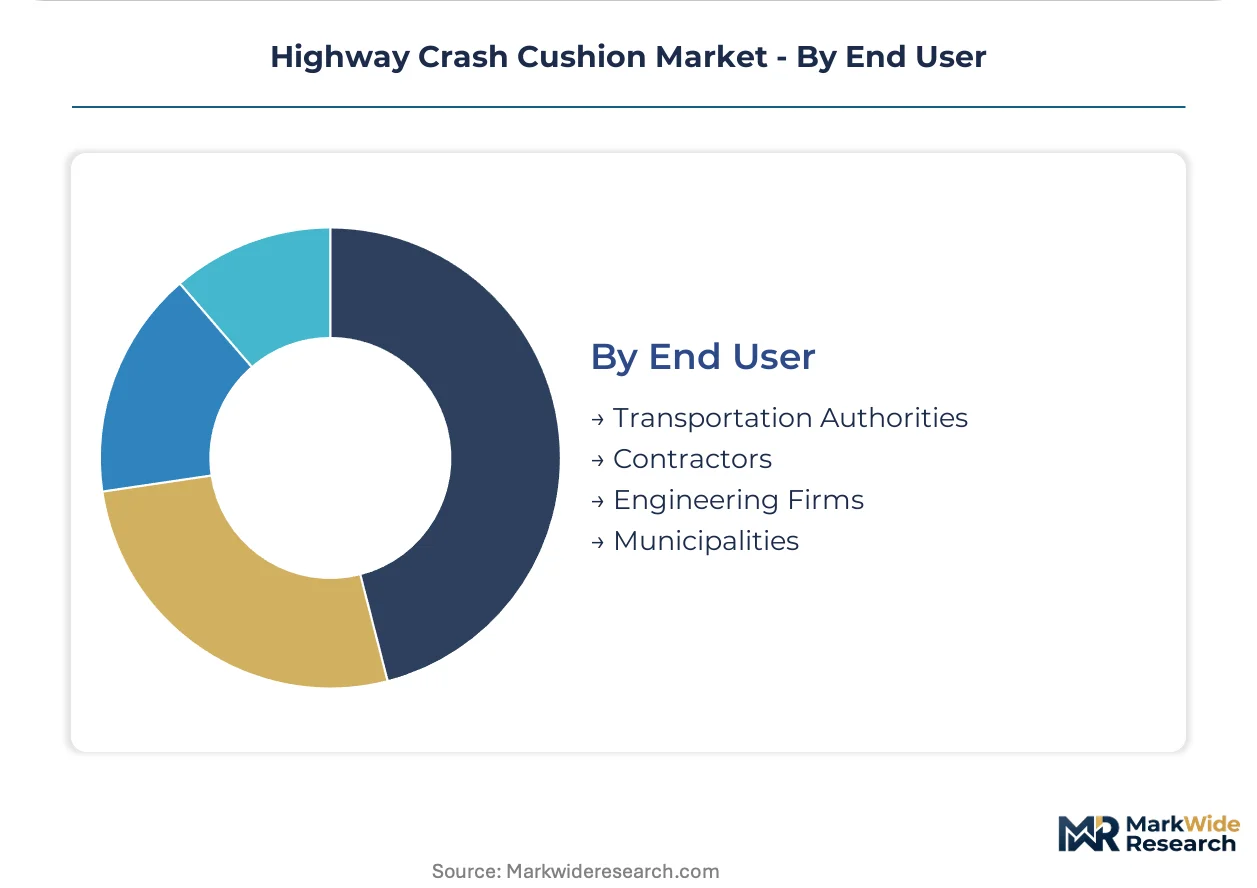
- Transportation Authorities:State DOTs coordinate federally mandated infrastructure upgrades through multi-year capital programs. These buyers specify lifecycle cost models and performance-based contracting with impact-absorption guarantees replacing fixed replacement schedules.
- Contractors:Construction firms procure temporary protection systems for project-specific deployment. These end users prioritize rental and lease structures over capital purchase, favoring vendors with rapid logistics and installation support.
- Municipalities:City and county governments manage localized road safety improvements with constrained maintenance budgets. These buyers exhibit price sensitivity and favor simplified systems with reduced inspection requirements.
- Engineering Firms:Design consultants influence specification through roadway design and safety audit engagements. These stakeholders drive adoption of emerging technologies including embedded sensing and predictive maintenance capabilities.
Transportation authorities anchor the volume base while contractor procurement is expanding most quickly through performance-based service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State DOT procurement elasticity varies sharply across geographies, with hurricane-recovery corridors absorbing premium pricing for rapid-deployment systems while Midwestern authorities enforce aggressive cost benchmarking on standardized median protection contracts.
United States
Federal MASH compliance deadlines are compressing replacement cycles for legacy NCHRP 350-certified systems across state transportation departments. The FHWA coordinates enforcement timelines that accelerate procurement in high-speed freeway corridors. Texas DOT capital programs concentrate deployment windows for TL-3 compliant energy-absorbing systems in the Dallas-Fort Worth and Houston metropolitan corridors.
Canada
Provincial transportation authorities in Ontario and Quebec are advancing systematic highway safety upgrades through multi-year infrastructure commitments. Transport Canada aligns with AASHTO design specifications while adapting MASH protocols for winter climate performance validation. The Greater Toronto Area anchors specification development for composite material systems in salt-exposure applications.
Germany
The KBA enforces rigorous passive safety certification for roadside infrastructure deployed on Autobahn corridors with unlimited speed segments. German state road construction administrations prioritize lifecycle cost modeling over upfront capital expenditure in procurement frameworks. The Stuttgart industrial cluster concentrates engineering expertise for tension-based redirective systems with continuous structural health monitoring.
Australia
State road authorities in New South Wales and Victoria are expanding median protection upgrades on Pacific Highway and Hume Highway corridors. Austroads publishes design specifications that reference MASH criteria while incorporating local vehicle fleet characteristics. Sydney-based engineering consultancies drive adoption of embedded impact sensors for predictive maintenance contracting models.
Japan
METI coordinates national expressway safety standardization through the Japan Road Association's design guidelines. Prefecture-level maintenance budgets prioritize systems with reduced foundation footprints for constrained urban right-of-way conditions. The Nagoya-Chubu corridor concentrates manufacturing capacity for pultruded fiberglass composite formulations with seismic resilience specifications.
Highway Crash Cushion Market Competitive Landscape
Capability concentration sits with specialized testing and certification providers; scale advantage sits with integrated highway infrastructure conglomerates. The market structures around three tiers: captive installation networks with recurring service contracts, MASH-compliant product specialists with approved testing relationships, and diversified metal fabricators with cross-selling opportunities into municipal markets. Dominant competitive moves include strategic partnerships with state DOTs for performance-based contracting and selective vertical integration into installation labor pools.
Among North American specialists, Trinity Highway Products, Energy Absorption Systems, and Hill & Smith Holdings occupy distinct positioning archetypes. Trinity Highway Products exemplifies the captive-network model through controlled deployment infrastructure. Energy Absorption Systems represents the certification-specialist tier with concentrated MASH testing relationships. Hill & Smith Holdings anchors the diversified fabricator category with cross-border distribution capabilities. These three entities collectively illustrate how procurement consolidation at state DOTs rewards scale in compliance overhead absorption.
| Leading Market Players |
|---|
| Trinity Highway Products |
| Barrier Systems |
| Energy Absorption Systems |
| Road Systems |
| Lindsay Corporation |
| Valmont Industries |
| Hill & Smith Holdings |
| Valtir |
| Shindo Industry |
| Others |
Pricing and Supply Chain Analysis
The I-35 freight corridor from Laredo to Dallas-Fort Worth anchors steel and aluminum logistics for crash cushion manufacturers, with fuel surcharge volatility feeding directly into both supply concentration among Gulf Coast metal fabricators and downstream price stratification between state DOT long-term contracts and municipal spot purchases.
Pricing Analysis
Long-term offtake agreements with state transportation departments dominate the pricing architecture, locking in volume commitments that insulate manufacturers from raw material swings while compressing margins for spot-market municipal buyers. Price differentiation rests on MASH certification tier and installation service bundling, with fully certified systems commanding substantial premiums over grandfathered NCHRP 350 inventory. Pricing pressure stems from Section 232 aluminum tariff exposure that manufacturers have only partially passed through. State DOTs exhibit the lowest price sensitivity given federal infrastructure funding backstops, while county municipal buyers enforce aggressive cost benchmarking.
Supply Chain Analysis
Tariff exposure between Canada and the United States on primary aluminum ingot dominates supply chain risk calculus for energy-absorbing cartridge producers. Manufacturing concentrates in Texas, Ohio, and Ontario, with these jurisdictions anchoring fabrication capacity for steel-reinforced assemblies and composite pultrusion operations. Raw material dependencies center on domestic hot-rolled steel coil, extruded aluminum sections, and fiberglass resin systems. Single-source vulnerability runs through approved MASH testing facilities that gate product launch timelines. Distribution runs through captive installation networks controlled by major manufacturers and independent highway contractors serving temporary work-zone deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The highway crash cushion market is recovering from cyclical infrastructure investment troughs, with federal MASH compliance deadlines now compressing replacement cycles and forcing accelerated procurement across state DOT portfolios.
For Market Incumbents: Harden MASH certification pipelines at Texas A&M Transportation Institute and competing approved facilities to secure product launch timelines against testing queue bottlenecks. Deepen backward integration into captive installation labor pools to defend service revenue streams from emerging competitors with asset-light deployment models. The priority lever centers on predictive maintenance contracts with embedded sensor technology that extends vendor relationships beyond hardware replacement cycles. For New Entrants and Emerging Players: Establish a beachhead in temporary water-filled barrier rentals for short-duration construction projects, where incumbent manufacturers underinvest due to lower margin profiles. Target municipal urban road segments with compact redirective systems that require reduced foundation footprints and simplified maintenance protocols. The most penetrable entry angle combines rapid logistics capabilities with lease-to-own structures that match contractor cash flow constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified metal fabricators with crash cushion divisions that lack dedicated MASH testing relationships or captive installation infrastructure. Long-term viability over the coming decade hinges on positioning against performance-based contracting displacement of unit-price procurement at mature state DOTs. The critical inflection signal to monitor is FHWA domestic content requirement adjustments that could unlock competitive access for manufacturers with flexible North American supply configurations.| Strategic Initiative | Industry Significance |
|---|---|
| MASH Certification Pipeline Investment | Testing queue access at Texas A&M Transportation Institute accelerates product launch timelines against competitors. |
| Embedded Sensor Technology Deployment | Real-time impact monitoring enables predictive maintenance contracts extending beyond hardware supply. |
| Captive Installation Network Expansion | Controlled deployment crews with MASH-compliant anchoring expertise secure recurring service revenue. |
| Composite Material Formulation R&D | Pultruded fiberglass with salt-spray resistance captures coastal highway and bridge-mounted specifications. |
| Performance-Based Contracting Capability | Impact-absorption guarantees align with Texas and Florida DOT procurement shifts away from unit-price models. |
Research Methodology
Desk research of FHWA infrastructure appropriations records, state DOT capital program disclosures, and AASHTO design specification archives preceded structured interviews with state transportation procurement officers, crash cushion product engineering directors, certified installation contractors, and municipal road maintenance supervisors. Secondary validation drew from NCHRP technical reports, MASH testing facility certification databases, and federal Buy America waiver filings. Bottom-up demand modeling across application segments was triangulated against top-down infrastructure spending forecasts.
Assumptions around federal MASH compliance enforcement timelines, steel and aluminum input cost trajectories, and state DOT procurement method evolution were held fixed across baseline scenarios while stress-tested against accelerated replacement schedules and tariff regime shifts. The analytical framework modeled volume and value outputs across type, material, application, and end-user segmentation dimensions. CAGRs were derived from replacement cycle analysis and infrastructure appropriation trajectories, with composite material adoption curves and connected infrastructure penetration serving as industry-specific forecast inputs.
Stress conditions across federal funding continuity, raw material tariff exposure, and MASH testing facility capacity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledgment that regulatory enforcement delays, state-level budget freezes, or breakthrough redirective system technologies could materially revise projected trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Vehicle Barrier System Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Adaptive Headlights Market