
 Asia-Pacific Seasoning and Spices Market | 2026-2036
Asia-Pacific Seasoning and Spices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Seasoning and Spices Market Outlook
Precision fermentation and enzyme-assisted extraction is reconfiguring how flavor compounds are isolated and standardized across the Asia-Pacific seasoning supply chain. Olam International leverages integrated sourcing networks from Vietnam and Indonesia to control raw material quality at origin. McCormick & Company anchors its regional competitiveness through R&D facilities in India that adapt global formulations to local heat and aroma profiles. Everest Food Products Pvt Ltd. differentiates via deep specialization in whole-spice grinding traditions tied to North Indian culinary identity.
Asia-Pacific seasoning and spices encompass dried botanicals, oleoresins, essential oils, and compounded flavor systems used to enhance taste, preserve food, and signal regional culinary authenticity. Steam distillation and supercritical CO2 extraction yield volatile oil concentrations ranging from 0.5% to 15% by weight depending on source material and intended application. Blends command margin concentration due to proprietary formulations and brand loyalty, while pouches and sachets gain traction in retail channels serving price-sensitive urban consumers. The foodservice end user segment leads volume absorption as chained restaurants and cloud kitchens standardize flavor outputs across dispersed kitchens.
India's FSSAI enforces pesticide residue ceilings and ethylene oxide bans that directly determine export eligibility for Kashmiri saffron and Malabar pepper consignments. Japan's Ministry of Health, Labour and Welfare applies positive list systems for food additives that constrain which oleoresin carriers enter processed food formulations. China's SAMR implements GB standards for heavy metal limits in imported spice shipments, creating compliance filtration at port of entry. Stakeholders must monitor regulatory divergence on irradiation permissions and labeling thresholds as these rules increasingly partition market access across the region.
Market Dynamics
Precision fermentation is collapsing the cost curve for high-value oleoresin production, forcing traditional solvent extraction facilities across India and Vietnam to retool or exit. This technological rupture coincides with tightening residue limits from India's FSSAI and Japan's positive list systems, compressing margins for non-compliant processors.
Growth Catalysts
- Ethylene oxide phase-out mandates:India's FSSAI maximum residue limits are accelerating investment in steam sterilization infrastructure among Kashmiri saffron and Malabar pepper exporters seeking EU and Gulf market access.
- Cloud kitchen standardization:Foodservice operators across Southeast Asia are locking in multi-year oleoresin supply contracts to ensure flavor consistency across dispersed ghost kitchen networks.
- Supercritical CO2 extraction:This solvent-free technology is capturing premium positioning in Japanese and South Korean retail channels where clean-label claims command shelf price premiums.
Market Restraints
- Raw material concentration:Vietnam and Indonesia supply over sixty percent of global black pepper and clove inputs, exposing processors to climate-driven harvest volatility and origin price spikes.
- Irradiation regulatory fragmentation:Australia's TGA permits gamma irradiation for microbial reduction while India's FSSAI maintains stricter approval thresholds, forcing dual-track processing investments.
- Synthetic flavor substitution:Encapsulated nature-identical compounds from fermentation are displacing mid-tier spice extracts in mass-market snack seasoning applications.
Strategic Opportunities
- Philippines foodservice penetration:Jollibee and local cloud kitchen aggregators are underdeveloped buyers for standardized curry and adobo seasoning systems versus saturated Thai and Vietnamese markets.
- PLI scheme alignment:India's production-linked incentive scheme for food processing offers capital subsidy coverage for spice oleoresin and essential oil extraction capacity expansion.
- Blockchain-IoT traceability convergence:Kerala cardamom and Gujarat cumin cooperatives are piloting combined sensor networks and distributed ledger systems to preempt EU deforestation regulation compliance requirements.
Industry Challenges
- Chromatography technician scarcity:FSSAI-mandated pesticide residue testing requires gas chromatography-mass spectrometry operators that Gujarat and Kerala processing clusters cannot source at scale.
- Legacy grinding equipment retrofit costs:Whole-spice traditions at family-owned mills in North India face seven-figure capital outlays to install metal detection and X-ray sorting for export compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Seasoning and Spices Market |
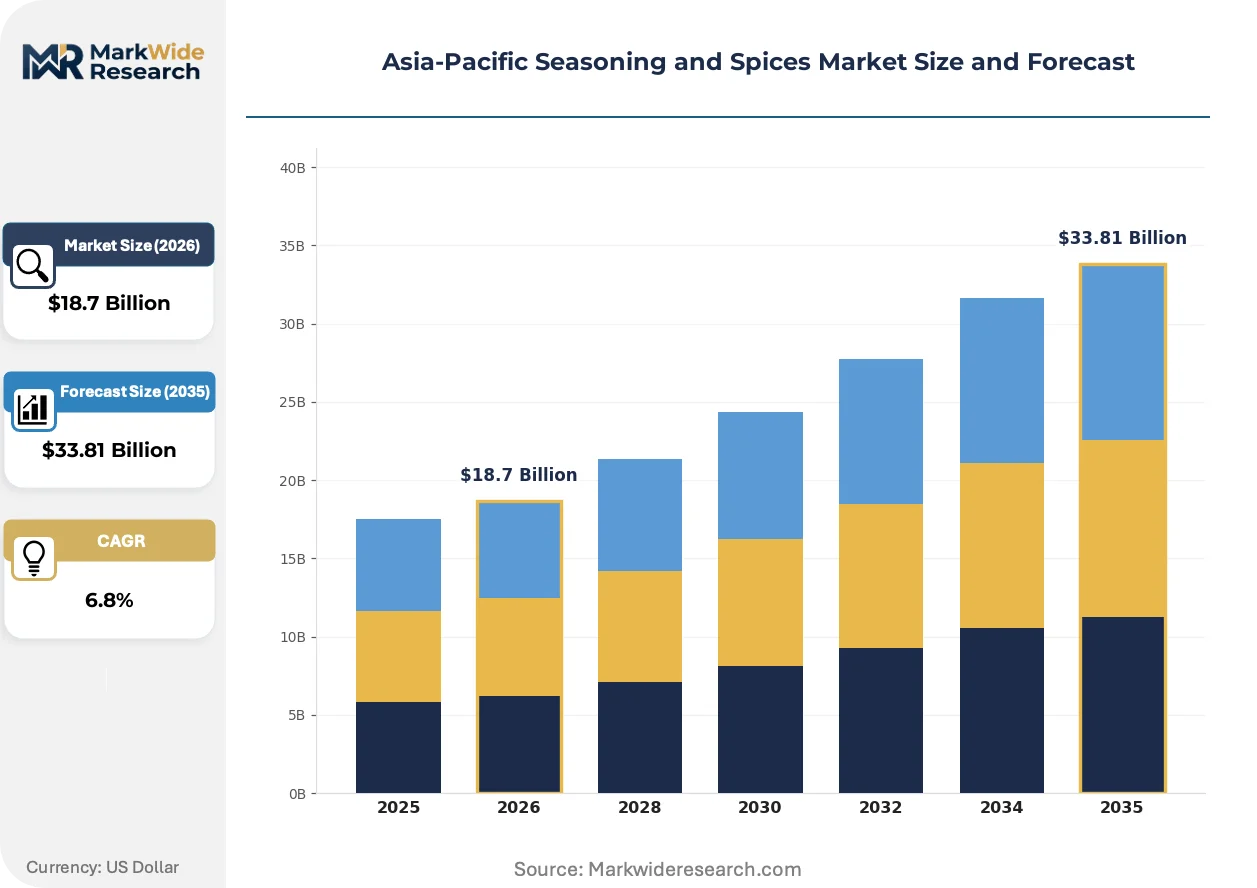
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Spices, Condiments, Blends End User: Food Industry, Retail, Foodservice, Home Cooking Packaging Type: Bottles, Pouches, Sachets, Jars Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Olam International, Kikkoman Corporation, McCormick & Company, Inc., Dohler GmbH, Everest Food Products Pvt Ltd., Kerry Group PLC, Sensient Technologies Corporation, DS Group, Ajinomoto Co., Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Seasoning and Spices Market Strategic Shifts
Bioprocessing advances and traceability mandates are restructuring how flavor compounds are validated, priced, and traded across the Asia-Pacific seasoning value chain. These shifts favor capital-intensive operators capable of integrating laboratory verification with agricultural sourcing.
Enzyme-assisted extraction is collapsing the yield gap between artisanal cold-pressing and industrial solvent methods for heat-sensitive volatile oils. South Korean and Japanese seasoning manufacturers are adopting membrane filtration coupled with cellulase pre-treatment at pilot scale. This convergence is compressing the premium attached to traditional steam distillation for cardamom and nutmeg essential oils.
China's SAMR GB standards for heavy metal limits in imported spice shipments are forcing Southeast Asian exporters to install inductively coupled plasma mass spectrometry at port-side testing facilities. Indonesian clove and Vietnamese cinnamon processors bear the capital burden of in-house laboratory certification to avoid detention at Chinese entry ports. Medium-scale traders lacking testing infrastructure are exiting the China-bound trade lane entirely.
Restaurant procurement teams are consolidating supplier relationships from fragmented spot-market buying to annual framework agreements with certified oleoresin houses. This concentration is displacing traditional auction-house pepper and chili traders in Kochi and Ho Chi Minh City. The shift is most visible in Thailand's chained restaurant sector, where central commissaries now dictate single-source seasoning specifications to franchise outlets.
Asia-Pacific Seasoning and Spices Market Segmentation
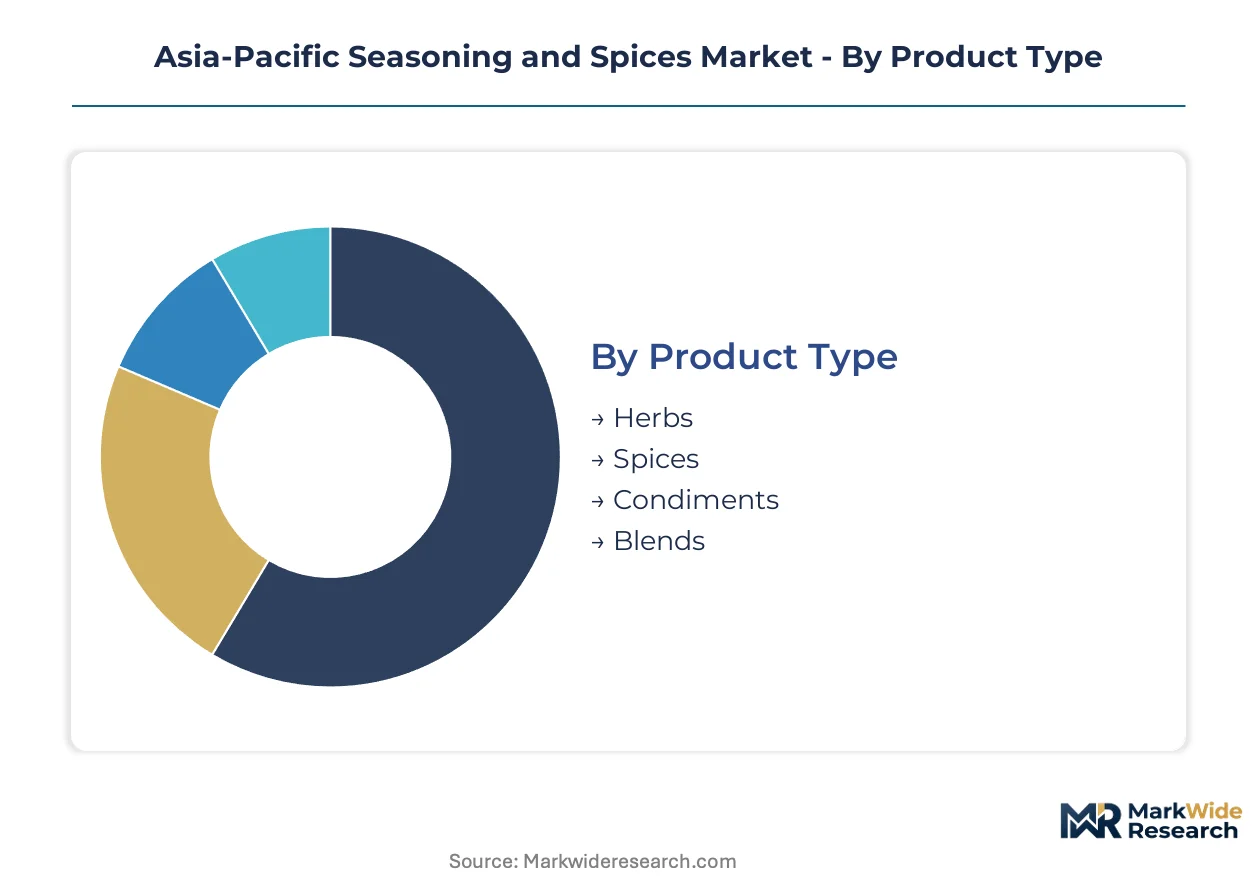
Segmentation in the Asia-Pacific seasoning and spices market reveals divergent margin structures and compliance burdens across product formats. Processing intensity, packaging specifications, and channel requirements create distinct operational profiles that determine competitive positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with oleoresin and essential oil extraction demanding sustained technical support for quality calibration.
- Herbs:Dried leafy botanicals including basil, oregano, and cilantro retain volatile oil concentrations between 0.3% and 2.5% by weight. Demand concentrates in Japan's retail channels where FSSAI-mandated residue documentation accompanies every import consignment.
- Spices:Whole and ground seed, bark, and rhizome products—black pepper, cinnamon, turmeric—carry higher per-kilogram value density. Kerala's Malabar pepper and Gujarat's cumin processing clusters supply standardized oleoresin inputs to South Korean and Japanese food manufacturers seeking batch-to-batch consistency.
- Condiments:Fermented and acidified preparations including soy sauce, fish sauce, and chili pastes require controlled microbial stabilization. Vietnam's anchovy-based fish sauce producers and China's fermented bean curd houses dominate regional supply.
- Blends:Proprietary compounded formulations for curry powders, five-spice, and garam masala command formulation premiums. McCormick's India R&D facilities and Everest's North Indian grinding traditions anchor competitive differentiation through recipe IP protection.
By volume, Spices leads. By growth pace, Blends is expanding most quickly as chained restaurants standardize proprietary formulations.
End User:
Cost tier stratification separates capital-intensive food industry buyers from fragmented home cooking segments with minimal quality verification requirements.
- Food Industry:Processed food manufacturers purchase oleoresins and essential oils in bulk tote quantities for snack seasoning and ready-meal applications. China's SAMR GB standards for heavy metal limits force Southeast Asian exporters to install inductively coupled plasma mass spectrometry at port-side testing facilities.
- Retail:Branded packaged goods sold through supermarkets and convenience stores carry clean-label certification premiums. South Korean and Japanese retail channels reward supercritical CO2 extraction claims with shelf price positioning above solvent-extracted alternatives.
- Foodservice:Chained restaurants, cloud kitchens, and institutional caterers demand batch-consistent seasoning systems. Thailand's central commissaries now dictate single-source specifications to franchise outlets, displacing traditional auction-house traders in Kochi and Ho Chi Minh City.
- Home Cooking:Individual consumers purchasing through traditional markets and modern trade. India's Gujarat and Kerala clusters serve this segment through loose-weight distribution with minimal processing overhead.
Foodservice absorbs the highest absolute volumes. Food Industry shows the steepest margin compression from regulatory compliance costs.
Packaging Type:
Application requirements drive format selection, with foodservice bulk handling favoring industrial totes and retail convenience demanding single-serve portability.
- Bottles:Glass and PET containers for liquid condiments and oil-based seasonings. Japan's Ministry of Health, Labour and Welfare positive list systems constrain which oleoresin carriers enter these formulations.
- Pouches:Flexible laminate structures for ground spices and wet pastes. Southeast Asian urban consumers favor this format for price-sensitive pantry stocking.
- Sachets:Single-serve portions for foodservice condiment dispensing and airline catering. Cloud kitchen aggregators across the Philippines and Indonesia specify sachet formats for standardized flavor dosing.
- Jars:Rigid plastic and glass containers for premium whole-spice presentation. North Indian family-owned mills face seven-figure capital outlays to install metal detection and X-ray sorting for export-compliant jarred products.
Pouches dominate unit volume. Sachets are climbing fastest as ghost kitchen networks proliferate.
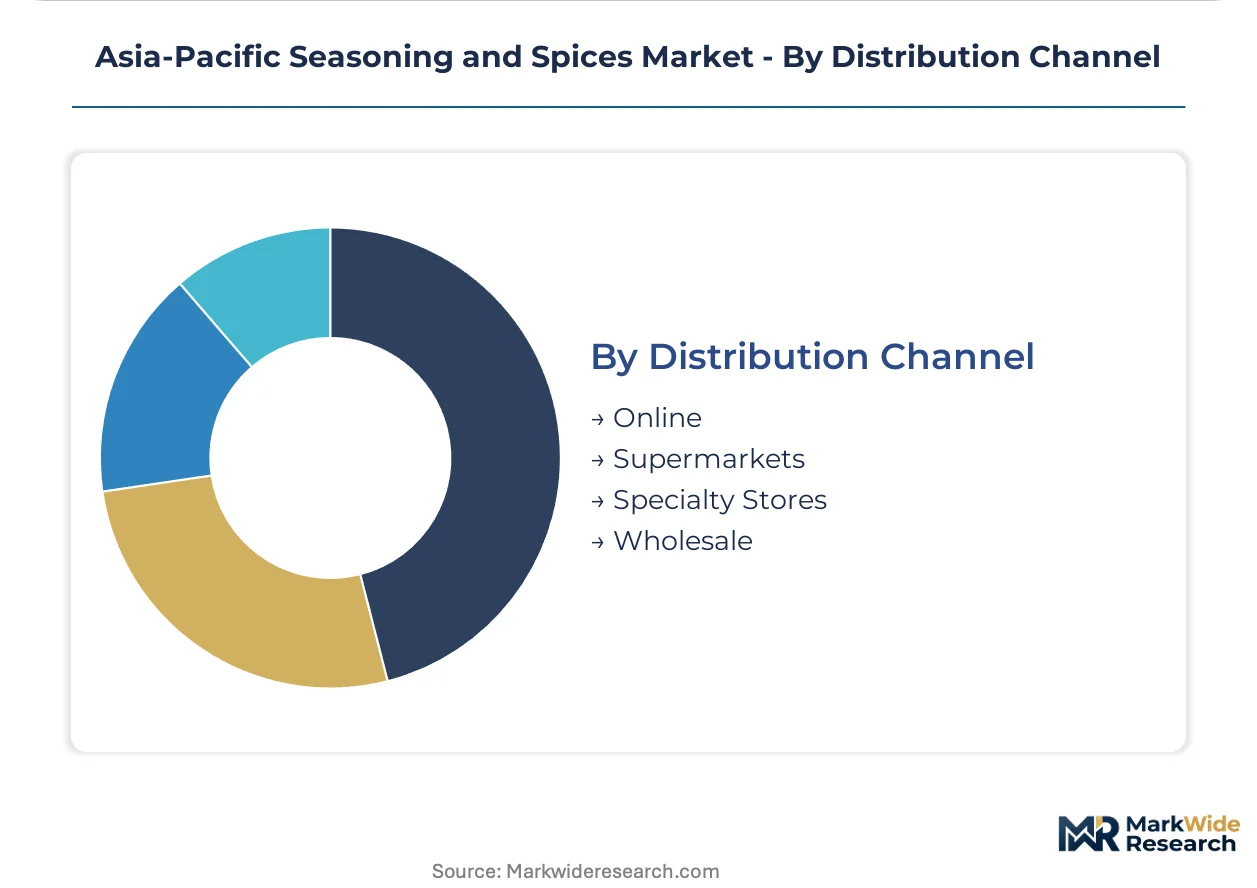
Distribution Channel:
Customer type fragmentation separates procurement professionals in wholesale from impulse-driven supermarket purchases.
- Online:E-commerce platforms and direct-to-consumer subscription services. India's FSSAI tightened maximum residue limits for ethylene oxide create documentation requirements that favor established brands with laboratory infrastructure.
- Supermarkets:Modern trade hypermarkets and grocery chains with centralized procurement. Kerala cardamom and Gujarat cumin cooperatives pilot blockchain-IoT traceability to preempt EU deforestation regulation compliance for this channel.
- Specialty Stores:Ethnic grocers, organic retailers, and gourmet provisions merchants. Clean-label positioning and origin storytelling command price premiums here.
- Wholesale:Bulk traders supplying food manufacturers, foodservice distributors, and traditional market vendors. Vietnam and Indonesia's concentration in black pepper and clove inputs exposes this channel to climate-driven harvest volatility.
Wholesale moves the largest tonnage. Online is gaining share fastest as urban consumers shift pantry stocking to digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across the Asia-Pacific seasoning and spices market are tightening regulatory scrutiny on residue limits and traceability documentation. Import-dependent markets in Northeast Asia are diversifying sourcing networks to reduce concentration risk in Vietnamese pepper and Indonesian clove supplies. Processing clusters in South Asia and Southeast Asia are capturing value-added margin through oleoresin extraction capacity expansion.
India
Gujarat's cumin processing cooperatives and Kerala's cardamom auction houses anchor regional supply of whole spices and essential oil feedstocks. India's FSSAI enforces pesticide residue ceilings and ethylene oxide bans that determine export eligibility for Kashmiri saffron and Malabar pepper consignments. The country's production-linked incentive scheme for food processing offers capital subsidy coverage for spice oleoresin extraction capacity expansion.
China
Domestic demand for compounded flavor systems in snack manufacturing and ready-meal production absorbs significant regional oleoresin output. China's SAMR implements GB standards for heavy metal limits in imported spice shipments, creating compliance filtration at port of entry. Sichuan's chili processing belt and Guangdong's sauce manufacturing corridor concentrate domestic blending and fermentation capacity.
Japan
Food manufacturers and retail channels prioritize clean-label positioning and batch-to-batch consistency in seasoning procurement. Japan's Ministry of Health, Labour and Welfare applies positive list systems for food additives that constrain which oleoresin carriers enter processed food formulations. Kansai-based seasoning houses and Tokyo-area foodservice distributors represent the primary demand aggregation points.
Vietnam
Black pepper harvest volatility and origin price spikes expose regional processors to climate-driven supply interruptions. The country's central highlands and Mekong Delta regions concentrate raw material sourcing for both export and domestic fish sauce fermentation. Vietnamese processors are installing steam sterilization infrastructure to meet tightening EU and Gulf market residue requirements.
South Korea
Retail channels reward supercritical CO2 extraction claims with shelf price premiums above solvent-extracted alternatives. The country's national food safety regulator maintains strict additive approval thresholds that shape oleoresin formulation choices. Seoul-based seasoning manufacturers and Busan-area import distributors dominate procurement of Indian and Southeast Asian spice inputs.
Asia-Pacific Seasoning and Spices Market Competitive Environment
On the supply side, the industry is bifurcated between capital-intensive integrated processors with laboratory verification capabilities and fragmented family-owned grinding operations facing compliance retrofit costs. Strategic archetypes include origin-controlling agricultural traders, formulation-specialist multinationals with regional R&D adaptation, and heritage-focused whole-spice traditionalists. Dominant competitive moves center on backward integration into controlled sourcing networks and technology licensing for clean-label extraction methods.
Within the integrated agricultural trading tier, Olam International and Kerry Group PLC represent archetypes of origin-controlling supply chain architecture. McCormick & Company, Inc. anchors the multinational formulation specialist position through regional R&D facilities that adapt global recipes to local heat and aroma profiles. Everest Food Products Pvt Ltd. occupies the heritage-focused traditionalist segment, exemplifying competitive differentiation through deep specialization in whole-spice grinding traditions tied to regional culinary identity.
| Leading Market Players |
|---|
| Olam International |
| Kikkoman Corporation |
| McCormick & Company, Inc. |
| Dohler GmbH |
| Everest Food Products Pvt Ltd. |
| Kerry Group PLC |
| Sensient Technologies Corporation |
| DS Group |
| Ajinomoto Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
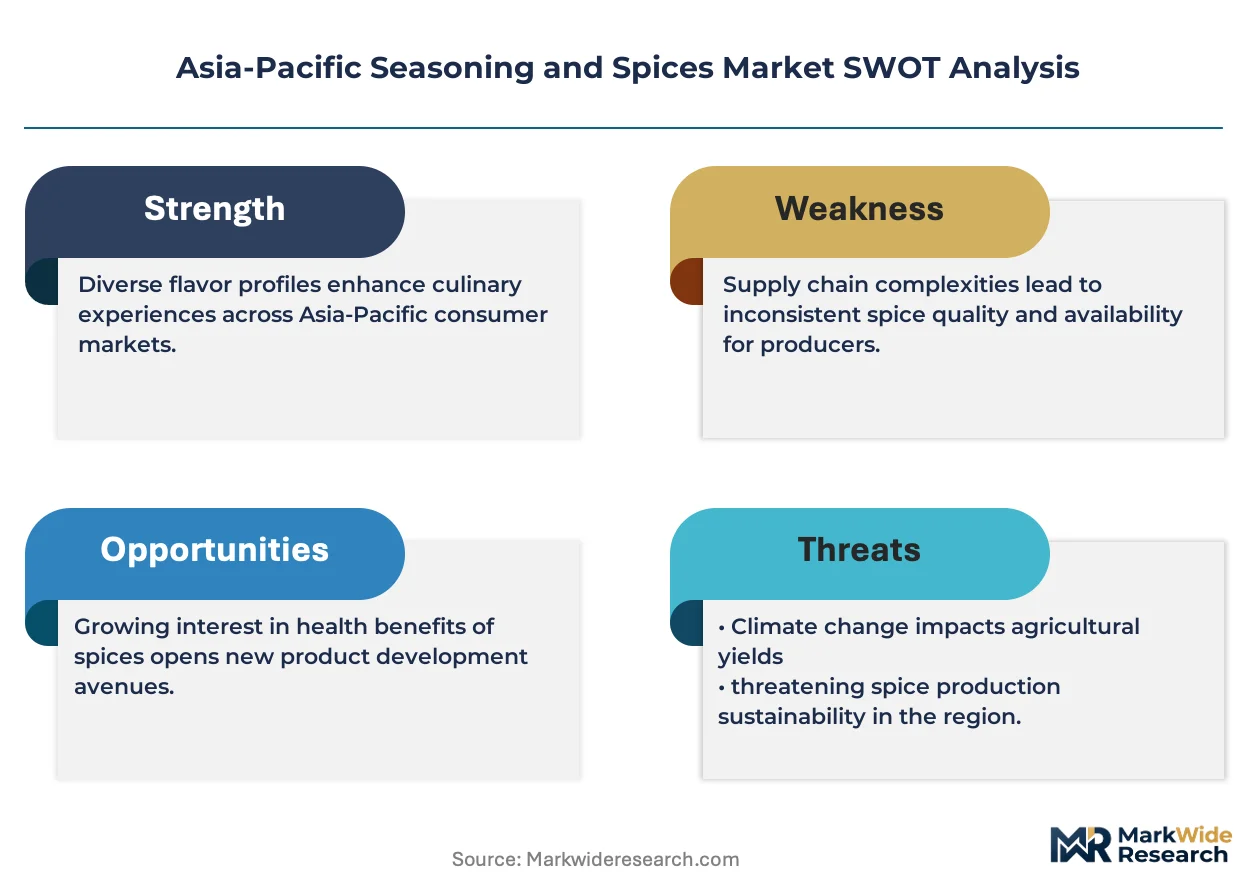
Single-source dependency on Vietnamese pepper and Indonesian clove harvests determines both pricing tier spreads and supply chain shape across the Asia-Pacific seasoning market. India's FSSAI ethylene oxide residue limits and China's SAMR heavy metal standards create regulatory chokepoints that widen the gap between certified premium oleoresins and unverified bulk commodities.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for oleoresin and essential oil procurement. Price differentiation rests on FSSAI certification tier and supercritical CO2 extraction claims that command shelf premiums in Japanese and South Korean retail channels. Cost compression in mid-tier solvent-extracted segments is intensifying because precision fermentation alternatives are collapsing yield economics. Home cooking segments through Gujarat and Kerala loose-weight markets show highest price sensitivity, while cloud kitchen aggregators prioritize batch consistency over unit cost.
Supply Chain Analysis
Vietnam, Indonesia, and India hold concentrated raw material sourcing capacity for black pepper, clove, and cumin inputs respectively. Processing infrastructure draws from cardamom rhizomes, cinnamon bark, and chili fruit feedstocks that flow through Kerala auction houses and Ho Chi Minh City trading posts. Single-source vulnerability runs through climate-exposed harvest cycles in the Mekong Delta and Malabar Coast. Distribution runs through wholesale auction networks for bulk industrial buyers and direct-to-commissary frameworks for Thailand's chained restaurant sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific seasoning market functions as a defensive-moat story where regulatory entrenchment creates durable barriers. Switching costs for foodservice operators locked into multi-year oleoresin contracts protect incumbent positions against price undercutting.
For Market Incumbents: Harden laboratory verification capabilities at Gujarat and Kerala processing clusters to preempt FSSAI enforcement escalation on pesticide residue documentation. Expand captive supply of steam-sterilized Kashmiri saffron and Malabar pepper to defend against precision fermentation substitutes displacing traditional extraction in premium applications.
For New Entrants and Emerging Players: Establish a beachhead in Philippines cloud kitchen seasoning systems where Jollibee and local aggregators remain underdeveloped buyers versus saturated Thai and Vietnamese markets. Pursue PLI scheme alignment for capital subsidy coverage on oleoresin extraction capacity as the go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors integrated processors with laboratory infrastructure over fragmented family-owned grinding operations. Long-term viability hinges on backward integration into blockchain-IoT traceability networks that preempt EU deforestation regulation compliance. Monitor chromatography technician hiring rates at Kerala and Gujarat clusters as the inflection indicator for regulatory compliance capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Sourcing Networks | Olam International's Vietnam and Indonesia origin control secures raw material quality at harvest point. |
| Clean-Label Extraction Technology Licensing | Supercritical CO2 adoption captures shelf price premiums in Japan's Ministry of Health, Labour and Welfare regulated channels. |
| Steam Sterilization Infrastructure Investment | FSSAI ethylene oxide phase-out mandates force capital deployment for EU and Gulf market access eligibility. |
| Blockchain-IoT Traceability Pilot Expansion | Kerala cardamom cooperatives' sensor networks preempt EU deforestation regulation compliance requirements. |
| Regional R&D Facility Establishment | McCormick's India facilities adapt global formulations to local heat and aroma profiles for foodservice standardization. |
Study Parameters
The analysis maps oleoresin extraction, whole-spice grinding, and compounded blend sub-sectors, each validated through procurement directors at chained restaurant commissaries, quality control managers at export-oriented processing cooperatives, and regulatory affairs leads navigating FSSAI and SAMR compliance frameworks. Primary interviews with Kerala auction house operators and Ho Chi Minh City bulk traders combined with secondary validation from FSSAI notification gazettes, China's SAMR GB standards documentation, and customs trade data for Vietnamese pepper and Indonesian clove shipments. Bottom-up volume aggregation across Gujarat, Kerala, and Vietnam processing clusters triangulates against top-down demand estimates from Japan's food manufacturers and South Korean retail channels.
Assumptions held fixed include India's PLI scheme subsidy coverage rates and China's SAMR heavy metal enforcement intensity at port of entry, while variables spanned climate-driven harvest volatility in Vietnamese pepper belts and precision fermentation cost curves across the projection horizon. Segmentation dimensions modeled encompass product type, end user archetype, packaging format, and distribution channel with regional regulatory cluster overlays. CAGRs derive from slope analysis of historical volume trajectories adjusted for ethylene oxide phase-out compliance deadlines and cloud kitchen network proliferation rates.
Stress conditions across monsoon failure frequency in the Western Ghats and FSSAI residue limit tightening velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology substitution pace. Quarterly review of chromatography technician placement rates at Gujarat and Kerala clusters and EU deforestation regulation draft implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Pumpkin Pie Spices Market
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Bolivian Rose Salt Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Smoked Black Pepper Market