
 Espresso Salt Market | 2026-2036
Espresso Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Espresso Salt Market Analytics
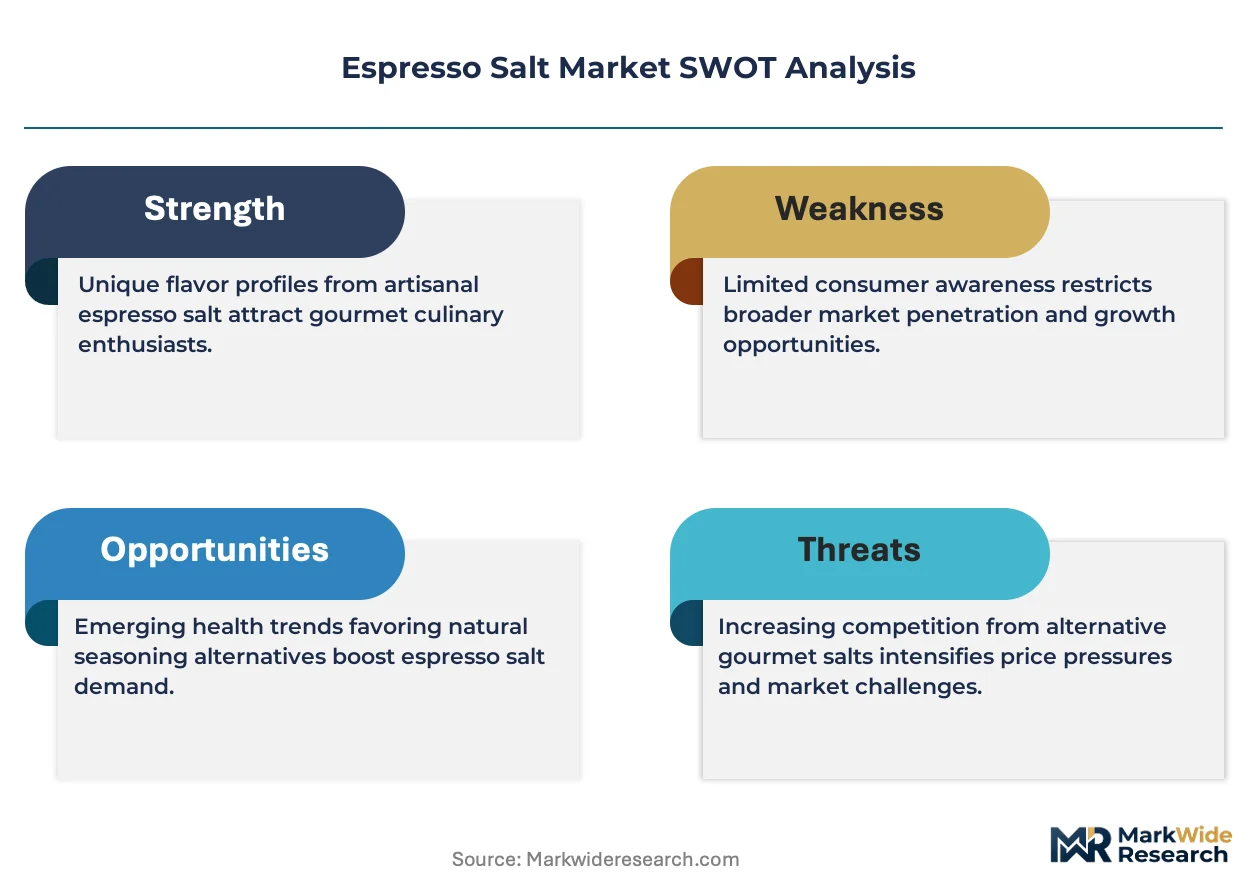
EU Green Deal sustainability benchmarks are realigning the cost-of-entry calculus for specialty salt processors seeking European market access. Caravel Gourmet leverages its direct-trade sourcing relationships to sustain premium positioning across North American retail channels. Artisan Salt Company anchors its competitive stance through small-batch production methods that emphasize traceability.
Espresso salt is a flavored finishing salt produced by blending natural sea salt or rock salt with ground espresso beans, typically containing 5-15% coffee solids by weight, and is manufactured through low-temperature drying to preserve volatile aromatic compounds. The product serves primarily as a gourmet seasoning for sweet and savory applications where bitter-salt contrast enhances flavor complexity. Gourmet product types command the widest margin pools due to positioning in gift and specialty retail, while coarse granulation dominates volume through its versatility in cooking and garnishing. Food Manufacturers represent the fastest-growing end-user channel as ready-meal and snack producers incorporate espresso salt into limited-edition product lines.
FDA food additive regulations and USDA organic certification standards govern ingredient labeling and processing claims for espresso salt sold in the United States, while EU EFSA flavoring substance evaluations shape permissible coffee-derived additive concentrations in European formulations. BIS food safety standards in India and FSSAI labeling mandates add compliance layers for exporters targeting emerging markets. Stakeholders must monitor evolving caffeine-content disclosure requirements and sustainability certification demands as retail buyers increasingly tie procurement decisions to verified supply chain credentials.
Market Dynamics
Clean-label disclosure mandates from FDA and EU EFSA are compressing formulation flexibility for espresso salt processors, forcing reformulations and supply chain requalification cycles that favor established players with compliance infrastructure.
Growth Catalysts
- EU Green Deal sustainability benchmarks:These standards are redirecting procurement decisions toward verified low-carbon salt sourcing, creating preference premiums for processors with certified supply chains.
- Ready-meal manufacturers:Food Manufacturers represent the fastest-growing end-user channel as limited-edition product lines incorporate espresso salt for flavor differentiation in premium snacking.
- Low-temperature drying technology:Process improvements preserve volatile aromatic compounds at scale, expanding viable batch sizes without quality degradation.
Market Restraints
- Arabica coffee price volatility:Input cost swings in green coffee beans compress margin predictability for processors locked into annual supply contracts.
- Indonesian sea salt concentration:Artisan producers depend on a narrow geographic band of traditional salt farms, creating weather and logistics vulnerability.
- Caffeine-content disclosure thresholds:FDA labeling ambiguity around coffee-derived additives generates compliance friction for cross-border formulations.
Strategic Opportunities
- Indian FSSAI market entry:Emerging premium food retail in Mumbai and Bangalore offers first-mover positioning before domestic artisan salt capacity scales.
- Direct-to-chef subscription channels:Bypassing conventional distribution, specialty salt houses build recurring revenue through restaurant procurement platforms.
- USDA organic certification tailwind:Certified organic espresso salt commands shelf space allocation advantages in natural grocery reset programs.
Industry Challenges
- Flavor chemist talent scarcity:Formulating stable coffee-salt emulsions requires specialized expertise that competes with broader food science hiring pools.
- Dual certification timelines:Simultaneous pursuit of organic and fair-trade credentials extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Espresso Salt Market |
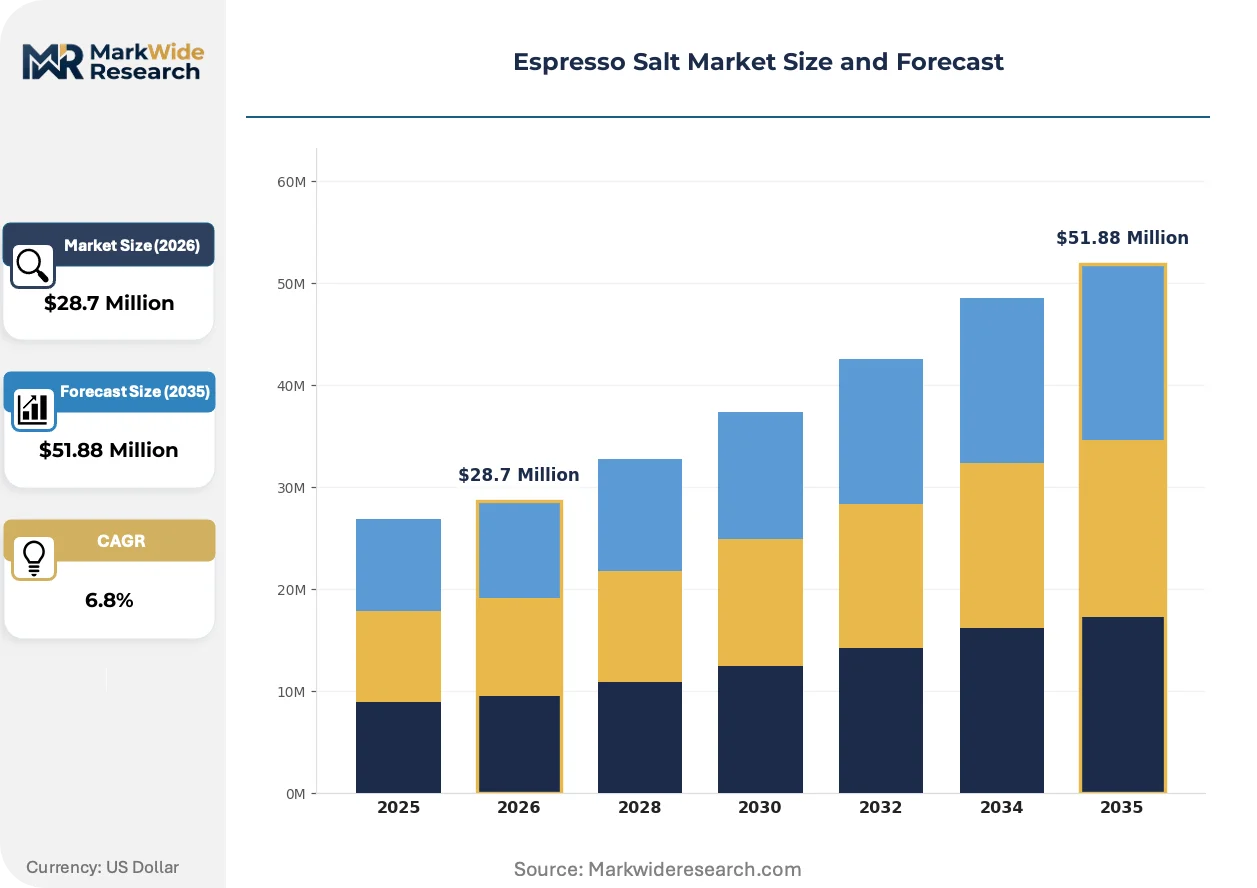
| Market Size in 2026 | $28.7 Million |
| Market Size in 2035 | $51.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse, Fine, Flavored, Gourmet Form: Granulated, Shaker, Block, Liquid End User: Restaurants, Cafés, Home Cooks, Food Manufacturers Application: Cooking, Baking, Garnishing, Beverage Enhancer |
| Companies Covered | Salt Works, Artisan Salt Company, Caravel Gourmet, Didi Davis Foods, With Love Spices and Herbs, Woodland Food, Spiceology, Syracuse Salt Company, Steel City Salt Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Espresso Salt Market Evolving Landscape
Processing technology and procurement transparency are rewriting competitive boundaries in espresso salt, with automation and traceability systems now determining which processors can sustain premium positioning.
Cryogenic grinding systems are rewriting production economics for volatile compound retention. Specialty coffee roasters adopting this technology at pilot scale report aromatic stability improvements that extend finished product shelf life. The structural consequence is compression of small-batch quality premiums as larger processors close the sensory gap.
EU EFSA flavoring substance evaluations are tightening permissible coffee-derived additive concentrations in European formulations. Processors serving dual US-EU markets face reformulation costs or SKU fragmentation. Gourmet product lines with EU export exposure are responding by segregating production runs and building separate inventory pools.
Chef-direct procurement platforms are fragmenting traditional distributor control over premium ingredient access. Restaurant buyers in New York and San Francisco now source espresso salt through specialized B2B marketplaces that bypass broadline foodservice. This channel shift is most visible in independent fine-dining segments where menu differentiation drives ingredient experimentation.
Espresso Salt Market Segmentation
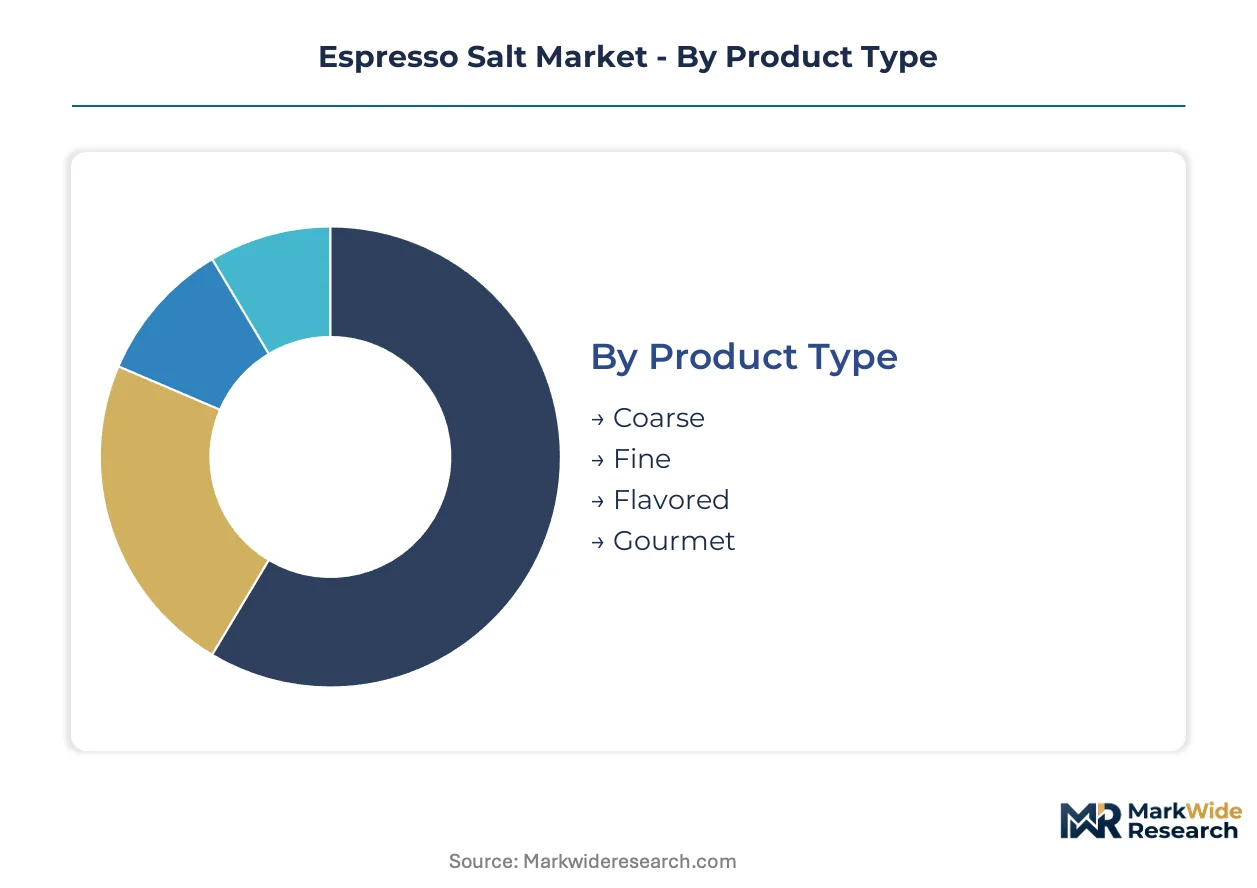
Espresso salt processors configure production lines around granulation precision and packaging formats that determine shelf stability and end-use versatility. Each segmentation axis reveals distinct margin structures and compliance burdens that shape competitive positioning across retail and foodservice channels.
Product Type:
Granulation technology and finishing protocols separate commodity-grade offerings from premium positioning in gift and specialty retail.
- Coarse:Large crystal structures (2-4mm) withstand high-heat applications without dissolution. Food Manufacturers in the United States incorporate coarse espresso salt into limited-edition snack lines where texture contrast drives purchase intent.
- Fine:Micronized particles below 0.5mm dissolve rapidly for uniform flavor distribution. Artisan bakeries in San Francisco and New York specify fine granulation for laminated dough applications where visual specking must be minimized.
- Flavored:Espresso salt augmented with vanilla, cocoa, or spice infusions targets dessert-focused foodservice. Product development cycles run shorter than gourmet lines but face steeper SKU proliferation costs.
- Gourmet:Small-batch production with single-origin coffee attribution commands gift retail placement. FDA organic certification and direct-trade sourcing claims support price premiums in natural grocery resets.
Coarse leads on scale; gourmet leads on momentum.
Form:
Packaging engineering determines moisture protection, dispensing precision, and retail channel access.
- Granulated:Bulk foodservice formats (5-25kg) serve high-volume restaurant kitchens. BIS food safety standards in India govern moisture content specifications for imported bulk shipments.
- Shaker:Consumer retail formats with controlled-flow apertures dominate supermarket condiment aisles. EU EFSA labeling mandates for caffeine-derived additives complicate cross-border packaging design.
- Block:Solid salt-coffee matrices for grating applications target chef-direct procurement platforms. Production yields remain lower than granulated formats due to compression curing requirements.
- Liquid:Brine concentrates with suspended coffee solids enable beverage and sauce integration. Shelf-life stability challenges limit distribution radius without refrigerated logistics.
Shaker formats capture household volume; liquid forms are gaining share fastest in beverage innovation pipelines.
End User:
Procurement sophistication and volume predictability vary sharply across foodservice and manufacturing buyers.
- Restaurants:Independent fine-dining establishments source through specialized B2B marketplaces that bypass broadline distributors. Menu differentiation pressures drive experimentation with finishing salts.
- Cafés:Specialty coffee shops deploy espresso salt across both beverage and pastry applications. Seasonal limited offerings create demand spikes that strain small-batch supplier capacity.
- Home Cooks:Enthusiast consumers purchasing through direct-to-consumer channels respond to recipe content and origin storytelling. USDA organic certification influences purchase decisions in natural grocery segments.
- Food Manufacturers:Ready-meal and snack producers represent the fastest-growing end-user channel as limited-edition product lines incorporate espresso salt for flavor differentiation. Annual contracting patterns favor processors with certified supply chains and volume scalability.
Food Manufacturers lead on scale; cafés lead on momentum.
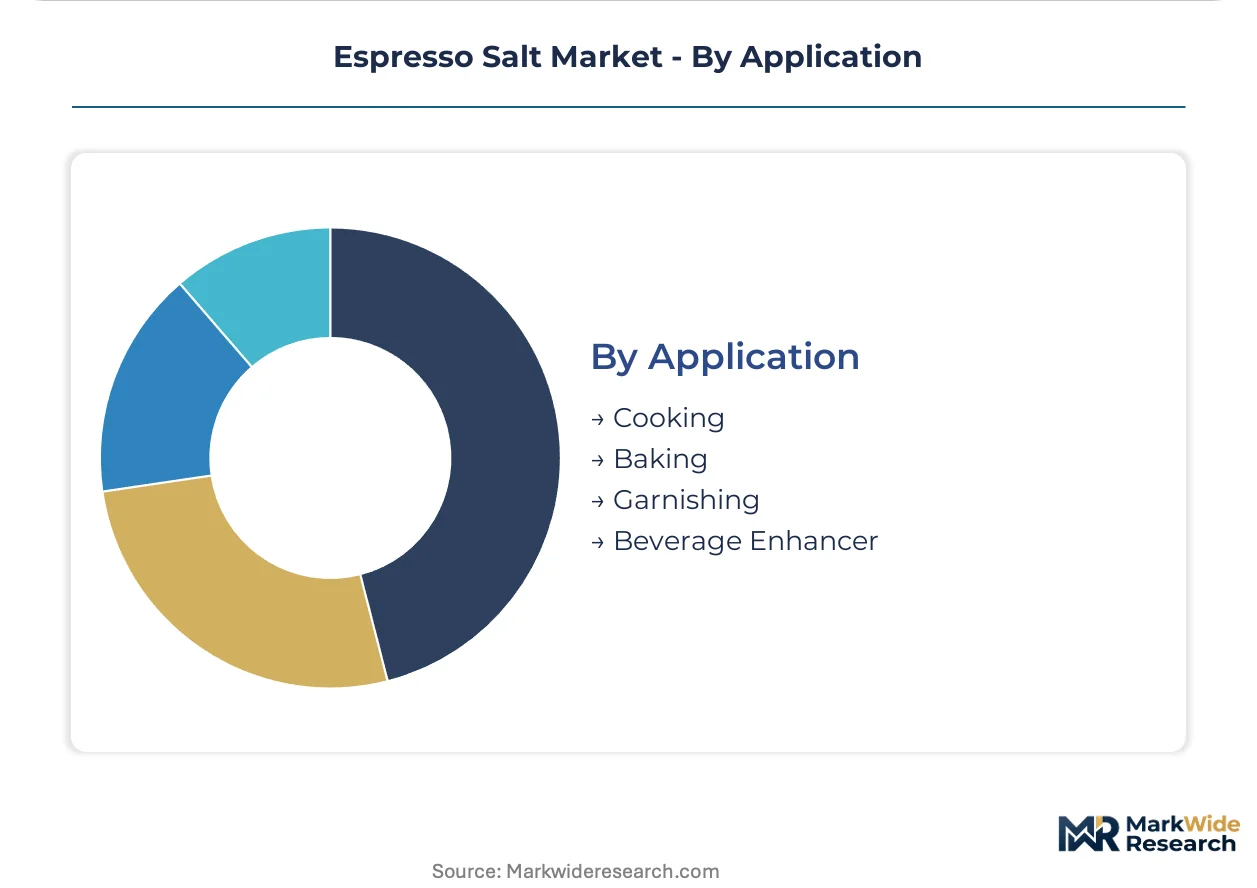
Application:
Functional use case determines heat tolerance requirements, dosage precision, and sensory outcome specifications.
- Cooking:High-heat applications require coarse granulation that releases coffee aromatics without burning. Professional kitchens in Chicago and Austin specify espresso salt for red meat finishing.
- Baking:Fine granulation integrates into chocolate and caramel matrices where bitter-salt contrast amplifies sweetness perception. Artisan producers in Portland and Seattle dominate supply relationships with regional bakeries.
- Garnishing:Visual presentation demands uniform crystal sizing and color consistency. Plating applications in fine-dining segments prioritize aesthetic impact over cost efficiency.
- Beverage Enhancer:Espresso salt rims and dissolved concentrates appear in craft cocktail programs. Liquid and fine granulated forms compete for mixologist preference based on dissolution speed.
Cooking leads on scale; beverage enhancer leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan salt processors and specialty coffee roasters cluster in coastal metropolitan areas where craft food culture intersects with established gourmet ingredient distribution networks. This workforce concentration shapes regional production capacity and export logistics across key producing markets.
United States
Specialty coffee shops in New York and San Francisco drive premium seasoning adoption through experimental pastry and beverage programs. FDA food additive regulations govern caffeine-content disclosure thresholds for coffee-derived additives in interstate commerce. Pacific Northwest artisan producers dominate small-batch supply relationships with regional bakery chains.
Germany
EU Green Deal sustainability benchmarks redirect procurement decisions toward verified low-carbon salt sourcing for food manufacturers. EFSA flavoring substance evaluations tighten permissible coffee-derived additive concentrations in European formulations. Bavarian specialty food processors build separate inventory pools for EU-compliant production runs.
India
Mumbai and Bangalore retail expansion creates first-mover positioning opportunities before domestic artisan salt capacity scales. FSSAI labeling mandates add compliance layers for imported gourmet seasonings targeting emerging premium food retail. Maharashtra-based distributors establish direct-trade relationships with Indonesian sea salt farms.
Indonesia
Traditional salt farm concentration in specific coastal provinces creates weather and logistics vulnerability for artisan producers dependent on narrow geographic sourcing. BIS food safety standards in India govern moisture content specifications for exported bulk shipments. Javanese processing clusters face pressure to adopt low-temperature drying technology for volatile compound retention.
United Kingdom
Chef-direct procurement platforms in London fragment traditional distributor control over premium ingredient access. EFSA regulations shape permissible formulation concentrations for coffee-salt blends exported to continental European markets. Independent fine-dining establishments in the capital source through specialized B2B marketplaces bypassing broadline foodservice.
Espresso Salt Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The vendor base spans multinational seasoning houses with broad portfolio diversification and artisan micro-producers anchored in single-origin sourcing narratives. Three strategic archetypes dominate: scale-driven mass-market suppliers, premium-tier craft specialists, and private-label contract manufacturers. Competitive moves concentrate on direct-trade sourcing relationships and chef-direct subscription channel development.
Within the craft specialist tier, Artisan Salt Company exemplifies small-batch production methods emphasizing traceability, while Caravel Gourmet occupies a position built on direct-trade sourcing relationships sustaining premium positioning across North American retail channels. Salt Works anchors the scale-driven segment with diversified seasoning portfolio breadth. These three represent distinct competitive vectors: traceability narrative, sourcing control, and manufacturing scale.
| Leading Market Players |
|---|
| Salt Works |
| Artisan Salt Company |
| Caravel Gourmet |
| Didi Davis Foods |
| With Love Spices and Herbs |
| Woodland Food |
| Spiceology |
| Syracuse Salt Company |
| Steel City Salt Company |
| Others |
Value Network & Pricing Analysis
Captive sourcing of Indonesian sea salt and direct-trade Arabica relationships anchors both supply security and premium pricing power for espresso salt processors serving North American and European channels. This integration choice insulates gourmet tier producers from commodity volatility while compressing margin pools for non-integrated competitors dependent on spot-market inputs.
Pricing Analysis
Bundled certification-plus-origin storytelling commands shelf-space premiums, while unbundled commodity-grade espresso salt trades on volume discounts to food manufacturers. Pricing stratifies across premium, standard, and economy tiers, with USDA organic certification and single-origin attribution driving the widest spreads. Cost compression in the standard tier intensifies because Arabica coffee price volatility feeds directly into processor margins. Food manufacturers exhibit the highest price sensitivity due to annual contracting patterns, while chef-direct buyers prioritize traceability over per-unit cost.
Supply Chain Analysis
EU Green Deal domestic-content mandates and FSSAI labeling requirements in India are reshaping sourcing decisions for processors seeking multi-regional market access. Geographic supply concentrates in Indonesia for traditional sea salt, Vietnam and Brazil for Arabica coffee inputs, and the United States for low-temperature drying equipment. Raw material dependencies center on green coffee beans, evaporated sea salt, and moisture-barrier packaging substrates. Single-source vulnerability runs through Indonesian salt farm concentration exposed to monsoon disruption. Distribution runs through specialty foodservice distributors in North America, chef-direct B2B platforms in metropolitan markets, and natural grocery resets for certified organic lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Espresso salt functions as a late-cycle quality story where craft food culture has matured toward specification-driven procurement. Demand is shifting toward verified low-carbon sourcing and direct-trade attribution as baseline requirements rather than premium differentiators.
For Market Incumbents: Acquire cryogenic grinding capability to close the sensory gap with artisan competitors. Salt Works and Caravel Gourmet should pursue backward integration into Indonesian salt farm partnerships to secure supply continuity against weather volatility. Dual certification investment in organic and fair-trade credentials extends product launch windows but locks in shelf-space allocation advantages as retail buyers tighten procurement standards. For New Entrants and Emerging Players: Chef-direct subscription platforms offer the most penetrable route for bypassing established distributor relationships. Target independent fine-dining establishments in Chicago and Austin where menu experimentation drives finishing salt adoption. White-space exists in Indian premium retail before domestic artisan capacity scales; leverage FSSAI compliance expertise as a first-mover barrier. Launch through specialized B2B marketplaces that fragment broadline foodservice control. For Investors and Strategic Acquirers: Consolidation pressure builds where flavor chemist talent scarcity and dual certification timelines favor scaled processors with compliance infrastructure. The five-to-ten year viability frame favors vertically integrated specialists with captive sourcing over pure-brand marketing plays. Acquisition targets should display direct-trade relationships and low-temperature drying capacity. Watch cryogenic grinding adoption rates as the inflection signal for when small-batch quality premiums compress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt Sourcing | Captive Indonesian farm relationships insulate against monsoon logistics disruption and ESG audit requirements. |
| Cryogenic Grinding Technology Deployment | Aromatic stability improvements extend shelf life and close sensory gaps with artisan competitors. |
| Dual Certification Investment | USDA organic plus fair-trade credentials secure natural grocery reset placement and EU Green Deal compliance. |
| Chef-Direct Platform Development | Bypassing broadline distributors captures independent fine-dining procurement shifting to specialized B2B marketplaces. |
| Indian Market Entry | FSSAI compliance positioning ahead of domestic artisan scaling captures Mumbai and Bangalore premium retail expansion. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster combining executive interviews with specialty salt processors, specialty coffee roasters, and chef procurement managers alongside secondary validation. Trade data from customs records, FDA food additive filings, and EU EFSA flavoring substance evaluations anchored supply-side assessment. Nielsen retail audit data and natural grocery channel reports informed demand-side calibration. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level outputs.
Granularity-level modeling operated at product-type, form, end-user, and application dimensions, with regional regulatory clusters treated as distinct forecast boundaries. CAGRs were derived from segment-level volume trajectories and value-per-unit spreads across the projection horizon. Arabica coffee price elasticity, low-temperature drying capacity expansion, and chef-direct platform penetration served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for cryogenic grinding; alternative pathways for volatile compound retention would alter the outlook. Forecasts reflect assumptions around EU Green Deal implementation pace, FDA caffeine-content disclosure clarity, and Indonesian salt farm weather patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Europe and Asia Juniper Berries Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market