
 Myrrh Gum Market | 2026-2036
Myrrh Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Myrrh Gum Market Analytics
Traditional medicine practitioners is collapsing as the dominant buyer archetype while pharmaceutical formulators gain procurement share. Symrise AG leverages backward integration into Somali and Ethiopian sourcing networks to secure resin supply chains. Givaudan SA anchors its position through specialized extraction capabilities for fragrance-grade essential oils. Firmenich SA differentiates via proprietary purification technologies that meet pharmaceutical-grade specifications.
Myrrh gum comprises dried oleo-gum resin exuded from Commiphora myrrha trees, containing 25-40% resin, 40-60% gum, and 3-8% essential oil with characteristic furanosesquiterpenes. Manufacturers steam-distill the raw resin to isolate volatile compounds for fragrance applications or solvent-extract to produce oleoresin for pharmaceutical use. Raw myrrh and resin segments dominate volume trade, while essential oil commands premium pricing due to concentration ratios requiring eight to ten kilograms of raw material per liter of distilled oil. Powder formulations are accelerating fastest as dietary supplement manufacturers seek standardized dosing formats. Specialty stores and pharmacies control the highest-margin distribution channels, particularly in European markets with strict herbal product licensing under the EU Traditional Herbal Medicinal Products Directive.
EMA guidelines on herbal medicinal products and the EU REACH regulation shape import documentation and residue testing requirements for European market access. FDA oversight of dietary supplements under DSHEA creates parallel compliance pathways for US-bound powder and capsule formats. Stakeholders must monitor evolving organic certification standards and geopolitical stability in Horn of Africa sourcing regions to secure long-term supply continuity.
Market Dynamics
Pharmaceutical formulators are displacing traditional medicine practitioners as the dominant procurement force, tightening specifications around resin purity, essential oil concentration, and batch-to-batch consistency that raw myrrh traders historically ignored.
Growth Catalysts
- EU Traditional Herbal Medicinal Products Directive:Standardized licensing pathways enable pharmaceutical manufacturers to register myrrh-based expectorants and antiseptics across Germany, France, and Italy.
- Solvent extraction technology:Advanced oleoresin recovery methods yield pharmaceutical-grade purity levels that satisfy EMA monograph requirements for gum resin applications.
- Ethiopian supply expansion:Cultivation cooperatives in the Somali Region and Oromia are scaling Commiphora myrrha tapping operations to meet contracted volume commitments from Indian processors.
Market Restraints
- Frankincense substitution:Boswellia carterii resin offers comparable anti-inflammatory properties at lower procurement costs for dietary supplement formulators.
- Horn of Africa supply concentration:Over seventy percent of raw myrrh originates from conflict-affected zones in Somalia and eastern Ethiopia, exposing buyers to force majeure disruptions.
- Steam distillation yield limits:Essential oil recovery rates of three to eight percent create fundamental scarcity constraints for fragrance-grade applications.
Strategic Opportunities
- US dietary supplement channel:FDA DSHEA compliance pathways for myrrh powder capsules remain underdeveloped relative to European herbal registrations.
- Sustainable wild-harvest certification:FairWild and organic standards command thirty to fifty percent premiums in German pharmacy distribution.
- Blockchain traceability integration:Immutable chain-of-custody records satisfy EU REACH documentation requirements for resin sourcing transparency.
Industry Challenges
- Phytochemical standardization expertise:Few contract laboratories possess validated HPLC methods for furanosesquiterpene quantification in oleo-gum resins.
- Dual certification timelines:Simultaneous EU organic and US NOP organic approvals require eighteen to twenty-four month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myrrh Gum Market |
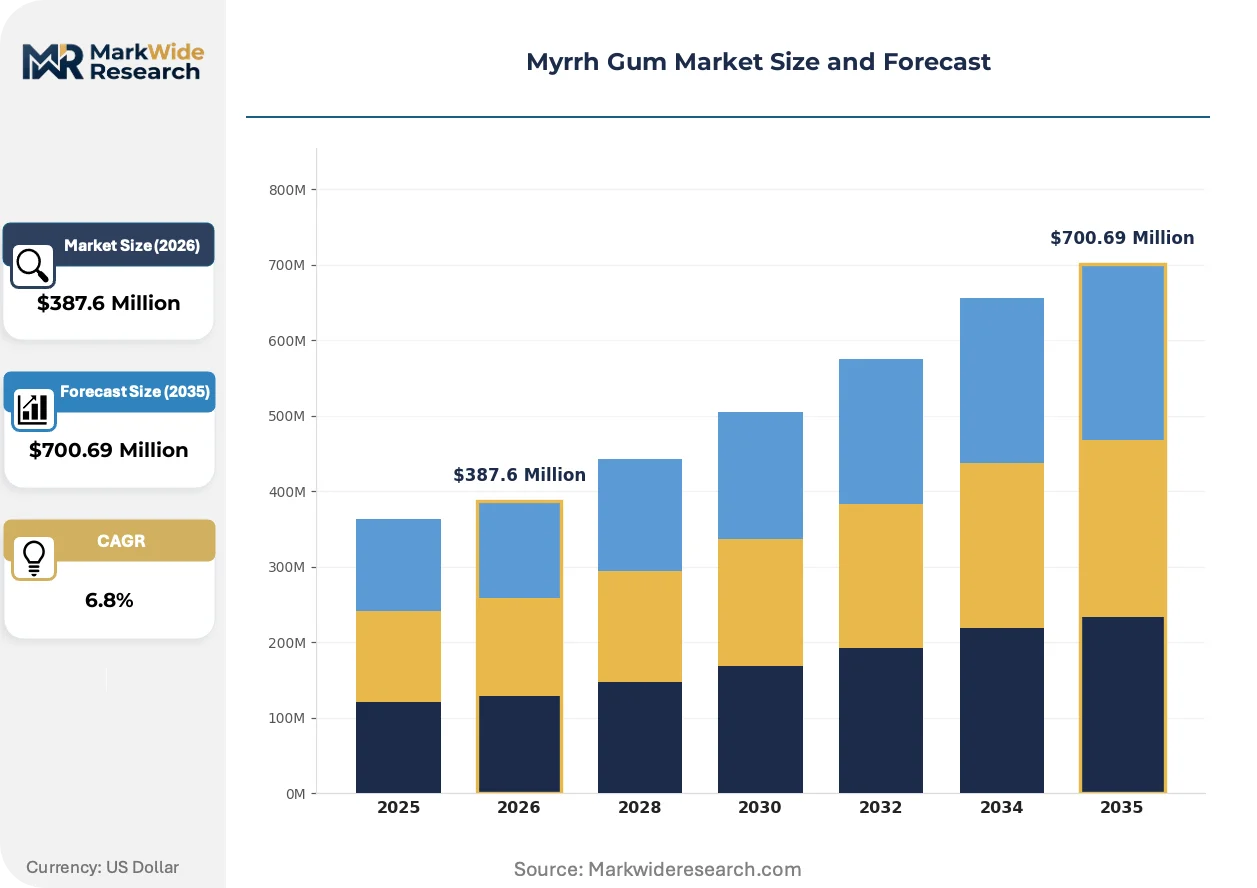
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Myrrh, Essential Oil, Resin, Powder End User: Cosmetics, Pharmaceuticals, Food & Beverages, Traditional Medicine Application: Fragrance, Antiseptic, Flavoring, Expectorant Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Native Spice Traders, Symrise AG, Givaudan SA, Firmenich SA, Kalsec Inc., Olam Group Limited, Liberty Natural Products Inc., AOS Products, Best Botanicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myrrh Gum Market Evolving Landscape
Processing technology and regulatory digitization are compressing traditional supply chain hierarchies, enabling direct relationships between Ethiopian cooperatives and European pharmaceutical buyers that previously relied on Mumbai trading houses.
Supercritical CO2 extraction is supplanting conventional steam distillation and hexane solvent methods for essential oil recovery. Fragrance houses in Grasse and Geneva are adopting these systems to preserve heat-sensitive sesquiterpenes. The technology is enabling pharmaceutical-grade purity claims that command premium positioning in Swiss and German therapeutic markets.
EU REACH Article 33 documentation requirements now mandate full substance identity disclosure for resin imports exceeding one tonne annually. ECHA enforcement actions against undocumented myrrh shipments have triggered compliance investments among Dutch and German importers. Small-volume traders lacking SIEF participation are exiting the market, consolidating procurement among REACH-registered entities.
Direct-to-manufacturer contracting is replacing spot-market purchasing for powder and oleoresin grades. Ethiopian cooperatives now maintain long-term supply agreements with Indian and European processors, bypassing traditional Aden and Dubai auction houses. This pattern concentrates most visibly in Germany, where pharmacy chains require certified sustainable sourcing that spot markets cannot guarantee.
Myrrh Gum Market Segmentation
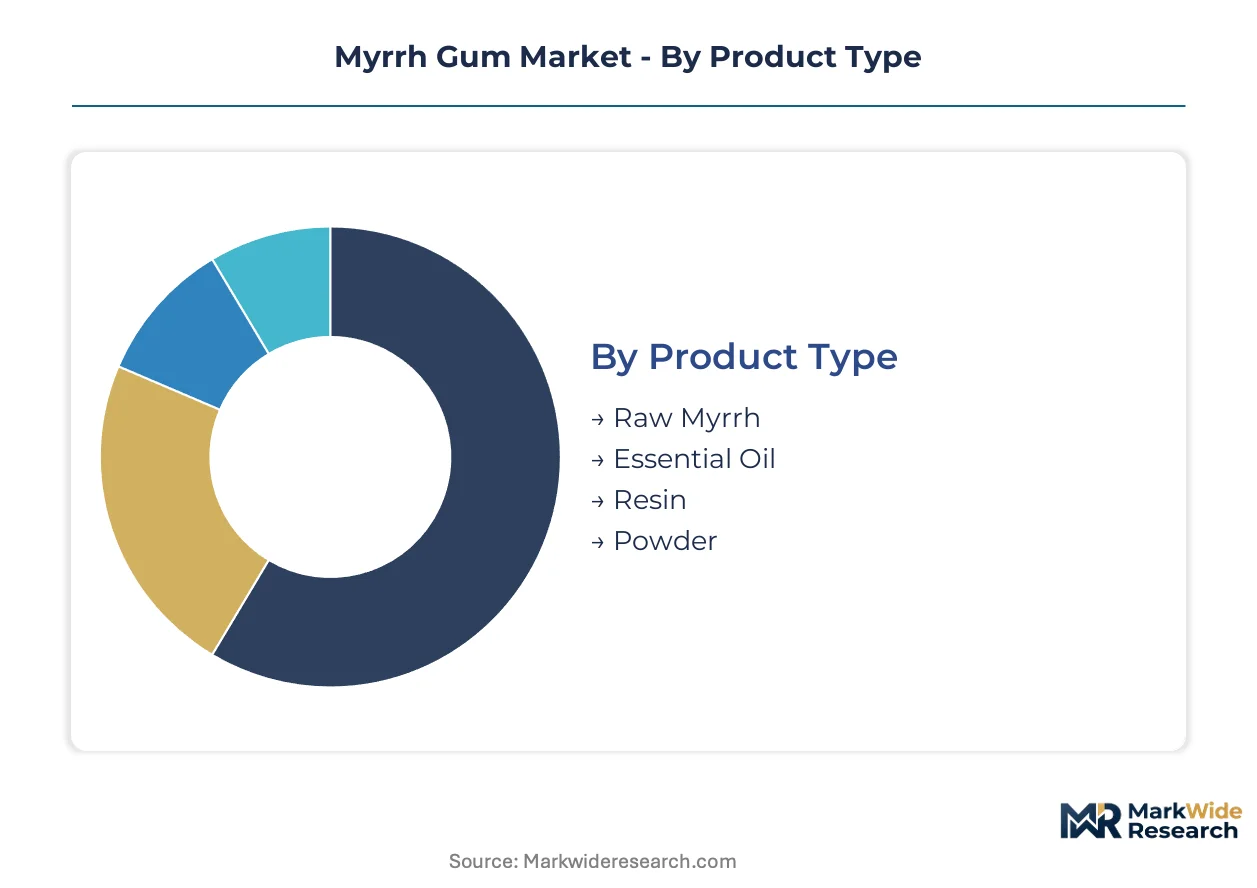
Myrrh gum segmentation reflects divergent purity standards across pharmaceutical and fragrance applications. Regulatory pathways in Germany and Switzerland impose distinct certification requirements that reshape procurement patterns for each product grade.
Product Type:
EMA monograph compliance and REACH documentation obligations create tiered market access barriers that separate commodity resin from pharmaceutical-grade derivatives.
- Raw Myrrh:Dried oleo-gum resin containing 25-40% resin, 40-60% gum, and 3-8% essential oil. Ethiopian cooperatives supply Mumbai processors under long-term contracts, though ECHA enforcement actions against undocumented shipments are consolidating trade among REACH-registered Dutch and German importers.
- Essential Oil:Steam-distilled volatile fraction requiring eight to ten kilograms of raw material per liter. Fragrance houses in Grasse and Geneva adopt supercritical CO2 extraction to preserve heat-sensitive sesquiterpenes for premium therapeutic positioning.
- Resin:Purified gum-resin fraction meeting pharmaceutical specifications for expectorant formulations.
- Powder:Standardized dosing format accelerating fastest as dietary supplement manufacturers seek capsule-ready inputs.
Established volume favors raw myrrh; emerging adoption favors powder formulations.
End User:
Customer procurement sophistication determines specification stringency and contract duration across value chain tiers.
- Pharmaceuticals:Formulators displace traditional buyers by demanding batch-to-batch consistency in resin purity and essential oil concentration. EU Traditional Herbal Medicinal Products Directive registrations in Germany, France, and Italy enable standardized expectorant and antiseptic marketing claims.
- Cosmetics:Fragrance-grade essential oil consumption concentrates among Swiss and French compounders seeking Furadenine-free sesquiterpene profiles for skin-care applications.
- Traditional Medicine:Collapsing procurement share as practitioners lose volume to certified pharmaceutical channels.
- Food & Beverages:Limited flavoring applications constrained by FEMA GRAS status uncertainties and EU Novel Food assessment requirements.
Contract security favors pharmaceuticals; margin compression threatens traditional medicine.
Application:
Functional efficacy claims determine regulatory pathway complexity and market access velocity.
- Antiseptic:Pharmaceutical-grade oleoresin applications require validated HPLC methods for furanosesquiterpene quantification that few contract laboratories possess.
- Expectorant:EMA monograph recognition enables centralized EU registration procedures, accelerating German pharmacy distribution.
- Fragrance:Steam distillation yield limits of three to eight percent create fundamental scarcity constraints for fine fragrance formulations.
- Flavoring:Regulatory ambiguity under FDA GRAS and EU food additive frameworks restricts commercial development.
Regulatory clarity favors expectorant; supply scarcity constrains fragrance expansion.
Distribution Channel:
Certification requirements and traceability mandates reshape channel economics and buyer concentration.
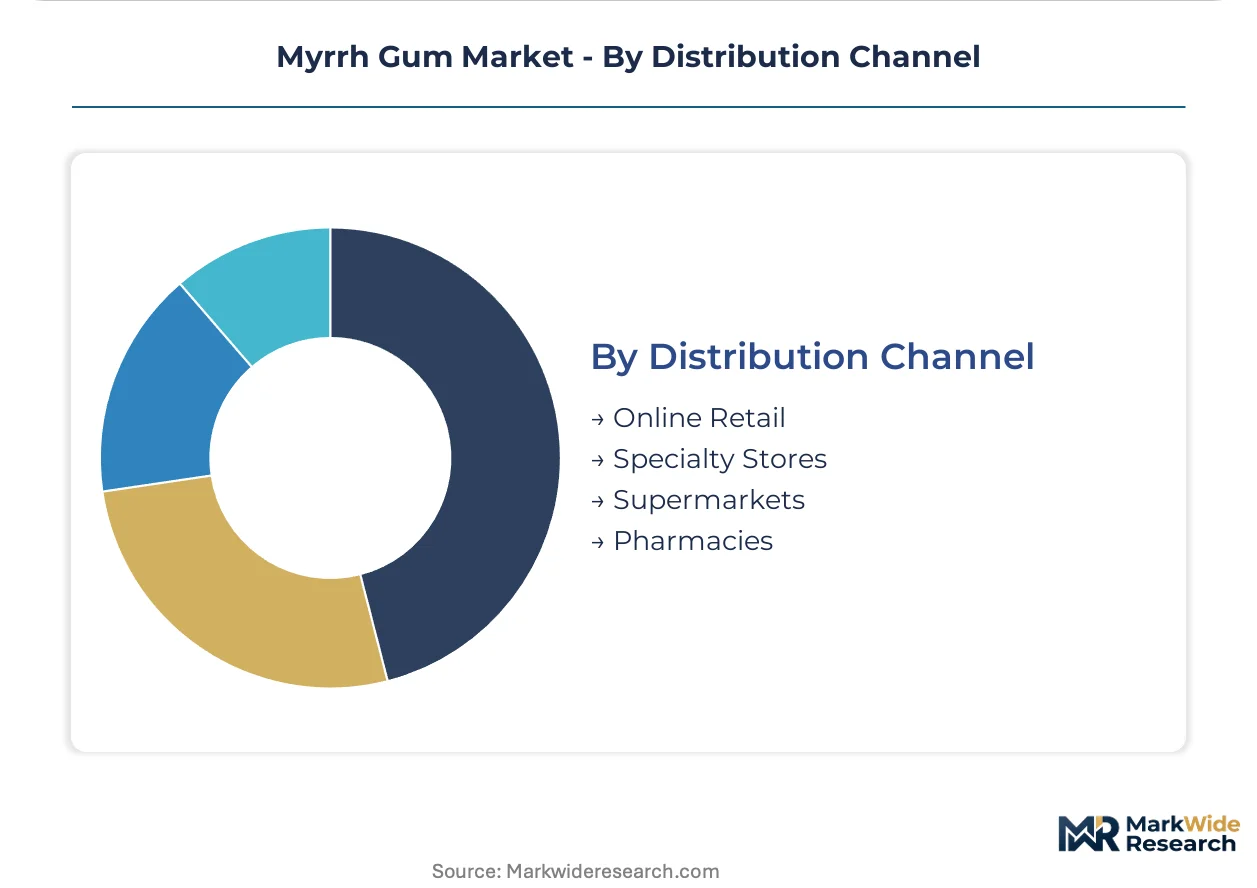
- Pharmacies:German pharmacy chains require FairWild and organic certifications commanding thirty to fifty percent premiums, consolidating procurement among vertically integrated processors with direct Ethiopian cooperative relationships.
- Specialty Stores:Highest-margin channel in European markets under strict herbal product licensing, though volume remains constrained by prescription-equivalent positioning.
- Online Retail:Expanding fastest for powder and capsule formats targeting US dietary supplement consumers under DSHEA compliance pathways.
- Supermarkets:Limited penetration due to mass-market price sensitivity incompatible with sustainable wild-harvest certification costs.
Margin concentration favors pharmacies; volume scaling favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Djibouti anchors Horn of Africa resin exports to Indian processing hubs, while the Suez Canal corridor funnels refined myrrh derivatives toward European pharmaceutical markets.
Germany
German pharmacy chains command thirty to fifty percent premiums for FairWild-certified myrrh powders. EMA monograph recognition for Commiphora myrrha expectorants streamlines centralized EU registration procedures. The Baden-Württemberg region hosts specialized extraction facilities serving Swiss and German fragrance compounders.
India
Mumbai processors contract directly with Ethiopian cooperatives for raw oleo-gum resin supply. FSSAI standards for herbal product safety create parallel compliance frameworks alongside EU export requirements. The Gujarat cluster concentrates solvent-extraction capacity for pharmaceutical-grade oleoresin production.
United States
Dietary supplement manufacturers in Utah and California accelerate powder capsule formulation under FDA DSHEA pathways. GRAS self-affirmation processes for myrrh flavoring applications remain underdeveloped relative to European herbal registrations. The Pacific Northwest hosts botanical distributors supplying naturopathic practitioner channels.
Switzerland
Swissmedic therapeutic product classifications enable premium positioning for supercritical CO2-extracted essential oils. Geneva fragrance houses adopt non-thermal extraction to preserve heat-sensitive furanosesquiterpenes. The Basel pharmaceutical corridor imports standardized resin fractions for antiseptic formulation.
France
Grasse fragrance compounders source steam-distilled myrrh oil for fine perfume applications. ANSM vigilance requirements for herbal medicinal products tighten import documentation standards. The Provence-Alpes-Côte d'Azur region maintains traditional distillation capacity alongside modern extraction investments.
Myrrh Gum Market Competitive Landscape
Concentration sits with integrated fragrance houses and specialized botanical processors. Three to five major players control premium-grade essential oil and pharmaceutical oleoresin segments, while commodity raw resin trade fragments across Mumbai trading houses and Ethiopian cooperatives. Strategic archetypes include backward-integrated fragrance multinationals, Indian solvent-extraction specialists, and certified wild-harvest cooperatives. Dominant competitive moves encompass direct-to-manufacturer contracting and blockchain traceability investments.
Within the integrated fragrance house tier, Symrise AG and Givaudan SA exemplify archetypes securing captive supply through Somali and Ethiopian sourcing networks. Firmenich SA occupies a position emphasizing proprietary purification technologies. Among specialized processors, Kalsec Inc. and AOS Products represent mid-scale extraction specialists serving pharmaceutical and dietary supplement channels.
| Leading Market Players |
|---|
| Native Spice Traders |
| Symrise AG |
| Givaudan SA |
| Firmenich SA |
| Kalsec Inc. |
| Olam Group Limited |
| Liberty Natural Products Inc. |
| AOS Products |
| Best Botanicals |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at Mumbai trading houses compress margin capture for spot-market resin purchases while amplifying pricing power for processors with direct Ethiopian cooperative contracts. This lead-time differential separates commodity traders from integrated fragrance houses and pharmaceutical formulators who lock in volume commitments at origin.
Pricing Analysis
Three-tier pricing structure across FairWild-certified, organic-compliant, and conventional resin grades anchors transaction economics. Certification premiums of thirty to fifty percent in German pharmacy distribution separate sustainable wild-harvest supply from spot-market commodity flows. Cost compression in conventional grades intensifies as frankincense substitution pressures expectorant formulation budgets. Dietary supplement manufacturers in the United States exhibit highest price sensitivity due to undeveloped DSHEA compliance pathways, while Swiss fragrance compounders absorb premiums for supercritical CO2-extracted essential oils.
Supply Chain Analysis
Ethiopia and Somalia anchor raw oleo-gum resin extraction, while India concentrates solvent-extraction and steam-distillation processing capacity. Gujarat facilities draw from Somali Region and Oromia cooperative networks, resting on Commiphora myrrha tapping labor and hexane solvent inputs. Single-source vulnerability concentrates in the Horn of Africa, where conflict exposure in eastern Ethiopia and Somalia threatens force majeure disruptions. Distribution runs through the Port of Djibouti to Indian processing hubs, with refined derivatives transiting the Suez Canal corridor toward European pharmaceutical markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated HPLC methods for furanosesquiterpene quantification represent the critical skill gap separating pharmaceutical-grade suppliers from commodity traders, concentrating margin capture among laboratories with proprietary analytical capabilities.
For Market Incumbents: Secure backward integration into Somali and Ethiopian sourcing networks before cooperative direct-contracting consolidates supply access among REACH-registered competitors. Invest in blockchain traceability infrastructure to preempt ECHA enforcement actions against undocumented shipments. Channel control through German pharmacy chain partnerships defends margin position against Indian processor expansion into European distribution. For New Entrants and Emerging Players: Differentiate on supercritical CO2 extraction capabilities for heat-sensitive sesquiterpene preservation, targeting Swiss and German therapeutic markets where premium positioning commands sustainable procurement premiums. The United States dietary supplement channel offers the most penetrable white-space, with DSHEA compliance pathways for myrrh powder capsules remaining underdeveloped relative to European herbal registrations. A go-to-market angle anchored in naturopathic practitioner education bypasses entrenched pharmaceutical distribution barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated fragrance multinationals seeking to divest non-core resin trading operations amid regulatory compliance cost escalation. Long-term viability hinges on positioning within REACH-registered import channels and direct cooperative relationships that survive spot-market trader consolidation. The signal to watch is ECHA enforcement action velocity against small-volume undocumented shipments, which accelerates procurement concentration among compliant entities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sourcing Networks | Captive Ethiopian cooperative contracts preempt spot-market volatility and secure REACH documentation compliance. |
| Supercritical CO2 Extraction Investment | Non-thermal essential oil recovery preserves furanosesquiterpenes for Swissmedic therapeutic product classifications. |
| Blockchain Traceability Deployment | Immutable chain-of-custody records satisfy EU REACH Article 33 substance identity disclosure mandates. |
| Dual Organic Certification Pursuit | Simultaneous EU organic and US NOP approvals unlock thirty to fifty percent pharmacy channel premiums. |
| Direct-to-Manufacturer Contracting | Long-term supply agreements with Indian and European processors bypass Aden and Dubai auction house intermediation. |
Research Methodology
The analysis maps raw resin trading, essential oil distillation, pharmaceutical oleoresin extraction, and powder formulation segments, each validated through procurement managers at fragrance houses, regulatory affairs leads at Indian processors, pharmacy chain buyers in Germany, and cooperative coordinators in Ethiopia. Primary interview findings were cross-checked against customs and trade data, ECHA REACH registration databases, EMA herbal monograph filings, and FSSAI herbal product safety standards. Bottom-up volume estimates from cooperative tapping operations and processor capacity utilization were triangulated with top-down demand projections from pharmaceutical formulator procurement patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user sophistication, application efficacy claims, and distribution channel certification requirements as core segmentation dimensions. CAGRs were derived from contracted volume commitments between Ethiopian cooperatives and Indian processors, supercritical CO2 extraction adoption curves among Swiss fragrance compounders, and EMA monograph registration velocity for expectorant formulations. Industry-specific forecast inputs included geopolitical stability indices for Horn of Africa sourcing regions and evolving EU organic certification standard timelines.
The analysis sits within stated boundaries; outcomes outside sustained Ethiopian supply expansion and stable EMA regulatory pathways would require recalibration. Forecasts reflect documented assumptions regarding cooperative tapping operation scaling and REACH compliance investment continuity among Dutch and German importers. Geopolitical disruption in Somalia, frankincense substitution acceleration in dietary supplements, or ECHA enforcement intensity exceeding historical patterns represent specific risk factors that could revise projections. Recalibration cycles align with material shifts in EU herbal product licensing frameworks and Horn of Africa sourcing region stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Pumpkin Pie Spices Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Europe and Asia Juniper Berries Market
Spices and Seasonings
Mustard Market