
 Helicopter Services Market | 2026-2036
Helicopter Services Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Services Market Intelligence
The industry-wide adoption of advanced digital avionics suites and integrated health and usage monitoring systems (HUMS) is reorganizing the competitive landscape. Airbus Helicopters leverages its investment in the Helionix avionics platform to secure contracts in emergency medical and law enforcement segments. Bristow Group Inc. specializes in complex offshore missions demanding such advanced systems for its energy clients. Bell Textron Inc. competes by integrating its latest flight deck technologies across its commercial helicopter lines.
Helicopter services encompass the deployment of rotary-wing aircraft, operated by certified crews, for commercial, civil, and parapublic missions. These services are defined by aircraft capabilities such as maximum takeoff weight, operational range, and mission-specific configurations like external hoists or electro-optical sensors. Their primary purpose is to provide rapid air mobility and aerial work in environments inaccessible to fixed-wing aircraft. Emergency Medical Services and Offshore Transport represent the largest service type segments. Demand for Aerial Surveying applications is expanding, driven by infrastructure and environmental projects.
The market operates under stringent safety oversight from national and regional aviation authorities. Regulations from the U.S. Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) dictate pilot certification, maintenance schedules, and equipment mandates. These rules directly influence operational costs and fleet composition choices. Operators must strategically balance investments in next-generation, sustainable aviation fuel (SAF) compatible aircraft against the near-term profitability of existing fleets.
Market Dynamics
The imperative to upgrade aging fleets with next-generation, digitally-equipped aircraft is the central force shaping the helicopter services market. This dynamic is driven by a confluence of stricter safety mandates from regulators and client demand for enhanced mission capabilities.
Growth Catalysts
- Offshore Energy Demand:Exploration and production activities in deepwater oil and gas basins, particularly offshore Brazil and in the North Sea, require long-range, high-capacity helicopters for crew transport and logistical support, driving service demand.
- Advanced Avionics Adoption:The integration of digital cockpits and Health and Usage Monitoring Systems (HUMS) enhances safety and operational efficiency, making operators with modern fleets more competitive in parapublic and commercial tenders.
- Infrastructure Development:Expanding requirements for aerial surveying in large-scale infrastructure, renewable energy, and environmental monitoring projects are creating new revenue streams for specialized aerial work operators.
Market Restraints
- High Operational Costs:The cost structure is burdened by significant expenses for fuel, particularly sustainable aviation fuel (SAF), along with rigorous maintenance schedules and high pilot salaries, which can compress operator margins.
- Regulatory Compliance Burden:Stringent and frequently updated airworthiness and operational directives from authorities like the FAA and EASA necessitate continuous investment in training and equipment, increasing capital expenditure.
- Component Supply Chain Bottlenecks:Long lead times and limited global production capacity for critical components, such as advanced composite rotor blades and turbine engines, can delay aircraft delivery and maintenance schedules.
Strategic Opportunities
- Urban Air Mobility (UAM):The development of electric vertical takeoff and landing (eVTOL) aircraft opens future opportunities for short-haul passenger and cargo services in congested urban centers across North America and Asia.
- Wind Energy Support:The global expansion of offshore wind farms presents a significant opportunity for helicopter services, including hoist operations for technician transfer and aerial inspections of turbine blades.
- Emergency Service Privatization:A trend towards outsourcing Emergency Medical Services (EMS) and Search and Rescue (SAR) functions by government agencies creates opportunities for private operators with mission-ready, compliant fleets.
Industry Challenges
- Pilot and Technician Shortage:A global deficit of qualified helicopter pilots and certified maintenance technicians, driven by retirements and competition from airlines, poses a significant threat to operational capacity and growth.
- Fleet Modernization Capital:The substantial capital investment required to replace legacy helicopters with newer, more efficient, and SAF-compatible models presents a major financial hurdle for small and mid-sized operators.
- Digital Systems Integration:Integrating advanced avionics and data-intensive HUMS into existing operational frameworks requires significant investment in IT infrastructure, software, and specialized training for crew and ground staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Services Market |
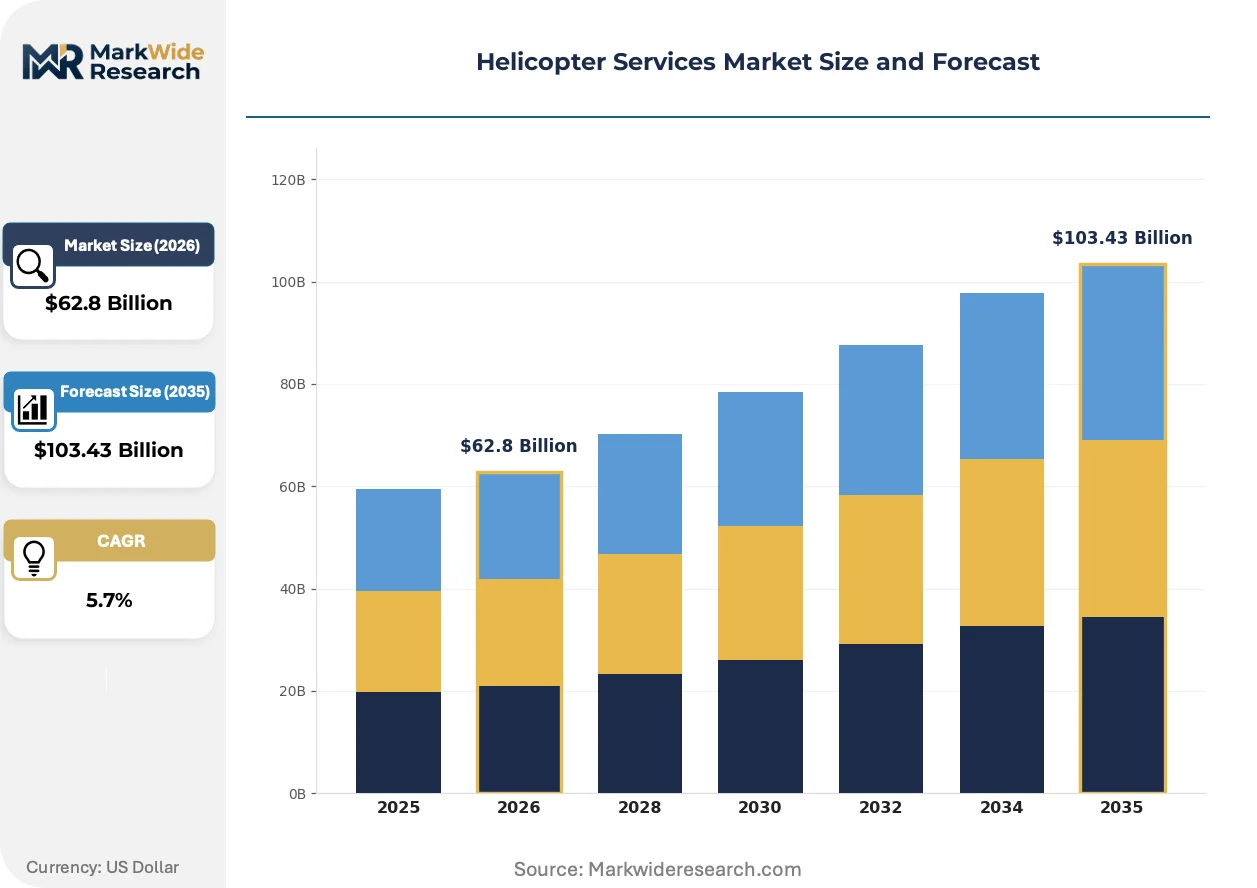
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $103.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Medical Services, Search & Rescue, Offshore Transport, Aerial Surveying, Law Enforcement, Firefighting Application: Oil & Gas Support, Tourism & Sightseeing, Cargo Transport, Agricultural Spraying, Construction Assistance, Event Coverage Customer Type: Government Agencies, Private Corporations, Non-Governmental Organizations, Military Units, Charters, News Media Deployment Model: Direct Ownership, Lease Agreements, Time & Material Contracts, Managed Services, Franchise Operation |
| Companies Covered | Air Methods Corporation, Airbus Helicopters, Bristow Group Inc., Lockheed Martin Corporation (Sikorsky Aircraft), Bell Textron Inc., CHC Group LLC, Leonardo S.p.A., Abu Dhabi Aviation, PHI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Services Market Strategic Shifts & Innovations
The digital transformation of the cockpit and maintenance operations defines the market's current trajectory. Data generated from advanced onboard systems is becoming a critical asset for optimizing flight safety, asset availability, and operational efficiency across all service segments.
Health and Usage Monitoring Systems (HUMS) provide real-time diagnostic data on critical aircraft components using an array of embedded sensors. Offshore transport and emergency medical service operators are rapidly adopting these systems to maximize aircraft availability and enhance safety protocols. The proliferation of smaller, more powerful onboard processors is miniaturizing the required diagnostic hardware, enabling more comprehensive data collection without imposing significant weight or power penalties on the aircraft.
European Union Aviation Safety Agency (EASA) regulations are mandating the use of flight data monitoring (FDM) programs for an expanding range of commercial helicopter operations. This regulatory push forces operators to invest in data recording and analysis capabilities to proactively identify safety risks and improve pilot training. Helicopter fleets serving the North Sea energy sector are at the forefront of this compliance-driven technology adoption.
A clear shift toward longer-term, availability-based service contracts is altering how end-users procure helicopter support. This model, which replaces traditional ad-hoc chartering, provides operators with predictable revenue streams while transferring the risk of aircraft downtime away from the client. This contracting structure is most visible in the offshore energy sector, where continuous, reliable transport is a critical operational requirement.
Helicopter Services Market Segmentation
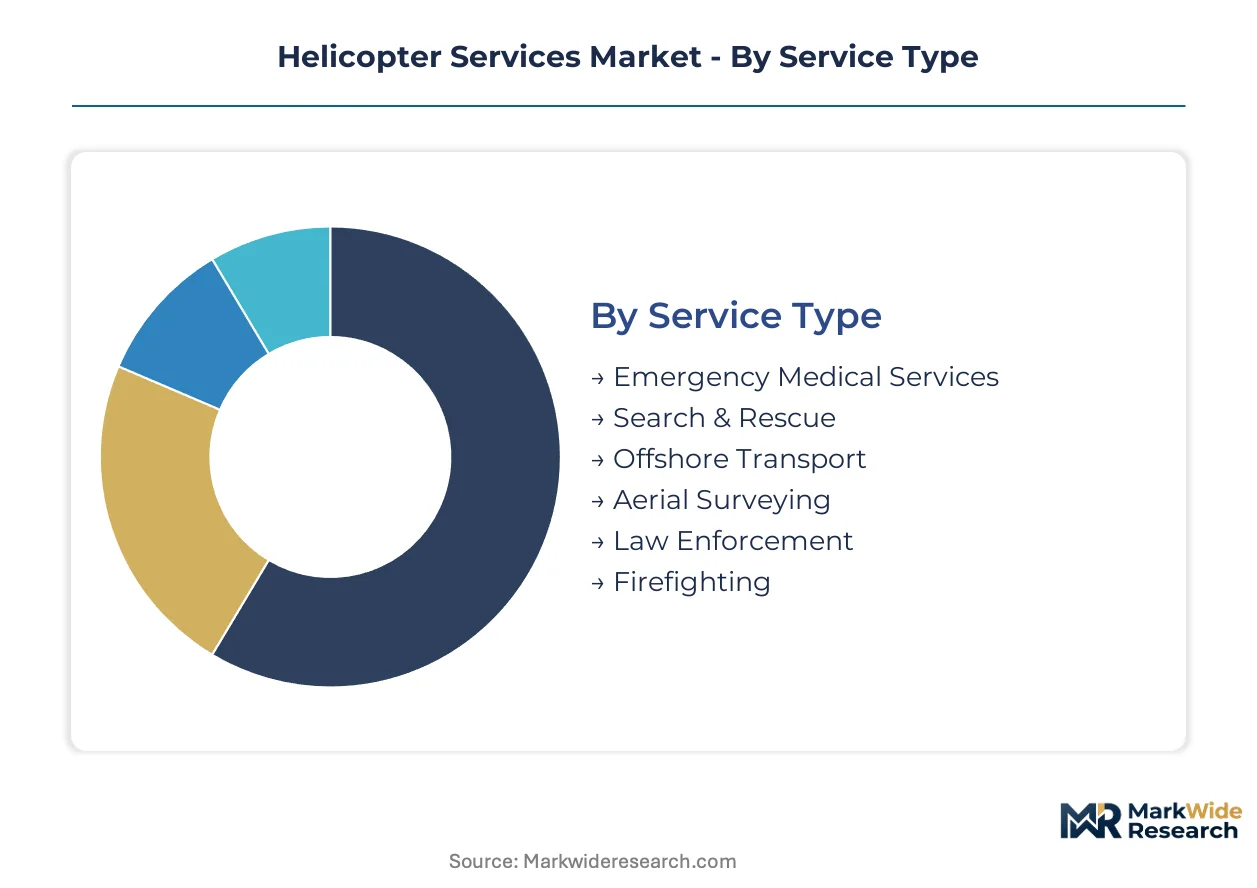
Understanding the distinct segments within the helicopter services market reveals varied operational demands and regulatory landscapes. Each service type, application, customer, and deployment model carries unique requirements for aircraft capability and financial structuring. This granular analysis guides strategic investment in fleet modernization.
Service Type:
The operational parameters for helicopter service types are heavily influenced by specific regulatory frameworks governing safety, flight rules, and equipment mandates.
- Offshore Transport:Long-range flights over water require multi-engine aircraft with advanced navigation and flotation. Demand concentrates in deepwater oil and gas basins, including offshore Brazil, for critical personnel transfer.
- Emergency Medical Services:EMS operations utilize helicopters with specialized medical equipment, requiring trained flight and medical crews for rapid patient transport. Demand from North American healthcare systems drives critical care access.
- Search & Rescue:SAR missions involve hoist operations and specialized sensors, conducted by government agencies for emergencies.
- Aerial Surveying:Aerial surveying supports infrastructure development and environmental monitoring, using helicopters with LiDAR and thermal cameras.
- Law Enforcement:Law enforcement agencies deploy helicopters for surveillance and tactical support, equipped with electro-optical sensors.
- Firefighting:Firefighting services utilize helicopters for aerial suppression and personnel insertion in remote wildfire zones.
Offshore Transport handles the majority of throughput; Aerial Surveying is the fastest mover on share.
Application:
Each helicopter application dictates specific operational requirements for aircraft configuration, payload capacity, and crew expertise.
- Oil & Gas Support:Helicopters provide essential logistical support for offshore and onshore oil and gas operations, including crew changes. Deepwater exploration projects in the North Sea drive this application.
- Construction Assistance:Helicopters perform precision lifting, material transport, and personnel placement for construction projects. Infrastructure development in North America, particularly for renewable energy, drives demand.
- Tourism & Sightseeing:Tourism and sightseeing flights offer aerial tours over scenic locations, requiring comfortable cabins.
- Cargo Transport:Cargo transport moves high-value freight to remote locations, utilizing helicopters with significant lift capabilities.
- Agricultural Spraying:Agricultural spraying helicopters precisely apply pesticides and fertilizers over large crop areas.
- Event Coverage:Event coverage involves aerial photography and live broadcasting for major public events.
Oil & Gas Support applications command the highest flight hours; Construction Assistance is expanding most quickly by new project volume.
Customer Type:
Customer types exhibit distinct procurement models and service expectations, influencing contract duration and mission complexity.
- Government Agencies:Government agencies procure helicopter services for diverse parapublic missions, including law enforcement and search and rescue. Stricter safety mandates from the FAA compel fleet upgrades or outsourcing.
- Private Corporations:Private corporations in energy and construction utilize helicopters for personnel transport and logistical support. Deepwater oil and gas exploration in offshore Brazil drives contract demand.
- Non-Governmental Organizations:NGOs deploy helicopters for humanitarian aid and disaster relief, operating in challenging environments.
- Military Units:Military units employ helicopters for tactical transport and combat support, frequently requiring advanced avionics.
- Charters:Charter services provide on-demand executive transport, tourism, and specialized aerial tasks.
- News Media:News media organizations use helicopters for live reporting and rapid deployment to breaking news.
Government Agencies represent the dominant customer segment; Non-Governmental Organizations are gaining procurement volume for humanitarian operations.
Deployment Model:
The chosen deployment model significantly influences an operator's capital expenditure, operational flexibility, and risk management profile.
- Lease Agreements:Lease agreements allow operators to access modern aircraft fleets without large upfront capital, enabling fleet upgrades. Stricter safety mandates from EASA compel operators to lease compliant aircraft.
- Managed Services:Managed services involve comprehensive outsourcing of helicopter operations, including maintenance and crew. Outsourcing EMS and SAR functions by government agencies creates opportunities.
- Direct Ownership:Direct ownership provides full control over asset utilization and maintenance, requiring substantial capital.
- Time & Material Contracts:Time & Material contracts bill clients for actual hours flown and materials used, offering flexibility.
- Franchise Operation:Franchise operations involve a licensee operating under a franchisor's brand and operational standards.
Lease Agreements balance cost efficiency with operational control for many operators; Managed Services are increasingly preferred for comprehensive support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Helicopter Services Market exhibits a varied regional demand, with some nations serving as net exporters of specialized operational expertise while others primarily import advanced capabilities. This dynamic shapes fleet investment and service contract structures across continents. Significant regional variations in regulatory oversight further influence operational models.
United States
Offshore energy exploration and emergency medical services drive substantial demand for helicopter services in the United States. Federal Aviation Administration (FAA) regulations mandate stringent pilot certification and maintenance protocols for all commercial operations. Key operators in Houston, Texas, focus on supporting the Gulf of Mexico's extensive oil and gas infrastructure.
United Kingdom
The North Sea oil and gas sector, alongside a robust demand for search and rescue operations, underpins the helicopter services market in the United Kingdom. European Union Aviation Safety Agency (EASA) directives, even post-Brexit through retained law, influence fleet modernization and safety standards. Aberdeen, Scotland, remains a vital hub for offshore transport services.
Brazil
Deepwater oil and gas basins off the coast of Brazil require long-range, high-capacity helicopters for personnel and equipment transfer. The country's national aviation authority dictates specific requirements for offshore flight operations and emergency procedures. Rio de Janeiro serves as a primary operational base for helicopter services supporting the pre-salt layer exploration.
United Arab Emirates
The United Arab Emirates sees consistent demand for helicopter services in oil and gas support, executive transport, and tourism. The General Civil Aviation Authority (GCAA) implements strict safety and operational standards, aligning with international best practices. Dubai's aviation cluster caters to a wide array of commercial and private helicopter operations.
Australia
Mining and resource sector support, coupled with extensive remote area search and rescue, fuels the helicopter services market across Australia. The Civil Aviation Safety Authority (CASA) oversees all aviation activities, including specialized aerial work and emergency services. Perth, Western Australia, supports critical logistics for the region's vast mining operations.
Helicopter Services Market Key Industry Players
Concentration sits with a few large, globally operating service providers and major original equipment manufacturers (OEMs) in the helicopter services market. The industry structure is tiered, featuring a strong presence of integrated service firms alongside specialized niche players. Strategic archetypes include full-service offshore operators, specialized medical and parapublic providers, and aircraft lessors. Operators pursue strategic partnerships and fleet modernizations to enhance their market position.
Full-service offshore operators like Bristow Group Inc. exemplify the market's demand for integrated, complex mission capabilities, particularly for energy sector clients. Bell Textron Inc., as a prominent North American original equipment manufacturer, anchors the segment requiring advanced flight deck technologies across its commercial helicopter lines. Airbus Helicopters, a major European aerospace manufacturer, represents a key player leveraging proprietary avionics platforms to secure diverse contracts across emergency medical and law enforcement segments. These companies collectively demonstrate the varied approaches to market leadership.
| Leading Market Players |
|---|
| Air Methods Corporation |
| Airbus Helicopters |
| Bristow Group Inc. |
| Lockheed Martin Corporation (Sikorsky Aircraft) |
| Bell Textron Inc. |
| CHC Group LLC |
| Leonardo S.p.A. |
| Abu Dhabi Aviation |
| PHI Inc. |
| Others |
Cost & Logistics Intelligence
Scale economies in helicopter maintenance and operational support underwrite the market structure. This scale shapes both service provider concentration and price floors for long-term contracts in critical segments.
Pricing Analysis
Government agencies anchor long-term, outcome-based contracts for helicopter services. Pricing stratifies across premium, standard, and economy tiers, driven by aircraft capabilities like maximum takeoff weight and the operator's safety record. High operational costs, including sustainable aviation fuel and pilot salaries, compress margins. Pricing pressure stems from the capital intensity of fleet modernization. Government agencies and offshore energy clients are typically less price-sensitive due to mission criticality, while private charter clients exhibit higher price sensitivity.
Supply Chain Analysis
Component supply chain bottlenecks for advanced composite rotor blades and turbine engines underwrite global delivery schedules. Supply for critical components concentrates in Europe with Airbus Helicopters and Leonardo S.p.A., and in North America with Bell Textron Inc. and Lockheed Martin Corporation. Raw material dependencies include specialized alloys for engines and advanced composites for airframes. Single-source vulnerability for specialized avionics systems presents a structural risk. Distribution runs through direct sales from original equipment manufacturers and a network of certified maintenance, repair, and overhaul (MRO) providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The helicopter services market presents high-growth disruption. Advanced digital avionics suites and integrated HUMS represent a significant technological inflection point.
For Market Incumbents: Consolidate specialized service capabilities through strategic acquisitions targeting niche operators. Invest heavily in fleet modernization with SAF-compatible aircraft to meet evolving environmental mandates and client demands. This strategy mitigates the threat of new entrants leveraging advanced technology and addresses the pilot and technician shortage by offering modern platforms. Focus on vertical integration into MRO to secure critical maintenance capacity.
For New Entrants and Emerging Players: Lead with specialized, digitally-enabled solutions for underserved or emerging applications. Target Urban Air Mobility (UAM) infrastructure development or offshore wind energy support, which represent significant white-space opportunities. Aerial surveying for renewable energy projects is a penetrable segment. A strong go-to-market angle involves offering efficiency gains and safety enhancements through advanced HUMS data analytics and predictive maintenance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators securing long-term availability-based service contracts. Long-term demand for critical infrastructure support, such as offshore energy and emergency medical services, ensures sustained revenue streams. Acquire mid-sized operators with modern, compliant fleets and strong regional presence in high-demand basins like offshore Brazil. Increased regulatory mandates for advanced safety systems, such as EASA FDM programs, serve as a key signal to watch for market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization Program | Replaces aging aircraft with next-generation, SAF-compatible models for enhanced operational efficiency. |
| Digital Avionics Integration | Enhances pilot situational awareness and reduces operational workload in complex missions. |
| MRO Capability Expansion | Secures critical maintenance capacity for advanced composite rotor blades and turbine engines. |
| Strategic Alliance for UAM | Positions for future urban air mobility opportunities with eVTOL aircraft developers. |
| Pilot Training Academy Investment | Addresses global deficit of qualified helicopter pilots for sustained operational capacity. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the data collection process. Primary insights from helicopter service operators, fleet managers, aviation safety officers, and offshore energy project leads were gathered. These insights were validated against secondary data from FAA and EASA regulatory documents, industry association reports, and OEM financial filings. The research employed both bottom-up and top-down approaches for comprehensive market triangulation.
Across the analysis window, the quantitative framework models market evolution. Segmentation dimensions included service type, application, customer type, deployment model, and regional demand patterns. Compound Annual Growth Rates were derived from historical data analysis and projected future demand trends. Key industry-specific forecast inputs included offshore oil and gas exploration budgets and new wind farm development schedules.
Underlying assumptions cover fleet modernization rates and regulatory compliance, with deviation risk concentrated in fuel price volatility and pilot availability. Practitioners should keep alternative scenarios live as global energy policies and aviation safety mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
Domestic Aviation Market
Aviation and Defense Training and Simulation
Global Airlines Market
Aviation and Defense Training and Simulation
North America Charter Jet Services Market
Aviation and Defense Training and Simulation
South-East Asia Civil Aviation Market
Aviation and Defense Training and Simulation
US Helicopter Services Market
Aviation and Defense Training and Simulation
Digital Aviation Market
Aviation and Defense Training and Simulation
Charter Jet Services Market
Aviation and Defense Training and Simulation
Middle-East and Africa Jet Charter Services Market