
 Digital Aviation Market | 2026-2036
Digital Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Aviation Market Analytics
Asset-light leasing and power-by-the-hour financing is tilting competitive dynamics toward vendors with recurring revenue platforms rather than one-time hardware sales. Honeywell leverages its integrated avionics ecosystem to sustain long-term service contracts across commercial fleets. Airbus Skywise anchors its position through open data architecture that competes with proprietary airline systems. RTX specializes in sensor-to-cloud analytics, differentiating its maintenance solutions from point-product rivals.
Digital aviation encompasses the networked hardware, software, and data infrastructure that optimizes flight operations, aircraft health monitoring, and ground-to-air coordination through real-time telemetry and predictive algorithms. The primary purpose is to reduce fuel burn, minimize unscheduled downtime, and enhance safety margins across commercial and cargo fleets. Flight Operations within the Service Type dimension leads current deployment as carriers prioritize route optimization and fuel efficiency dashboards. Artificial Intelligence under the Technology segment represents the fastest-expanding capability area, with airlines deploying machine learning models for predictive maintenance and crew scheduling optimization.
FAA airworthiness directives and EASA certification standards shape product development timelines by mandating cybersecurity resilience and data integrity in connected aircraft systems. The EU AI Act introduces additional compliance layers for automated decision systems used in flight planning and safety management applications. China's CAAC and GB standards enforce localized data sovereignty requirements that redirect vendor architecture decisions. Stakeholders must weigh regulatory fragmentation against platform standardization when allocating R&D budgets across jurisdictions.
Market Dynamics
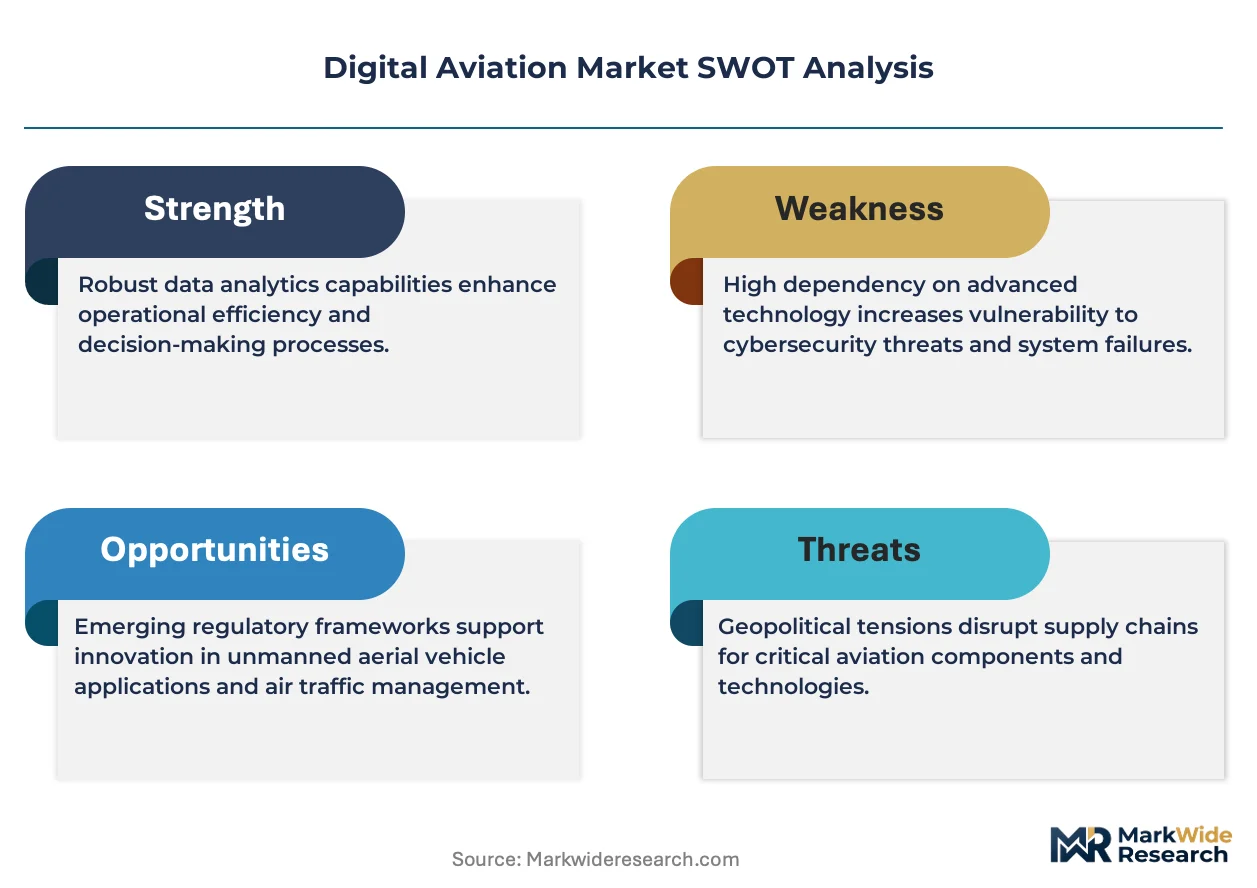
Power-by-the-hour financing models are restructuring vendor economics toward recurring revenue platforms and compressing hardware-only business models across commercial aviation fleets.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for cybersecurity resilience in connected aircraft systems are accelerating fleet-wide avionics upgrades and predictive maintenance platform deployments.
- Machine Learning Adoption:Airlines are integrating AI-driven crew scheduling and fuel optimization algorithms that reduce operational costs and unscheduled downtime.
- China Fleet Modernization:CAAC enforcement of localized data sovereignty requirements is redirecting vendor architecture decisions and stimulating domestic smart airport investments.
Market Restraints
- Semiconductor Supply Concentration:Avionics manufacturers face input volatility from concentrated Asian foundry capacity, extending lead times for flight control systems.
- EASA Certification Timelines:Extended validation cycles for software-updatable equipment create regulatory friction that delays product commercialization.
- Legacy System Interoperability:Technical limitations in bridging proprietary airline data architectures with open-platform solutions constrain upgrade pathways.
Strategic Opportunities
- India Fleet Expansion:Underpenetrated narrowbody and regional jet markets offer white space for digital cockpit retrofits as domestic carriers double fleet sizes.
- EU AI Act Tailwinds:Compliance frameworks for automated flight planning systems create first-mover advantages for certified algorithm vendors.
- Edge-to-Cloud Convergence:Integration of onboard sensor processing with ground-based analytics enables real-time health monitoring services.
Industry Challenges
- Embedded Systems Engineering Talent:Shortages in aviation-certified software developers extend development cycles and inflate compensation costs.
- Type Certificate Amendment Costs:Hardware-software integration complexity demands capital-intensive recertification for each platform variant.
- Multi-Jurisdiction Compliance:Divergent FAA, EASA, and CAAC cybersecurity standards fragment R&D allocation and delay unified product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Aviation Market |
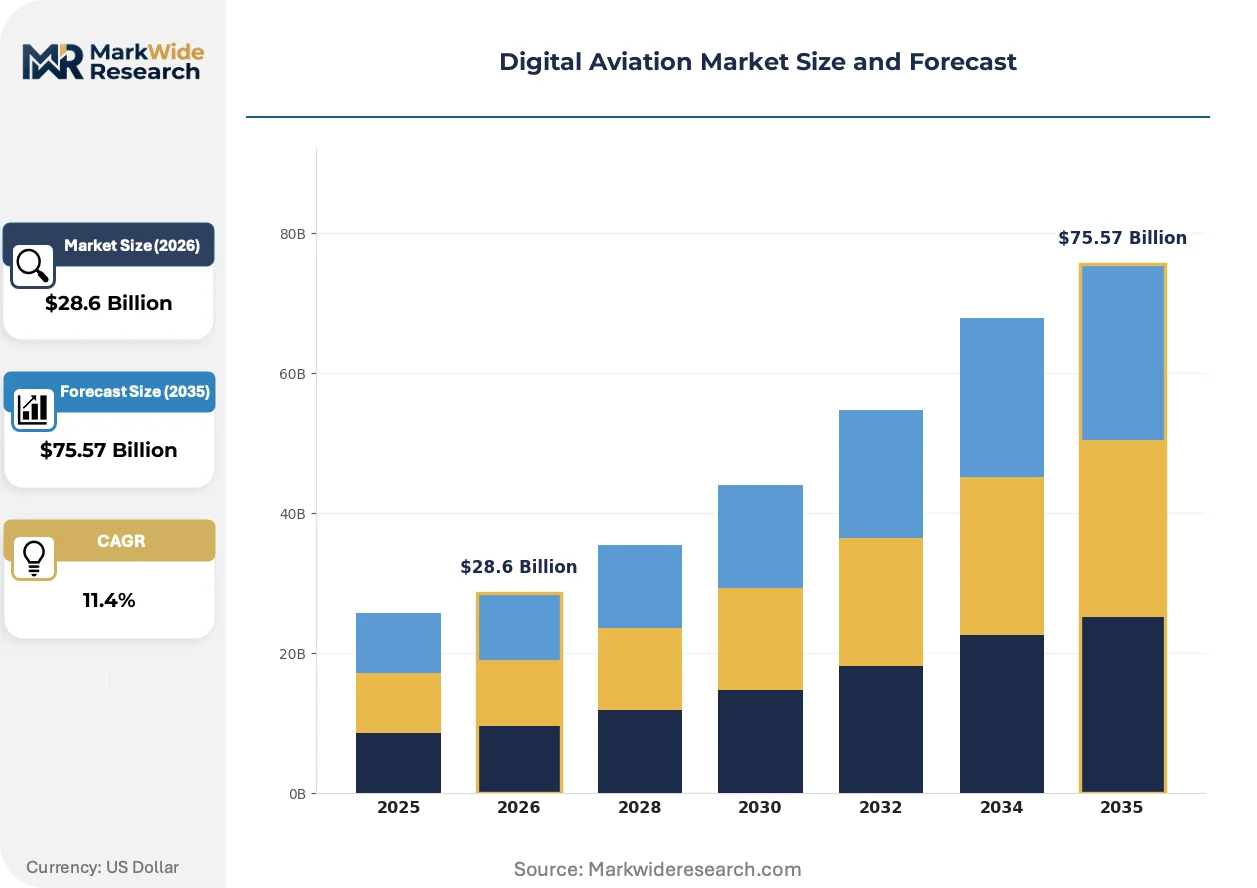
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Flight Operations, Maintenance Solutions, Ground Services, Navigation Systems Application: Passenger Experience, Cargo Management, Flight Planning, Safety Management Technology: Artificial Intelligence, IoT Solutions, Data Analytics, Blockchain End User: Airlines, Airports, Service Providers, Government Agencies |
| Companies Covered | RTX, Boeing HorizonX, Honeywell, AirSense Analytics, avathon, IBM, Airbus Skywise, Kaiban, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Aviation Market Evolving Landscape
Aviation data architectures are fragmenting between proprietary airline systems and vendor-agnostic open platforms, forcing suppliers to choose interoperability strategies.
Digital twin technology for aircraft propulsion and airframe systems is hybridizing physical simulation with live telemetry feeds. MRO providers and fleet operators are adopting these fused models at accelerating pace for predictive maintenance. This convergence is hybridizing hardware service contracts with software subscription revenue, compressing traditional parts-based business models.
The EU AI Act's risk classification framework for automated decision systems is reshaping flight planning software development. Developers must now embed explainability and human oversight mechanisms into algorithmic route optimization tools. European carriers and their technology partners are responding by restructuring AI procurement to prioritize certified transparent systems over black-box alternatives.
Airline technical procurement teams are unbundling integrated avionics suites to source best-of-breed components from specialized vendors. This disintermediation of traditional full-stack suppliers is fragmenting purchasing authority across engineering, IT, and finance functions. North American legacy carriers are most visibly advancing this pattern, driven by pressure to reduce capital deployment per aircraft while accelerating digital capability refresh cycles.
Digital Aviation Market Segmentation
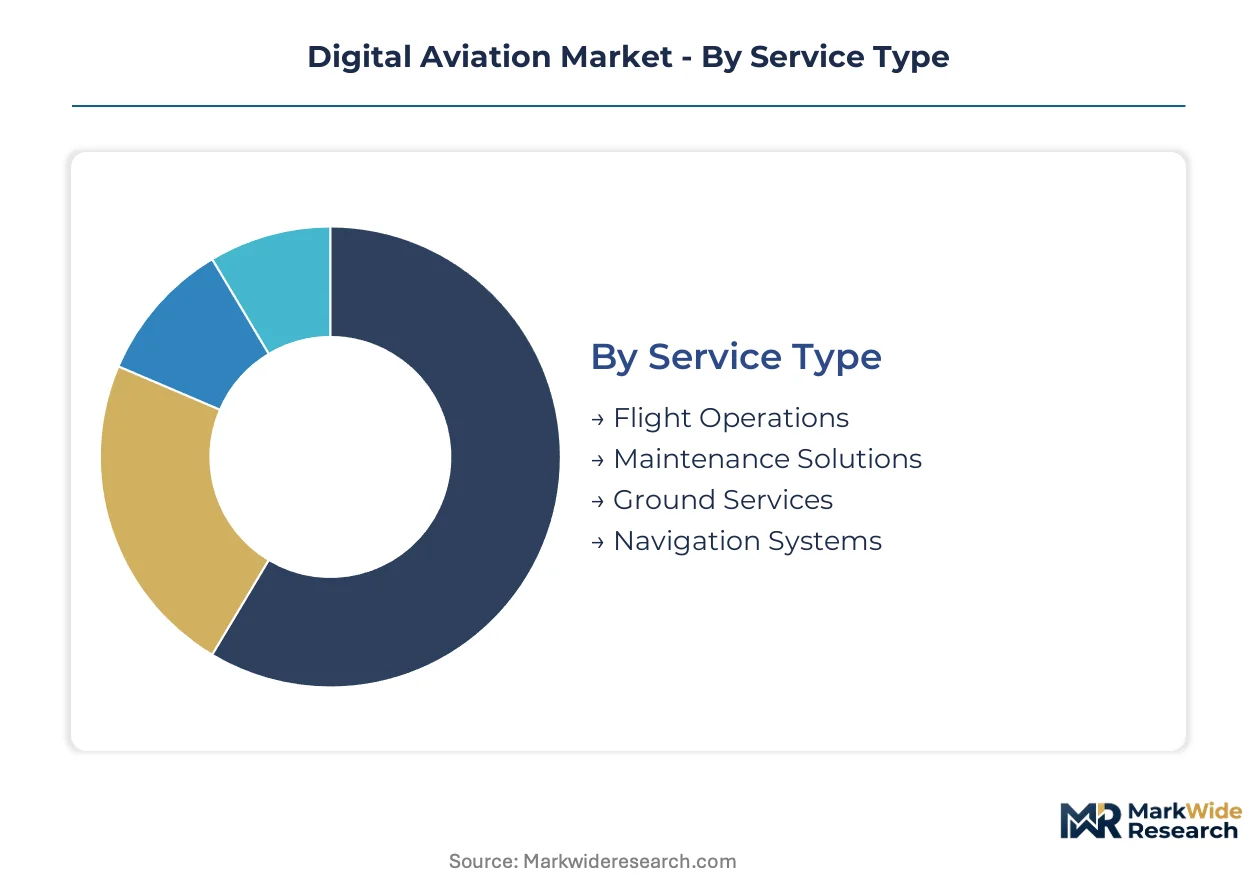
Digital aviation procurement decisions fragment across operational, regulatory, and technological dimensions. Each segment category carries distinct margin profiles and after-sales-service intensity that reshape vendor commercial strategies.
Service Type:
After-sales-service intensity varies dramatically across service categories, with recurring platform revenue displacing one-time hardware sales.
- Flight Operations:Route optimization dashboards and fuel efficiency algorithms dominate current airline procurement budgets. United States and Germany lead deployment as carriers face tightening FAA and EASA emissions compliance deadlines.
- Maintenance Solutions:Predictive analytics platforms integrate sensor-to-cloud architectures for unscheduled downtime reduction. Power-by-the-hour financing models accelerate adoption across narrowbody fleets in China and India.
- Ground Services:Turnaround optimization and baggage handling automation systems concentrate investment in smart airport programs.
- Navigation Systems:GPS augmentation and precision approach technologies require capital-intensive type certificate amendments.
By volume, Flight Operations leads. By growth pace, Maintenance Solutions is ahead.
Application:
Cost tier segmentation separates mission-critical safety systems from passenger-facing amenities with divergent procurement cycles.
- Safety Management:Real-time hazard detection and crew alerting systems anchor regulatory compliance investments. EASA certification standards and FAA airworthiness directives mandate continuous software updates across European and North American fleets.
- Flight Planning:AI-driven route optimization with embedded explainability mechanisms responds to EU AI Act risk classification requirements. European carriers prioritize certified transparent algorithms over black-box alternatives.
- Passenger Experience:In-flight connectivity and personalized service platforms compete for discretionary capital allocation.
- Cargo Management:Temperature monitoring and load optimization tools expand with dedicated freighter fleet growth.
Safety Management commands the highest per-unit spend. Passenger Experience expands most quickly as ancillary revenue competition intensifies.
Technology:
Customer type concentration splits between airline-operated proprietary systems and vendor-managed platform subscriptions.
- Artificial Intelligence:Machine learning models for predictive maintenance and crew scheduling optimization represent the capability area with steepest expansion trajectory. China's CAAC data sovereignty requirements redirect architecture decisions toward localized processing.
- IoT Solutions:Onboard sensor networks and edge computing devices bridge physical aircraft systems with ground analytics infrastructure.
- Data Analytics:Fleet-wide performance benchmarking and operational dashboards consolidate purchasing authority across airline IT and finance functions.
- Blockchain:Supply chain provenance and maintenance record verification pilots remain experimental with limited commercial scale.
Artificial Intelligence attracts the largest R&D allocation. IoT Solutions delivers the most predictable recurring revenue streams.
End User:
Supply concentration among full-service network carriers versus fragmented regional operators determines platform standardization feasibility.
- Airlines:Technical procurement teams unbundle integrated avionics suites to source best-of-breed components from specialized vendors. North American legacy carriers advance this disintermediation pattern most visibly.
- Airports:Smart infrastructure investments in the United States, Germany, and China drive demand for coordinated ground-to-air data exchange platforms.
- Service Providers:MRO operators adopt digital twin technology for propulsion and airframe predictive maintenance at accelerating pace.
- Government Agencies:Military and regulatory bodies impose cybersecurity resilience mandates that cascade through commercial certification requirements.
Airlines account for the dominant procurement volume. Airports demonstrate the fastest budget expansion as smart infrastructure programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Full-service network carriers in the United States, Germany, and China concentrate procurement authority for digital aviation platforms, while regional operators in India and Brazil expand fleet modernization budgets.
United States
Legacy carriers unbundle integrated avionics suites to source specialized components from multiple vendors. FAA airworthiness directives mandate cybersecurity resilience in connected aircraft systems, accelerating fleet-wide upgrades. Seattle and Wichita clusters host avionics engineering centers where predictive maintenance platforms undergo continuous software iteration.
Germany
Lufthansa Group and cargo operators prioritize AI-driven route optimization with embedded explainability mechanisms. EASA certification standards enforce extended validation cycles for software-updatable equipment, creating regulatory friction. Hamburg and Munich metropolitan areas concentrate MRO providers adopting digital twin technology for propulsion systems.
China
Domestic carriers double narrowbody fleet sizes while CAAC enforces localized data sovereignty requirements. GB standards and cybersecurity mandates redirect vendor architecture decisions toward onshore processing capabilities. Beijing and Shanghai smart airport programs drive ground-to-air coordination platform investments.
India
IndiGo and Air India expand technical procurement teams to manage digital cockpit retrofits across underpenetrated regional jet markets. The country's national aviation regulator tightens airworthiness data standards in alignment with international benchmarks. Bangalore and Hyderabad host engineering centers where airlines pilot sensor-to-cloud analytics for unscheduled downtime reduction.
Brazil
Azul and Gol Linhas Aéreas deploy fuel efficiency dashboards to manage emissions compliance costs across thin-margin domestic networks. ANAC, the national civil aviation agency, harmonizes certification requirements with FAA and EASA precedents to accelerate technology imports. São Paulo and Rio de Janeiro metropolitan areas concentrate airline IT procurement functions.
Digital Aviation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where integrated platform vendors extract recurring revenue while point-product suppliers face margin compression. Three archetypes dominate: full-stack aerospace conglomerates with captive avionics ecosystems, open-data platform specialists, and sensor-to-cloud analytics pure-plays. Consolidation pressure favors M&A activity among mid-scale maintenance software vendors, while technology licensing agreements proliferate between legacy hardware manufacturers and AI algorithm developers.
Among diversified aerospace conglomerates, RTX and Honeywell anchor positions through integrated avionics ecosystems that sustain long-term service contracts. Airbus Skywise exemplifies the open-data platform archetype, competing against proprietary airline systems through vendor-agnostic architecture.
| Leading Market Players |
|---|
| RTX |
| Boeing HorizonX |
| Honeywell |
| AirSense Analytics |
| avathon |
| IBM |
| Airbus Skywise |
| Kaiban |
| Microsoft |
| Others |
Value Network & Pricing Analysis
Seattle's avionics engineering cluster concentrates flight control system manufacturing capacity, translating concentrated semiconductor sourcing power into tiered subscription pricing for predictive maintenance platforms. Hardware vendors face margin compression as power-by-the-hour financing models displace upfront equipment sales across commercial fleets.
Pricing Analysis
Cost-plus contracts indexed to aerospace-grade semiconductor spot markets dominate avionics procurement. Three-tier pricing structure across premium, standard, and economy levels segments by FAA/EASA certification tier and after-sales service bundling intensity. Pricing pressure stems from airline technical procurement teams unbundling integrated suites to source specialized components. Regional operators exhibit highest price sensitivity; legacy network carriers prioritize certified reliability over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor tiered supplier relationships in avionics manufacturing. Taiwan, South Korea, and the United States concentrate semiconductor foundry capacity feeding flight control systems. The supply chain draws from gallium nitride substrates, radiation-hardened microcontrollers, and specialized aerospace connectors. Single-source vulnerability concentrates in advanced node fabrication. Distribution runs through OEM-authorized service centers and MRO channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power concentrates among full-service network carriers unbundling avionics suites, fragmenting purchasing authority across engineering and finance functions. This consolidation of procurement sophistication tilts vendor economics toward recurring platform revenue.
For Market Incumbents: Entrench platform stickiness through sensor-to-cloud analytics integration that locks in long-term service contracts. Deepen backward integration into edge computing hardware to offset semiconductor supply volatility. Counter airline disintermediation by embedding proprietary data architectures that resist open-platform migration. For New Entrants and Emerging Players: Pursue white space in India's underpenetrated regional jet retrofit market where domestic carriers double fleet sizes without legacy system baggage. Target CAAC-compliant localized processing architectures for China's data sovereignty requirements. Lead with power-by-the-hour financing to bypass capital-constrained airline procurement cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core maintenance software units to focus on integrated avionics hardware. Long-term viability favors vendors with recurring revenue platforms over point-product suppliers facing margin compression. Watch for FAA cybersecurity directive acceleration as inflection signal for fleet-wide upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Open Data Platform Integration | Airbus Skywise architecture competes against proprietary airline systems through vendor-agnostic interoperability. |
| Sensor-to-Cloud Analytics Acquisition | RTX and Honeywell anchor predictive maintenance positions through integrated avionics ecosystem control. |
| CAAC-Compliant Localization | GB standards enforcement redirects vendor architecture toward onshore processing capabilities in China. |
| Digital Twin Technology Licensing | MRO providers adopt hybrid physical simulation with live telemetry for propulsion system maintenance. |
| EU AI Act Certification Investment | European carriers prioritize explainable algorithms over black-box alternatives for flight planning procurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with avionics engineering directors, airline technical procurement leads, MRO operations managers, and regulatory compliance officers; and secondary validation through FAA airworthiness directive filings, EASA certification databases, CAAC regulatory notices, and airline fleet modernization disclosures. Bottom-up triangulation across service type, technology, and end-user segments converged with top-down market sizing.
Forecast inputs considered deployment trajectories across the projection horizon by service type, technology capability, application criticality, and end-user procurement authority. Segmentation dimensions modeled include flight operations versus maintenance solutions, AI versus IoT technology stacks, and airline versus airport end-user concentration. CAGRs derived from fleet expansion schedules, regulatory mandate timelines, and platform adoption curves specific to predictive maintenance and connected aircraft systems.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by open-data specialists or sensor-to-cloud pure-plays would shift outcomes. Macroeconomic deviation in fleet renewal cycles, regulatory acceleration in cybersecurity mandates, or breakthrough edge-AI processing efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
Charter Jet Services Market
Aviation and Defense Training and Simulation
Global Airlines Market
Aviation and Defense Training and Simulation
South-East Asia Civil Aviation Market
Aviation and Defense Training and Simulation
Domestic Aviation Market
Aviation and Defense Training and Simulation
Helicopter Services Market
Aviation and Defense Training and Simulation
North America Charter Jet Services Market
Aviation and Defense Training and Simulation
US Helicopter Services Market
Aviation and Defense Training and Simulation
Middle-East and Africa Jet Charter Services Market