
 Global Airlines Market | 2026-2036
Global Airlines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airlines Market Analysis
Wide-body aircraft deliveries from Boeing and Airbus is decoupling from pre-pandemic fleet planning assumptions. Delta Air Lines sustains its transatlantic network density through joint venture structures with European partners. Emirates dominates long-haul international capacity with an all-wide-body fleet strategy centered on Dubai's geographic position.
Airlines are commercial air transport operators providing scheduled and non-scheduled passenger and cargo services using fixed-wing aircraft with minimum certified payloads exceeding 3,400 kilograms. The industry functions through yield management systems optimizing revenue per available seat kilometer across variable route networks. Passenger Services generates the dominant revenue share within service type segmentation, while Cargo Services captures premium yields from pharmaceutical and e-commerce verticals. Commercial Jets constitute the fleet backbone across Aircraft Type segmentation, though Regional Aircraft command disproportionate slot access at constrained airports.
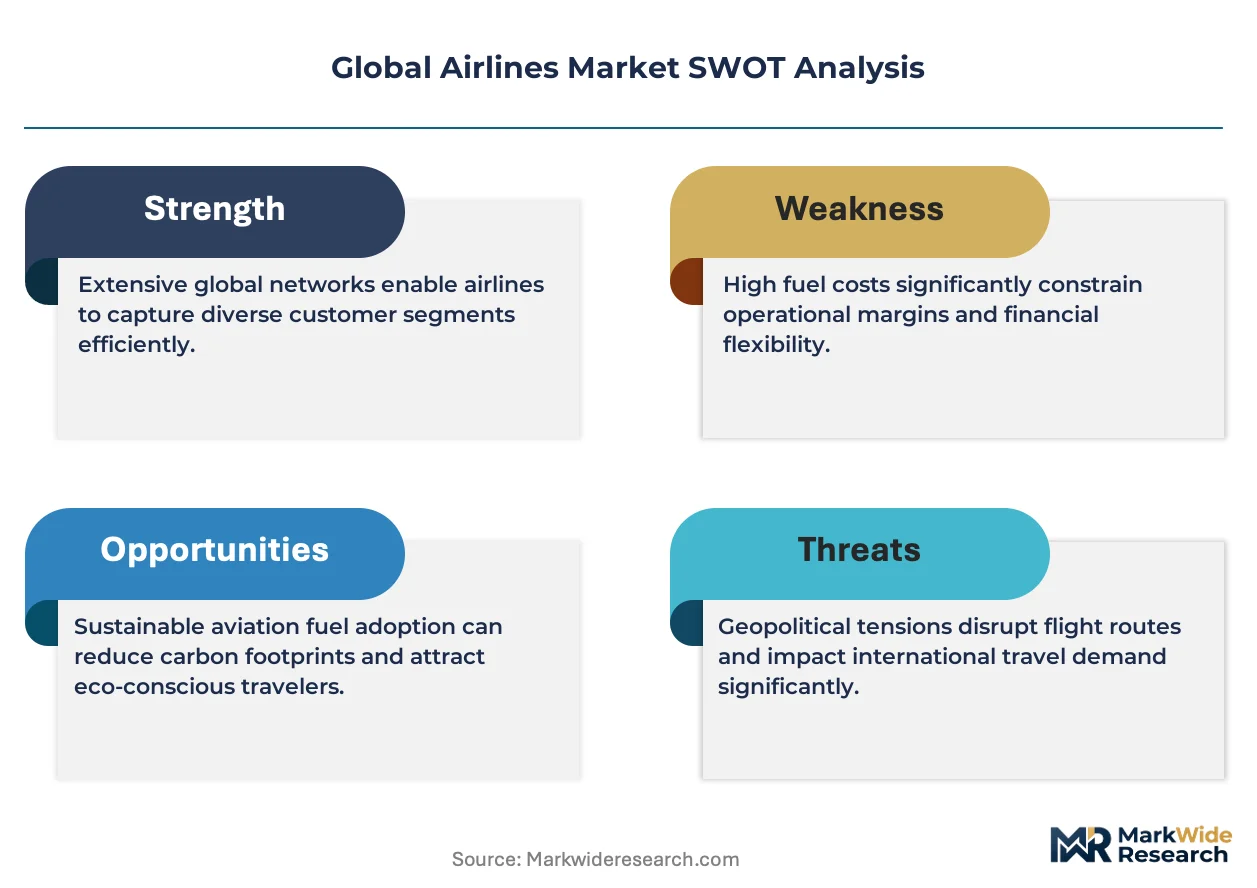
FAA certification standards govern aircraft airworthiness and pilot training protocols in the United States, while EASA oversees equivalent safety frameworks across European Union member states. The EU Green Deal's ReFuelEU Aviation mandate progressively raises sustainable aviation fuel blending obligations, reshaping fuel procurement contracts and fleet renewal timelines. ICAO's Carbon Offsetting and Reduction Scheme for International Aviation imposes emissions compliance costs on cross-border operations. Stakeholders must weigh fleet decarbonization pathways against shareholder return expectations as regulatory compliance costs escalate.
Market Dynamics
Fleet decarbonization mandates from the EU Green Deal are compressing aircraft replacement cycles and forcing carriers to renegotiate fuel procurement contracts against shareholder return expectations. This regulatory pressure cascades through every operational decision.
Growth Catalysts
- Sustainable Aviation Fuel Mandates:ReFuelEU Aviation progressively raises blending obligations, creating guaranteed offtake demand for alternative fuel producers and incentivizing fleet renewal toward more efficient aircraft types.
- India:Airports Authority of India is expanding runway capacity at Delhi and Mumbai while IndiGo and Air India place record narrow-body orders, concentrating passenger volume growth in South Asian corridors.
- Geographic Arbitrage:Dubai's position between Europe and Asia enables Emirates to capture sixth-freedom traffic that bypasses traditional hub-and-spoke networks through European gateways.
Market Restraints
- Jet Fuel Price Volatility:Brent crude fluctuations and refining capacity constraints at Singapore and Rotterdam directly compress operating margins for carriers lacking hedging sophistication.
- OEM Duopoly:Boeing and Airbus control virtually all commercial jet deliveries above 100 seats, creating queue risk and limiting pricing leverage for airline procurement teams.
- ICAO CORSIA Compliance Costs:Carbon offsetting obligations for international routes add measurable expense per available seat kilometer without delivering direct operational efficiency gains.
Strategic Opportunities
- Saudi Arabia:Saudia and Riyadh Air are building Jeddah and Riyadh into competing hubs with government-backed infrastructure spending and visa liberalization targeting transit passengers.
- Pharmaceutical Cold Chain:Temperature-controlled cargo services for biologics and vaccines command premium yields that offset passenger revenue seasonality on wide-body routes.
- LEAP-1A and PW1100G Convergence:Next-generation engine architectures enable single-aisle aircraft to operate transatlantic missions previously requiring twin-aisle equipment, opening point-to-point network possibilities.
Industry Challenges
- Pilot Certification Bottlenecks:FAA and EASA training hour requirements and simulator availability constraints limit crew supply expansion despite fleet growth.
- Maintenance Talent Scarcity:Airframe and powerplant mechanics with composite repair certification command wage premiums that inflate MRO costs at US and European bases.
- Legacy PSS Integration:Sabre and Amadeus reservation systems resist rapid modification for dynamic pricing and ancillary bundling, constraining revenue management innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airlines Market |
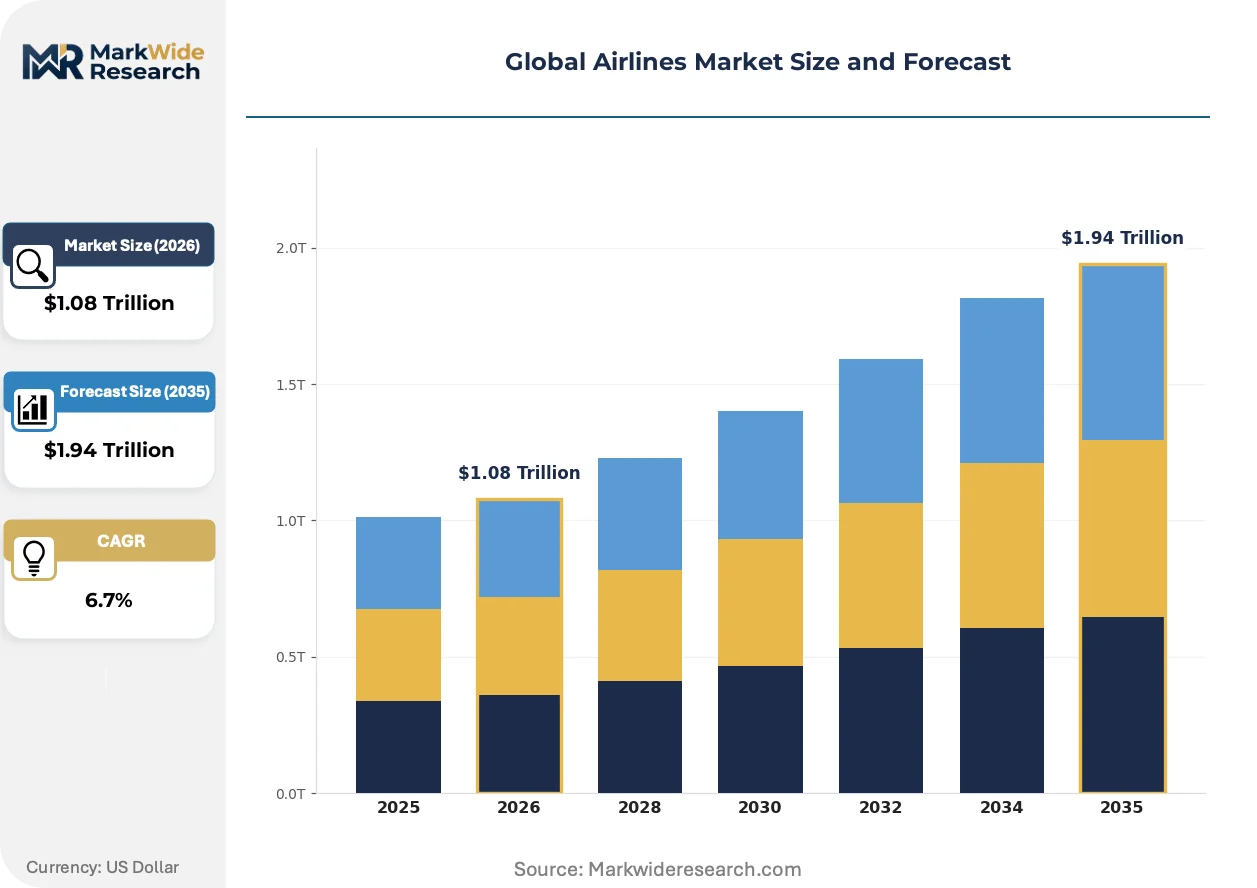
| Market Size in 2026 | $1.08 Trillion |
| Market Size in 2035 | $1.94 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Passenger Services, Cargo Services, Maintenance Services, Ground Services Aircraft Type: Commercial Jets, Cargo Planes, Private Jets, Regional Aircraft Booking Channel: Online Travel Agencies, Direct Bookings, Travel Agents, Mobile Apps Travel Class: Economy Class, Business Class, First Class, Premium Economy |
| Companies Covered | Lufthansa Group, International Airlines Group, Delta Air Lines, Air China, China Southern Airlines, United Airlines, Air France–KLM, Emirates, American Airlines Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airlines Market Emerging Trajectories
Digital distribution channels and alternative propulsion architectures are fragmenting traditional carrier business models while creating new revenue attachment points beyond the seat.
Advanced engine monitoring through embedded sensors and edge computing is modularizing maintenance planning. Low-cost carriers with high fleet commonality deploy these systems to compress A-check intervals and shift from fixed to condition-based overhaul schedules. This modularizing of maintenance responsibility between airlines and OEMs through power-by-the-hour contracts transfers balance sheet risk while locking in long-term supplier relationships.
ReFuelEU Aviation's progressive blending mandates are restructuring fuel supply contracts. Airlines must now secure offtake agreements with SAF producers years ahead of delivery, forcing procurement teams to become commodity traders. European network carriers face the steepest compliance curves and are responding by pooling purchasing consortia to achieve volume commitments that individual carriers cannot support.
Corporate travel managers are unbundling policy compliance from booking execution. Third-party platforms now audit expense data against sustainability criteria, directing employees toward carriers with verified emissions disclosures. This behavior shift is most visible in Germany and the Netherlands, where CSRD reporting requirements extend to scope-three travel emissions and procurement teams select vendors based on CORSIA participation status rather than schedule convenience alone.
Global Airlines Market Segmentation
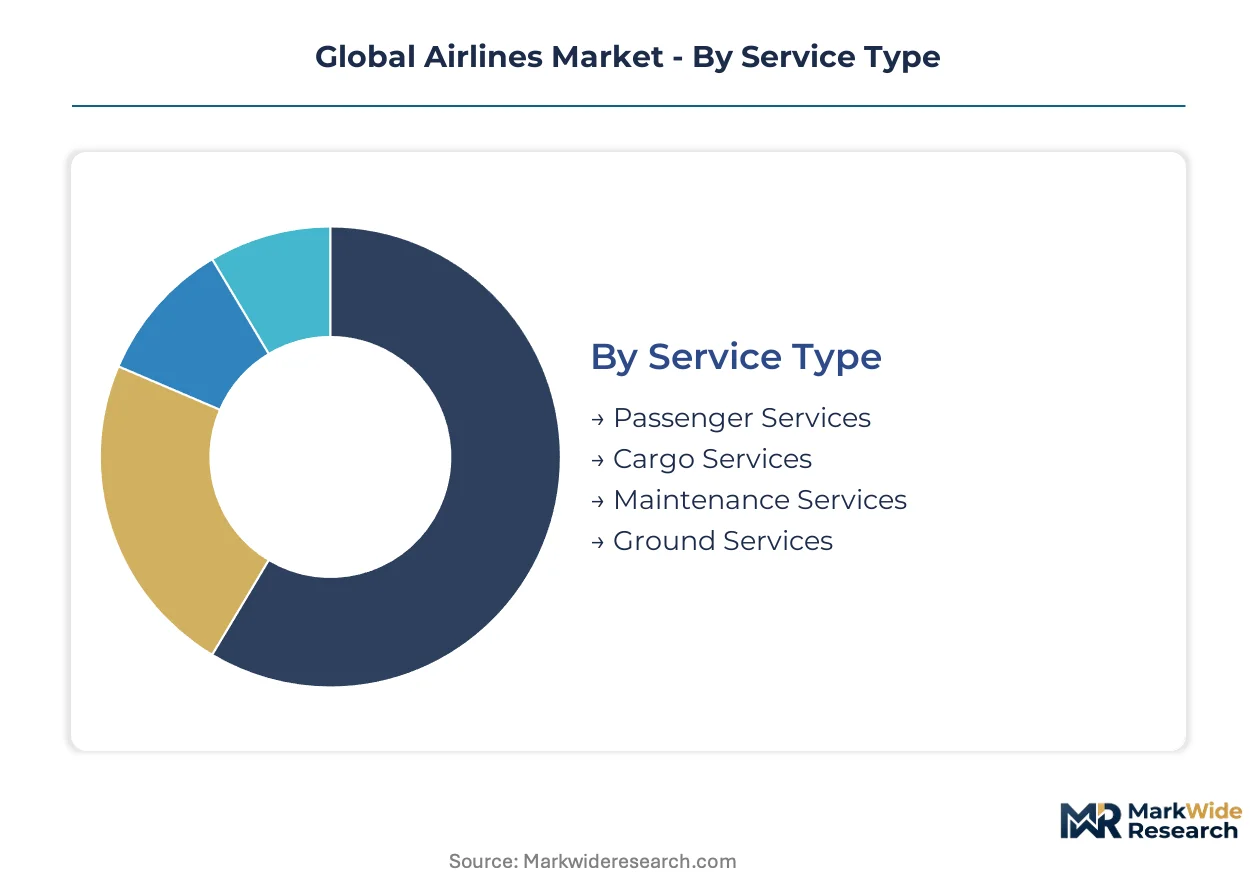
Airline revenue architecture fragments across four distinct axes. Service type determines capital intensity and margin profile. Aircraft type governs route economics and regulatory exposure. Booking channel and travel class shape yield management sophistication and customer lifetime value extraction.
Service Type:
Technology intensity varies sharply across service modalities, from capital-heavy flight operations to labor-intensive ground handling.
- Passenger Services:Scheduled and non-scheduled air transport using fixed-wing aircraft above 3,400 kilograms certified payload. Demand concentrates in India and the Middle East as emerging aviation hubs expand runway capacity and visa liberalization programs attract transit volume.
- Cargo Services:Dedicated freight operations and belly-hold utilization on passenger wide-bodies. Pharmaceutical cold chain services for biologics command premium yields from temperature-controlled infrastructure at Singapore and Rotterdam hubs.
- Maintenance Services:Airframe, engine, and component overhaul including composite repair certification. MRO talent scarcity at US and European bases inflates labor costs as mechanics with specialized credentials command wage premiums.
- Ground Services:Ramp handling, baggage systems, and passenger terminal operations. Airport privatization in Saudi Arabia and India is fragmenting incumbent ground handler relationships.
Mature deployment sits with Passenger Services. Newer deployment is concentrated in Cargo Services.
Aircraft Type:
Cost tier stratification separates long-haul capital commitments from regional fleet flexibility.
- Commercial Jets:Narrow-body and wide-body aircraft from Boeing and Airbus above 100 seats. Fleet renewal timelines compress under EU Green Deal mandates as carriers renegotiate procurement against shareholder return expectations.
- Cargo Planes:Dedicated freighter conversions and factory-built pure freighters. E-commerce verticals from Southeast Asia drive dedicated freighter demand on trans-Pacific corridors.
- Private Jets:Business aviation aircraft below commercial certification thresholds. Fractional ownership models expand in the Middle East as wealth concentration supports on-demand charter platforms.
- Regional Aircraft:Turboprops and small jets below 100 seats. Slot-constrained airports at London City and Tokyo Haneda depend on regional equipment for frequency maintenance.
Commercial Jets absorb the dominant capital allocation. Regional Aircraft gain share fastest at infrastructure-constrained nodes.
Booking Channel:
Customer acquisition economics diverge between direct ownership and intermediary dependency.
- Online Travel Agencies:Third-party platforms aggregating inventory across multiple carriers. Corporate travel managers in Germany and the Netherlands now audit OTAs against sustainability criteria from CSRD reporting requirements.
- Direct Bookings:Carrier-owned websites and loyalty program channels. Dynamic pricing and ancillary bundling constraints from legacy Sabre and Amadeus systems limit revenue management innovation.
- Travel Agents:Traditional intermediaries serving complex multi-leg itineraries. Consolidation in corporate travel management reduces independent agency count in North American and European markets.
- Mobile Apps:Native applications with biometric boarding pass integration. IndiGo and Air India deploy mobile-first strategies for India's digitally native passenger base.
Direct Bookings retain the highest margin per transaction. Mobile Apps are expanding most quickly in emerging markets with smartphone-first demographics.
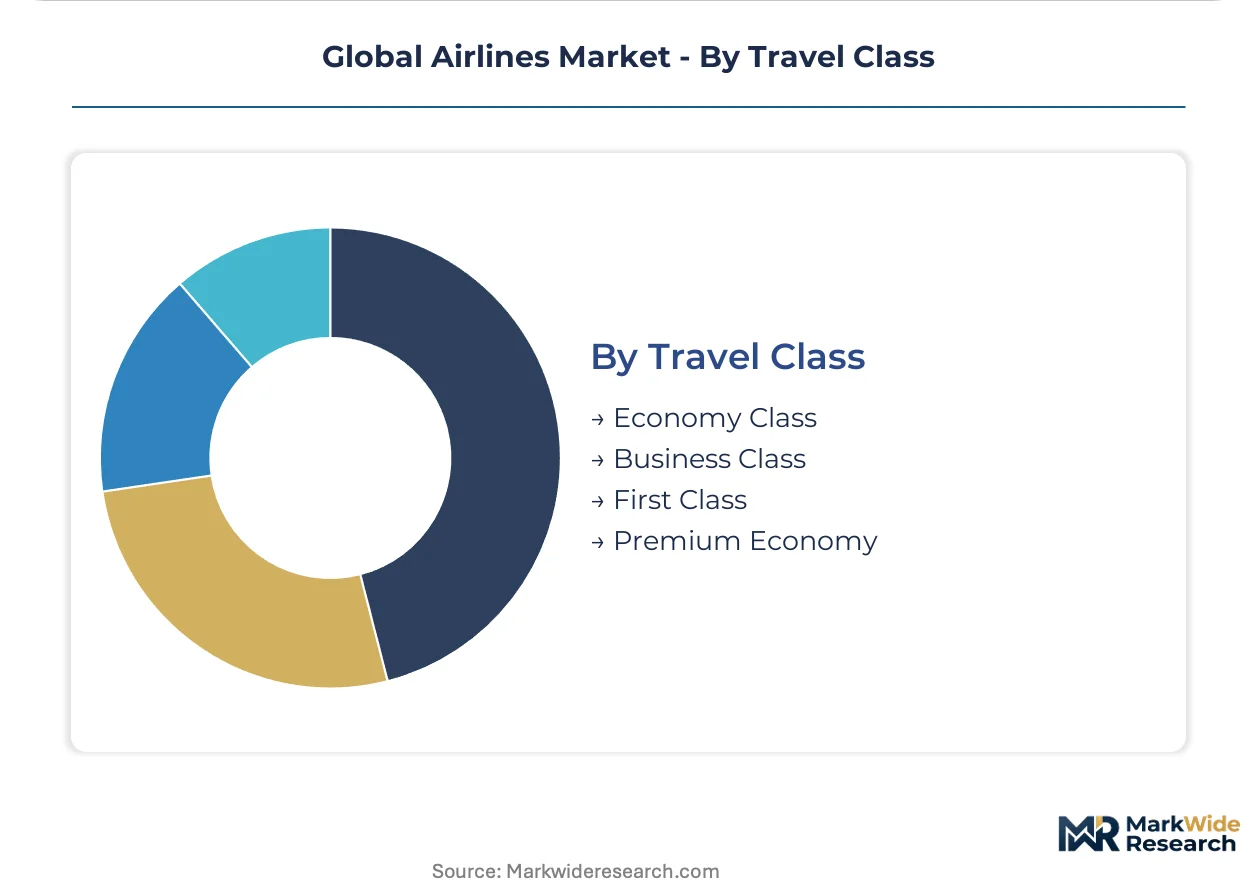
Travel Class:
Margin structure stratifies across cabin density and service intensity tiers.
- Economy Class:High-density seating configurations maximizing available seat kilometers. Low-cost carriers with high fleet commonality deploy yield management systems optimizing load factor over unit revenue.
- Business Class:Lie-flat seating and priority ground services on long-haul routes. Joint venture structures between Delta Air Lines and European partners sustain transatlantic network density through coordinated premium inventory.
- First Class:Ultra-premium cabins with enclosed suites and dedicated service. Emirates dominates this segment through Dubai's sixth-freedom geographic arbitrage between Europe and Asia.
- Premium Economy:Intermediate cabin product with enhanced pitch and meal service. Single-aisle aircraft with LEAP-1A and PW1100G engines now operate transatlantic missions previously requiring twin-aisle equipment, opening point-to-point premium economy routes.
Business Class generates the highest absolute contribution margin. Premium Economy climbs the fastest as carriers unbundle legacy first and business products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet fuel refining capacity at Singapore and Rotterdam anchors supply security for carriers operating between Europe and Asia. Fleet procurement decisions increasingly weigh regulatory exposure from EU Green Deal mandates against growth opportunities in India and the Middle East.
United States
Corporate travel recovery and premium cabin demand from financial services and technology sectors drive yield improvements. FAA certification standards govern pilot training protocols and aircraft airworthiness approvals. Dallas-Fort Worth and Atlanta maintain their positions as the two largest connecting complexes by passenger volume.
Germany
CSRD reporting requirements extend to scope-three travel emissions, redirecting corporate procurement toward carriers with verified CORSIA participation. The EU Green Deal's ReFuelEU Aviation mandate progressively raises sustainable aviation fuel blending obligations. Frankfurt and Munich serve as the primary hubs for transatlantic and intra-European connectivity.
India
Airports Authority of India is expanding runway capacity at Delhi and Mumbai while IndiGo and Air India place record narrow-body orders. PLI scheme incentives support domestic manufacturing of aircraft components and MRO capabilities. Bangalore and Hyderabad emerge as secondary hubs with technology-sector business travel concentration.
United Arab Emirates
Dubai's geographic position between Europe and Asia enables sixth-freedom traffic capture that bypasses traditional European gateways. MOHAP and GCAA oversee aviation safety frameworks alongside international ICAO standards. Emirates operates an all-wide-body fleet strategy centered on Dubai International Airport's connecting complex.
Saudi Arabia
Saudia and Riyadh Air are building Jeddah and Riyadh into competing hubs with government-backed infrastructure spending and visa liberalization. SFDA regulates air cargo standards for pharmaceutical cold chain services. NEOM Northwest is developing a greenfield airport designed for sustainable aviation fuel integration from inception.
Global Airlines Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue point-to-point network architectures and sustainable aviation fuel differentiation. The market structures around a duopoly of Boeing and Airbus for aircraft supply, while airline operators fragment across full-service, low-cost, and hybrid business models. Three archetypes dominate: network carriers with joint venture immunization, Gulf-based sixth-freedom operators, and ultra-low-cost specialists with fleet commonality. Competitive moves center on strategic partnerships for route authority and fleet renewal timelines compressed by decarbonization mandates.
Among Europe-based network carriers, Lufthansa Group and International Airlines Group exemplify the joint venture archetype sustaining transatlantic density through immunized alliances. Air France–KLM occupies a similar position with coordinated scheduling across Paris and Amsterdam hubs. Emirates anchors the sixth-freedom model through Dubai's geographic arbitrage between Europe and Asia.
| Leading Market Players |
|---|
| Lufthansa Group |
| International Airlines Group |
| Delta Air Lines |
| Air China |
| China Southern Airlines |
| United Airlines |
| Air France–KLM |
| Emirates |
| American Airlines Group |
| Others |
Supply Flow & Price Mechanics
ReFuelEU Aviation's progressive blending mandates are forcing procurement teams into multi-year offtake negotiations that compress operating margins and transfer commodity risk to carriers lacking hedging sophistication. This regulatory pressure reshapes how airlines contract fuel supply and what cost structures they can sustain.
Pricing Analysis
Power-by-the-hour contracts bundle engine maintenance with flight-hour guarantees, unbundling traditional capital expenditure into operational line items. Pricing stratifies across premium full-service, hybrid network, and ultra-low-cost tiers based on loyalty program density and corporate contract penetration. Cost compression in the ultra-low-cost tier is intensifying as IndiGo and Air India fleet expansion saturates South Asian point-to-point markets. Corporate travel managers in Germany and the Netherlands demonstrate lowest price sensitivity, prioritizing CORSIA participation status over fare minimization.
Supply Chain Analysis
Regional distribution centers at Singapore and Rotterdam anchor jet fuel supply security for Europe-Asia corridors, with pipeline and barge networks feeding airport hydrant systems. Manufacturing concentration rests on Boeing and Airbus final assembly in the United States, France, and Germany, with engine production clustered at GE Aerospace and Pratt & Whitney facilities in Ohio and Connecticut. Single-source vulnerability runs through titanium sponge supply from Russia and China for airframe structures. Distribution runs through OEM direct delivery with airline customization at completion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance costs function as a barrier-to-entry moat, advantaging carriers with balance sheet capacity to absorb SAF procurement premiums and fleet renewal acceleration.
For Market Incumbents: Lock in long-term SAF offtake agreements before European blending mandates tighten supply availability. Consolidate maintenance capabilities through power-by-the-hour contract renegotiation to offset mechanic wage inflation at US and European bases. Low-cost specialist entrants from India threaten yield on short-haul trunk routes. For New Entrants and Emerging Players: Capture pharmaceutical cold chain cargo yields on trans-Pacific corridors where temperature-controlled infrastructure commands premium pricing. Point-to-point transatlantic routes with single-aisle aircraft represent the most penetrable segment. Lead with sustainability credentials to displace legacy carriers in corporate travel RFP processes. For Investors and Strategic Acquirers: The window for entry favors carriers with verified CORSIA participation and established SAF procurement relationships. Long-term viability hinges on fleet decarbonization pathway credibility rather than network scale alone. Watch for ICAO CORSIA phase-in acceleration as the inflection indicator for compliance cost repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Offtake Agreement | ReFuelEU Aviation mandates progressively raise blending obligations, creating guaranteed demand for compliant carriers. |
| Power-by-the-Hour Contract Restructuring | GE Aerospace and Pratt & Whitney transfer balance sheet risk while locking long-term supplier relationships. |
| Pharmaceutical Cold Chain Certification | SFDA and MOHAP standards enable premium cargo yields on biologics routes through Singapore and Dubai. |
| Single-Aisle Transatlantic Route Launch | LEAP-1A and PW1100G engine architectures open point-to-point missions previously requiring twin-aisle equipment. |
| Corporate Travel Sustainability Partnership | CSRD reporting requirements in Germany and the Netherlands redirect procurement toward CORSIA-participating carriers. |
Methodological Framework
Document review covered ICAO regulatory filings, EASA certification databases, airline SEC 10-K disclosures, and IATA operational statistics, complemented by interviews with fleet planning executives, fuel procurement directors, MRO operations managers, and corporate travel managers. Secondary validation drew from FAA airworthiness directives, EU Green Deal implementation texts, and airport authority capacity reports. Bottom-up route-level demand modeling triangulated against top-down macroeconomic projections.
Revenue and capacity outputs reflect integrated segmentation across service type, aircraft type, booking channel, and travel class dimensions, with geographic splits at country level. CAGRs were derived from trend extrapolation moderated by regulatory phase-in schedules and fleet delivery backlogs. Forecast inputs incorporated jet fuel price scenarios, pilot training pipeline constraints, and SAF production capacity buildout timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CORSIA enforcement stringency and OEM delivery reliability. Outputs reflect documented assumptions around regulatory implementation pace and alternative fuel cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
North America Charter Jet Services Market
Aviation and Defense Training and Simulation
Digital Aviation Market
Aviation and Defense Training and Simulation
Domestic Aviation Market
Aviation and Defense Training and Simulation
Helicopter Services Market
Aviation and Defense Training and Simulation
US Helicopter Services Market
Aviation and Defense Training and Simulation
Middle-East and Africa Jet Charter Services Market
Aviation and Defense Training and Simulation
South-East Asia Civil Aviation Market
Aviation and Defense Training and Simulation
Charter Jet Services Market