
 North America Charter Jet Services Market | 2026-2036
North America Charter Jet Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Charter Jet Services Market Analytics
Pilot shortages across the United States and Canada is reorganizing fleet utilization schedules and pricing power for regional operators. NetJets leverages its fractional ownership scale to secure long-term crew contracts and retain cockpit talent. Flexjet competes through manufacturer-backed training pipelines that reduce pilot churn. Wheels Up anchors its position via a membership model that pools demand across underutilized aircraft, offsetting labor scarcity through asset efficiency.
Charter jet services encompass the commercial provision of on-demand aircraft access without scheduled airline obligations, typically operating under FAA Part 135 or equivalent Transport Canada regulations with aircraft ranging from light turboprops to heavy intercontinental jets capable of nonstop transoceanic range. These services deliver point-to-point mobility for time-sensitive executives, medical evacuations, and discretionary leisure travelers who prioritize schedule control over commercial aviation constraints. Fractional ownership and jet card programs now capture the most durable revenue streams, as clients lock in predictable hourly rates and guaranteed availability during peak periods. On-demand charter retains higher per-flight margins but faces sharper volume volatility tied to corporate discretionary spending cycles. Light jets and midsize jets dominate aircraft utilization hours, though heavy jets command premium positioning for coast-to-coast and international missions.
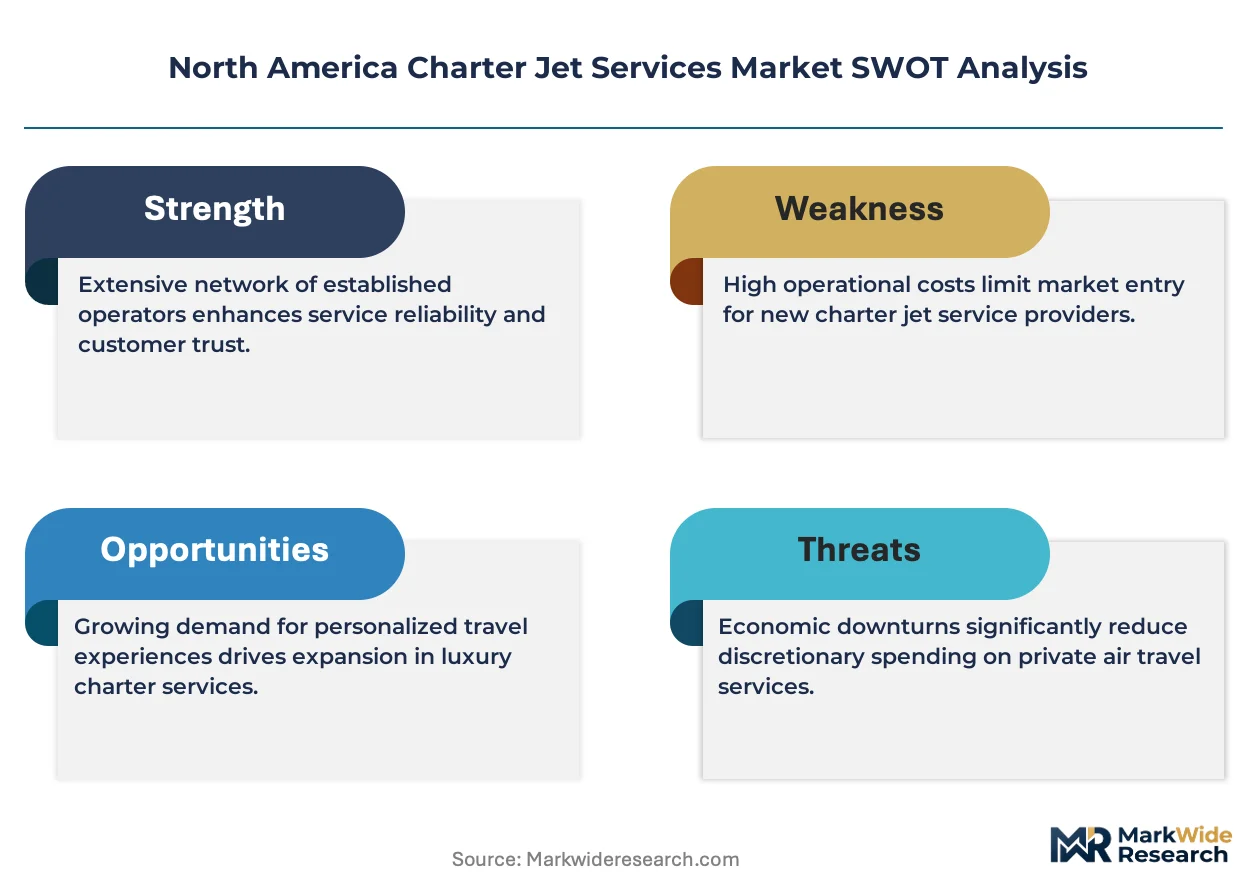
FAA Part 135 certification, Transport Canada CARs Subpart 704, and DOT consumer protection rules collectively shape operator economics, crew rest mandates, and maintenance intervals that directly constrain fleet deployment capacity. The Transportation Security Administration's Twelve-Five Standard Security Program imposes additional screening protocols for aircraft exceeding passenger thresholds, filtering which operators can serve government and high-security corporate contracts. Stakeholders must weigh crew retention investments against digital booking platform expansion as the twin determinants of sustainable market share.
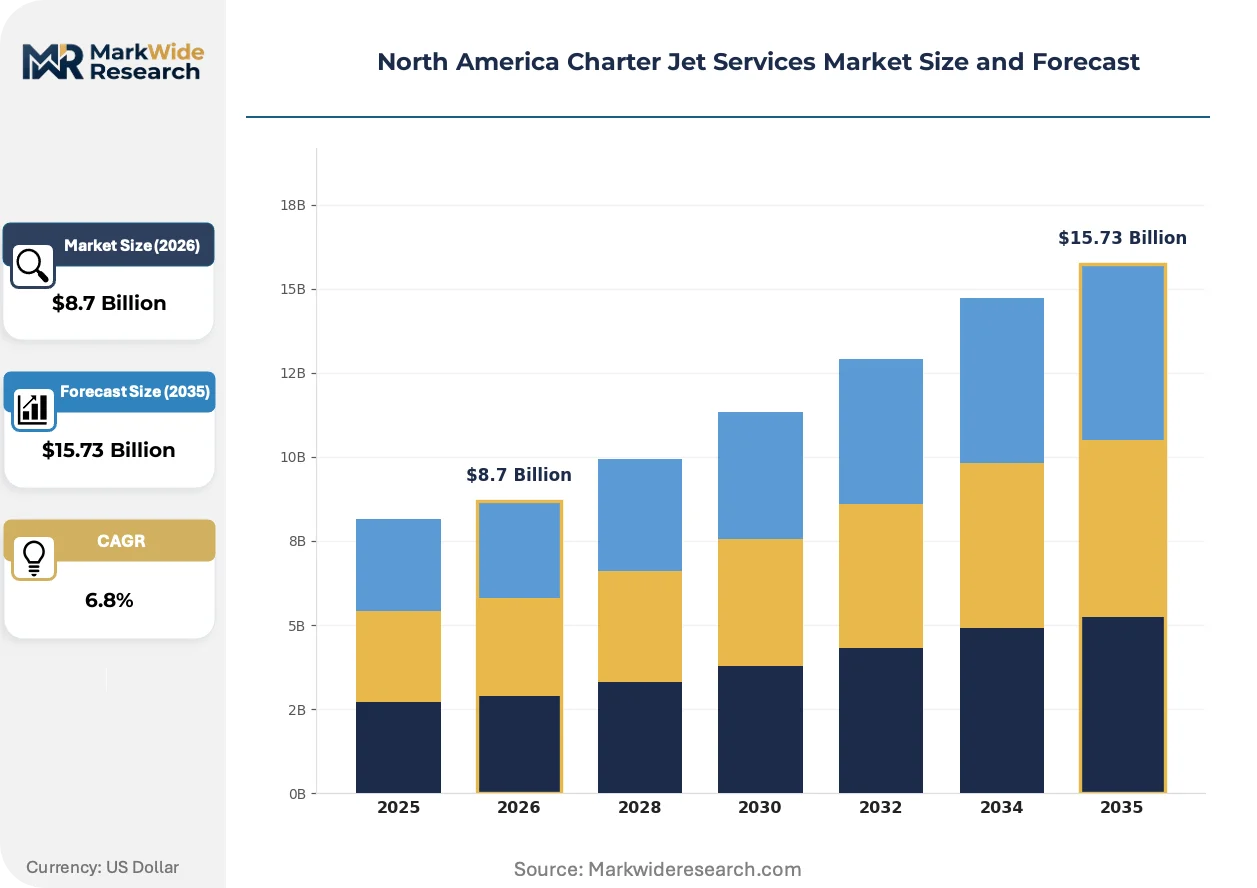
Market Dynamics
Pilot scarcity across the United States and Canada is compressing fleet utilization rates and elevating crew retention costs for regional operators, fundamentally restructuring how charter capacity gets priced and deployed.
Growth Catalysts
- FAA Part 135 Certification:Regulatory clarity around on-demand operations enables fractional ownership models to expand fleet access without full aircraft ownership burdens, attracting corporate travel managers seeking workforce mobility solutions.
- Energy Sector Concentration:Texas-based oil and gas executives sustain route density between Houston, Midland, and Denver, generating consistent utilization that subsidizes network coverage for discretionary travelers.
- Telemedicine Integration:Medical evacuation operators now embed remote patient monitoring capabilities, expanding addressable missions beyond traditional emergency response into scheduled critical care transport.
Market Restraints
- Aviation Fuel Volatility:Jet-A price swings directly pass through to hourly charter rates, eroding pricing predictability that jet card programs promise and compressing operator margins during spike periods.
- Airframe Supply Concentration:Bombardier, Gulfstream, and Textron Aviation control over 80 percent of midsize and heavy jet production, creating delivery backlogs that constrain fleet expansion timelines for charter operators.
- Airspace Congestion:FAA slot restrictions at Teterboro, Van Nuys, and Palm Beach limit peak-period departures, capping revenue potential during highest-demand windows.
Strategic Opportunities
- Canadian Arctic Routes:Resource extraction camps and remote indigenous communities lack scheduled service, creating white-space demand for turboprop operators with Transport Canada CARs Subpart 704 certification.
- Sustainable Aviation Fuel Mandates:California's Low Carbon Fuel Standard and proposed federal SAF tax credits create procurement advantages for early-adopting fleets serving ESG-mandated corporate clients.
- Empty-Leg Marketplaces:Digital platforms aggregating repositioning flights are compressing search friction and capturing price-sensitive leisure demand that previously exited the market.
Industry Challenges
- ATP Certification Pipeline:The FAA's Airline Transport Pilot hour requirements and medical clearance backlogs extend crew onboarding timelines to 18-24 months, constraining fleet expansion velocity.
- Maintenance Technician Scarcity:A&P mechanic retirement waves outpace vocational program output, forcing operators to outsource heavy checks and surrender margin to MRO providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Charter Jet Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand, Empty Leg, Fractional Ownership, Jet Card Client Type: Corporate, Leisure, Government, Medical Aircraft Type: Light Jets, Midsize Jets, Heavy Jets, Turboprops Booking Channel: Online Platforms, Travel Agencies, Direct Sales, Brokers |
| Companies Covered | NetJets, Flexjet, Wheels Up, FlyExclusive, Vista Global, Jet Linx, Air Charter Service, Executive Jet Management, Gama Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Charter Jet Services Market Evolving Landscape
Digital booking infrastructure and sustainable propulsion alternatives are restructuring how charter demand gets discovered, priced, and fulfilled across North American airspace.
Artificial intelligence-driven flight matching algorithms are displacing traditional broker networks by instantly pairing empty-leg capacity with origin-destination searches. Leisure travelers and small corporate flight departments now bypass human intermediaries for transparent, bookable pricing. This compression of search friction is reallocating margin from brokers to operators while expanding total addressable demand.
The FAA's ongoing NextGen airspace modernization and proposed sustainable aviation fuel tracking mandates are reshaping operational compliance burdens. Operators investing in ADS-B equipage and emissions documentation systems gain preferential slot access at congested airports. Charter fleets serving government and Fortune 500 contracts face accelerated retrofit timelines to maintain contract eligibility.
Corporate procurement departments now unbundle aircraft access from crew and management services, treating charter as a commoditized spend category subject to competitive bidding platforms. This disintermediation pressures traditional jet card programs to demonstrate hourly rate advantages against on-demand alternatives. The shift is most pronounced among technology sector clients with centralized travel management offices in Austin and Seattle.
North America Charter Jet Services Market Segmentation
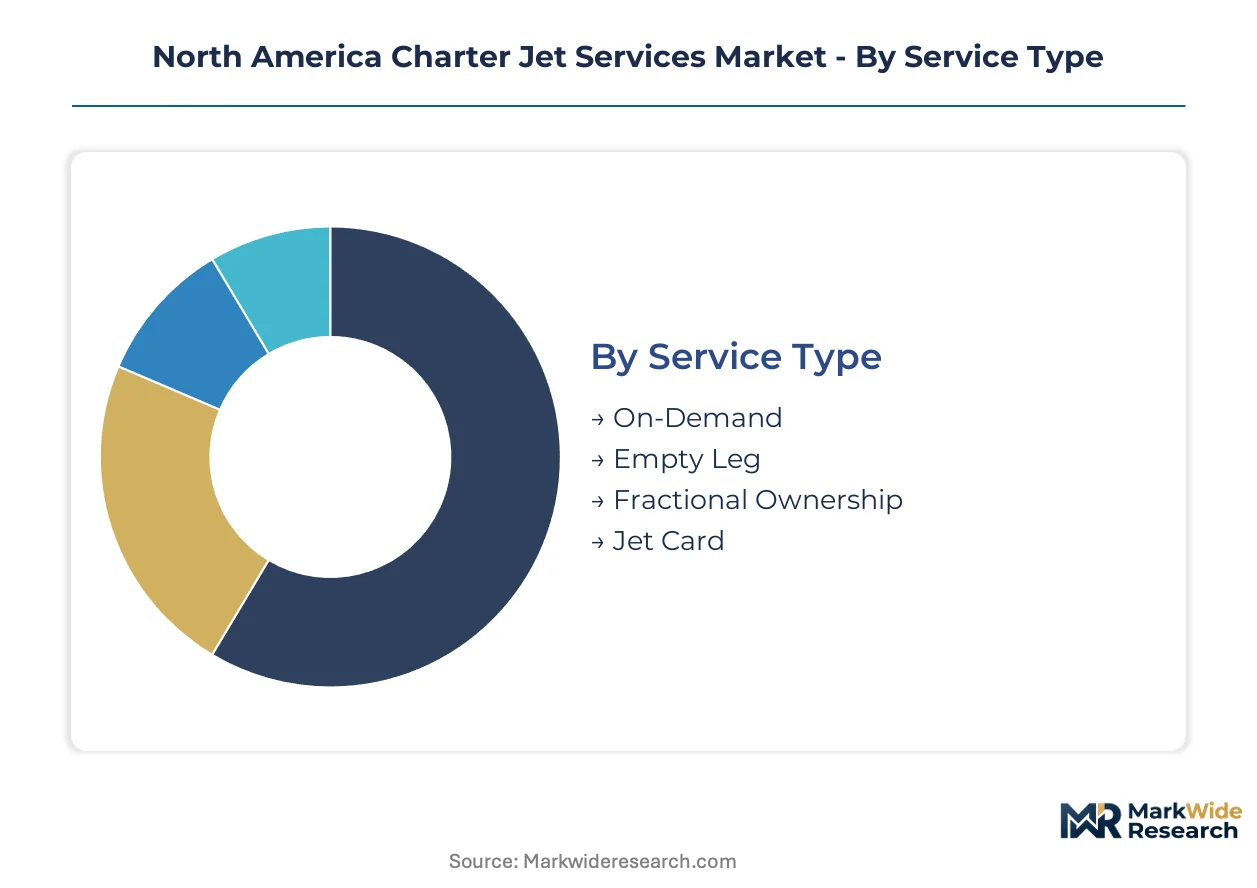
Segmentation in the North America Charter Jet Services Market reveals how distinct client behaviors and operational models create parallel revenue streams. Service configuration, aircraft selection, and booking pathways each determine margin structure and competitive positioning for operators across the United States and Canada.
Service Type:
Channel mix varies sharply across service models, with fractional ownership and jet card programs flowing through dedicated sales teams while on-demand and empty-leg volume migrates toward digital platforms.
- On-Demand:Ad-hoc flight procurement with aircraft and crew assigned per mission. Texas energy corridors and Florida seasonal leisure routes sustain the highest utilization density for this volatile revenue stream.
- Empty Leg:Repositioning flights offered at discounted rates through aggregator platforms. Digital marketplaces now capture price-sensitive demand that previously abandoned private aviation entirely.
- Fractional Ownership:Shared aircraft equity with guaranteed hourly access. Corporate travel managers in Houston and Denver favor this model for predictable workforce mobility budgeting.
- Jet Card:Prepaid hourly blocks with fixed rates and peak-period guarantees. ESG-mandated corporate clients in California increasingly specify sustainable aviation fuel inclusion in card terms.
Fractional ownership dominates installed base. Empty-leg digitalization is where expansion concentrates.
Client Type:
Cost tier stratification separates these segments, with government and medical missions commanding rate premiums while corporate and leisure volumes compete on efficiency.
- Corporate:Flight departments and travel managers procuring workforce mobility. Technology sector consolidation in Austin and Seattle is driving centralized competitive bidding for charter spend.
- Leisure:Discretionary travelers prioritizing schedule control over commercial constraints. Aspen, Palm Beach, and Nantucket seasonality creates extreme peak-valley utilization patterns.
- Government:Federal, state, and municipal contracts requiring TSA Twelve-Five security compliance. FAA Part 135 certification with enhanced screening protocols filters eligible operators.
- Medical:Patient transport and organ procurement missions. Telemedicine integration is expanding addressable missions beyond emergency response into scheduled critical care.
Corporate clients anchor revenue stability. Medical evacuation is climbing the fastest.
Aircraft Type:
Volume concentration sits with light and midsize platforms, while heavy jets and turboprops occupy specialized mission profiles at opposite ends of the range spectrum.
- Light Jets:Aircraft under 20,000 lbs MTOW with 1,500-2,000 nm range. Fractional programs deploy Citation CJ and Phenom 300 fleets most intensively for regional corporate missions.
- Midsize Jets:Transcontinental capability with stand-up cabins. Gulfstream G280 and Challenger 350 backlogs constrain fleet expansion timelines for charter operators.
- Heavy Jets:Intercontinental range for coast-to-coast and international missions. Bombardier Global and Gulfstream G650 command premium positioning in this thin-volume segment.
- Turboprops:Short-field performance for remote access. Canadian Arctic resource camps and indigenous communities create white-space demand for Transport Canada CARs Subpart 704 operators.
Light jets dominate flight hours. Heavy jets concentrate margin expansion.
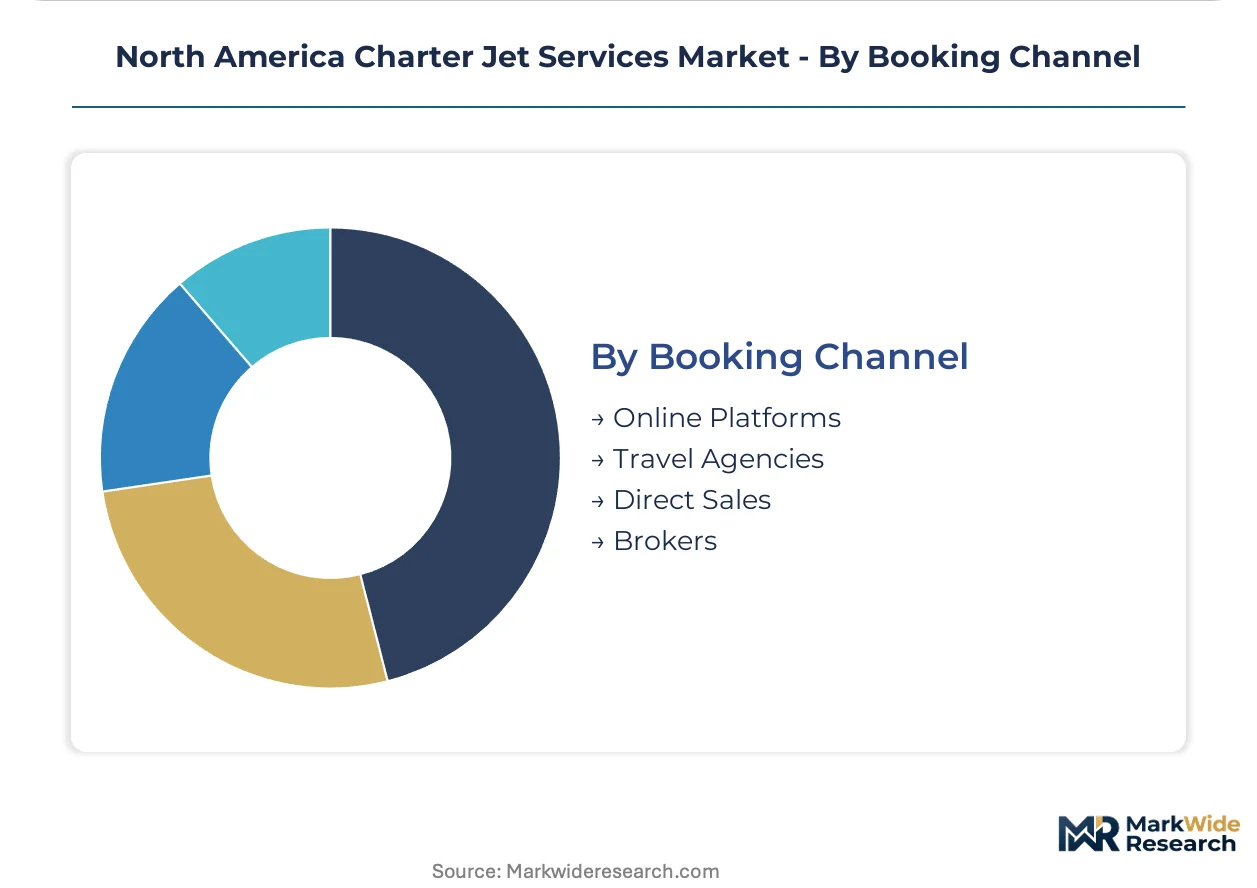
Booking Channel:
Customer type and maturity determine channel selection, with established flight departments favoring direct relationships while new entrants default to platform-mediated discovery.
- Online Platforms:AI-driven matching algorithms displacing traditional broker networks. Leisure travelers and small flight departments now bypass human intermediaries for transparent pricing.
- Travel Agencies:Corporate travel management companies bundling charter with commercial aviation procurement. Consolidated spend categories subject competitive pressure on jet card programs.
- Direct Sales:Operator-owned account teams for fractional and jet card acquisition. NetJets and Flexjet maintain captive sales forces to secure long-term crew contracts through scale.
- Brokers:Independent intermediaries sourcing capacity across operator networks. Margin compression from digital platforms is reallocating broker share to operators and aggregators.
Direct sales govern high-value retention. Online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 135 certification requirements anchor the regulatory framework across the dominant United States market, while Transport Canada CARs Subpart 704 governs cross-border operations. Regional demand concentrates in energy corridors and leisure destinations where route density sustains fleet utilization.
United States
Texas energy executives and Florida seasonal travelers sustain the highest charter utilization density nationwide. FAA Part 135 certification mandates crew rest protocols and maintenance intervals that constrain fleet deployment capacity during peak periods. Houston, Midland, and Denver form the core energy-sector triangle generating consistent mission volume.
Canada
Remote resource extraction camps and indigenous communities in the Arctic territories generate white-space demand for turboprop operators. Transport Canada CARs Subpart 704 certification requirements filter eligible providers for these specialized missions. Alberta oil sands operations and northern Quebec mining clusters anchor year-round contract revenue.
Mexico
Cross-border corporate shuttle demand connects Monterrey and Mexico City manufacturing hubs with Texas operations. Mexico's DGAC operational specifications for charter services create compliance layering for US-registered aircraft. Baja California leisure corridors and Cancun vacation routes concentrate discretionary traveler volume seasonally.
North America Charter Jet Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America Charter Jet Services Market. Fractional ownership providers with captive sales forces and long-term crew contracts occupy the upper tier, while on-demand brokers and digital platform operators fill the specialist layer below. Three archetypes dominate: scale-driven fractional programs, membership-based demand aggregators, and manufacturer-aligned fleet operators. Competitive moves center on pilot retention investments and digital booking infrastructure expansion.
Within the integrated leader tier, NetJets and Flexjet exemplify scale-driven fractional ownership models that secure workforce stability through size. Wheels Up occupies a position as the membership-based aggregator archetype, pooling demand across underutilized assets. These three entities anchor the competitive structure by representing divergent paths to addressing pilot scarcity and asset efficiency.
| Leading Market Players |
|---|
| NetJets |
| Flexjet |
| Wheels Up |
| FlyExclusive |
| Vista Global |
| Jet Linx |
| Air Charter Service |
| Executive Jet Management |
| Gama Aviation |
| Others |
Value Network & Pricing Analysis
Twenty-four-month delivery backlogs for Bombardier Global and Gulfstream G650 airframes concentrate pricing power with manufacturers while compressing operator fleet expansion timelines. This inventory scarcity across the United States and Canada feeds directly into hourly charter rate premiums, as fractional ownership programs and on-demand operators compete for limited aircraft slots. FAA Part 135 certification requirements add compliance cost layers that operators pass through to corporate travel managers and leisure clients.
Pricing Analysis
Hourly rate spreads between Houston energy corridors and Florida seasonal leisure routes reflect utilization density differentials rather than service tiering. Three-tier pricing structure across premium heavy-jet, standard midsize, and economy light-jet levels segments buyer budgets, with jet card programs locking in fixed rates against on-demand volatility. Pricing pressure stems from pilot scarcity elevating crew retention costs, with ATP certification pipelines constraining supply-side response. Corporate flight departments in Austin and Seattle demonstrate highest price sensitivity through competitive bidding platforms, while energy sector executives in Texas accept rate premiums for guaranteed availability.
Supply Chain Analysis
Inventory scarcity for midsize and heavy jet airframes stretches lead times to twenty-four months, anchoring fleet expansion timelines for charter operators. Manufacturing concentrates in Canada, the United States, and France, with Bombardier, Gulfstream, and Textron Aviation controlling production capacity. Raw material dependencies span aerospace-grade aluminum, titanium forgings, and avionics systems from specialized Tier 2 suppliers. Single-source vulnerability for engine platforms from Pratt & Whitney and Rolls-Royce creates fleet grounding risk. Distribution runs through manufacturer-direct sales teams and fractional program fleet managers rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed flight crew availability constrains fleet deployment velocity across North American airspace, making pilot retention infrastructure the decisive capability gap separating sustainable operators from capacity-constrained competitors. This scarcity dynamic rewards stakeholders who secure workforce stability before competitors exhaust the shallow talent pool.
For Market Incumbents: Secure long-term crew contracts through scale advantages that NetJets and Flexjet have already demonstrated, insulating against ATP certification pipeline bottlenecks. Invest in manufacturer-backed training pipelines to reduce pilot churn and accelerate onboarding timelines. Defend against digital platform disintermediation by embedding direct sales relationships with corporate travel managers in Houston and Denver. For New Entrants and Emerging Players: Anchor in Canadian Arctic turboprop corridors where Transport Canada CARs Subpart 704 certification filters competition for resource extraction camp contracts. Target empty-leg marketplace aggregation as the most penetrable segment, capturing price-sensitive leisure demand through AI-driven flight matching algorithms. Pursue go-to-market partnerships with telemedicine platforms to expand medical evacuation missions beyond emergency response. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy fractional ownership programs seeking capital for fleet modernization and sustainable aviation fuel retrofit compliance. Long-term viability hinges on operators with installed base scale sufficient to amortize crew retention investments across utilization hours. Monitor FAA NextGen airspace modernization timelines as the critical inflection signal for ADS-B equipage compliance costs and preferential slot access advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Pilot Retention Infrastructure | Long-term crew contracts secure workforce stability against ATP certification bottlenecks. |
| Sustainable Aviation Fuel Procurement | Early SAF adoption gains preferential access to California ESG-mandated corporate contracts. |
| Digital Booking Platform Expansion | AI-driven empty-leg matching captures price-sensitive demand from traditional broker networks. |
| Canadian Arctic Route Certification | Transport Canada CARs Subpart 704 qualification opens white-space turboprop missions. |
| Telemedicine Integration | Remote patient monitoring expands medical evacuation into scheduled critical care transport. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA certification databases, Transport Canada operational records, and operator fleet registries. Interviews with fractional ownership program directors, Part 135 operator chief pilots, corporate travel managers, and aviation MRO procurement leads inform demand-side and supply-side dynamics. Secondary validation draws from DOT consumer protection filings, TSA security program registrations, and customs aircraft import data. Bottom-up triangulation across service type, aircraft category, and booking channel segmentation layers against top-down market sizing from fleet utilization and hourly rate benchmarks.
Segmentation dimensions modeled span service configuration, aircraft type, client category, and booking channel across the analysis window. The analytical framework projects fleet expansion velocity constrained by pilot certification pipelines and airframe delivery backlogs. CAGRs derive from utilization hour growth trajectories and hourly rate escalation patterns. Industry-specific forecast inputs include ATP certification completion rates, sustainable aviation fuel mandate adoption curves, and NextGen airspace equipage compliance timelines.
Material uncertainties — aviation fuel price volatility, regulatory crew rest mandate revisions, and airspace congestion policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions about pilot supply recovery and manufacturer production capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
Charter Jet Services Market
Aviation and Defense Training and Simulation
Digital Aviation Market
Aviation and Defense Training and Simulation
US Helicopter Services Market
Aviation and Defense Training and Simulation
South-East Asia Civil Aviation Market
Aviation and Defense Training and Simulation
Domestic Aviation Market
Aviation and Defense Training and Simulation
Global Airlines Market
Aviation and Defense Training and Simulation
Middle-East and Africa Jet Charter Services Market
Aviation and Defense Training and Simulation
Helicopter Services Market