
 Charter Jet Services Market | 2026-2036
Charter Jet Services Market Size, Share, and Industry Trends Forecast 2026-2036
Charter Jet Services Market Analysis
Subscription-style membership programs is hardening into the dominant commercial layer of charter jet services, converting sporadic flyers into recurring revenue streams with guaranteed hourly rates and fixed monthly fees. NetJets leverages its fractional ownership pedigree to anchor the membership segment with guaranteed aircraft availability and depreciation-sharing structures. VistaJet differentiates through a globally uniform fleet of super-midsize and large-cabin jets, eliminating positioning costs for transcontinental clients. Flexjet sustains competitive intensity by combining fractional shares with lease-like flexibility, appealing to corporate flight departments seeking capital-light alternatives to whole-aircraft ownership.
Charter jet services encompass the commercial arrangement of aircraft and crew for non-scheduled passenger or cargo transport, typically operated under Part 135 or equivalent regulatory frameworks with aircraft ranging from light jets below 10,000 pounds maximum takeoff weight to long-range large-cabin platforms exceeding 6,000 nautical miles. The primary industrial purpose centers on time arbitrage for executives, medical evacuations, and specialized logistics where airline schedules impose unacceptable delay costs. On-demand charter and membership programs capture the deepest margin pools as they command premium pricing for guaranteed availability and reduced deadhead exposure. Large jets and mid-size jets dominate the revenue base due to their transcontinental utility, though light jets retain structural importance in the United States for short-haul regional hops where runway length and operating economics favor smaller platforms.
FAA Part 135 certification, EASA Air Operations regulations, and ICAO carbon offset mechanisms collectively shape fleet modernization timelines, pilot duty limits, and emissions disclosure obligations across operating jurisdictions. Compliance investments in Safety Management Systems and continuous monitoring technology are becoming baseline requirements for market access rather than competitive differentiators. Stakeholders must monitor how sustainable aviation fuel mandates and noise-abatement curfews at capacity-constrained airports reshape network economics and aircraft retirement schedules.
Market Dynamics
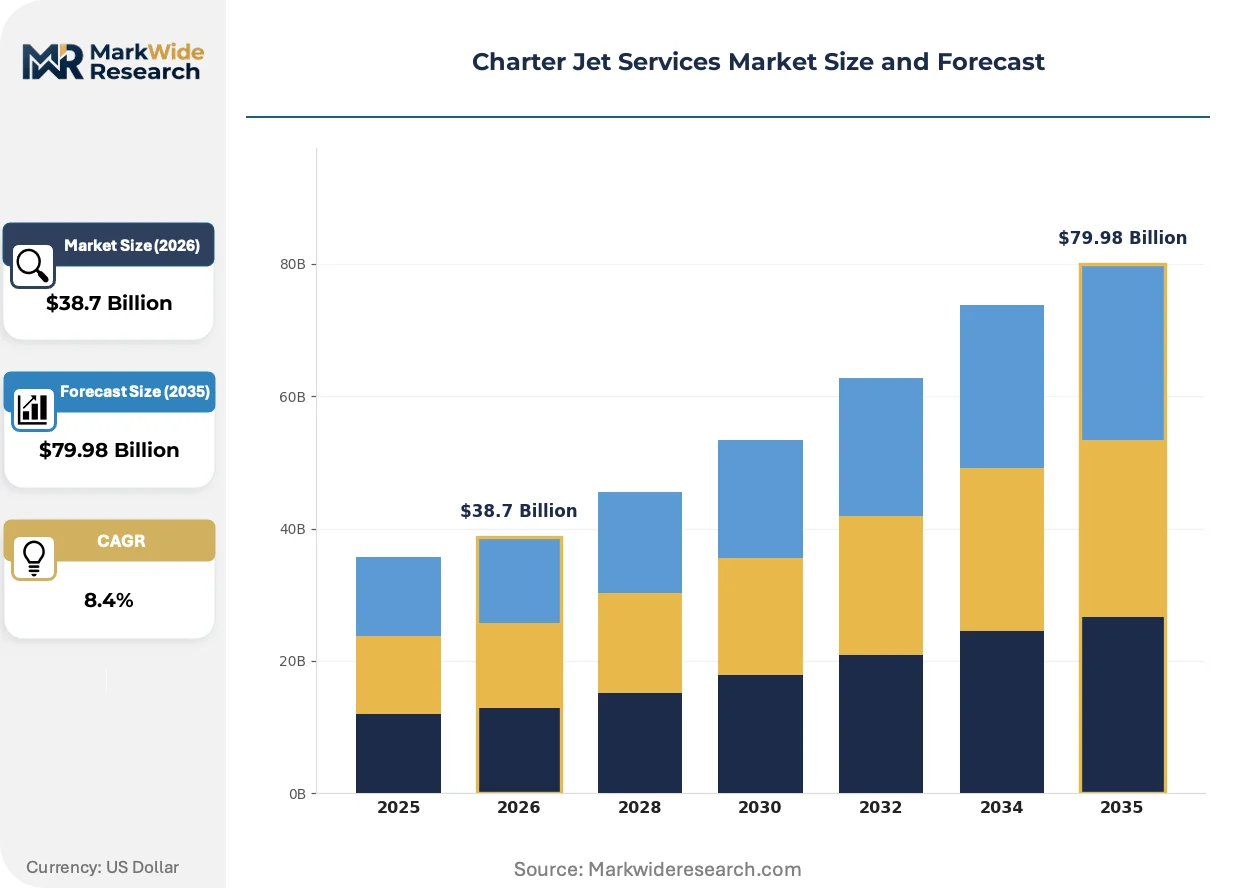
Subscription-style membership programs is hardening into the dominant commercial layer, converting sporadic flyers into recurring revenue streams with guaranteed hourly rates and fixed monthly fees that reshape fleet utilization economics.
Growth Catalysts
- Ultra-high-net-worth individual concentration:Wealth density in the United States, the United Arab Emirates, and the United Kingdom generates sustained demand for on-demand and fractional arrangements that absorb excess fleet capacity.
- EASA Air Operations regulations:Evolving European standards for Safety Management Systems and continuous monitoring technology drive fleet modernization investments that improve asset residual values and market access.
- Sustainable aviation fuel mandates:ICAO carbon offset mechanisms and national blending requirements in multiple jurisdictions create procurement premiums for operators with early SAF integration capabilities.
Market Restraints
- Pilot supply constraints:FAA Part 135 certification requirements and duty limit regulations compress available flight crew hours, restricting fleet expansion velocity regardless of aircraft availability.
- Jet fuel price volatility:Unhedged fuel exposure represents 25-35% of operating costs for most charter operators, compressing margins during supply shocks without contractual pass-through mechanisms.
- Airport slot scarcity:Noise-abatement curfews at capacity-constrained airports like Teterboro and Van Nuys limit peak-hour departure capacity, constraining revenue per aircraft day.
Strategic Opportunities
- Medical evacuation specialization:Underpenetrated air ambulance segments in secondary US metropolitan areas offer premium rate structures with government reimbursement stability.
- Intermodal cargo integration:Time-critical logistics clients seek seamless handoffs between charter aircraft and ground transport, creating stickiness through proprietary booking platforms.
- EU Green Deal compliance services:Emissions disclosure obligations and carbon accounting requirements generate advisory revenue streams for operators with verified SAF supply chains and monitoring infrastructure.
Industry Challenges
- Maintenance technician scarcity:Specialized airframe and powerplant certification timelines extend to 24-36 months, delaying fleet expansion and increasing labor arbitrage costs.
- Legacy reservation system integration:Proprietary scheduling platforms resist API connectivity with corporate travel management systems, fragmenting booking workflows and increasing customer acquisition friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charter Jet Services Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand, Membership, Private, Charter Shuttle Aircraft Type: Light Jets, Mid-Size Jets, Large Jets, Turbo Props End User: Corporate, Leisure, Government, Sports Teams Booking Channel: Online Platforms, Brokers, Direct, Travel Agencies |
| Companies Covered | NetJets, VistaJet, Flexjet, Wheels Up, Jet Linx Aviation, Air Charter Service, Magellan Jets, Solairus Aviation, Chapman Freeborn Airchartering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charter Jet Services Market Emerging Trajectories
Digital booking platforms and predictive analytics is actively compressing the gap between aircraft availability and customer demand, reshaping how operators manage empty-leg exposure and dynamic pricing.
Blockchain-verified maintenance records is decentralizing trust in aircraft airworthiness documentation. Fractional ownership programs and charter brokers adopt distributed ledger systems to accelerate pre-flight due diligence. This compression of verification timelines is decentralizing transaction authority from centralized registries to peer-validated networks, reducing intermediary friction in secondary aircraft markets.
The EU Green Deal's sustainable aviation fuel blending mandates is forcing fleet operators to restructure fuel procurement contracts around certified supply chains. Industrial consequence includes multi-year offtake agreements with biorefinery developers that lock in premium pricing against conventional jet fuel. Large-cabin and super-midsize operators with transcontinental routes face the steepest compliance cost gradients, responding through membership program restructuring that internalizes fuel surcharges into fixed monthly fees.
Corporate flight departments is consolidating vendor relationships around integrated membership programs that bundle guaranteed availability with depreciation-sharing structures. Traditional on-demand charter brokers lose share to subscription models that eliminate per-trip negotiation friction. This consolidation is most visible in the United States, where Fortune 500 procurement teams prioritize capital-light alternatives to whole-aircraft ownership with predictable budgeting frameworks.
Charter Jet Services Market Segmentation
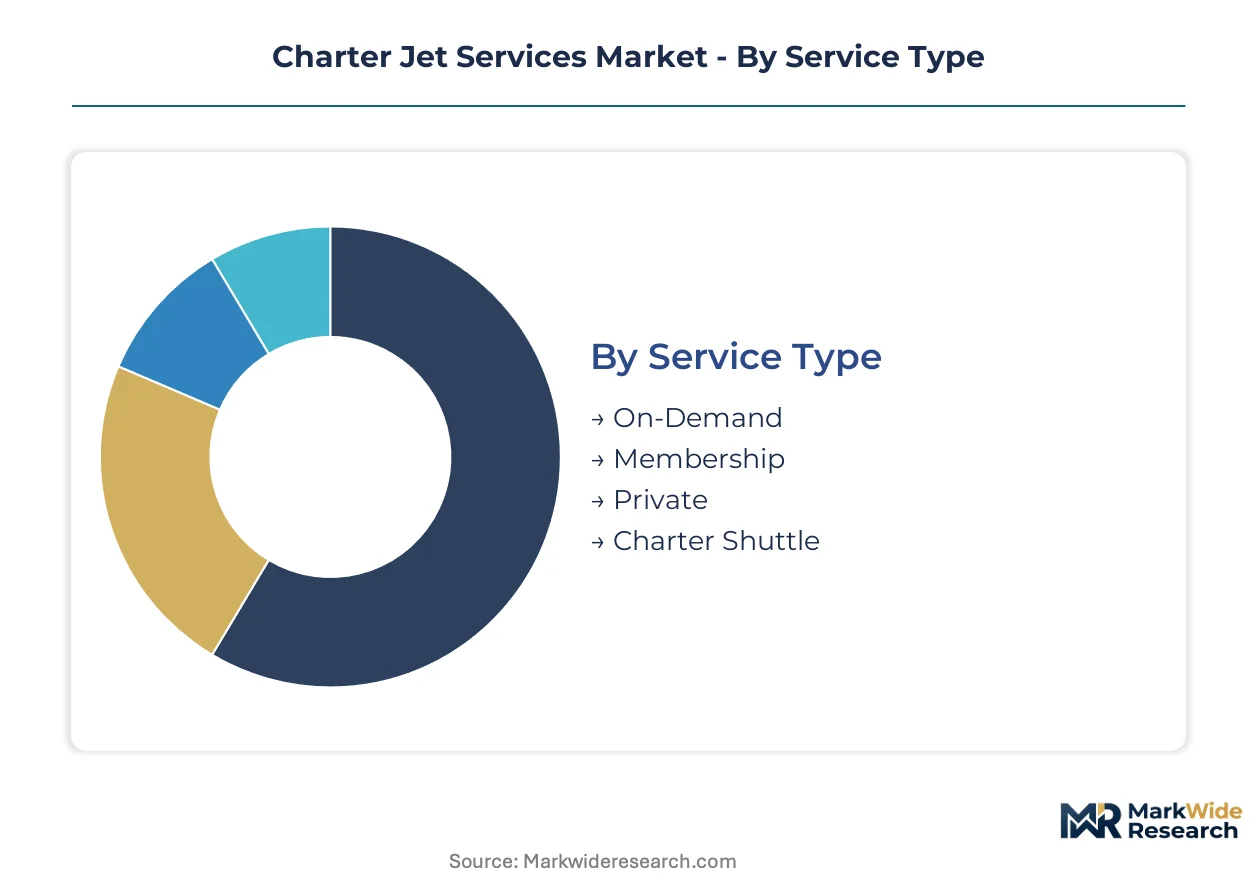
Segmentation in charter jet services determines fleet configuration, pricing architecture, and regulatory compliance pathways. Each dimension shapes how operators deploy capital and capture margin across distinct customer workflows.
Service Type:
Supply concentration in membership programs is restructuring fleet utilization economics around recurring revenue rather than transactional charter.
- On-Demand:Ad-hoc charter arrangements with per-flight pricing and variable aircraft availability. Demand concentrates among Fortune 500 procurement teams seeking capital-light alternatives to fractional ownership for irregular travel patterns.
- Membership:Subscription models with fixed monthly fees and guaranteed hourly rates. NetJets anchors this segment through depreciation-sharing structures that convert sporadic flyers into predictable revenue streams.
- Private:Dedicated aircraft arrangements with exclusive crew assignment and full schedule control.
- Charter Shuttle:Scheduled point-to-point services on high-density routes with shared-occupancy pricing.
Membership absorbs the bulk of installed capacity; Charter Shuttle is expanding most quickly.
Aircraft Type:
Cost tier differentiation separates short-haul regional platforms from transcontinental assets with crew rest compartments and extended-range fuel systems.
- Light Jets:Aircraft below 10,000 pounds maximum takeoff weight with 1,500-2,000 nautical mile range. Demand concentrates in the United States for runway-constrained airports like Teterboro and Aspen where operating economics favor smaller platforms.
- Large Jets:Long-range platforms exceeding 6,000 nautical miles with stand-up cabins and lie-flat seating. VistaJet deploys a globally uniform fleet of these assets to eliminate positioning costs for intercontinental clients.
- Mid-Size Jets:Transcontinental aircraft with 3,000-4,000 nautical mile range and enclosed lavatories.
- Turbo Props:Turbine-powered propeller aircraft with short-field performance and lower hourly operating costs.
Large Jets command the steepest capital deployment; Light Jets are gaining share fastest in secondary US metropolitan markets.
End User:
Application-specific requirements drive aircraft selection, with medical evacuation and sports team logistics demanding specialized cabin configurations.
- Corporate:Executive travel with time-sensitive scheduling and in-flight productivity infrastructure. Demand concentrates among technology and financial services firms in the United States and United Kingdom seeking alternatives to airline network limitations.
- Leisure:Ultra-high-net-worth individual travel with destination flexibility and multi-leg itineraries. The United Arab Emirates generates sustained demand for super-midsize and large-cabin arrangements to European and Asian leisure destinations.
- Government:Official travel with security protocols and diplomatic clearance requirements.
- Sports Teams:Roster transport with equipment capacity and coordinated arrival logistics.
Corporate absorbs the bulk of flight hours; Leisure is climbing the fastest as wealth density expands in Gulf Cooperation Council states.
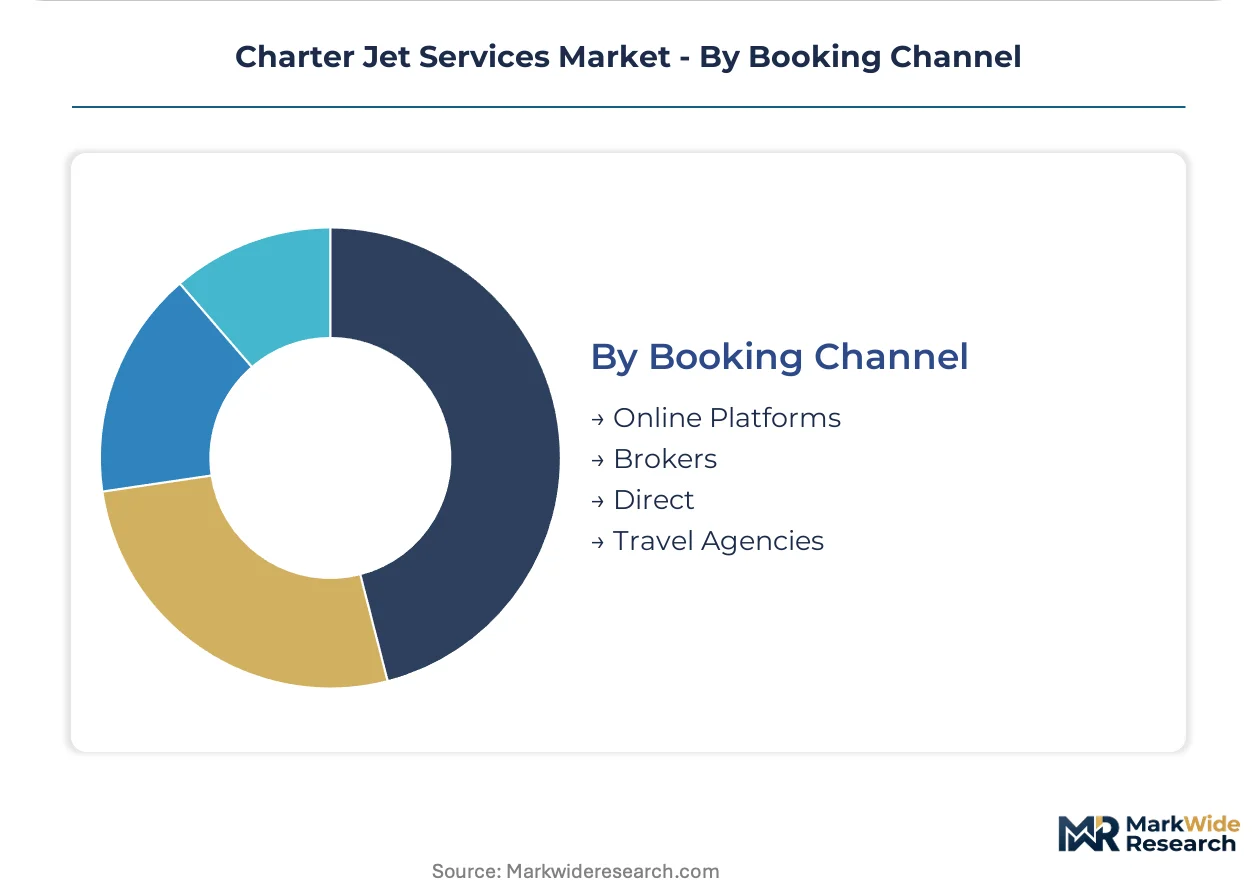
Booking Channel:
Customer type fragmentation between procurement departments and individual travelers is fragmenting reservation workflows across digital and intermediary pathways.
- Online Platforms:Direct digital booking with real-time aircraft availability and dynamic pricing. Flexjet and VistaJet invest in proprietary apps that compress the gap between demand signals and fleet dispatch.
- Brokers:Intermediary arrangements with market-wide aircraft sourcing and negotiation services. Traditional brokers lose share to integrated membership programs that eliminate per-trip friction.
- Direct:Operator-customer relationships with dedicated account management.
- Travel Agencies:Corporate travel management system integration with consolidated billing.
Online Platforms capture the bulk of new customer acquisition; Direct relationships are deepening most quickly among enterprise accounts with annual flight hour commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charter jet services concentrate where wealth density intersects with regulatory accommodation. The United States consumes the bulk of global flight hours while the United Arab Emirates and United Kingdom anchor transcontinental demand corridors.
United States
Ultra-high-net-worth individuals and corporate flight departments in New York, California, and Texas generate sustained demand for fractional and on-demand arrangements. FAA Part 135 certification requirements shape fleet compliance investments and pilot duty limits. Teterboro Airport in New Jersey and Van Nuys Airport in California remain critical infrastructure nodes where noise-abatement curfews constrain peak-hour capacity.
United Arab Emirates
Gulf Cooperation Council wealth expansion drives premium demand for super-midsize and large-cabin jets connecting Dubai and Abu Dhabi to European and Asian leisure destinations. The General Civil Aviation Authority maintains operational standards aligned with ICAO carbon offset mechanisms. Dubai South's aviation district hosts concentrated charter operator facilities serving transcontinental clientele.
United Kingdom
Financial services and technology firms in London sustain executive travel demand for time-sensitive scheduling alternatives to airline networks. EASA Air Operations regulations govern Safety Management Systems and continuous monitoring technology investments. Farnborough Airport anchors private aviation infrastructure with dedicated handling facilities for large-cabin aircraft.
Germany
Industrial conglomerates and mid-market enterprises in Bavaria and Baden-Württemberg utilize charter services for supply chain and client visit logistics. EU Green Deal sustainable aviation fuel mandates reshape fuel procurement contracts toward certified biorefinery supply chains. Munich Airport's private aviation terminal accommodates fractional ownership program bases serving Central European routes.
Switzerland
Private banking and pharmaceutical headquarters in Zurich and Geneva generate discrete travel demand with security and schedule flexibility requirements. Swissmedic-aligned operational standards complement EASA frameworks for cross-border medical evacuation services. Geneva Cointrin Airport's dedicated business aviation facilities handle significant transalpine charter volume.
Charter Jet Services Market Vendor Landscape
Capital-heavy fleet operators compete with asset-light membership platforms for customer relationships. The market exhibits tiered consolidation around fractional ownership incumbents, subscription-based challengers, and on-demand brokerage networks. Three strategic archetypes dominate: depreciation-sharing fractional providers, fixed-fee membership programs, and dynamic-pricing digital platforms. Competitive intensity manifests through fleet standardization investments and proprietary booking platform development rather than price-based rivalry.
Within the fractional ownership tier, NetJets anchors the segment with guaranteed aircraft availability structures. VistaJet occupies a position exemplifying globally uniform fleet deployment for transcontinental clientele. Flexjet represents the hybrid archetype combining fractional shares with lease-like flexibility for corporate flight departments. These three operators collectively illustrate how capital deployment scale and geographic coverage breadth determine competitive positioning in subscription-style charter services.
| Leading Market Players |
|---|
| NetJets |
| VistaJet |
| Flexjet |
| Wheels Up |
| Jet Linx Aviation |
| Air Charter Service |
| Magellan Jets |
| Solairus Aviation |
| Chapman Freeborn Airchartering |
| Others |
Supply Flow & Price Mechanics
Pilot certification bottlenecks in the United States and maintenance technician shortages across North American MRO hubs widen the spread between premium membership rates and transactional charter pricing. Labor-cost differentials between FAA Part 135-certified crew bases and emerging training pipelines in the United Arab Emirates feed directly into tiered hourly rate structures.
Pricing Analysis
Margin tightening in on-demand charter reflects unhedged jet fuel exposure and pilot premium wages compressing operator returns. Three-tier pricing structure across premium membership, standard fractional, and economy on-demand levels stratifies by aircraft availability guarantees and positioning cost absorption. Price differentiation hinges on Safety Management System certification tier and guaranteed aircraft replacement commitments. Corporate flight departments exhibit lowest price sensitivity due to capital-light budgeting frameworks, while leisure travelers in secondary US metropolitan markets drive hardest hourly rate negotiations.
Supply Chain Analysis
Airframe and powerplant technician availability constraints in the United States, Germany, and Switzerland extend maintenance slot lead times and inflate labor arbitrage costs. Aircraft manufacturing concentrates in Brazil, Canada, and the United States for light and mid-size platforms, while large-cabin completions cluster in European and US completion centers. Supply chain risk centers on single-source avionics dependencies from concentrated semiconductor fabricators. Distribution runs through fractional ownership program bases, charter broker networks, and direct operator relationships with Fortune 500 procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
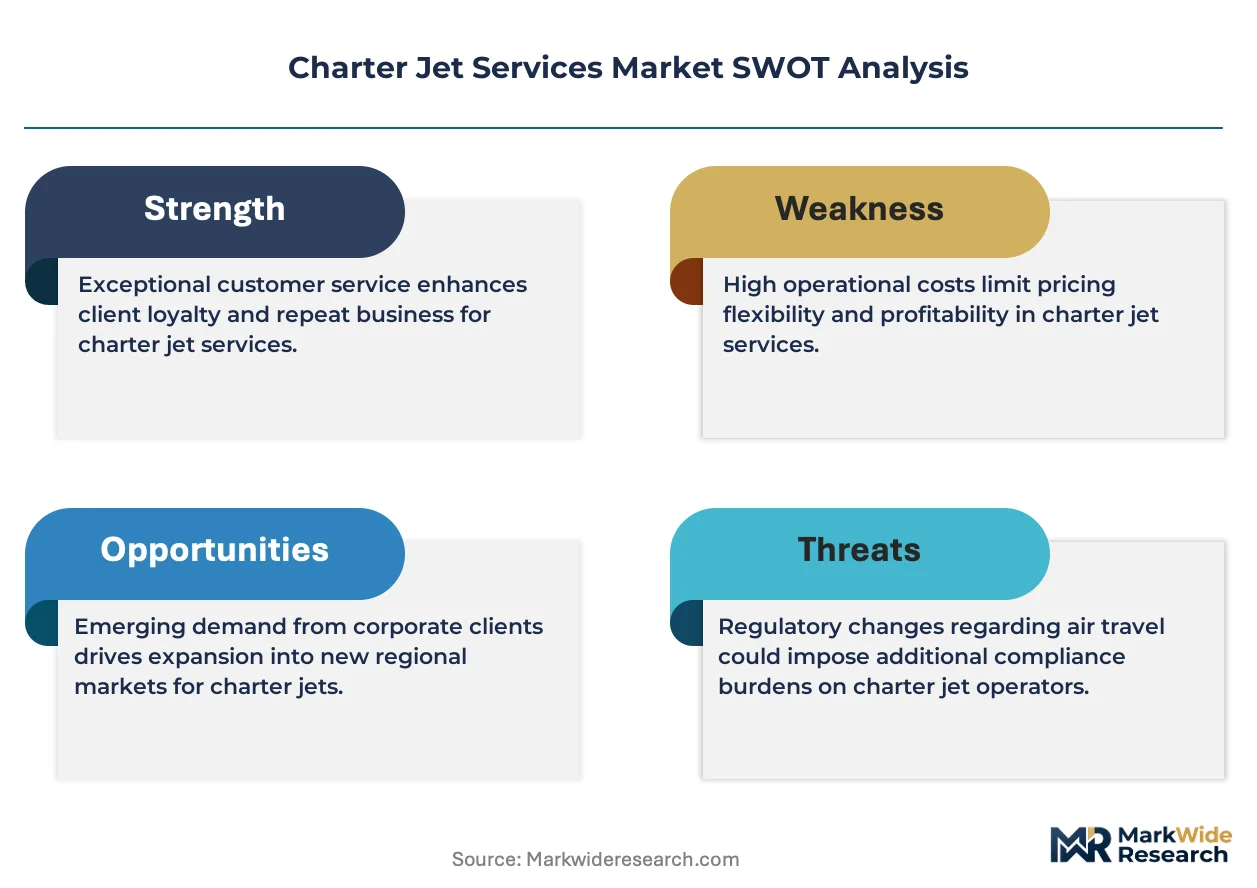
This market rewards vertical integration into proprietary booking platforms and captive maintenance infrastructure. Operators securing upstream control over pilot training pipelines and downstream control over customer-facing digital interfaces capture structural margin.
For Market Incumbents: Extend fleet standardization investments to compress maintenance part inventories and accelerate technician cross-utilization. Consolidate around Safety Management System certification tiers that exceed baseline FAA Part 135 requirements, creating regulatory moats against asset-light entrants. Anchor membership program restructuring around fixed monthly fees that internalize fuel surcharge volatility. For New Entrants and Emerging Players: Blockchain-verified maintenance records offer a technology-first wedge into corporate flight department procurement workflows resistant to legacy broker fragmentation. Target medical evacuation specialization in secondary US metropolitan areas where government reimbursement stability and underpenetrated air ambulance infrastructure create white-space entry. Deploy direct-to-enterprise sales bypassing traditional charter broker intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with operators possessing verified sustainable aviation fuel supply chains and multi-year biorefinery offtake agreements given EU Green Deal compliance cost gradients. Long-term viability favors fractional ownership incumbents with depreciation-sharing structures and globally uniform fleet deployment. Monitor SAF blending mandate enforcement timelines as inflection indicator for asset-stranded risk among conventional fuel-dependent operators.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Supply Chain Integration | Multi-year biorefinery offtake agreements lock in premium fuel pricing against EU Green Deal mandates. |
| Proprietary Booking Platform Development | API connectivity with corporate travel management systems eliminates customer acquisition friction. |
| Maintenance Infrastructure Expansion | Captive MRO capabilities reduce technician scarcity exposure and compress turnaround timelines. |
| Pilot Training Pipeline Investment | In-house certification programs bypass FAA Part 135 crew availability constraints. |
| Membership Program Restructuring | Fixed monthly fees internalize fuel surcharge volatility and convert sporadic flyers to recurring revenue. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with charter operations directors, fractional ownership program managers, corporate flight department procurement leads, and FAA certification specialists combined with secondary validation from EASA operational standard disclosures, ICAO carbon offset mechanism documentation, and airport authority slot allocation records. Bottom-up fleet deployment modeling triangulated against top-down wealth density and private aviation infrastructure assessments.
Granularity-level modeling operated at aircraft type, service tier, end-user application, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from segment-specific utilization rate projections, membership program penetration curves, and fleet replacement cycle assumptions. Forecast inputs incorporated pilot supply elasticity estimates and sustainable aviation fuel procurement cost trajectories without year-specific anchoring.
Several conditions sit outside the modeled scope, including abrupt FAA duty limit regulatory revisions, geopolitical disruption to biorefinery feedstock supply, and pandemic-scale demand collapse scenarios. Forecasts reflect documented assumptions around wealth concentration trajectories and carbon pricing enforcement continuity. Material deviation in SAF mandate implementation timelines or pilot certification throughput rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
US Helicopter Services Market
Aviation and Defense Training and Simulation
Global Airlines Market
Aviation and Defense Training and Simulation
North America Charter Jet Services Market
Aviation and Defense Training and Simulation
Middle-East and Africa Jet Charter Services Market
Aviation and Defense Training and Simulation
Domestic Aviation Market
Aviation and Defense Training and Simulation
South-East Asia Civil Aviation Market
Aviation and Defense Training and Simulation
Digital Aviation Market
Aviation and Defense Training and Simulation
Helicopter Services Market