
 US Helicopter Services Market | 2026-2036
US Helicopter Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Helicopter Services Market Insights
Digital flight management systems and satellite-based helicopter route optimization is reshaping fleet dispatch efficiency across the sector. Bristow Group Inc. leverages its Gulf Coast infrastructure to sustain offshore oil and gas contracts. Air Methods Corporation anchors its position through hospital-based emergency medical services networks. Era Group Inc. differentiates via specialized heavy-lift capabilities for utility and construction clients.
US Helicopter Services encompass crewed and uncrewed rotary-wing operations delivering point-to-point aerial transport, typically utilizing turbine-powered aircraft with operational ceilings between 10,000 and 20,000 feet and payload capacities ranging from 1,200 to 20,000 pounds depending on airframe class. These services execute missions inaccessible to fixed-wing aircraft, including vertical replenishment, hoist rescue, and precision load placement in confined zones. Emergency Medical Services commands the largest share of flight hours, driven by hospital system outsourcing and rural healthcare access gaps. Offshore Transport generates the highest revenue per flight hour due to fuel-intensive long-range missions over the Gulf of Mexico. Light Helicopters dominate unit sales for training and surveillance roles, while Medium Lift Helicopters capture the broadest application span across commercial and government contracts.
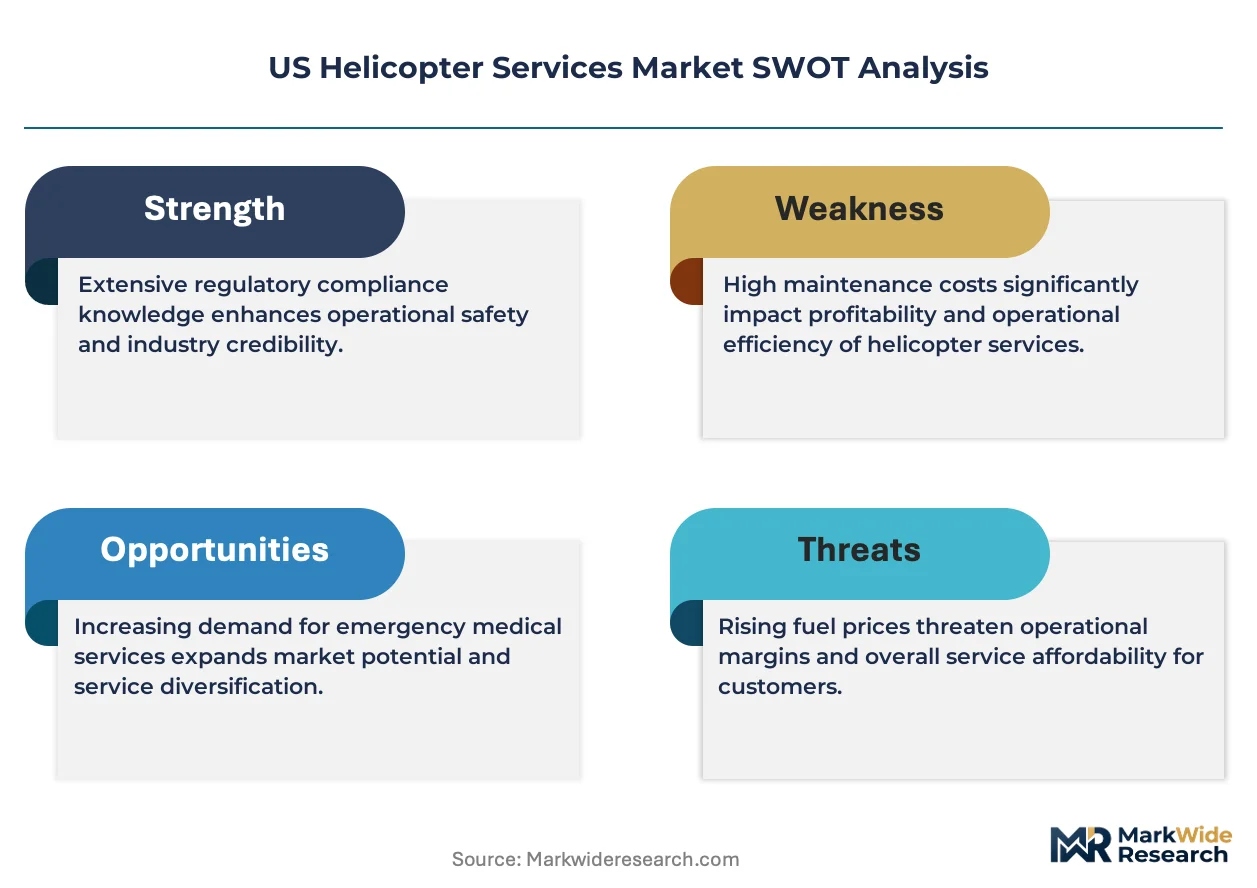
FAA Part 135 operating certificates and OSHA workplace safety standards govern pilot duty limits, maintenance intervals, and passenger transport protocols, directly constraining fleet scalability and labor scheduling flexibility. EPA noise regulations and local land-use ordinances restrict heliport siting in metropolitan corridors, compressing urban service expansion timelines. Stakeholders must monitor FAA UAS integration timelines and urban air mobility corridor designations, as these frameworks will determine whether autonomous rotary platforms complement or displace traditional crewed services in logistics and medical delivery roles.
Market Dynamics
FAA UAS integration mandates and urban air mobility corridor designations are compressing the operational boundary between crewed and autonomous rotary platforms, forcing incumbent operators to recertify fleets for mixed-traffic environments while defending core offshore energy contracts.
Growth Catalysts
- Offshore Energy Logistics:Deepwater exploration in the Gulf of Mexico sustains long-range heavy-lift demand, with platform decommissioning cycles extending fleet utilization into marginal field redevelopment.
- FAA Reauthorization Act:Evolving Part 135 certification pathways for autonomous operations are creating regulatory on-ramps for medical cargo and logistics trials in designated urban corridors.
- Rural Healthcare Access Gaps:Hospital system outsourcing of emergency transport is expanding hospital-based EMS networks across underserved Appalachian and Rocky Mountain regions.
Market Restraints
- Aviation Fuel Volatility:Jet A price swings directly compress margins on fuel-intensive offshore missions, with Gulf Coast operators bearing disproportionate exposure to refinery capacity constraints.
- Pilot Labor Scarcity:Military-to-civilian transition bottlenecks and ATP certification backlogs are constraining fleet expansion timelines for Part 135 operators.
- Heliport Siting Restrictions:EPA noise regulations and municipal land-use ordinances in metropolitan corridors are blocking urban vertiport development in high-density demand zones.
Strategic Opportunities
- Texas-Louisiana Gulf Coast:Offshore wind installation logistics present a structural demand pivot as oil and gas field maturity accelerates platform repurposing.
- Intermodal Medical Distribution:Hospital system networks are piloting drone-crewed hybrid models for pharmaceutical delivery between rural clinics and trauma centers.
- Utility Infrastructure Modernization:Grid hardening and transmission line upgrades are expanding specialized heavy-lift contracts for precision load placement in terrain-constrained environments.
Industry Challenges
- Airframe Certification Timelines:FAA STC approvals for avionics retrofits and autonomy integration kits are extending 18-24 months, delaying fleet modernization.
- Maintenance Technician Shortage:A&P mechanic pipeline constraints are compressing turnaround times for turbine overhaul cycles, particularly in remote base locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Helicopter Services Market |
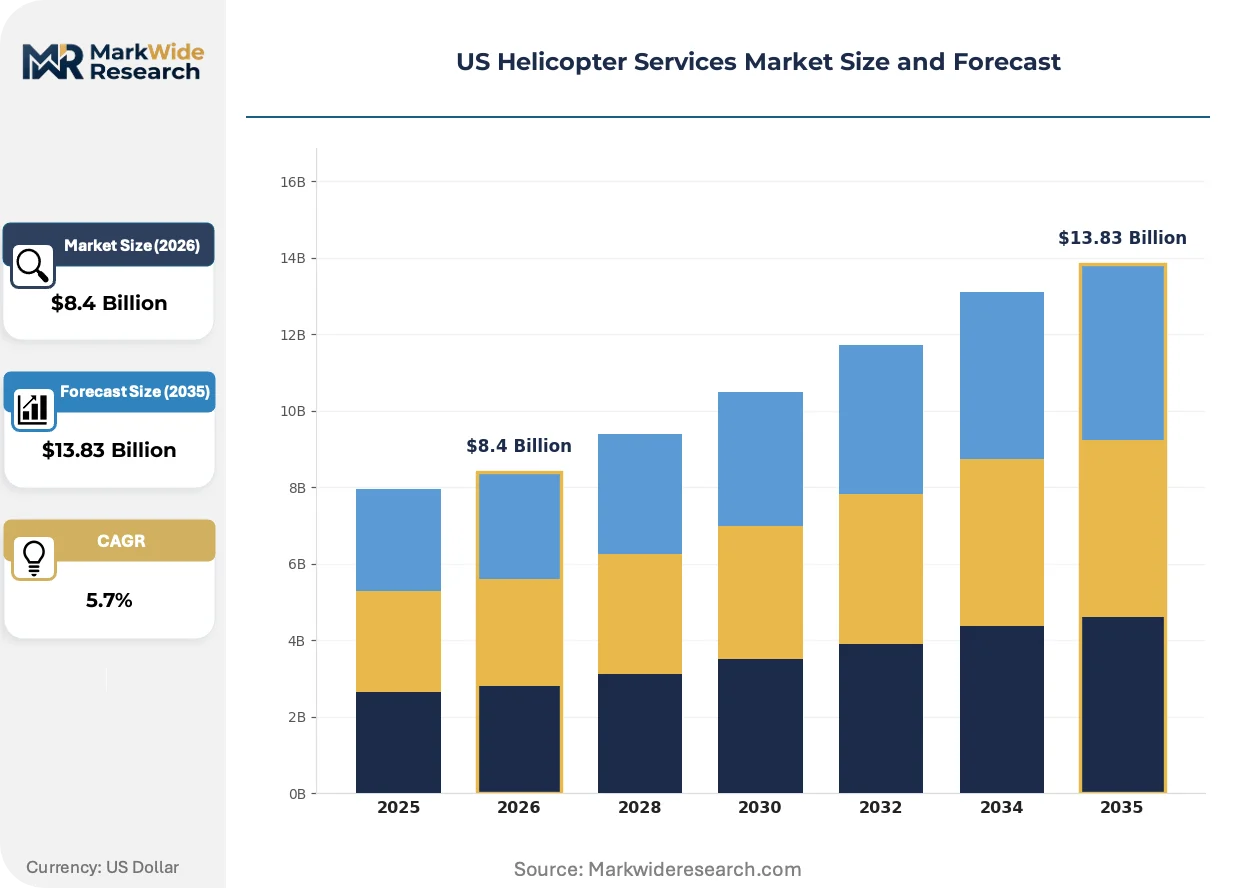
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Medical Services, Aerial Firefighting, Search & Rescue, Law Enforcement Support, Agricultural Spraying, Photogrammetry Application: Offshore Transport, Executive Travel, Tourism & Sightseeing, Construction Assistance, News & Media Coverage, Wildlife Monitoring End User: Private Operators, Government Agencies, Oil & Gas Companies, Mining Corporations, Media Houses, Utility Providers Helicopter Type: Light Helicopters, Medium Lift Helicopters, Heavy Lift Helicopters, Unmanned Aerial Vehicles, Multi-Engine Helicopters, Single-Engine Helicopters |
| Companies Covered | Bristow Group Inc., Air Methods Corporation, Petroleum Helicopters International Inc., CHC Helicopter Group, Era Group Inc., Metro Aviation, CHI Aviation, Global Medical Response Inc., Erickson Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Helicopter Services Market Trends and Innovations
Digital flight management architectures are compressing the operational stack between dispatch and execution, with satellite-based route optimization and predictive maintenance analytics converging to reshape fleet economics across mission profiles.
Synthetic vision systems and augmented reality head-up displays are collapsing the minimum visibility thresholds for instrument approaches in degraded visual environments. Offshore operators in the Gulf of Mexico are retrofitting medium-lift fleets with these systems to sustain mission completion rates during sea-state deterioration. The technology is collapsing the historical trade-off between safety margins and flight-hour throughput in energy logistics contracts.
FAA Part 135 operating certificate modernization under the Reauthorization Act is mandating electronic record-keeping and remote monitoring capabilities for all passenger-carrying operations. The regulation is forcing dispatch system upgrades and real-time telemetry integration across legacy fleets. EMS operators in the Mountain West are responding fastest, driven by hospital system contracting requirements for operational transparency.
Hospital procurement departments are consolidating air medical transport contracts under system-wide master service agreements, displacing the fragmented hospital-by-hospital purchasing that historically dominated EMS revenue. Aggregated buying power is compressing per-flight-hour rates while demanding guaranteed response-time commitments. This concentration is most visible across the Southeast, where regional health systems are absorbing independent community hospitals and their associated aviation contracts.
US Helicopter Services Market Segmentation
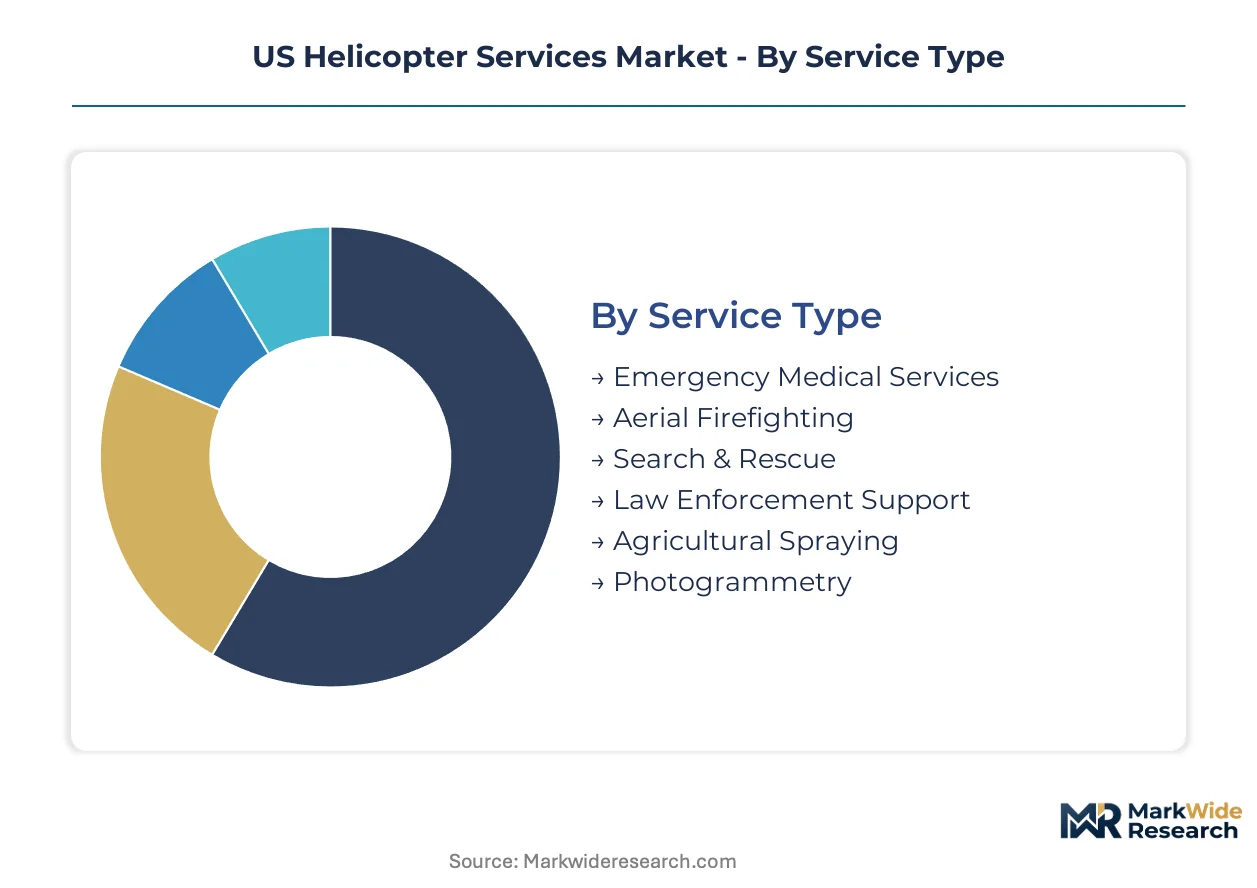
Segmentation in the US Helicopter Services Market reveals distinct operational economics across mission profiles. Service type determines fleet configuration and certification requirements, while end-user concentration shapes contract structures and pricing power. Understanding these divides exposes where margin compression and expansion concentrate.
Service Type:
The use-case spectrum spans life-critical interventions to precision agriculture, with each service demanding specialized airframes, crew training, and regulatory compliance.
- Emergency Medical Services:Hospital-based networks utilize turbine-powered aircraft with medical interiors for rapid patient transport from accident scenes to trauma centers. Demand concentrates across Appalachian and Rocky Mountain regions where ground ambulance response times exceed clinical thresholds.
- Aerial Firefighting:Bambi bucket and tanker configurations deploy for wildfire suppression in California, Oregon, and Arizona timberlands. US Forest Service contracting cycles and CAL FIRE mutual aid agreements drive seasonal fleet utilization peaks.
- Search & Rescue:Hoist-equipped helicopters execute extraction missions in maritime and alpine environments. Coast Guard and National Guard units dominate procurement with specialized night-vision and de-icing capabilities.
- Law Enforcement Support:Thermal imaging and loudspeaker systems enable aerial surveillance and crowd management. State police aviation units in Texas, Florida, and California anchor multi-year fleet renewal programs.
- Agricultural Spraying:Low-altitude crop dusting with GPS-guided precision application targets Midwest corn and soybean belts. EPA pesticide handling regulations and drift mitigation rules constrain operator licensing.
- Photogrammetry:Stabilized camera platforms capture terrain mapping and infrastructure inspection data. Utility companies and state DOTs commission pipeline corridor and transmission line surveys.
The dominant share belongs to Emergency Medical Services, while Aerial Firefighting is closing the gap fastest.
Application:
Cost tiers separate fuel-intensive offshore logistics from short-hop executive transport, with capital recovery timelines varying by mission distance and payload requirements.
- Offshore Transport:Long-range missions to Gulf of Mexico drilling platforms utilize medium and heavy-lift helicopters with extended fuel capacity. Platform decommissioning and offshore wind installation are redirecting demand from oil and gas logistics.
- Executive Travel:Point-to-point urban mobility for corporate clients utilizes light and multi-engine helicopters with premium interiors. Heliport siting restrictions in Manhattan, Los Angeles, and Chicago metropolitan corridors constrain network expansion.
- Tourism & Sightseeing:Scenic flights over Grand Canyon, Hawaiian volcanoes, and Alaskan glaciers operate on seasonal schedules with high passenger turnover. FAA Part 135 sightseeing waivers and noise abatement protocols govern route planning.
- Construction Assistance:Precision load placement for high-rise steel erection and remote infrastructure projects demands heavy-lift capacity. Utility-scale wind turbine installation in Texas and Iowa is expanding contract volumes.
- News & Media Coverage:Rapid-response ENG (electronic news gathering) helicopters deploy for traffic reporting and breaking event coverage. Broadcast station ownership consolidation in top-20 media markets is reducing independent operator counts.
- Wildlife Monitoring:Aerial census and tagging operations support federal and state conservation agencies in Montana, Wyoming, and Alaska. US Fish and Wildlife Service contracts specify low-disturbance flight protocols.
Offshore Transport commands the highest revenue per flight hour, though Construction Assistance is expanding most quickly.
End User:
Customer type determines procurement sophistication, with government and corporate buyers demanding outcome-based contracts and real-time operational transparency.
- Private Operators:Independent flight schools, charter services, and personal aircraft owners utilize light helicopters for training and recreational flying. Insurance premium escalation and fuel cost volatility constrain fleet growth.
- Government Agencies:Federal, state, and municipal aviation units procure through competitive bidding with socio-economic contracting preferences. Department of Homeland Security and Department of Interior anchor multi-airframe fleet programs.
- Oil & Gas Companies:Supermajors and independents contract dedicated offshore transport services under long-term agreements with minimum utilization guarantees. Chevron, ExxonMobil, and Shell operations in Gulf Coast waters sustain heavy-lift demand.
- Mining Corporations:Remote site logistics and personnel rotation in Nevada, Arizona, and Alaska depend on helicopter transport where road infrastructure is absent. Tier-1 operators specify all-weather IFR capabilities.
- Media Houses:Broadcast network affiliates and independent news stations lease or own ENG helicopters for metropolitan coverage. Sinclair Broadcast Group and Nexstar Media Group centralize aviation procurement across station portfolios.
- Utility Providers:Power generation and transmission companies deploy helicopters for line inspection, tower construction, and emergency storm response. Duke Energy, Southern California Edison, and Pacific Gas & Electric maintain captive aviation units or exclusive vendor relationships.
Government Agencies represent the most stable demand base, while Utility Providers are gaining share fastest.
Helicopter Type:
Airframe class dictates payload-range tradeoffs and certification pathways, with unmanned platforms introducing new regulatory and operational paradigms.
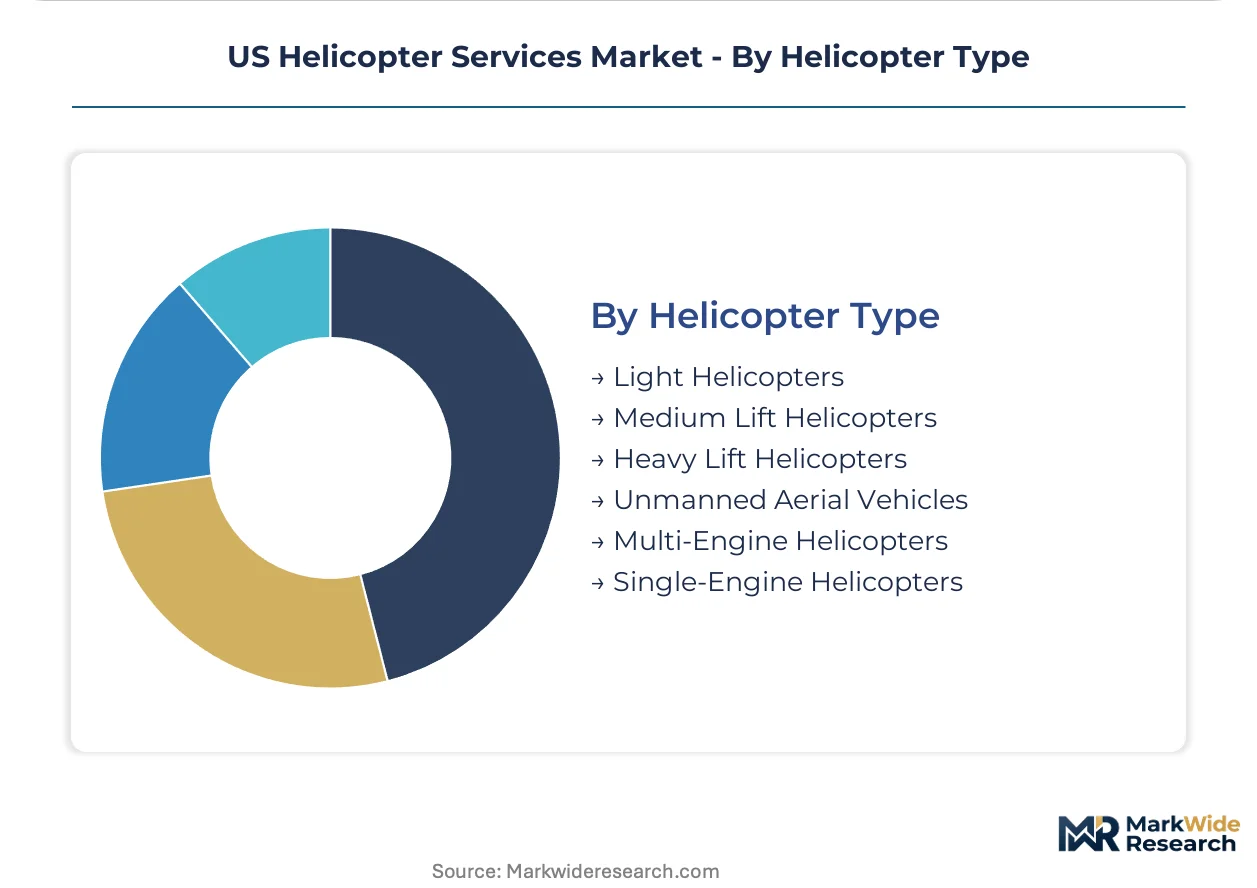
- Light Helicopters:Single-engine aircraft under 3,000 pounds MTOW dominate flight training, surveillance, and short-haul executive transport. Robinson R44 and R66 models anchor US production volume.
- Medium Lift Helicopters:Twin-turbine aircraft between 6,000 and 12,000 pounds MTOW capture the broadest mission span across EMS, offshore transport, and utility work. Bell 407 and Airbus H125 variants lead fleet counts.
- Heavy Lift Helicopters:Aircraft exceeding 20,000 pounds MTOW execute construction, logging, and firefighting with external load capabilities. Sikorsky S-64 Skycrane and Boeing CH-47 Chinook configurations serve specialized contracts.
- Unmanned Aerial Vehicles:Rotary-wing drones under 55 pounds are piloting medical cargo and inspection missions under FAA Part 107 and emerging BVLOS waivers. Autonomy integration timelines will determine crewed displacement potential.
- Multi-Engine Helicopters:Twin-turbine redundancy satisfies IFR and over-water requirements for passenger transport and offshore operations. FAA Part 135 passenger rules mandate multi-engine configuration for certain routes.
- Single-Engine Helicopters:Lower acquisition and operating costs sustain VFR training and light utility roles. Robinson Helicopter Company manufacturing in Torrance, California anchors domestic supply.
Medium Lift Helicopters hold the dominant share, though Unmanned Aerial Vehicles are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast operators export offshore transport services to international supermajors operating in Mexican and Brazilian waters, creating a transnational corridor for deepwater logistics expertise.
Texas-Louisiana Gulf Coast
Offshore oil platform decommissioning and emerging wind turbine installation sustain heavy-lift demand. FAA Part 135 certificate holders face heightened scrutiny for over-water operations. Houston and Lake Charles anchor the densest concentration of medium-lift fleets serving energy logistics contracts.
Appalachian Region
Hospital system consolidation drives emergency medical services outsourcing across West Virginia, Kentucky, and Tennessee. Rural healthcare access gaps trigger state Medicaid reimbursement adjustments. Pittsburgh and Charleston clusters specialize in mountain terrain rescue capabilities.
California
Wildfire suppression contracts and utility infrastructure inspection expand seasonal fleet utilization. CAL FIRE mutual aid agreements and CPUC grid hardening mandates reshape procurement timelines. Sacramento and Redding bases coordinate aerial firefighting resource deployment across Sierra Nevada corridors.
Alaska
Remote mining logistics and wildlife monitoring sustain year-round operations beyond road networks. Department of Interior contracting preferences favor operators with Arctic IFR certification. Anchorage and Fairbanks serve as hubs for North Slope oil field personnel rotation.
Mountain West
Ski resort medical evacuation and high-altitude construction projects demand specialized performance capabilities. State DOT avalanche control programs supplement commercial revenue streams. Denver and Salt Lake City operators maintain rapid response networks across Continental Divide terrain.
US Helicopter Services Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service platforms with diversified mission portfolios. Tier-1 operators combine offshore energy logistics with emergency medical networks to stabilize utilization across cyclical demand patterns. Three strategic archetypes dominate: Gulf Coast offshore specialists, hospital-system EMS integrators, and diversified utility contractors. Competitive intensity centers on fleet modernization cycles and FAA certification pathway navigation for autonomous platform integration.
Among publicly traded operators, Bristow Group Inc. and Era Group Inc. exemplify the offshore-heavy archetype with Gulf Coast infrastructure concentration, while Air Methods Corporation anchors the hospital-based EMS tier through system-wide contracting relationships. These named entities represent distinct strategic positioning vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Bristow Group Inc. |
| Air Methods Corporation |
| Petroleum Helicopters International Inc. |
| CHC Helicopter Group |
| Era Group Inc. |
| Metro Aviation |
| CHI Aviation |
| Global Medical Response Inc. |
| Erickson Incorporated |
| Others |
Pricing and Supply Chain Analysis
Canadian turbine engine manufacturing concentration at Pratt & Whitney Canada and French gearbox production at Safran Helicopter Engines anchor upstream pricing power, directing margin capture toward airframe integrators with long-term power-by-the-hour contracts rather than independent operators bearing fuel and maintenance volatility.
Pricing Analysis
Technology-generation pricing gaps separate legacy analog-cockpit fleets from glass-cockpit retrofits and emerging autonomous-capable platforms. Three-tier pricing structure across premium multi-engine IFR configurations, standard single-turbine VFR workhorses, and economy piston training aircraft governs charter and EMS contracts. Price differentiation rests on FAA Part 135 certification tier and installed avionics generation. Cost compression in economy training tiers is intensifying because Robinson Helicopter production scale and used-aircraft import supply from Australia and South Africa. Hospital system procurement departments exhibit lowest price sensitivity due to patient-outcome liability exposure, while independent flight schools face acute margin pressure.
Supply Chain Analysis
Extended payment terms from Bell Textron and Airbus Helicopters to tier-one avionics suppliers are compressing working capital cycles across the component base. Manufacturing concentrates in France, Germany, and Canada for turbine powerplants and main rotor systems. Raw material dependencies include titanium forgings from Russia and Japan, composite prepregs from the United States, and rare-earth magnets for electric propulsion prototypes from China. Single-source vulnerability in FAA-certified avionics suites creates regulatory lock-in risk. Distribution runs through factory-authorized service centers and independent Part 145 repair stations with geographic exclusivity arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as urban air mobility corridor designations and FAA Reauthorization Act autonomy pathways create regulatory on-ramps for medical cargo and logistics trials that extend addressable demand beyond traditional crewed operations.
For Market Incumbents: Build regulatory moat through early FAA STC acquisition for autonomy integration kits and mixed-traffic airspace certification. Deepen vertical integration into predictive maintenance analytics platforms to capture recurring revenue from hospital system contracting demands. Defend against unmanned aerial vehicle displacement by embedding crewed-uncrewed hybrid service models into existing EMS and offshore logistics contracts. For New Entrants and Emerging Players: Pursue white-space positioning in offshore wind installation logistics along the Texas-Louisiana Gulf Coast, where platform decommissioning expertise transfers directly to turbine foundation transport. Target rural pharmaceutical distribution corridors between Appalachian clinics and trauma centers, where drone-crewed hybrid models bypass pilot shortage constraints. Anchor go-to-market through exclusive vendor relationships with regional health systems consolidating independent hospital aviation contracts. For Investors and Strategic Acquirers: Capital is best deployed toward diversified utility contractors with captive heavy-lift capabilities and hospital-system EMS integrators with system-wide master service agreements. Long-term viability hinges on fleet modernization runway and autonomy certification pipeline positioning. Watch FAA BVLOS waiver expansion velocity and urban vertiport infrastructure funding allocations as inflection signals for crewed-displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Autonomy Certification Investment | STC approvals for mixed-traffic operations unlock urban corridor access before competitors complete retrofit cycles. |
| Offshore Wind Logistics Pivot | Platform decommissioning expertise transfers to turbine installation contracts as Gulf Coast energy mix diversifies. |
| Hospital System Contract Consolidation | System-wide master service agreements displace fragmented purchasing and lock in multi-year utilization guarantees. |
| Predictive Maintenance Platform Deployment | Real-time telemetry integration satisfies hospital procurement transparency demands and creates recurring revenue streams. |
| Vertically Integrated Pilot Training Pipeline | Captive Part 141 flight schools address ATP certification backlogs constraining fleet expansion timelines. |
Research Methodology
Desk research of FAA certification databases, SEC 10-K filings from publicly traded operators, and US Forest Service contracting records preceded structured interviews with Part 135 certificate holders, hospital system aviation procurement directors, and offshore energy logistics planners. Primary fieldwork with maintenance technicians at Gulf Coast base locations and EMS dispatch coordinators in Appalachian and Mountain West regions validated utilization rate assumptions. Secondary sources included Department of Interior contracting disclosures, CAL FIRE mutual aid agreements, and turbine overhaul cost benchmarks. Bottom-up fleet counts triangulated against top-down revenue estimates from operator financial disclosures.
Assumptions held fixed include FAA UAS integration timelines, Jet A price volatility bands, and pilot labor supply recovery trajectories, while offshore wind installation demand curves and hospital system consolidation velocity were stress-tested across scenarios. Segmentation modeling spanned service type, application cost tier, end-user procurement sophistication, and helicopter airframe class. CAGRs derived from historical utilization patterns projected against fleet replacement cycles and regulatory modernization mandates. Industry-specific inputs included Part 135 certificate issuance rates and heliport permitting approval timelines in metropolitan corridors.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting aircraft financing availability or Jet A refining capacity constraints would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway timing and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
Charter Jet Services Market
Aviation and Defense Training and Simulation
Domestic Aviation Market
Aviation and Defense Training and Simulation
South-East Asia Civil Aviation Market
Aviation and Defense Training and Simulation
Middle-East and Africa Jet Charter Services Market
Aviation and Defense Training and Simulation
North America Charter Jet Services Market
Aviation and Defense Training and Simulation
Helicopter Services Market
Aviation and Defense Training and Simulation
Global Airlines Market
Aviation and Defense Training and Simulation
Digital Aviation Market