
 Dehydrated Pet Food Market | 2026-2036
Dehydrated Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Pet Food Market Analysis
High-pressure processing and low-temperature dehydration is reshaping how manufacturers preserve nutritional integrity without synthetic additives. The Honest Kitchen leverages vertical integration into human-grade ingredient sourcing to sustain premium positioning. Stella & Chewy's anchors its competitive edge through freeze-dried specialization and veterinary channel control. Mars Inc. dominates mass-market distribution through shelf-stable formulations that compete on convenience and price accessibility.
Dehydrated pet food refers to moisture-reduced feed products typically containing 2-10% water content, produced through controlled thermal drying or sublimation methods that preserve protein bioavailability and enzymatic activity while eliminating refrigeration requirements. The manufacturing process involves raw material preparation, precise temperature modulation between 40°C and 80°C, and final moisture equilibration to achieve shelf stability exceeding twelve months. Freeze-dried formulations command the highest margin pools due to superior nutrient retention and palatability metrics, while air-dried alternatives occupy the fastest-growing volume tier as price-sensitive consumers trade up from conventional kibble. Meat-based ingredient types lead absolute revenue contribution, though grain-free positioning has matured into a baseline expectation rather than a differentiator across premium channels.
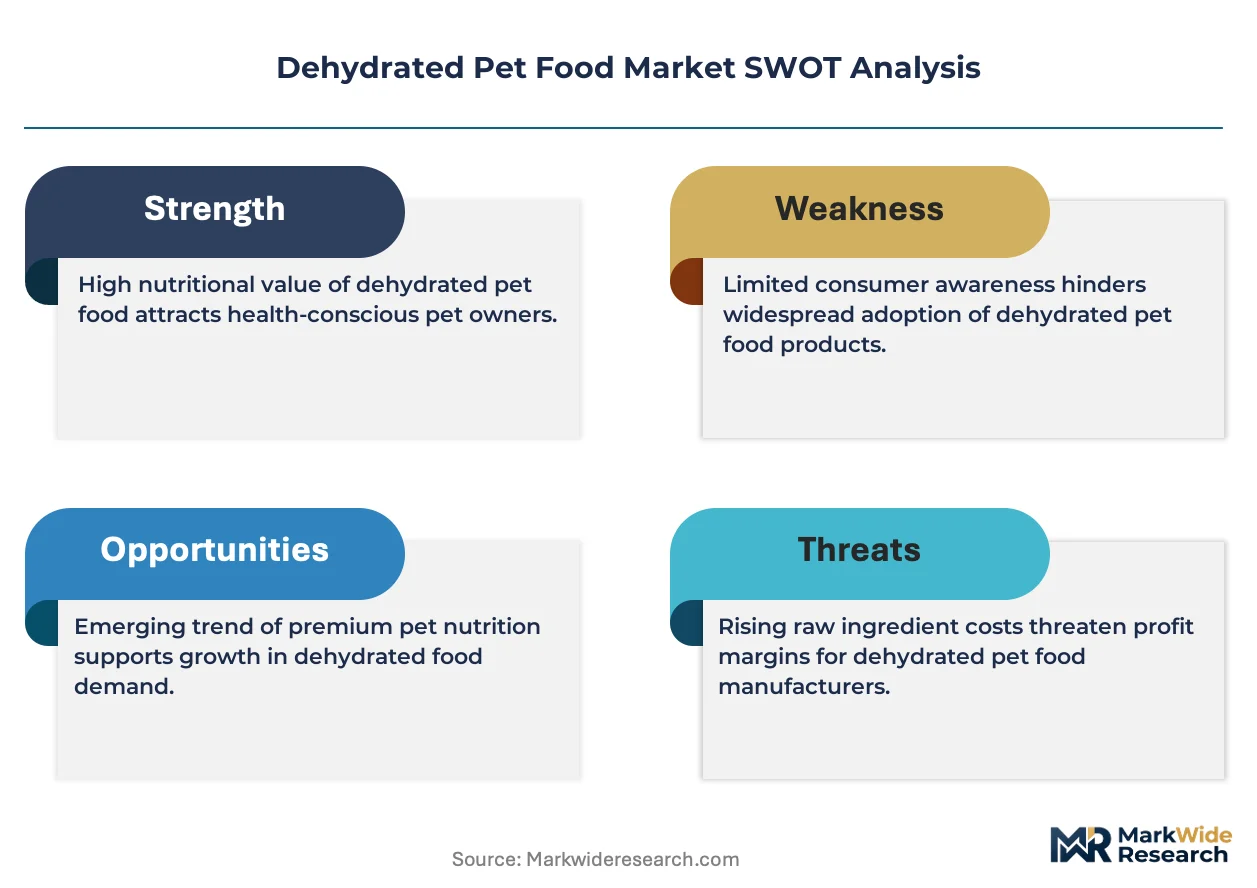
The FDA's Food Safety Modernization Act requirements for preventive controls and the Association of American Feed Control Officials nutrient profiles constrain formulation flexibility while elevating compliance costs for new entrants. State-level inspection protocols in California and Texas impose additional facility certification burdens that filter out smaller producers. Stakeholders must monitor evolving consumer litigation around label claims and the regulatory trajectory of novel protein sources entering the dehydrated category.
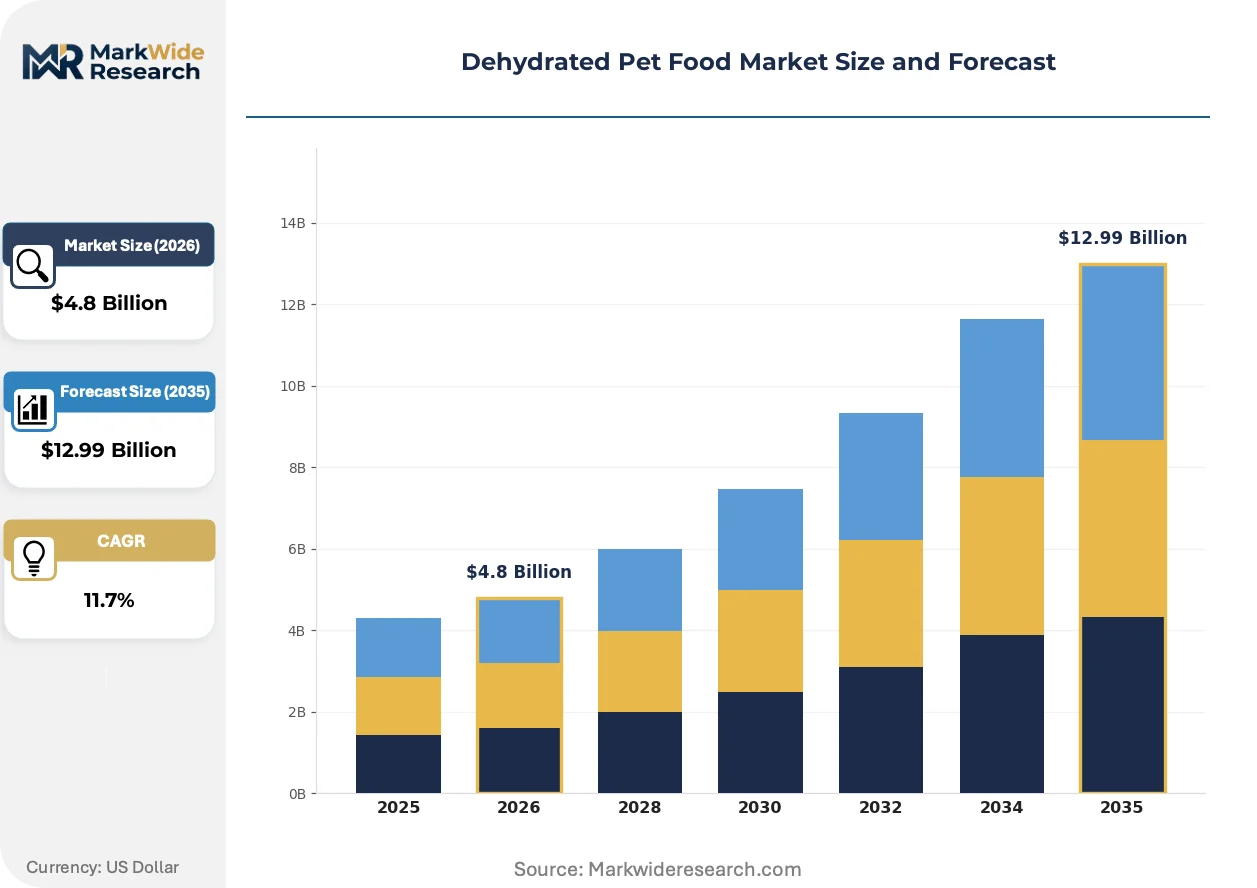
Market Dynamics
High-pressure processing and low-temperature dehydration methods are compressing traditional thermal preservation, forcing manufacturers to retool facilities around nutrient-retention metrics rather than shelf-life extension alone. This technological pivot elevates capital requirements while fragmenting competitive positioning between legacy air-dried specialists and freeze-dried innovators.
Growth Catalysts
- FDA Food Safety Modernization Act preventive controls:Mandatory hazard analysis and risk-based preventive controls for animal food facilities are professionalizing manufacturing standards and filtering out subscale competitors.
- Subscription-based direct-to-consumer channels:Recurring revenue models in the United States are compressing customer acquisition costs and deepening lifetime value metrics for premium formulations.
- Cold-chain-free processing infrastructure:Elimination of refrigerated logistics requirements is expanding distribution reach into secondary and tertiary retail tiers previously inaccessible to fresh or frozen alternatives.
Market Restraints
- Human-grade ingredient cost volatility:Premium protein sourcing from USDA-inspected facilities exposes margins to livestock commodity price swings and slaughterhouse capacity constraints.
- California and Texas state facility certification burdens:Additional inspection protocols beyond federal requirements create geographic concentration risk for production capacity expansion.
- Freeze-drying equipment lead times:Specialized vacuum chamber and condenser system procurement cycles extend 12-18 months, throttling rapid capacity scaling for emerging entrants.
Strategic Opportunities
- Veterinary clinic channel penetration:Prescription-adjacent positioning through licensed practitioner endorsement commands price premiums and creates switching friction for pet owners.
- Novel protein source regulatory pathways:Cultivated and insect-based protein approvals under evolving FDA Center for Veterinary Medicine frameworks open formulation differentiation.
- Hybrid air-dried and freeze-dried product architectures:Blended moisture-reduction techniques are lowering unit economics while preserving palatability metrics for mid-tier buyers.
Industry Challenges
- Preventive controls qualified individual staffing:FSMA-mandated food safety plan oversight requires specialized expertise scarce outside human food manufacturing.
- Label claim litigation exposure:Class action vulnerability around "human-grade," "natural," and "grain-free" positioning necessitates legal review overhead and insurance cost escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Pet Food Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried, Air-Dried, Dehydrated Raw, Cooked Dehydrated Ingredient Type: Meat-based, Grain-free, Vegetables, Fruits End User: Cat Owners, Dog Owners, Small Pets, Birds Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Mars Inc., Nestle Purina, Blue Buffalo, Diamond Pet Foods, Heristo, The Honest Kitchen, Stella & Chewy’s, Affinity Petcare, Grandma Lucy’s, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Pet Food Market Emerging Trajectories
Formulation science and preservation technology are converging to redefine nutritional integrity benchmarks, with manufacturers competing on enzymatic activity retention rather than moisture reduction alone. This shift elevates R&D intensity while compressing acceptable processing temperature windows.
High-pressure processing is hybridizing with low-temperature air-drying to create intermediate moisture products that retain heat-sensitive vitamins without freeze-drying capital intensity. Mid-market manufacturers are adopting this hybrid architecture to bridge the price gap between conventional kibble and premium freeze-dried formats. The structural consequence is tier compression, as technical differentiation between air-dried and freeze-dried categories narrows and price premiums contract.
EFSA novel food approval pathways for insect protein and cultivated meat ingredients are creating regulatory precedent that FDA Center for Veterinary Medicine is monitoring for domestic framework adaptation. This transatlantic regulatory arbitrage is accelerating dossier preparation by ingredient suppliers seeking first-mover positioning in protein diversification. European approval timelines are compressing commercialization windows for North American market entry.
Direct-to-consumer subscription models are displacing specialty retail as the primary customer acquisition channel for premium dehydrated formulations. Chewy and independent brand-owned platforms are capturing recurring revenue relationships that brick-and-mortar pet specialty stores struggle to replicate. This channel rotation is most visible in coastal United States metropolitan markets where delivery density supports unit economics.
Dehydrated Pet Food Market Segmentation
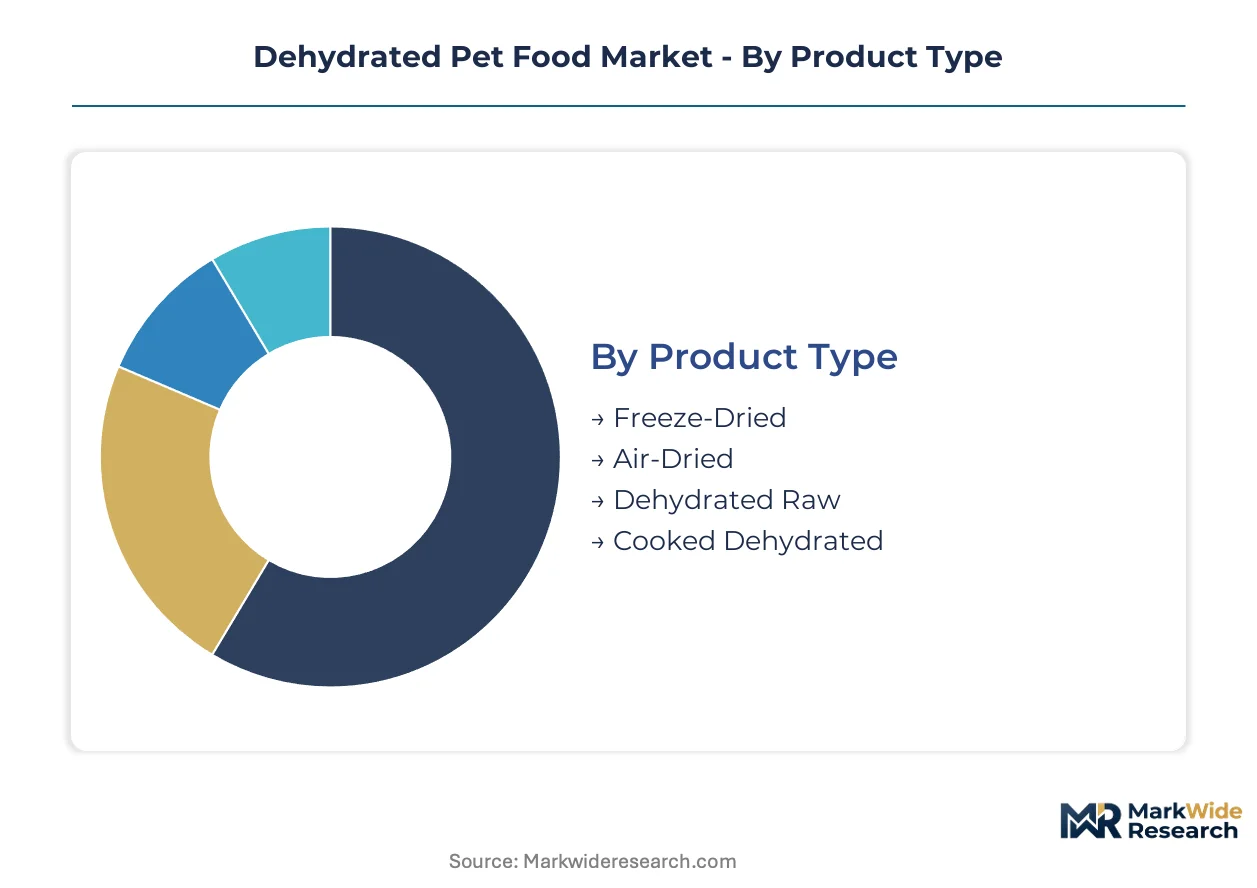
Dehydrated pet food manufacturers segment their portfolios across preservation technology, ingredient sourcing, species targeting, and channel access. Each dimension carries distinct margin profiles and capital requirements that shape competitive positioning and expansion sequencing.
Product Type:
Freeze-dried formulations command the longest production cycles due to vacuum chamber processing times, while air-dried alternatives compress manufacturing throughput by 60-70%.
- Freeze-Dried:Sublimation-based moisture removal at sub-zero temperatures preserves enzymatic activity and protein bioavailability without thermal degradation. Dog owners in United States coastal metros drive premium demand through veterinary-endorsed subscription channels, constrained by 12-18 month equipment lead times that throttle capacity scaling.
- Air-Dried:Controlled thermal drying between 40°C and 80°C achieves shelf stability with moderate nutrient retention at accessible price points. United States secondary markets and price-sensitive dog owners are expanding fastest as hybrid processing techniques narrow quality gaps with freeze-dried alternatives.
- Dehydrated Raw:Minimal processing preserves raw ingredient integrity through low-temperature moisture reduction. Cat owners seeking ancestral diet positioning represent the core constituency.
- Cooked Dehydrated:Pre-cooking eliminates pathogen risks before dehydration, aligning with FDA preventive control requirements for thermally treated formulations. Mass-market retail penetration concentrates this segment.
Freeze-dried dominates installed base. Air-dried is where expansion concentrates.
Ingredient Type:
Cost tier stratification separates commodity-driven formulations from premium protein sourcing, with margin compression most acute in grain-free positioning that has matured into baseline expectation.
- Meat-based:USDA-inspected protein sources anchor premium positioning through human-grade supply chain integration. United States dog owners and direct-to-consumer subscription models concentrate demand, though livestock commodity volatility exposes margin stability.
- Grain-free:Elimination of corn, wheat, and soy responds to digestive sensitivity concerns among cat and dog owners. California and Texas specialty retail channels show saturation as positioning shifts from differentiator to table stakes.
- Vegetables:Sweet potato, pumpkin, and pea formulations address fiber and micronutrient supplementation. Small pet and bird owners in United States urban clusters drive niche adoption.
- Fruits:Cranberry, blueberry, and apple inclusions target antioxidant and urinary health positioning. Premium cat formulations in veterinary-adjacent channels represent primary uptake.
Meat-based commands revenue concentration. Grain-free is where competitive pressure intensifies most acutely.
End User:
Species-specific nutritional requirements dictate formulation complexity, with canine formulations permitting greater ingredient flexibility than feline obligate carnivore constraints.
- Dog Owners:Omnivore digestive capacity supports diverse protein and carbohydrate combinations across all preservation formats. United States direct-to-consumer channels and subscription models show deepest penetration, with premiumization trends accelerating fastest in this cohort.
- Cat Owners:Taurine and arachidonic acid requirements mandate animal-derived ingredient dominance, limiting vegetarian formulation options. Veterinary clinic channels and prescription-adjacent positioning command price premiums.
- Small Pets:Rabbit, guinea pig, and hamster formulations emphasize hay-based fiber content and controlled calcium ratios. Specialty pet retailers in United States metropolitan markets concentrate distribution.
- Birds:Seed, pellet, and dried fruit combinations target species-specific beak morphology and foraging behavior. Niche positioning limits scale economics.
Dog owners anchor volume scale. Cat owners concentrate margin extraction.
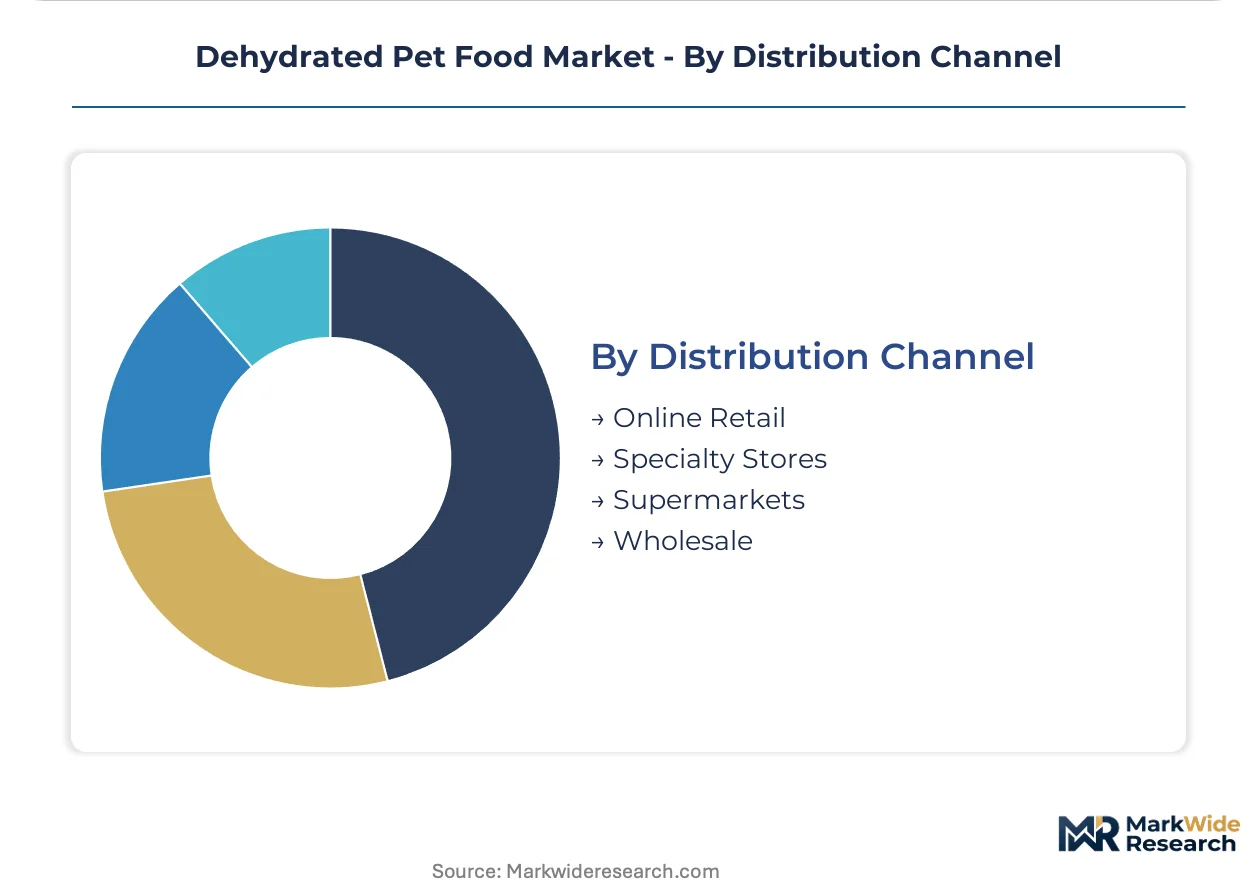
Distribution Channel:
Customer acquisition economics favor recurring revenue models over transactional retail, with channel selection directly determining lifetime value and switching cost architecture.
- Online Retail:Chewy and brand-owned platforms capture subscription relationships with automated replenishment and personalized formulation recommendations. United States coastal metros with delivery density advantages show strongest unit economics.
- Specialty Stores:Independent pet retailers and regional chains provide tactile product evaluation and staff consultation. California and Texas state certification requirements filter assortment toward compliant manufacturers.
- Supermarkets:Mass-market shelf placement competes on convenience and price accessibility through Mars Inc. and conglomerate brand portfolios. Air-dried and cooked dehydrated formats dominate this tier.
- Wholesale:Bulk procurement by veterinary clinics, breeders, and kennel operations emphasizes cost efficiency over premium positioning. Freeze-dried penetration remains limited due to price sensitivity.
Online retail is gaining share fastest. Specialty stores retain premium brand incubation function.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export dehydrated pet food formulations to Canadian and European buyers seeking cold-chain-free alternatives. This trade corridor channels premium freeze-dried products toward veterinary clinics and subscription platforms in destination markets.
United States
Direct-to-consumer subscription models and specialty retail penetration drive demand concentration in coastal metropolitan markets. FDA Food Safety Modernization Act preventive controls mandate hazard analysis for animal food facilities, professionalizing manufacturing standards. California and Texas state facility certification requirements create geographic concentration risk for production capacity expansion.
Germany
Veterinary channel endorsement and premium pet humanization trends accelerate adoption among dog owners in urban centers. EFSA novel food approval pathways for insect protein and cultivated meat ingredients create regulatory precedent that manufacturers monitor for domestic framework adaptation. The Rhine-Ruhr industrial corridor hosts processing facilities serving Central European distribution networks.
United Kingdom
Online retail channel migration and recurring revenue platform growth displace traditional specialty store relationships. FSA enforcement of feed hygiene regulations and post-Brexit import certification requirements constrain cross-border sourcing flexibility. Greater London and Southeast England concentrate demand through delivery-density advantages and premium consumer demographics.
Japan
Small living spaces and refrigeration constraints favor shelf-stable formulations among urban cat and dog owners. METI standards for pet food quality labeling and import quarantine protocols filter foreign supplier participation. The Kanto region around Tokyo anchors consumption volume through high pet ownership rates and premium positioning acceptance.
Australia
Raw feeding movement persistence and biosecurity-conscious formulation preferences support dehydrated alternatives to frozen products. Department of Agriculture biosecurity import permits and AQIS inspection protocols constrain ingredient sourcing from non-approved countries. New South Wales and Victoria concentrate manufacturing capacity near major population centers and export ports.
Dehydrated Pet Food Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass-market conglomerates leverage shelf-stable distribution networks while premium specialists capture veterinary and subscription revenue streams. Two archetypes dominate: vertically integrated human-grade ingredient sourcers and freeze-dried technology specialists. Competitive moves center on capacity scaling through equipment procurement and strategic partnerships for novel protein supply security.
Among publicly traded consumer goods conglomerates, Mars Inc. and Nestle Purina occupy positions representing mass-market scale advantages. Within the premium independent tier, The Honest Kitchen exemplifies human-grade supply chain integration archetypes. Stella & Chewy's represents freeze-dried specialization positioning. These anchors illustrate how competitive positioning fragments between convenience-driven volume players and nutrient-retention-focused premium specialists.
| Leading Market Players |
|---|
| Mars Inc. |
| Nestle Purina |
| Blue Buffalo |
| Diamond Pet Foods |
| Heristo |
| The Honest Kitchen |
| Stella & Chewy's |
| Affinity Petcare |
| Grandma Lucy's |
| Others |
Supply Flow & Price Mechanics
California's Central Valley processing corridor anchors North American dehydrated pet food capacity, with facility density in Fresno and Modesto counties creating localized sourcing leverage that compresses ingredient transport costs and amplifies margin capture for operators with captive supply arrangements. This geographic concentration funnels pricing power toward vertically integrated manufacturers while exposing regional buyers to freight cost volatility when sourcing outside the cluster.
Pricing Analysis
Freeze-dried formulations command a three-to-four-fold premium over air-dried alternatives due to vacuum chamber capital intensity and extended processing cycles, while hybrid processing techniques are collapsing the mid-market price gap. Price differentiation hinges on USDA human-grade certification tier and veterinary channel endorsement, with prescription-adjacent positioning extracting maximum willingness-to-pay. Cost compression in air-dried tiers is intensifying because livestock commodity volatility exposes margins at volume scale. Mass-market retail buyers exhibit highest price sensitivity, whereas subscription-based direct-to-consumer adopters prioritize nutrient retention metrics over per-unit cost.
Supply Chain Analysis
Tariff exposure between the United States and key protein-exporting nations dominates supply chain risk planning, with Australian beef and New Zealand lamb shipments facing periodic quota constraints. Manufacturing capacity concentrates in the United States, Canada, and Germany, with raw material sourcing drawing from USDA-inspected slaughterhouses, novel protein cultivation facilities, and spray-dried plasma operations. Single-source vulnerability in specialized freeze-drying equipment procurement creates 12-18 month capacity scaling bottlenecks. Distribution runs through direct-to-consumer subscription platforms, veterinary clinic networks, and mass-market retail tiers with diverging margin profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dehydrated pet food is approaching a platform-economics inflection where subscription data interoperability between Chewy and independent brand platforms will determine customer lifetime value capture, with veterinary practice management software integration emerging as the critical ecosystem battleground.
For Market Incumbents: Insulate premium positioning through backward integration into human-grade ingredient sourcing and captive freeze-drying capacity expansion in Texas to offset California regulatory concentration risk. Mars Inc. and Nestle Purina must defend against specialist encroachment by locking veterinary clinic formulary relationships before prescription-adjacent positioning hardens into switching costs. For New Entrants and Emerging Players: Pursue white-space penetration in cat owner segments where taurine-fortified freeze-dried formulations remain underdeveloped relative to canine saturation, with Japan and United Kingdom coastal metros offering highest delivery-density subscription economics. A veterinary endorsement-first go-to-market angle bypasses mass-market retail slotting fee barriers. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription platform ownership captures data assets that compound switching costs beyond product differentiation alone. Acquisition targets should demonstrate freeze-dried technology specialization plus direct-to-consumer channel control. The signal to watch is veterinary practice management software partnership announcements as integration precedes formulary lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Prescription-adjacent endorsement through Chewy Vet and independent clinic networks commands price premiums. |
| Freeze-Drying Capacity Expansion | Vacuum chamber procurement in Texas diversifies geographic risk beyond California certification burdens. |
| Human-Grade Supply Integration | USDA-inspected facility backward integration secures protein sourcing against livestock commodity volatility. |
| Novel Protein Regulatory Dossier | FDA Center for Veterinary Medicine approval for insect and cultivated ingredients opens formulation differentiation. |
| Subscription Platform Data Asset | Automated replenishment algorithms on brand-owned sites deepen lifetime value beyond retail transactional economics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pet food manufacturing executives, FDA preventive controls qualified individuals, veterinary clinic procurement managers, direct-to-consumer platform operators, and specialty retail category buyers. Secondary validation drew from FDA Food Safety Modernization Act facility inspection records, USDA organic certification databases, Association of American Feed Control Officials nutrient profiles, and Chewy subscription disclosure filings. Bottom-up capacity modeling triangulated against top-down retail audit data from coastal United States metropolitan markets.
Calibration against historical capacity utilization rates and protein commodity price cycles anchored volume and value projections across the analysis window. Segmentation dimensions modeled include preservation technology tier, ingredient sourcing certification level, species-specific nutritional requirements, and distribution channel type. CAGRs were derived from regression analysis of premiumization trend velocity and subscription penetration curves, with freeze-drying equipment lead times and state-level facility certification timelines incorporated as supply-side constraints.
Sensitivities concentrate around FDA novel protein approval timelines, livestock disease outbreaks affecting human-grade supply chains, and veterinary channel consolidation altering prescription-adjacent access economics. Forecasts reflect assumptions about sustained premiumization willingness-to-pay and cold-chain-free distribution expansion into secondary retail tiers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Transporting Service Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
United Kingdom Cat Litter Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Dog Safety Leash Market
Pet Care Products
UK Pet Grooming Market
Pet Care Products
Pet Gadgets Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Pet Calming Products Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
Saudi Arabia Pet Food Market