
 Small Breed Dog Food Market | 2026-2036
Small Breed Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Small Breed Dog Food Market Analytics
Veterinary nutritionist shortages across major pet food manufacturing regions are reorganizing how brands approach product development and claims substantiation. Mars Petcare leverages its in-house veterinary research network to sustain formulation credibility across premium small breed lines. Nestlé Purina PetCare anchors its competitive stance through dedicated kibble geometry research optimized for toy and miniature breed jaw structures. Hill's Pet Nutrition differentiates by controlling prescription-grade small breed formulations distributed through veterinarian clinics.
Small breed dog food encompasses nutritionally complete diets engineered for dogs under twenty pounds, with kibble dimensions typically ranging from seven to ten millimeters and elevated caloric density per cup to match accelerated metabolic rates. These formulations address dental health challenges, digestive sensitivities, and blood sugar stability specific to compact canine physiology. Dry kibble commands the largest volume share due to shelf stability and cost efficiency, while freeze-dried segments capture disproportionate margin pools through raw-nutrition positioning. The grain-free ingredient source category faces structural recalibration as veterinary cardiologists link certain formulations to dilated cardiomyopathy risk, redirecting R&D investment toward hydrolyzed protein and ancient grain alternatives.
The FDA Center for Veterinary Medicine monitors manufacturing safety through Food Safety Modernization Act compliance requirements, while AAFCO establishes nutrient adequacy benchmarks that determine whether products qualify as complete diets. The EU's Feed Hygiene Regulation and FEDIAF nutritional guidelines shape market access for imported small breed formulations across European member states. Stakeholders must track evolving regulatory postures on novel protein sources and sustainability labeling claims as these frameworks mature.
Market Dynamics
AAFCO's tightening nutrient profiles are compressing formulation flexibility across North American small breed lines, forcing manufacturers to rebuild recipes around hydrolyzed proteins and ancient grains while maintaining palatability thresholds for toy breed consumers.
Growth Catalysts
- Metabolic Rate Engineering:Veterinary nutritionists are calibrating caloric density per cup to match accelerated small breed metabolism, creating distinct product tiers for toy versus miniature classifications.
- FDA FSMA Compliance Infrastructure:Manufacturers investing in preventive controls for raw material streams are capturing shelf placement in premium retail channels that demand documented safety protocols.
- Urban Household Concentration:Metropolitan apartment dwellers in dense US cities are driving volume for compact-packaging formats suited to limited storage spaces.
Market Restraints
- Novel Protein Input Volatility:Insect and cultivated meat protein costs fluctuate wildly, constraining R&D budgets for alternative ingredient pipelines.
- Veterinary Nutritionist Scarcity:The shallow talent pool across major pet food manufacturing regions limits substantiation of health claims and slows new product timelines.
- DCM-Linked Grain-Free Retrenchment:Veterinary cardiologist findings linking certain formulations to dilated cardiomyopathy have triggered costly reformulation cycles and inventory write-downs.
Strategic Opportunities
- Veterinary Clinic Channel Expansion:Prescription-grade small breed formulations distributed through licensed practitioners command premium pricing and build switching costs.
- Freeze-Dried Raw Positioning:Raw-nutrition segments capture disproportionate margin pools as affluent owners seek ancestral diet narratives for companion animals.
- EU FEDIAF Alignment:Manufacturers harmonizing with European nutritional guidelines unlock cross-border access across member states with unified formulation platforms.
Industry Challenges
- Kibble Geometry R&D Talent Gap:Specialized engineers capable of optimizing seven-to-ten millimeter dimensions for toy breed jaw mechanics command scarce compensation premiums.
- Dual Certification Timelines:Simultaneous AAFCO adequacy validation and state feed control approvals extend time-to-market by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Breed Dog Food Market |
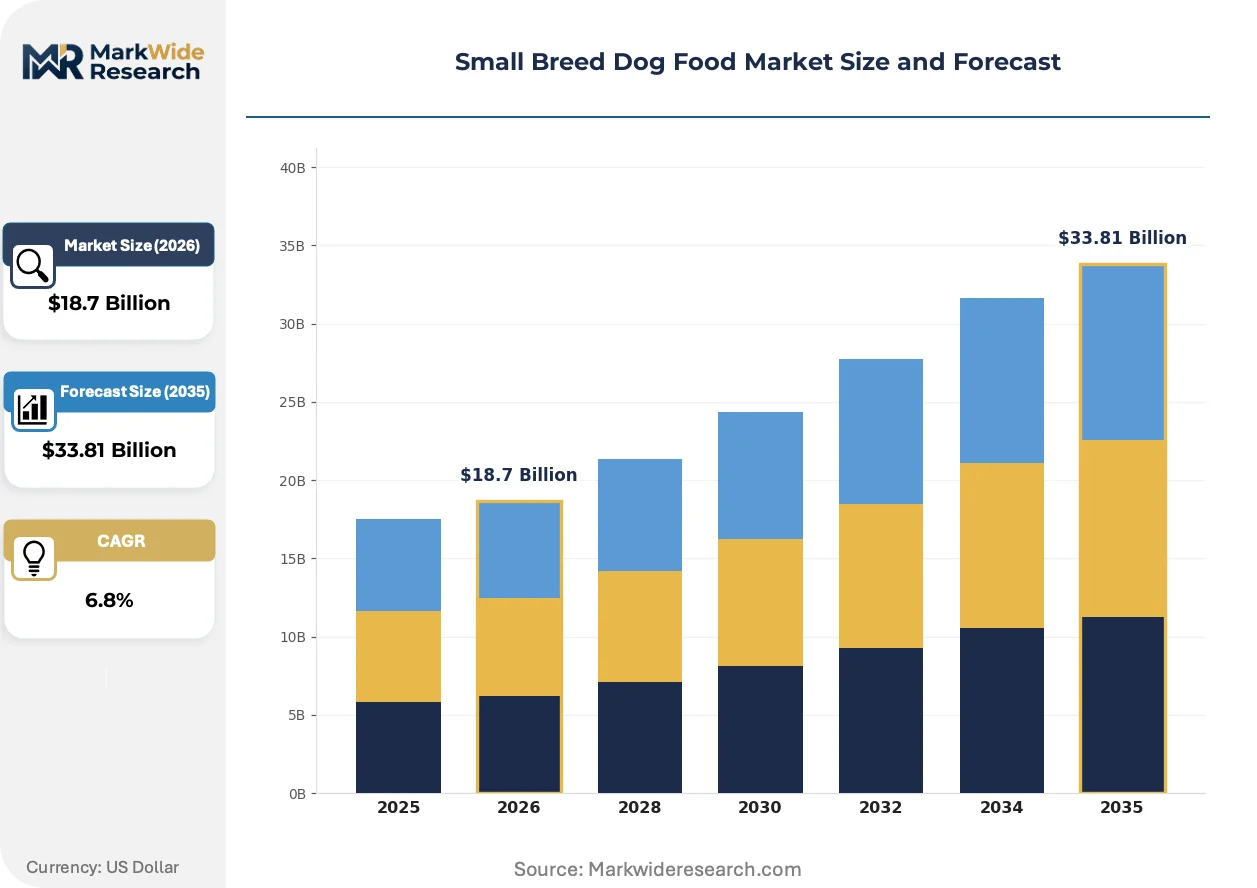
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Kibble, Wet Food, Freeze-dried, Treats Ingredient Source: Organic, Grain-free, High-protein, Hydrolyzed Packaging Type: Bags, Cans, Pouches, Bulk Distribution Channel: Online Retailers, Pet Specialty Stores, Supermarkets, Veterinarian Clinics |
| Companies Covered | Mars Petcare, Nestlé Purina PetCare, Hill's Pet Nutrition, General Mills, Spectrum Brands Holdings, Blue Buffalo, The J.M. Smucker Company, Diamond Pet Foods, Wellness Pet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Breed Dog Food Market Evolving Landscape
Ingredient sourcing transparency and metabolic customization are displacing one-size-fits-all formulations across small breed portfolios. Manufacturers now compete on physiological specificity rather than brand heritage alone.
Cold-pressed manufacturing is fragmenting thermal processing conventions in premium small breed production. Boutique manufacturers in Colorado and Oregon are adopting extrusion alternatives that preserve enzyme activity and reduce starch gelatinization. This technology is fragmenting the premium tier into raw-adjacent and minimally processed sub-segments with divergent margin structures.
The EU's Feed Hygiene Regulation is tightening manufacturing facility standards for imported small breed formulations entering European distribution. Non-EU manufacturers must demonstrate HACCP-equivalent protocols and veterinary oversight documentation. North American exporters are consolidating production in EU-registered facilities to avoid border inspection delays.
Subscription replenishment models are capturing recurring revenue from metropolitan small breed owners who prioritize convenience over retail browsing. Direct-to-consumer platforms in dense US urban corridors now bundle veterinary telehealth consultations with scheduled food deliveries. This channel shift is most visible in Manhattan, San Francisco, and Seattle apartment markets where storage constraints favor just-in-time fulfillment.
Small Breed Dog Food Market Segmentation
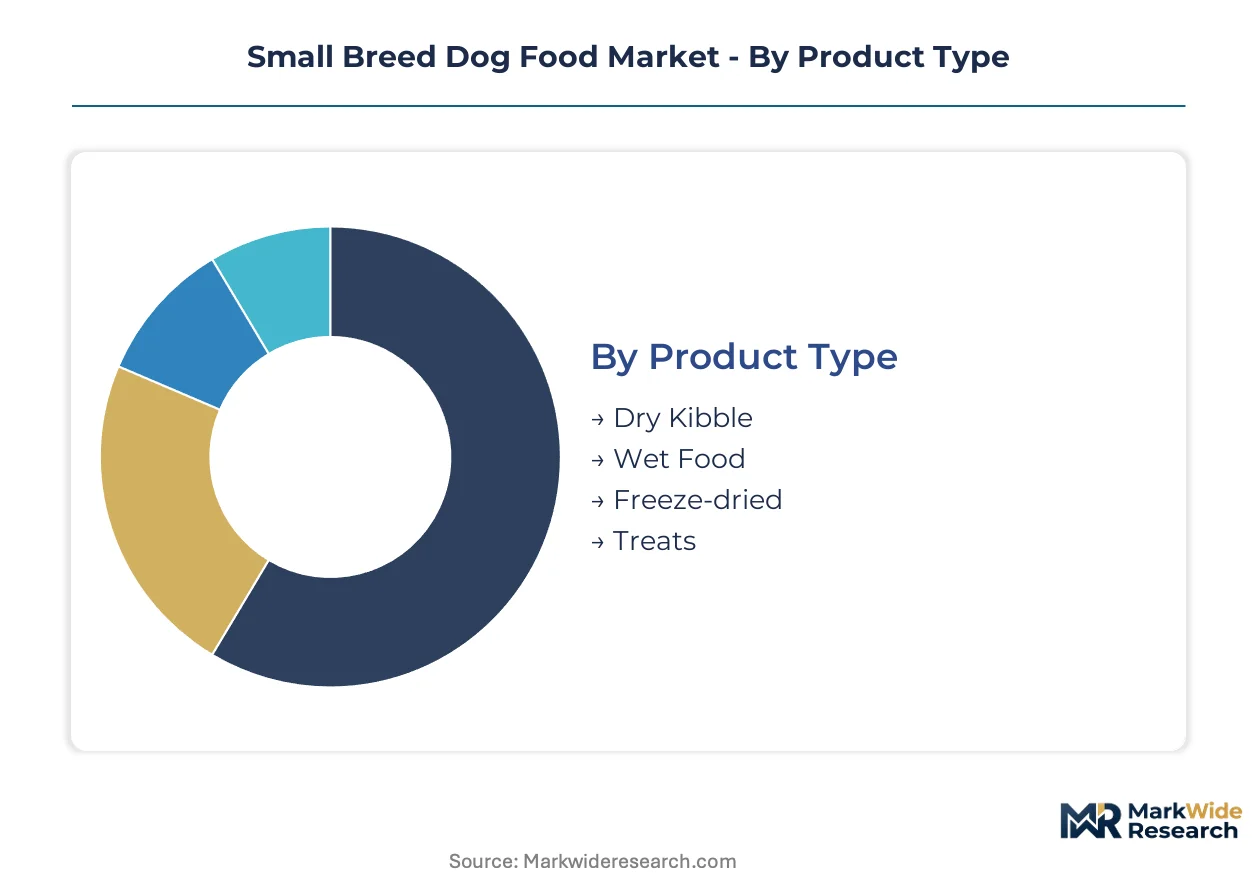
Small breed dog food segmentation reflects divergent metabolic needs, storage constraints in urban apartments, and channel-specific purchasing behaviors. Manufacturers calibrate formulations, packaging formats, and distribution strategies to match distinct owner profiles from subscription-driven millennials to veterinarian-guided prescription buyers.
Product Type:
Dry kibble dominates mass retail and subscription replenishment channels, while freeze-dried and wet formats concentrate in pet specialty stores and veterinary clinics where staff can explain nutritional positioning.
- Dry Kibble:Seven-to-ten millimeter kibble dimensions engineered for toy breed jaw mechanics deliver shelf-stable convenience at lower per-serving cost. Metropolitan apartment dwellers in dense US cities favor compact packaging formats suited to limited storage spaces, driving volume through online retailers and mass merchandisers.
- Wet Food:Higher moisture content addresses hydration needs in small breeds prone to urinary tract sensitivities, with single-serve pouches capturing convenience-oriented urban owners. Veterinary clinics stock therapeutic wet formulations for post-surgical recovery and appetite stimulation in geriatric toy breeds.
- Freeze-dried:Raw-nutrition positioning captures affluent owners seeking ancestral diet narratives through pet specialty stores and direct-to-consumer platforms.
- Treats:Functional dental and training varieties concentrate in impulse-buy channels near checkout counters.
By volume, dry kibble leads. By growth pace, freeze-dried is expanding most quickly.
Ingredient Source:
Cost tier stratification separates premium-positioned organic and hydrolyzed formulations from mass-market grain-free and high-protein alternatives, with margin compression forcing R&D investment toward veterinary-endorsed ingredient technologies.
- Organic:Certified ingredient chains command shelf placement in premium natural retailers and subscription services targeting sustainability-conscious owners. USDA organic verification requirements limit supplier pools, constraining scale and elevating price points relative to conventional alternatives.
- Hydrolyzed:Protein molecular weight reduction eliminates allergenic epitopes, positioning these formulations in veterinary clinics for elimination diet protocols and atopic dermatitis management. AAFCO tightening of nutrient profiles accelerates manufacturer migration toward hydrolyzed alternatives as grain-free formulations face DCM-linked reputational damage.
- Grain-free:Veterinary cardiologist findings linking certain formulations to dilated cardiomyopathy trigger costly reformulation cycles and inventory write-downs across mass retail channels.
- High-protein:Elevated meat inclusion percentages concentrate in performance-oriented small breeds and owner segments prioritizing ancestral feeding models.
By volume, high-protein leads. By margin capture, hydrolyzed is climbing the fastest.
Packaging Type:
Format selection tracks household storage capacity and purchase frequency, with single-serve and bulk options diverging across urban density gradients and multi-pet versus single-pet households.
- Pouches:Flexible single-serve formats dominate wet food distribution in convenience-oriented channels and veterinary clinic sample programs. Manhattan, San Francisco, and Seattle apartment markets favor just-in-time fulfillment of compact formats that minimize refrigeration footprint.
- Bags:Multi-layer barrier films protect dry kibble from oxidation in climate-variable storage environments, with resealable closures capturing recurring purchasers in pet specialty and mass retail.
- Cans:Metal packaging preserves wet food sterility for extended shelf life in stock-up purchasing patterns.
- Bulk:Refill stations and large-format bags serve multi-pet households and sustainability-focused buyers reducing packaging waste.
By volume, bags lead. By channel expansion, pouches are gaining share fastest.
Distribution Channel:
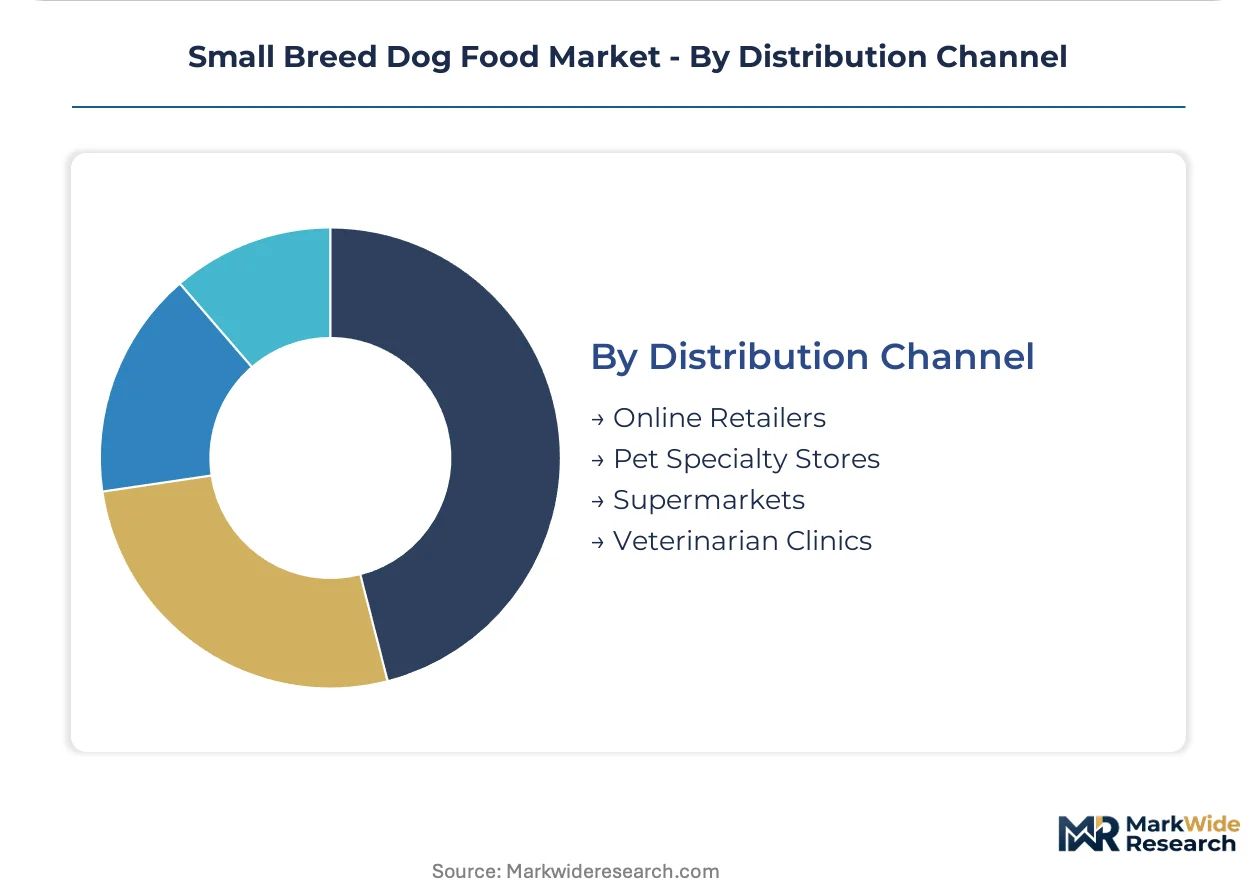
Customer type and purchase occasion determine channel selection, with convenience-seeking urban millennials diverging from veterinarian-guided therapeutic buyers and price-sensitive stock-up shoppers.
- Online Retailers:Subscription replenishment models capture recurring revenue through scheduled delivery bundled with veterinary telehealth consultations. Direct-to-consumer platforms in dense US urban corridors leverage data analytics to personalize formulation recommendations based on breed-specific metabolic profiles.
- Veterinarian Clinics:Prescription-grade small breed formulations distributed through licensed practitioners command premium pricing and build switching costs through professional endorsement. Hill's Pet Nutrition and Mars Petcare leverage in-house veterinary research networks to secure clinic shelf placement for therapeutic lines.
- Pet Specialty Stores:Staff expertise drives premium and freeze-dried trial in experiential retail environments.
- Supermarkets:Mass-market dry kibble concentrates in high-frequency grocery trips with impulse treat attachments.
By volume, supermarkets lead. By margin expansion, veterinarian clinics are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Small breed dog food consumption patterns diverge sharply across geographies. Urban apartment density in the United States drives demand for compact-packaging formats, while European markets prioritize regulatory-aligned formulations under FEDIAF guidelines. Asian markets exhibit faster adoption of freeze-dried raw segments despite higher price points.
United States
Metropolitan apartment dwellers in Manhattan, San Francisco, and Seattle favor just-in-time subscription fulfillment over bulk purchasing. FDA FSMA compliance infrastructure separates premium-channel manufacturers from mass-market competitors. Mars Petcare and Nestlé Purina PetCare anchor production networks across Midwestern states to serve dense coastal demand corridors.
Germany
Discerning owners in Berlin and Munich prioritize EU-registered facilities with HACCP-equivalent protocols for imported formulations. The country's national feed regulator enforces strict veterinary oversight documentation for non-EU products. Bavarian manufacturing clusters concentrate cold-pressed production for raw-adjacent premium segments.
United Kingdom
London's compact housing stock mirrors US urban demand for space-efficient packaging formats. Post-Brexit alignment with FEDIAF nutritional guidelines remains contested, creating formulation uncertainty for continental exporters. Midlands distribution hubs consolidate cross-channel logistics for specialty freeze-dried imports.
Japan
Tokyo's high-rise residential concentration generates comparable storage-constraint dynamics to Western metropolitan markets. METI standards for pet food manufacturing impose additional testing protocols beyond baseline FEDIAF requirements. Osaka-based specialty retailers drive trial of ancestral-diet positioning in affluent owner segments.
Australia
Melbourne and Sydney apartment markets exhibit rising small breed ownership among millennial professionals. TGA-equivalent veterinary oversight applies to therapeutic formulations distributed through clinic channels. Queensland production facilities increasingly serve export demand across Asia-Pacific markets with harmonized FEDIAF-aligned recipes.
Small Breed Dog Food Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in small breed dog food manufacturing. Three multinational conglomerates control prescription-grade distribution through veterinary clinics, while mid-scale specialists compete on cold-pressed manufacturing and novel protein sourcing. Strategic moves concentrate on clinic channel expansion and freeze-dried capacity additions rather than mass-market price competition.
Within the integrated leader tier, Mars Petcare and Nestlé Purina PetCare occupy positions defined by in-house veterinary research networks and dedicated kibble geometry capabilities. Hill's Pet Nutrition exemplifies the prescription-grade archetype through clinic-distributed therapeutic lines. Among mid-scale specialists, Blue Buffalo and Wellness Pet represent the premium-natural positioning vector competing on ingredient transparency claims.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| General Mills |
| Spectrum Brands Holdings |
| Blue Buffalo |
| The J.M. Smucker Company |
| Diamond Pet Foods |
| Wellness Pet |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Midwestern grain processors and major manufacturers lock in both supply access and price visibility for corn and soy inputs, insulating premium small breed lines from spot market volatility while compressing margins for competitors dependent on short-term procurement.
Pricing Analysis
Subscription-based pricing models dominate direct-to-consumer channels, with three-tier pricing structure across premium, standard, and economy levels separating veterinary-endorsed therapeutic formulations from mass-market alternatives. Price differentiation hinges on certification grade—AAFCO adequacy validation versus state feed control baseline compliance—and brand heritage in veterinary research networks. Cost compression in grain-free segments is intensifying because DCM-linked inventory write-downs force distressed liquidation. Mass-market grocery buyers exhibit highest price sensitivity; prescription-grade clinic purchasers show lowest elasticity.
Supply Chain Analysis
The United States and Canada anchor North American production of small breed formulations, with Midwestern states concentrating extrusion manufacturing and Pacific Northwest facilities pioneering cold-pressed alternatives. Raw material streams draw from domestic corn and soy cultivation, supplemented by hydrolyzed protein imports from EU-registered suppliers. Single-source vulnerability concentrates in veterinary nutritionist talent pools, where shallow availability constrains formulation innovation. Distribution runs through three parallel channels: veterinary clinics for prescription tiers, pet specialty stores for premium trial, and mass retail for volume replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The small breed dog food market exhibits cyclical recovery characteristics as urban millennial household formation accelerates post-pandemic, driving recurring subscription revenue from metropolitan apartment dwellers with storage-constrained purchasing patterns.
For Market Incumbents: Compound defensive moats by deepening in-house veterinary research networks to secure clinic channel shelf placement against emerging specialists. Accelerate backward integration into hydrolyzed protein processing to offset novel protein input volatility and capture margin pools currently leaked to third-party suppliers. Prioritize kibble geometry R&D talent retention through specialized compensation premiums that toy breed formulation competitors cannot match. For New Entrants and Emerging Players: Differentiate on cold-pressed manufacturing credentials in Pacific Northwest and Colorado production clusters, where raw-adjacent positioning commands disproportionate margins. Target the freeze-dried subscription segment in Manhattan, San Francisco, and Seattle apartment markets, where convenience-oriented millennials prioritize just-in-time fulfillment over brand heritage. Deploy veterinary telehealth bundling as the primary go-to-market angle to bypass entrenched retail shelf competition. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists with established EU FEDIAF alignment and existing cold-pressed capacity, as cross-border regulatory harmonization unlocks unified formulation platforms. Long-term viability over the next decade rests on clinic channel penetration depth rather than mass-market volume share. Watch AAFCO nutrient profile tightening timelines as the critical inflection signal for reformulation-driven consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Channel Expansion | Prescription-grade distribution through licensed practitioners commands premium pricing and builds switching costs through professional endorsement. |
| Freeze-Dried Capacity Addition | Raw-nutrition positioning in affluent urban markets captures disproportionate margin pools through ancestral diet narratives. |
| Hydrolyzed Protein Backward Integration | In-house processing of allergen-reduced ingredients insulates margins from novel protein input volatility and supply disruption. |
| EU FEDIAF Alignment Investment | Harmonized formulation platforms unlock cross-border access across member states without costly recipe duplication. |
| Kibble Geometry R&D Talent Acquisition | Specialized engineers optimizing seven-to-ten millimeter dimensions for toy breed jaw mechanics sustain palatability differentiation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with veterinary nutritionists, pet food manufacturing executives, clinic distribution managers, and subscription platform operators. Secondary validation drew from FDA Center for Veterinary Medicine compliance filings, AAFCO nutrient adequacy benchmarks, FEDIAF nutritional guidelines, and Nielsen retail audit data covering pet specialty and mass merchandiser channels. Bottom-up volume estimates from individual product lines were triangulated against top-down market sizing derived from household small breed ownership rates and per-pet consumption averages.
Across the projection horizon, the analytical framework modeled value and volume trajectories by product type, ingredient source, packaging format, and distribution channel, with additional segmentation by metropolitan density tier to capture urban apartment demand dynamics. CAGRs were derived from regression analysis against household formation trends, regulatory compliance cost indices, and channel shift velocities. Forecast inputs incorporated veterinary nutritionist hiring rates as a constraint variable and freeze-dried capacity expansion pipelines as a growth accelerant.
Material uncertainties — novel protein cost volatility, DCM-linked regulatory reversals, and veterinary nutritionist supply constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about AAFCO profile stability and EU FEDIAF harmonization progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Mink Oil Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Pet Apparel Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Smart Pet Collar Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Pet Water Fountain Market
Pet Care Products
Gcc Pet Food Market