
 Insoles Market | 2026-2036
Insoles Market Size, Share, and Industry Trends Forecast 2026-2036
Insoles Market Analytics
China is rewriting regional manufacturing dynamics for molded footbed production. Superfeet Worldwide leverages proprietary biomechanical shaping to sustain premium positioning in North American specialty retail. Bauerfeind AG anchors European medical distribution through certified orthotic fabrication. Dr. Scholl's dominates mass-market pharmacy channels with extensive retail shelf control.
Insoles are contoured inserts placed inside footwear to redistribute plantar pressure, correct gait abnormalities, or absorb impact shock; medical-grade variants incorporate thermoformable polypropylene shells calibrated to individual foot morphology. Foam-based constructions currently lead volume shipments due to cost scalability, while gel segments capture disproportionate margin pools in athletic and diabetic applications. Orthotic insoles command the highest unit economics where prescription workflows and insurance reimbursement apply.
ISO 13485 governs quality management for medical device insoles in Europe, while the FDA classifies prescription orthotics as Class I or II devices depending on therapeutic claims. REACH compliance constrains chemical formulations in EU-sold products, particularly for adhesives and synthetic leathers. Stakeholders must monitor evolving reimbursement codes and material restriction timelines to align R&D pipelines with regulatory access requirements.
Market Dynamics
Statutory insurance mandates for diabetic foot care are compressing clinical procurement cycles and forcing manufacturers to recalibrate fabrication workflows around reimbursement documentation rather than retail shelf velocity.
Growth Catalysts
- German Statutory Health Insurance Mandate:Diabetic foot care programs now require orthotic insole coverage, creating guaranteed payment rails for certified fabricators. This pulls volume from cash-pay retail into reimbursed clinical channels.
- Thermoformable Polypropylene Shells:Calibrated molding calibrated to individual foot morphology enables podiatrists to bill for custom-fitted devices rather than prefabricated inserts, expanding addressable margin pools per patient.
- US Sports Medicine Clinic Density:Referral networks in metropolitan markets concentrate demand for premium biomechanical correction, sustaining specialty retail price premiums despite mass-market commoditization pressure.
Market Restraints
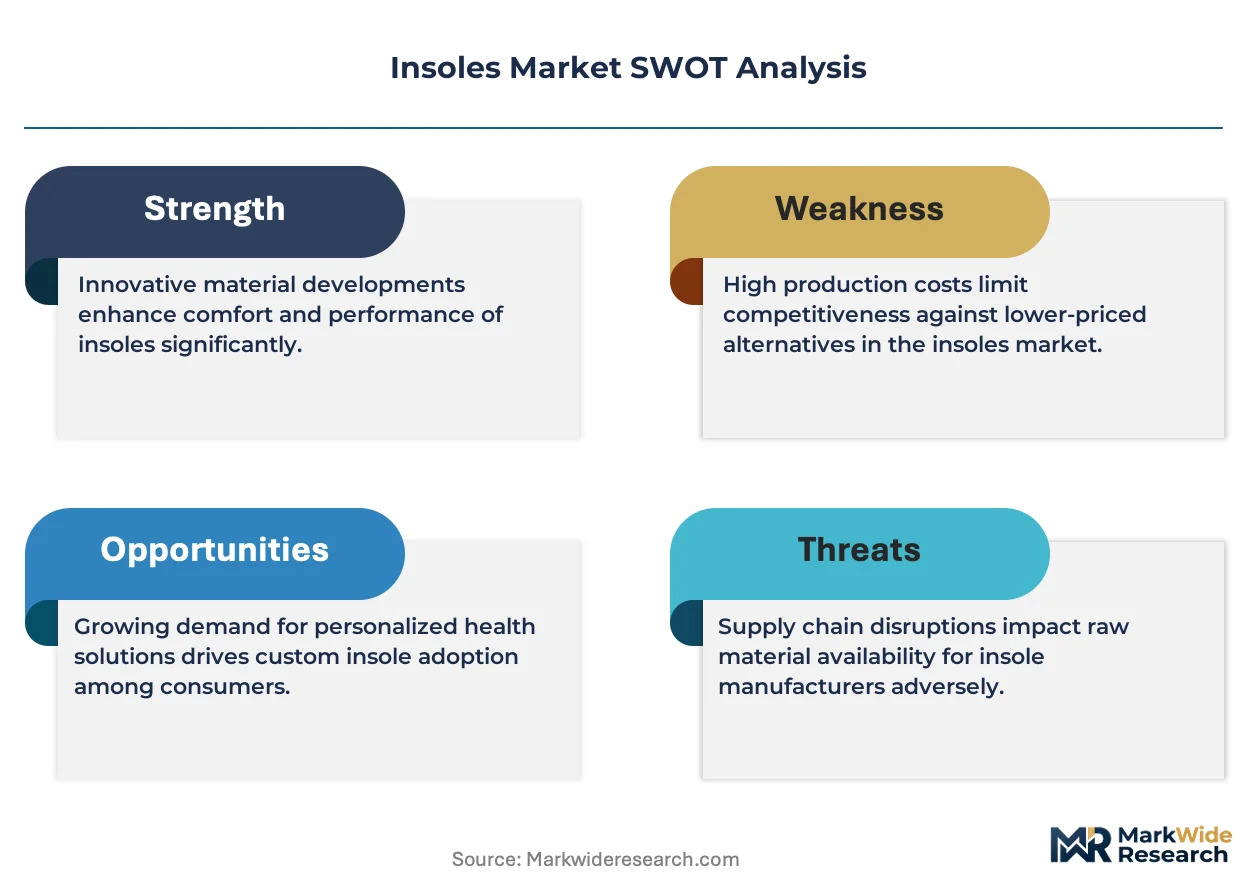
- REACH Chemical Formulation Constraints:ECHA restrictions on adhesives and synthetic leathers force reformulation of EU-bound products, extending R&D timelines and compressing gross margins on legacy SKUs.
- FDA Class I/II Device Classification:Prescription orthotics face therapeutic claim scrutiny that prefabricated wellness inserts avoid, creating regulatory friction for manufacturers straddling both segments.
- Petrochemical Input Volatility:Polypropylene and EVA foam feedstock prices track crude oil indices, exposing molders to margin compression that cannot be passed through to fixed-reimbursement clinical contracts.
Strategic Opportunities
- India's Underserved Diabetic Population:Rising diabetes prevalence without established orthotic reimbursement infrastructure creates first-mover advantage for manufacturers building direct-to-patient digital fitting platforms.
- EU Green Deal Material Incentives:Bio-based foam formulations qualify for accelerated regulatory review and public procurement preference, rewarding early movers in sustainable material substitution.
- Telehealth Gait Analysis Convergence:Smartphone pressure-mapping apps combined with remote podiatrist consultations enable prescription capture without brick-and-mortar clinic density, unlocking rural and exurban patient pools.
Industry Challenges
- ISO 13485 Certification Timeline:Medical device quality management system implementation requires 12-18 months of documented process validation before European market access, straining smaller fabricators' working capital.
- Biomechanist Talent Scarcity:Shortage of certified orthotic technicians capable of translating scan data into calibrated shell specifications limits production scaling for custom-fitted workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insoles Market |
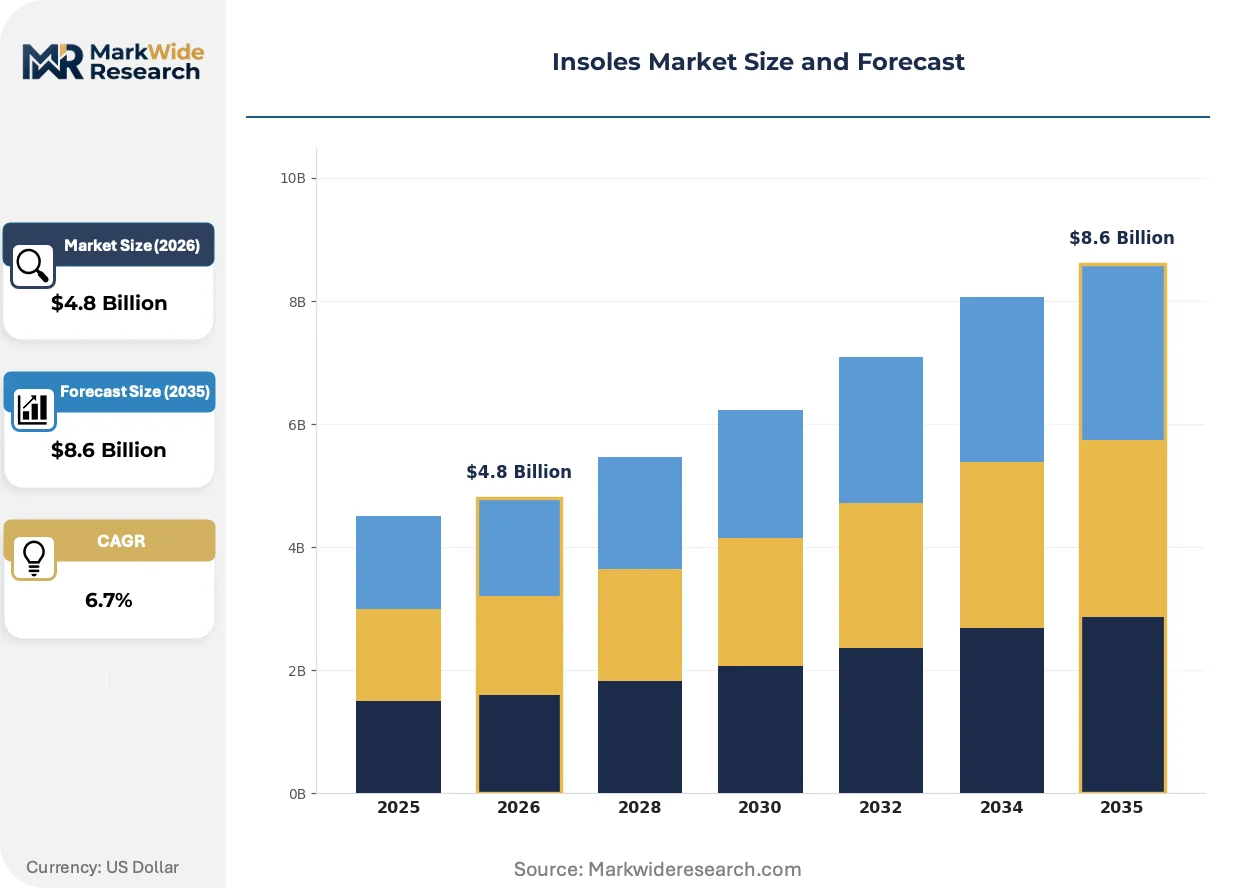
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic, Cushioned, Gel, Arch Support Material: Foam, Rubber, Leather, EVA End User: Athletes, Diabetics, General Consumers, Healthcare Professionals Application: Sports Footwear, Casual Footwear, Work Boots, Medical Footwear |
| Companies Covered | Dr. Scholl's, Superfeet Worldwide, PowerStep, Bauerfeind AG, Aetrex Worldwide, Foot Science International, Spenco Medical Corporation, Implus LLC, Vionic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insoles Market Evolving Landscape
Digital foot scanning and additive manufacturing are converging to compress the custom orthotic production cycle from weeks to days, threatening traditional plaster-cast fabrication networks.
Carbon fiber reinforced polymer shells are hybridizing with 3D-printed lattice midsoles in athletic applications. Marathon runners and professional cyclists now specify these constructions for gram-weight reduction without sacrificing torsional rigidity. The technology is hybridizing previously separate performance attributes—energy return and pronation control—into single-component architectures that displace multi-layer foam assemblies.
REACH chemical restriction timelines are forcing adhesive reformulation across EU-sold product lines. Manufacturers must phase out solvent-based bonding agents by specified deadlines or forfeit market access. Medical-grade insole producers with established thermoplastic welding capabilities bypass this constraint entirely, capturing share from competitors dependent on legacy chemical curing processes.
Direct-to-consumer fitting platforms are displacing pharmacy and specialty retail as the primary research and purchase channel for prefabricated inserts. Subscription models offering quarterly replacement shipments now dominate customer acquisition spend. This shift concentrates marketing investment in digital channels and compresses traditional wholesale relationships, with the United States exhibiting the most advanced channel migration.
Insoles Market Segmentation
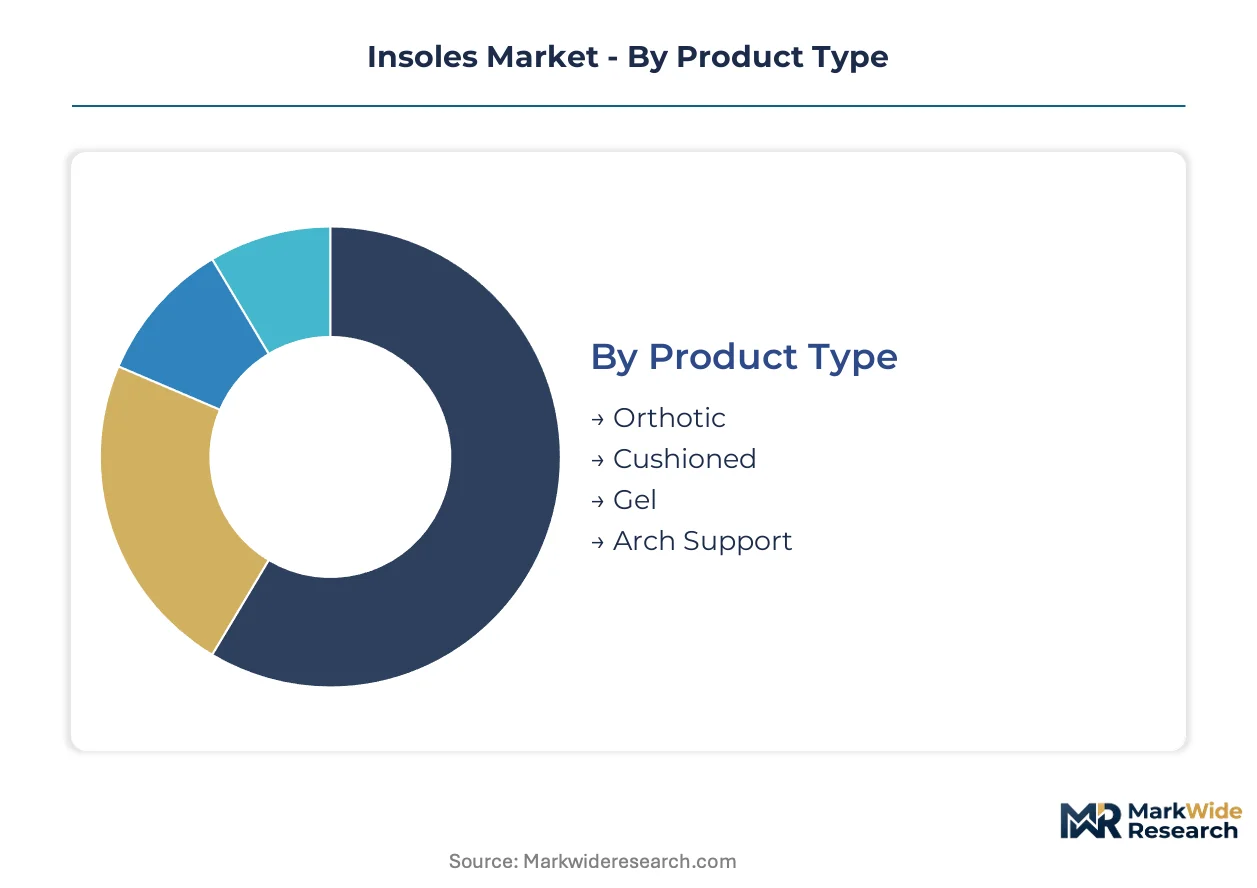
Segmentation in the insoles market determines fabrication workflows, margin structures, and channel strategy. Orthotic prescriptions carry reimbursement documentation requirements that cushioned retail inserts bypass entirely. Material selection and end-user targeting further stratify production economics across clinical versus consumer pathways.
Product Type:
Replacement cycles vary dramatically—athletic cushioned inserts turn over quarterly while prescription orthotics persist for years. Manufacturers must calibrate inventory velocity and customer lifetime value models to these divergent rhythms.
- Orthotic:Thermoformable polypropylene shells calibrated to individual foot morphology enable podiatrists to bill for custom-fitted devices. German statutory health insurance mandates now guarantee payment rails, pulling volume from cash-pay retail into reimbursed clinical channels with extended procurement cycles.
- Cushioned:Multi-density foam constructions absorb impact shock for high-frequency replacement regimes. Demand concentrates in United States sports medicine referral networks where marathon runners and recreational athletes drive quarterly replenishment through specialty retail and direct-to-consumer subscription platforms.
- Gel:Viscous polymer formulations redistribute plantar pressure in diabetic applications.
- Arch Support:Semi-rigid constructions correct pronation abnormalities in mass-market pharmacy channels.
Orthotic anchors the volume base while cushioned gains share at the steepest rate.
Material:
Cost tiers separate commodity feedstocks from performance-engineered compounds. EVA and basic foam compete on scale economies while rubber and leather command specialty positioning.
- Foam:Open-cell polyurethane and closed-cell polyethylene constructions dominate shipment volumes through cost scalability. REACH chemical restrictions on adhesives force reformulation of EU-bound product lines, compressing gross margins on legacy SKUs while rewarding thermoplastic welding capabilities.
- EVA:Ethylene-vinyl acetate copolymers deliver tunable durometer ratings for athletic energy return specifications. Petrochemical input volatility tracks crude oil indices, exposing molders to margin compression that cannot be passed through to fixed-reimbursement clinical contracts.
- Rubber:Natural and synthetic latex formulations provide durability in work boot applications.
- Leather:Vegetable-tanned hides serve premium casual footwear with moisture management properties.
Foam captures the widest addressable base while EVA demonstrates the most rapid climb in absolute tonnage.
End User:
Customer type dictates channel configuration and pricing architecture. Healthcare professionals route through reimbursement workflows while athletes and general consumers respond to direct marketing.
- Diabetics:Medical-grade insoles with pressure-mapping certification prevent ulcer formation and amputation. Germany now mandates orthotic coverage under statutory health insurance, accelerating clinical-grade adoption with guaranteed payment rails distinct from retail shelf velocity.
- Athletes:Carbon fiber reinforced polymer shells hybridized with 3D-printed lattice midsoles specify gram-weight reduction without torsional rigidity sacrifice. Marathon runners and professional cyclists in United States metropolitan markets drive premium biomechanical correction demand.
- General Consumers:Prefabricated inserts purchased through pharmacy and mass retail channels.
- Healthcare Professionals:Podiatrists and orthotists prescribing calibrated devices with ISO 13485 documentation.
Diabetics anchor the reimbursement-driven segment while athletes expand most quickly through performance innovation.
Application:
Footwear category determines durability specifications and replacement frequency. Medical and work applications prioritize longevity while sports and casual segments emphasize comfort refresh.
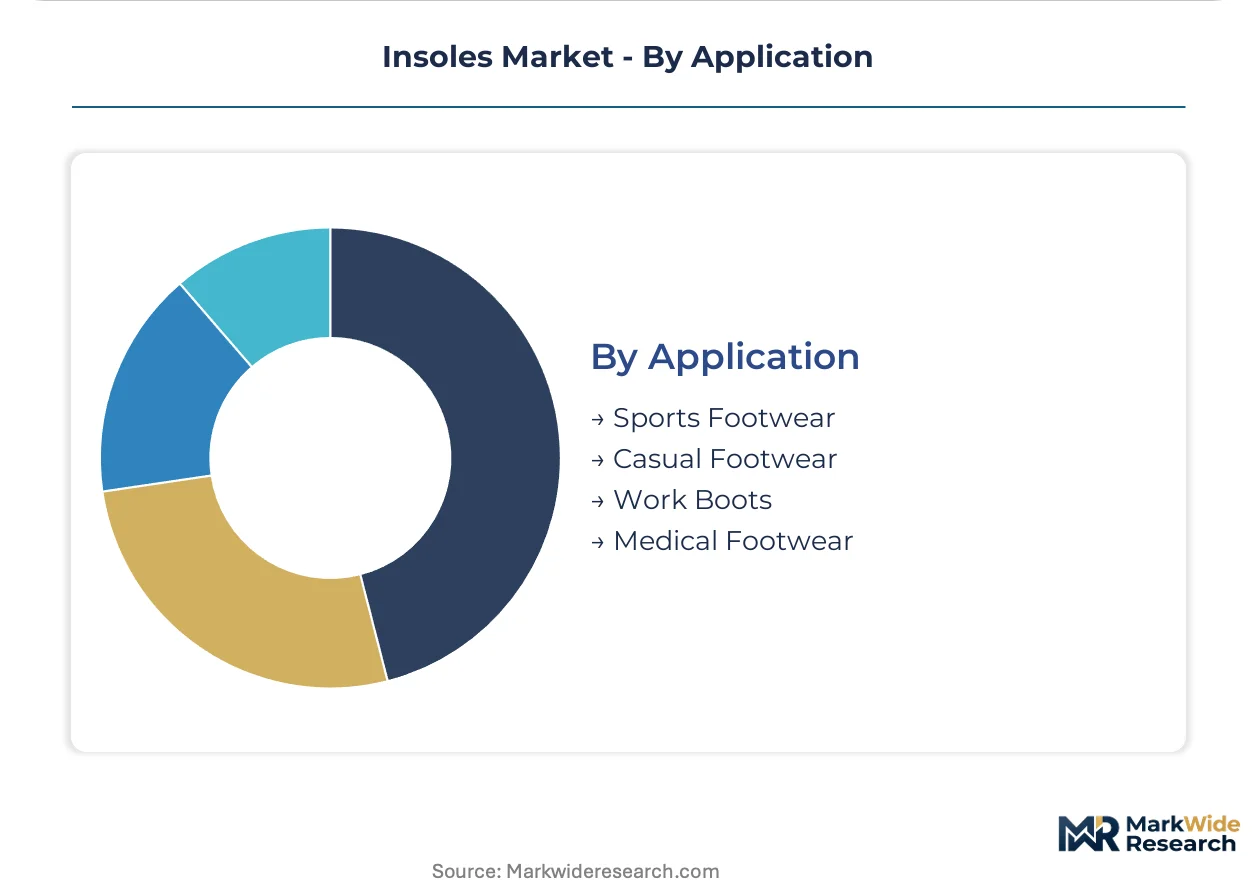
- Sports Footwear:Energy return and pronation control hybridized into single-component architectures displace multi-layer foam assemblies. Carbon fiber reinforced polymer shells with 3D-printed lattice midsoles now specify gram-weight reduction for marathon runners and professional cyclists.
- Medical Footwear:Pressure redistribution and ulcer prevention drive thermoformable polypropylene shell fabrication. ISO 13485 quality management governs European market access with 12-18 month certification timelines straining smaller fabricators' working capital.
- Work Boots:Impact absorption and fatigue reduction for industrial safety compliance.
- Casual Footwear:Comfort enhancement through gel and cushioned constructions in mass retail.
Medical footwear anchors the highest-margin application tier while sports footwear demonstrates the steepest technology-driven expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA therapeutic claim classifications in the United States create the regulatory anchor for prescription orthotic workflows, while ECHA REACH restrictions and German statutory insurance mandates reshape European clinical procurement patterns.
United States
Podiatry referral networks in metropolitan markets concentrate demand for premium biomechanical correction. FDA Class I/II device classifications subject prescription orthotics to therapeutic claim scrutiny that prefabricated wellness inserts avoid. Boston and Minneapolis anchor sports medicine clinic density that sustains specialty retail price premiums.
Germany
Statutory health insurance mandates now require orthotic insole coverage under diabetic foot care programs. ISO 13485 quality management certification governs European market access with documented process validation requirements. The Rhine-Ruhr and Bavarian industrial clusters host certified fabrication facilities serving reimbursed clinical channels.
China
Regional manufacturing dynamics for molded footbed production are rewriting supply chain configurations. NMPA medical device regulations and GB standards govern domestic market access for clinical-grade products. The Yangtze River Delta and Pearl River Delta concentrate thermoformable polypropylene shell production capacity.
India
Rising diabetes prevalence without established orthotic reimbursement infrastructure creates first-mover positioning for direct-to-patient digital fitting platforms. CDSCO medical device regulations frame import and domestic manufacturing compliance pathways. Maharashtra and Karnataka anchor emerging fabrication capacity for export-oriented and domestic clinical supply.
Japan
PMDA medical device classifications align with aging demographics driving pressure-mapping certification demand for ulcer prevention. METI industrial standards and JIS specifications govern material quality and manufacturing process documentation. The Kanto and Kansai regions concentrate podiatry clinic networks prescribing calibrated custom-fitted devices.
Insoles Market Competitive Landscape
Medical-grade fabricators and mass-market consumer brands split the market along reimbursement and retail channel lines. The structure concentrates around certified orthotic producers with ISO 13485 documentation capabilities and high-velocity consumer goods suppliers with pharmacy shelf control. Three archetypes dominate: clinical-certified fabricators billing through insurance workflows, sports performance specialists commanding specialty retail premiums, and mass-market brands distributing through pharmacy and direct-to-consumer platforms. Competitive moves center on thermoformable shell fabrication capacity expansion and digital fitting platform development to capture telehealth-integrated prescription flows.
Within the clinical-certified tier, Bauerfeind AG and Superfeet Worldwide exemplify divergent geographic anchoring strategies. Dr. Scholl's occupies the mass-market pharmacy channel position with extensive retail shelf control. These three entities represent the archetype spectrum from European medical distribution through North American specialty retail to global consumer goods scale.
| Leading Market Players |
|---|
| Dr. Scholl's |
| Superfeet Worldwide |
| PowerStep |
| Bauerfeind AG |
| Aetrex Worldwide |
| Foot Science International |
| Spenco Medical Corporation |
| Implus LLC |
| Vionic |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port congestion during peak thermoformable polypropylene import windows compresses margin buffers for European clinical-grade fabricators, forcing price differentiation between ISO 13485-certified and uncertified production tiers.
Pricing Analysis
United States metropolitan markets sustain 40-60% premiums over German reimbursed channels due to cash-pay sports medicine workflows versus statutory insurance fixation. Three-tier pricing structure across premium carbon fiber athletic, standard thermoplastic medical, and economy foam retail levels separates segments by certification burden and replacement frequency. Pricing pressure stems from REACH adhesive reformulation costs that cannot pass through to fixed-reimbursement German contracts. General consumers through pharmacy channels exhibit highest price sensitivity, while podiatry-referred athletes demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta thermoforming specialists and Bavarian ISO 13485-certified fabrication clusters serving distinct regulatory pathways. Polypropylene resin and EVA foam feedstocks draw from Saudi and South Korean petrochemical complexes, with carbon fiber sheet anchored in Japanese Toray supply. Single-source vulnerability concentrates in medical-grade adhesive formulations facing ECHA phase-out deadlines. Distribution runs through hospital procurement committees for clinical devices and direct-to-consumer platforms for retail inserts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diabetic foot care reimbursement expansion in statutory insurance markets represents an early-cycle tailwind, with penetration rates in reimbursed clinical channels still below 15% of addressable diabetic populations.
For Market Incumbents: Pre-empt telehealth-integrated prescription capture by acquiring smartphone gait analysis platforms before digital-native entrants lock podiatrist referral relationships. Expand thermoformable shell capacity in Rhine-Ruhr clusters to absorb German statutory insurance volume surges. ISO 13485 certification depth serves as the defensive moat against Asian contract manufacturers seeking European market access. For New Entrants and Emerging Players: India's uninsured diabetic population with smartphone penetration above 75% represents the most penetrable entry point for direct-to-patient digital fitting platforms bypassing brick-and-mortar clinic infrastructure. Target United States exurban markets where sports medicine clinic density falls below metropolitan thresholds but telehealth reimbursement parity now applies. Go-to-market through Strava and Garmin ecosystem partnerships captures athlete segments without specialty retail shelf investment. For Investors and Strategic Acquirers: European medical-grade fabricators with established thermoplastic welding capabilities and pending EU Green Deal bio-foam certifications offer asymmetric upside as REACH restrictions eliminate adhesive-dependent competitors. Long-term viability hinges on reimbursement code expansion beyond diabetes into preventive podiatry. Monitor German statutory insurance utilization rate acceleration as the inflection signal for clinical channel volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Gait Analysis Platform Development | Smartphone pressure-mapping apps unlock rural prescription capture without clinic density investment. |
| Bio-Based Foam Formulation Transition | EU Green Deal incentives reward early movers in sustainable material substitution with accelerated regulatory review. |
| ISO 13485 Certification Acceleration | Twelve-month quality management validation timelines strain smaller fabricators' working capital and market access. |
| Direct-to-Consumer Subscription Launch | Quarterly replacement shipments concentrate customer acquisition spend in digital channels over wholesale relationships. |
| Carbon Fiber Shell Manufacturing Scale-Up | Gram-weight reduction specifications from marathon runners and professional cyclists drive premium tier expansion. |
Research Methodology
Cross-validation between podiatrist practice management systems and GPO procurement databases anchors the qualitative findings on prescription workflow economics. Primary interviews with certified orthotic technicians, hospital purchasing committee members, biomedical engineers, and sports medicine clinic directors combine with secondary validation from FDA 510(k) filings, EMA medical device registrations, CMS Medicare reimbursement code updates, and German statutory health insurance utilization reports. Bottom-up patient volume modeling and top-down pharmaceutical channel spend analysis triangulate market sizing.
Calibration against historical diabetic population growth rates and orthotic penetration benchmarks shapes the projection framework across product type, material composition, end-user segment, application category, and regional regulatory cluster dimensions. CAGRs derive from segmented adoption curve modeling with inputs including REACH chemical restriction phase-out timelines, telehealth reimbursement parity expansion, and thermoformable polypropylene shell production capacity utilization.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices affecting EVA foam feedstock costs or euro-dollar exchange rates impacting German export competitiveness would shift the trajectory. Forecasts reflect documented assumptions on reimbursement code stability and adhesive reformulation compliance deadlines. Quarterly review of German statutory insurance utilization rates, United States telehealth parity legislation, and ECHA restricted substance list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Smart Hairbrush Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Electrical Neck Warmer Market