
 Shoe Care Market | 2026-2036
Shoe Care Market Size, Share, and Industry Trends Forecast 2026-2036
Shoe Care Market Outlook
Buyer concentration among premium leather footwear owners is restructuring how manufacturers allocate R&D resources toward professional-grade formulations. S.C. Johnson & Son, Inc. leverages its household chemical expertise to dominate mass-market spray channels across North American retail. Griffin Shoe Care anchors its position through specialized distribution to British cobblers and heritage footwear workshops. Allen Edmonds Corporation competes by integrating care products directly with its own footwear retail ecosystem.
Shoe care encompasses chemical formulations and mechanical tools designed to clean, condition, protect, and restore leather, suede, rubber, and synthetic footwear materials, typically involving pH-balanced surfactants, natural waxes, silicone compounds, or fluoropolymer barriers that repel water and resist abrasion while preserving material flexibility. The category serves both consumer maintenance routines and professional restoration services seeking to extend footwear functional life and aesthetic value. Shoe polish retains the largest revenue share among product types due to entrenched habitual use across formal footwear segments, while waterproofing spray captures the fastest expansion as outdoor and performance footwear categories broaden. Among applications, protection-oriented solutions command margin premiums compared to basic cleaning, reflecting consumer willingness to pay for preventive durability rather than reactive restoration.
REACH in Europe and EPA guidelines in the United States constrain volatile organic compound content in solvent-based polishes, compelling reformulation toward water-based and plant-derived alternatives that satisfy regulatory thresholds without sacrificing performance benchmarks. California's Proposition 65 adds disclosure requirements for specific chemical constituents, influencing labeling practices and supply chain documentation across brands serving the North American market. Stakeholders must monitor evolving chemical restriction schedules and certification standards to anticipate compliance costs and product line transitions ahead of enforcement deadlines.
Market Dynamics
REACH compliance deadlines and EPA volatile organic compound restrictions are forcing simultaneous reformulation of solvent-based polishes and sprays, compressing R&D timelines while premium leather footwear owners extend replacement cycles and expand maintenance spending.
Growth Catalysts
- REACH chemical restrictions:European manufacturers accelerate water-based polish development to meet ECHA thresholds, creating first-mover advantages in compliant formulations.
- Artisanal repair networks:Germany's cobbler tradition sustains professional-grade product demand through heritage footwear workshops and specialized retail channels.
- Fluoropolymer barriers:Performance footwear makers integrate advanced waterproofing into factory finishes, pulling companion aftermarket sprays into consumer routines.
Market Restraints
- Petrochemical input volatility:Silicone and synthetic wax feedstock costs fluctuate with crude oil indices, squeezing margin on mid-tier polish lines.
- Water-based performance gaps:Current plant-derived formulations struggle to match solvent-based shine durability on full-grain leather, limiting professional adoption.
- California Proposition 65:Disclosure requirements for specific chemical constituents add documentation burdens and label complexity across North American supply chains.
Strategic Opportunities
- India formal footwear expansion:Rising white-collar employment in Mumbai and Bangalore creates untapped demand for polish and conditioning kits.
- Direct-to-consumer subscription:Automated replenishment models bypass traditional retail markup and capture recurring revenue from heritage boot owners.
- EU Green Deal procurement standards:Public sector uniform programs increasingly specify bio-based maintenance products, opening institutional volume.
Industry Challenges
- Reformulation certification timelines:Third-party performance validation for new water-based chemistries extends product launch windows by 8-14 months.
- Skilled compounder scarcity:Experienced leather chemists capable of balancing pH stability with aesthetic finish are concentrated among retiring European specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoe Care Market |
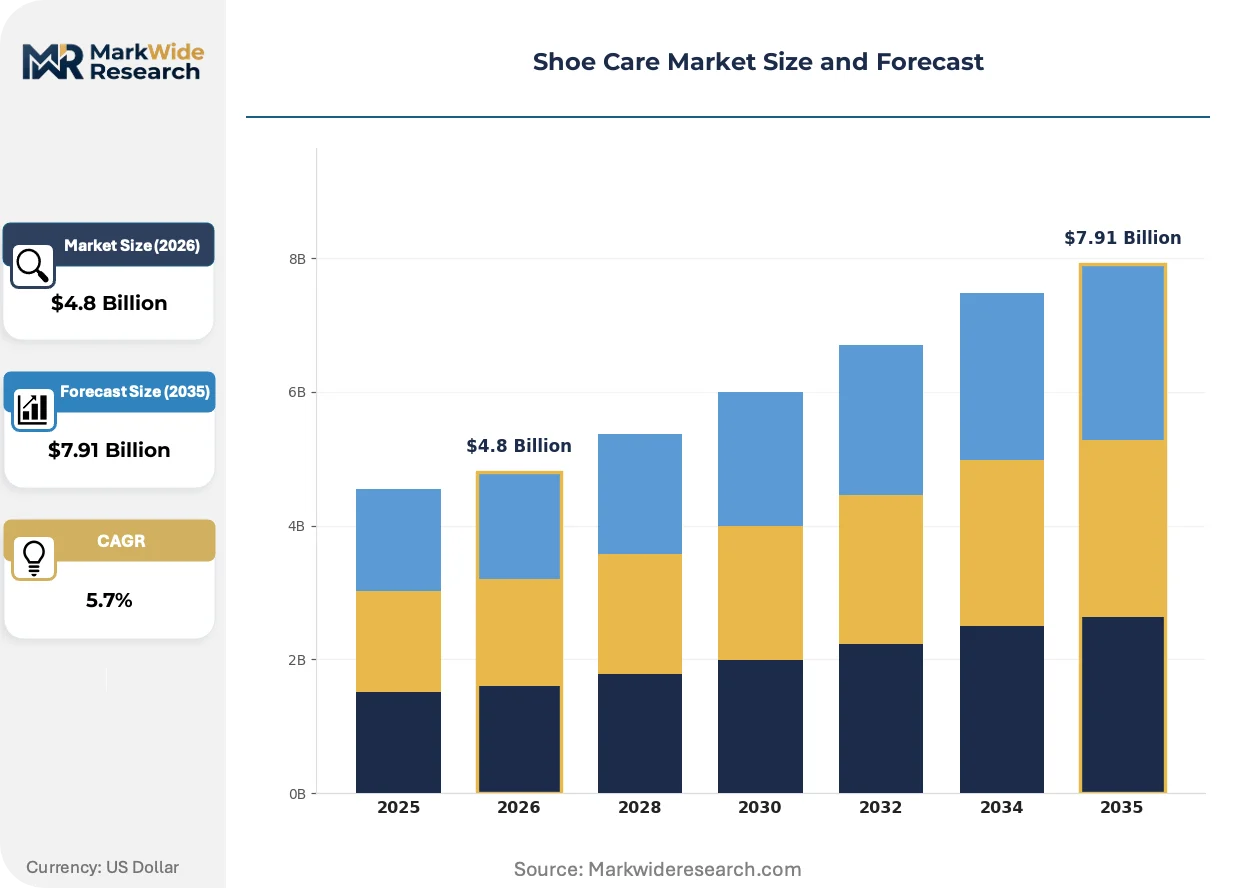
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoe Polish, Waterproofing Spray, Cleaner, Conditioner Application: Footwear Maintenance, Protection, Restoration, Stain Removal End User: Retail Customers, Shoe Manufacturers, Care Service Providers, Distributors Distribution Channel: Online Retail, Brick-and-Mortar Stores, E-commerce, Wholesale |
| Companies Covered | Griffin Shoe Care, Granger's International Limited, S.C. Johnson & Son, Inc., Allen Edmonds Corporation, Angelus Shoe Polish, Caleres, Tarrago Brands International, Charles Clinkard, Harry Hoffman Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoe Care Market Strategic Shifts
Formulation chemistry and distribution architecture are undergoing parallel transformation as regulatory pressure and direct-channel economics reshape how shoe care products reach end users.
Biopolymer-based conditioners are unifying cleaning and protective functions into single-application creams. Premium heritage boot owners in Germany and the United States adopt these hybrid formulations faster than traditional two-step routines. This convergence is unifying what were separate SKU categories into consolidated product lines, reducing shelf space requirements and simplifying inventory for specialty retailers.
EPA volatile organic compound standards are tightening permissible solvent content in aerosol polishes. Manufacturers face reformulation costs or portfolio pruning decisions as state-level adoption spreads beyond California. Professional cobblers and industrial uniform services bear the highest compliance burden, accelerating their shift toward paste and cream alternatives.
Subscription-based replenishment is displacing episodic retail purchase among dedicated footwear enthusiasts. Direct channels capture customer data that enables predictive restocking before product depletion. This pattern concentrates in the United States and United Kingdom where credit-card-on-file commerce infrastructure supports frictionless recurring billing.
Shoe Care Market Segmentation
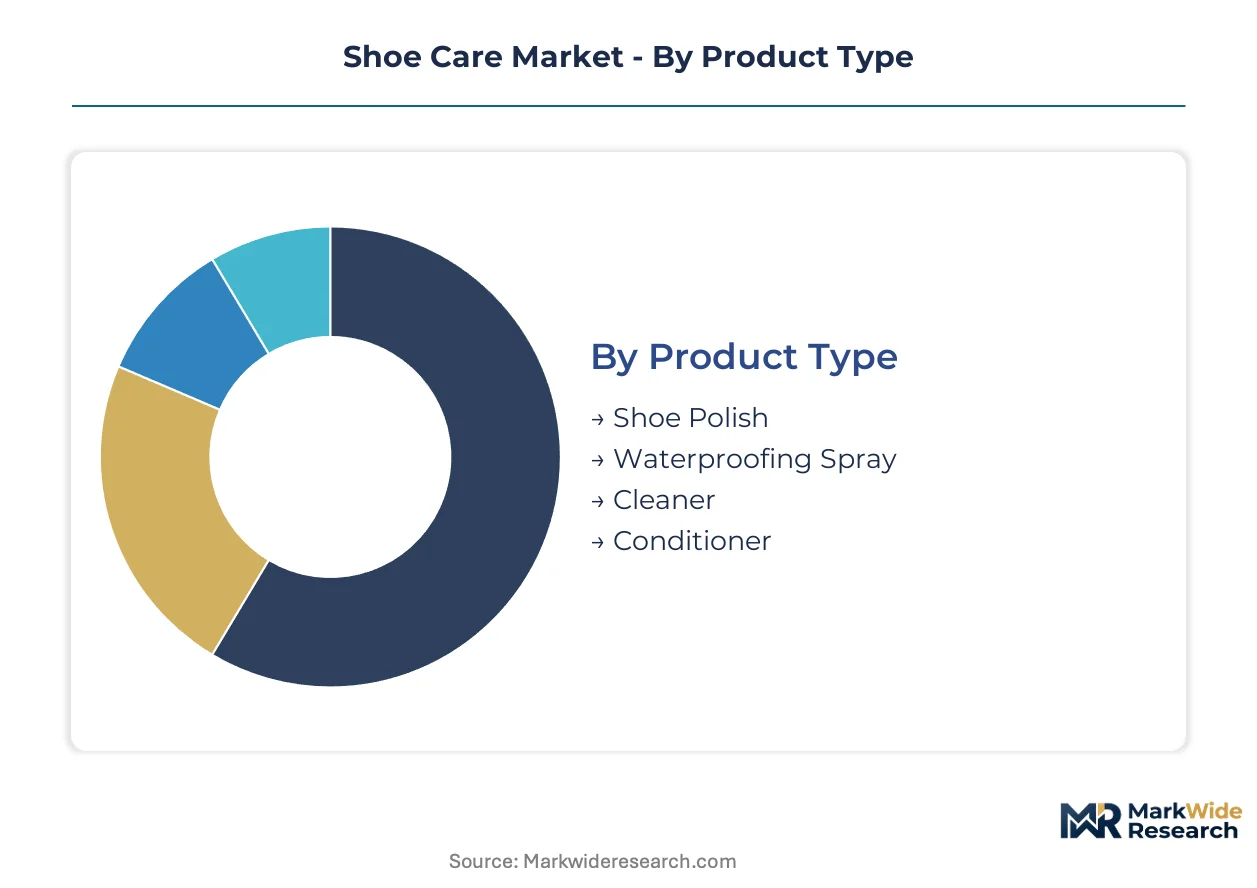
Shoe care manufacturers configure product lines around distinct usage occasions and buyer sophistication levels. Segmentation reveals where formulation complexity commands price premiums versus where volume scales through standardized SKUs.
Product Type:
Material composition and application frequency separate occasional users from dedicated footwear enthusiasts willing to invest in multi-step maintenance routines.
- Shoe Polish:Wax-based formulations combining carnauba, beeswax, and petroleum distillates deliver surface shine and leather nourishment through manual buffing. Demand concentrates among corporate professionals in Germany and the United Kingdom maintaining formal leather footwear, sustained by habitual weekly application routines that resist substitution.
- Waterproofing Spray:Fluoropolymer or silicone-based aerosol and pump-spray barriers create hydrophobic surface layers without altering material breathability. Outdoor footwear owners in the United States and Scandinavian countries drive expansion as hiking and performance boot categories broaden, pulling companion aftermarket protection into consumer purchase patterns.
- Cleaner:pH-balanced surfactant solutions remove surface soiling without stripping natural leather oils.
- Conditioner:Oil and lanolin emulsions restore suppleness to dried or cracked leather uppers.
Volume sits with shoe polish; growth tilts toward waterproofing spray.
Application:
Margin structure varies sharply between preventive maintenance and reactive intervention, with protection-oriented solutions capturing sustained premium pricing.
- Footwear Maintenance:Routine cleaning and conditioning protocols executed by individual owners or professional cobblers extend functional lifespan of leather goods. Heritage boot collectors in the United States and Germany sustain demand for premium formulations through disciplined care schedules that treat maintenance as investment preservation.
- Protection:Preventive treatments applied before wear to resist water, salt, and abrasion damage. Corporate uniform programs and outdoor retailers specify these solutions, accepting higher per-unit costs to reduce replacement frequency and warranty claims.
- Restoration:Intensive interventions for damaged or vintage footwear requiring color matching and structural repair.
- Stain Removal:Targeted treatments for specific contaminant types including oil, salt, and organic matter.
Protection commands the steepest expansion trajectory as buyers prioritize durability over reactive repair.
End User:
Procurement scale and technical specification intensity distinguish mass-market consumption from institutional and industrial volumes.
- Retail Customers:Individual purchasers selecting products through retail or direct channels for personal footwear collections. Enthusiast segments in the United States and United Kingdom demonstrate highest per-capita spending, driven by heritage boot ownership and subscription replenishment models.
- Shoe Manufacturers:Factory-applied finishes and bundled care kits integrated at point of sale. Performance footwear makers increasingly specify companion aftermarket products to reinforce brand loyalty and complete protection systems.
- Care Service Providers:Professional cobblers and restoration workshops requiring bulk formulations.
- Distributors:Intermediary procurement for resale through retail networks.
Retail customers generate absolute volume; shoe manufacturers represent the most concentrated growth vector through bundled distribution.
Distribution Channel:
Channel economics determine margin capture and customer data access, with direct models displacing traditional retail intermediation in enthusiast segments.
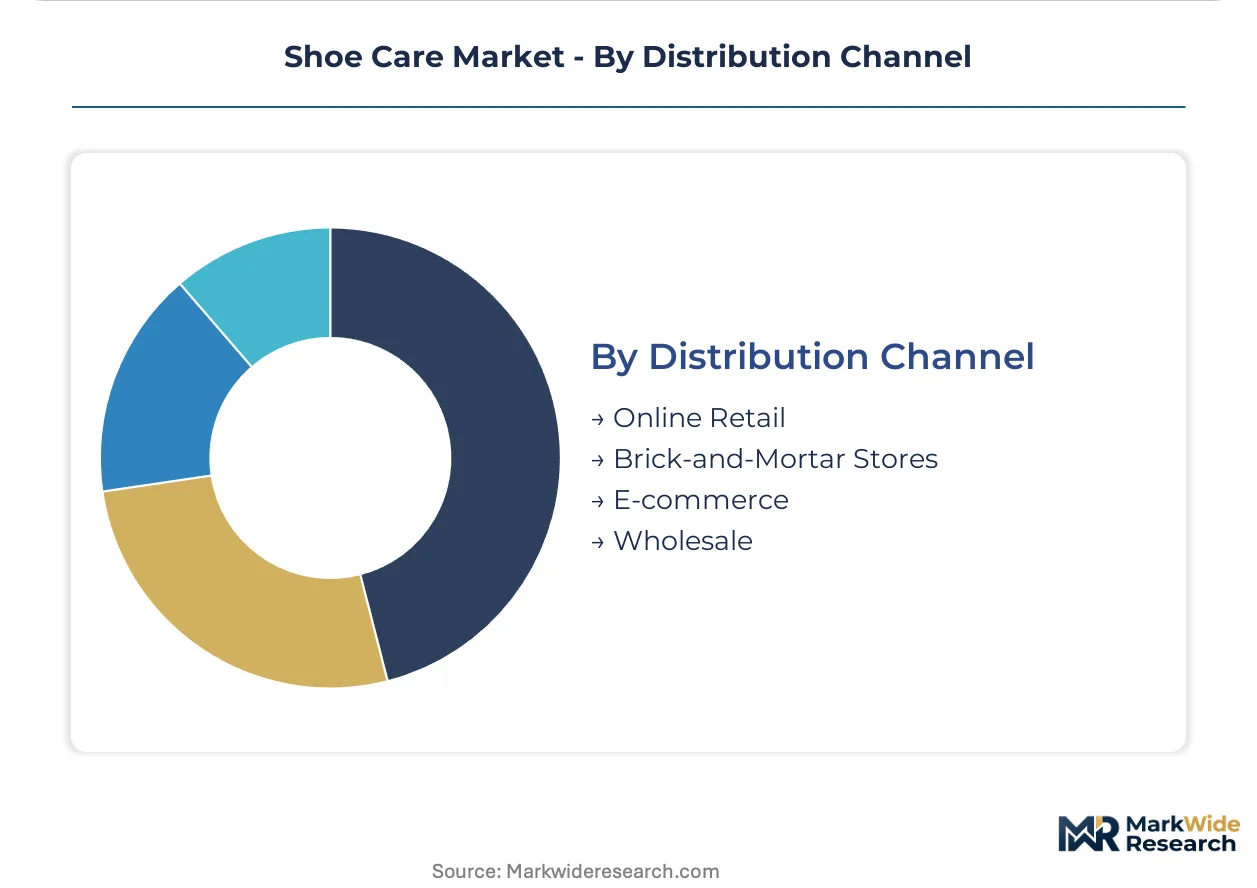
- Online Retail:Brand-controlled storefronts and marketplace listings enabling subscription replenishment and educational content delivery. United States and United Kingdom markets show highest penetration where credit-card-on-file infrastructure supports automated reordering before product depletion.
- Brick-and-Mortar Stores:Physical retail including specialty footwear shops, department stores, and cobbler-supply outlets. Germany's artisanal repair network sustains professional-grade product availability through specialized trade channels inaccessible to mass-market competitors.
- E-commerce:Third-party platform sales through major marketplace operators.
- Wholesale:Bulk supply arrangements to retailers and institutional buyers.
Brick-and-mortar retains volume leadership in professional segments; online retail climbs fastest among dedicated consumer enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum distillate and natural wax supply chains rooted in the United States, Germany, and India anchor formulation economics across key demand centers. REACH thresholds in Europe and EPA volatile organic compound limits in North America are redirecting production investment toward water-based chemistry platforms. Artisanal repair networks in Germany and subscription commerce infrastructure in the United States represent divergent but equally influential distribution models.
United States
Heritage boot collectors in Austin and Nashville sustain premium conditioner demand through disciplined maintenance routines. EPA volatile organic compound standards constrain aerosol polish formulations, pushing manufacturers toward paste and cream alternatives. Performance footwear makers in the Pacific Northwest integrate factory-applied fluoropolymer barriers that pull companion aftermarket sprays into consumer purchase patterns.
Germany
Corporate professionals in Munich and Frankfurt maintain formal leather footwear through habitual weekly polish application that resists substitution. ECHA REACH compliance deadlines accelerate water-based formulation development among domestic compounders. Artisanal cobbler workshops in Berlin and Hamburg sustain professional-grade product consumption through specialized trade channels inaccessible to mass-market competitors.
United Kingdom
Heritage footwear enthusiasts in London and Manchester demonstrate highest per-capita spending on subscription replenishment models. Credit-card-on-file commerce infrastructure supports frictionless recurring billing ahead of product depletion. Specialized distribution to British cobblers and heritage workshops sustains premium formulation availability outside mass retail.
India
Rising white-collar employment in Mumbai and Bangalore creates expanding demand for polish and conditioning kits among formal footwear owners. Bureau of Indian Standards certification requirements influence import documentation and label specifications for multinational brands. Leather goods manufacturing clusters in Chennai and Kanpur generate institutional volume for factory-applied finishes and bundled care kits.
Japan
Disciplined maintenance culture among Tokyo and Osaka professionals sustains demand for multi-step conditioning routines. Ministry of Economy, Trade and Industry guidelines influence chemical disclosure standards for imported shoe care products. Specialty retailers in Kansai and Kanto regions curate premium formulations targeting investment-oriented heritage footwear collectors.
Shoe Care Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and bio-based formulation niches. The vendor base organizes around three archetypes: mass-market chemical conglomerates leveraging household product distribution, heritage specialists serving artisanal repair networks, and vertically integrated footwear brands bundling care with original equipment. Competitive moves concentrate on portfolio diversification into water-based alternatives and strategic partnerships with performance footwear manufacturers.
Among heritage specialists, Griffin Shoe Care and Tarrago Brands International exemplify the professional-grade tier serving cobbler workshops and heritage footwear restoration. S.C. Johnson & Son, Inc. anchors the mass-market vector with household chemical expertise deployed across North American retail spray channels. Allen Edmonds Corporation represents vertical integration, embedding care products within its own footwear retail ecosystem to capture recurring maintenance spend from original purchasers.
| Leading Market Players |
|---|
| Griffin Shoe Care |
| Granger's International Limited |
| S.C. Johnson & Son, Inc. |
| Allen Edmonds Corporation |
| Angelus Shoe Polish |
| Caleres |
| Tarrago Brands International |
| Charles Clinkard |
| Harry Hoffman Company Inc. |
| Others |
Value Chain & Pricing Dynamics
Leather chemist concentration in retiring European specialists widens labor-cost spreads between premium heritage-grade formulations and mass-market solvent-based polishes, compressing mid-tier margins while REACH compliance investments push pricing stratification across professional, consumer, and institutional tiers.
Pricing Analysis
Volume aggregates in economy-grade shoe polish while margin concentrates in professional-grade conditioners and waterproofing sprays. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-compliant water-based formulations from legacy solvent polishes and generic petroleum-wax blends. Price differentiation hinges on certification grade for REACH thresholds and brand premium anchored in heritage cobbler networks. Cost compression in mid-tier paste lines is intensifying because petrochemical feedstock volatility squeezes compounders lacking backward integration into natural wax supply chains. Corporate uniform programs demonstrate lowest price sensitivity; episodic retail purchasers in mass channels exhibit highest elasticity.
Supply Chain Analysis
Direct-to-cobbler channels handle professional-grade demand through specialized trade networks in Germany and the United Kingdom, while mass-market spray distribution runs through North American retail intermediaries. Geographic supply concentration centers on Germany for synthetic wax polymerization, the United States for silicone compound blending, and India for natural carnauba and beeswax refinement. Raw material dependencies draw from crude oil derivatives for petroleum distillates, palm and coconut feedstocks for surfactant bases, and fluoropolymer resins for waterproofing barriers. Single-source vulnerability in European leather-chemist expertise threatens reformulation timelines for water-based alternatives. Distribution downstream feeds through heritage workshop supply houses, direct-to-consumer subscription platforms, and big-box retail spray aisles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH thresholds erect formulation-certification barriers that favor incumbent compounders with validated water-based chemistries over capital-constrained challengers.
For Market Incumbents: To counter skilled compounder scarcity in retiring European specialists, secure captive supply of leather-chemistry expertise through apprenticeship partnerships with German technical institutes and accelerate backward integration into natural wax sourcing from Indian refining clusters. Channel control through direct-to-cobbler distribution in Berlin and Hamburg trade networks defends professional-grade margin against mass-market private-label erosion. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian formal footwear maintenance opens white-space targeting of white-collar professionals in Mumbai and Bangalore with subscription-format conditioning kits bypassing traditional retail markup. Direct-to-consumer platforms leveraging credit-card-on-file infrastructure capture recurring revenue from heritage boot owners in the United States and United Kingdom. Specialty waterproofing spray for performance outdoor categories offers the most penetrable application segment. For Investors and Strategic Acquirers: The window for entry favors vertically integrated footwear brands with captive care-product bundling and compliant water-based formulation pipelines already validated. Acquisition targets should display established ECHA registration dossiers and direct-channel customer data infrastructure. Watch for EPA state-level VOC adoption spreading beyond California as the inflection signal accelerating paste-and-cream substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Formulation Certification | ECHA REACH dossier completion locks in professional cobbler channel access ahead of solvent-phaseout deadlines. |
| Direct-to-Consumer Subscription Launch | Credit-card-on-file infrastructure in US and UK markets captures predictive replenishment from heritage footwear collectors. |
| Backward Integration into Natural Wax Supply | Captive sourcing from Indian carnauba and beeswax refiners hedges petrochemical feedstock volatility squeezing mid-tier margins. |
| Performance Footwear Manufacturer Partnership | Factory-applied fluoropolymer barrier integration pulls companion aftermarket sprays into consumer purchase patterns. |
| Artisanal Cobbler Network Distribution Expansion | Specialized trade channels in Berlin and Hamburg sustain premium pricing outside mass-market retail commoditization. |
Study Parameters
Trade databases, customs records, and ECHA registration filings formed the secondary backbone, cross-referenced with primary interviews spanning leather-chemical compounders, professional cobbler workshop proprietors, footwear brand procurement directors, and specialty retail category buyers. Bottom-up triangulation against top-down production capacity estimates validated volume assumptions across water-based polish, waterproofing spray, and conditioner categories.
Historical trendline analysis of formulation chemistry transitions and channel migration patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, application occasion, end-user procurement scale, and distribution channel economics. CAGRs derived from elasticity-adjusted adoption curves for REACH-compliant alternatives and subscription-commerce penetration rates in enthusiast segments. Fluoropolymer barrier integration rates in performance footwear and artisanal repair network density in German urban clusters served as industry-specific forecast inputs.
Inputs from regulatory filing databases and primary field contacts were available through the study window; gaps in real-time cobbler workshop inventory turnover data introduce uncertainty bands around professional-grade volume estimates. Forecasts reflect assumptions regarding ECHA enforcement consistency and EPA state-level VOC adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Electrical Neck Warmer Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
360 Degree Toothbrush Market
Personal Grooming Products
Global Posture Corrector Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Hand Massager Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Ear Piercing Guns Market