
 Sports Broadcasting Technology Market | 2026-2036
Sports Broadcasting Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Broadcasting Technology Market Analytics
Software-defined production workflows are shifting how rights holders monetize live content beyond traditional linear feeds. Evertz Microsystems Ltd. leverages modular routing platforms to anchor large-scale venue installations across North American stadiums. Rohde & Schwarz sustains engineering intensity in terrestrial and satellite transmission standards. NEP Group Inc. dominates outsourced broadcast production through its fleet of mobile units and remote integration capabilities.
Sports broadcasting technology encompasses the integrated hardware, software, and network systems used to capture, process, distribute, and display live and recorded athletic content to mass audiences, typically operating with sub-100 millisecond latency thresholds for real-time synchronization. Its primary commercial purpose is to maximize audience reach and engagement value for rights holders while enabling granular viewer personalization through multi-camera angles and interactive overlays. IP-based systems now lead capital deployment as broadcasters retire SDI infrastructure in favor of SMPTE ST 2110 packetized workflows. Streaming services represent the fastest-expanding delivery category, though satellite transmission retains margin density in premium tier-one events where fiber backhaul remains unavailable. Video encoding efficiency determines operational economics at scale, with HEVC and emerging VVC codecs reducing bandwidth requirements.
The FCC governs spectrum allocation and anti-siphoning rules affecting how sports content reaches US households, while the EU AI Act imposes transparency obligations on automated highlight generation and real-time analytics deployed across European broadcasts. China's MIIT and GB standards regulate codec certification and cross-border streaming platform licensing, creating compliance thresholds for foreign technology suppliers. Stakeholders must monitor divergence between regional content sovereignty mandates and the technical interoperability required for global multi-event production contracts.
Market Dynamics
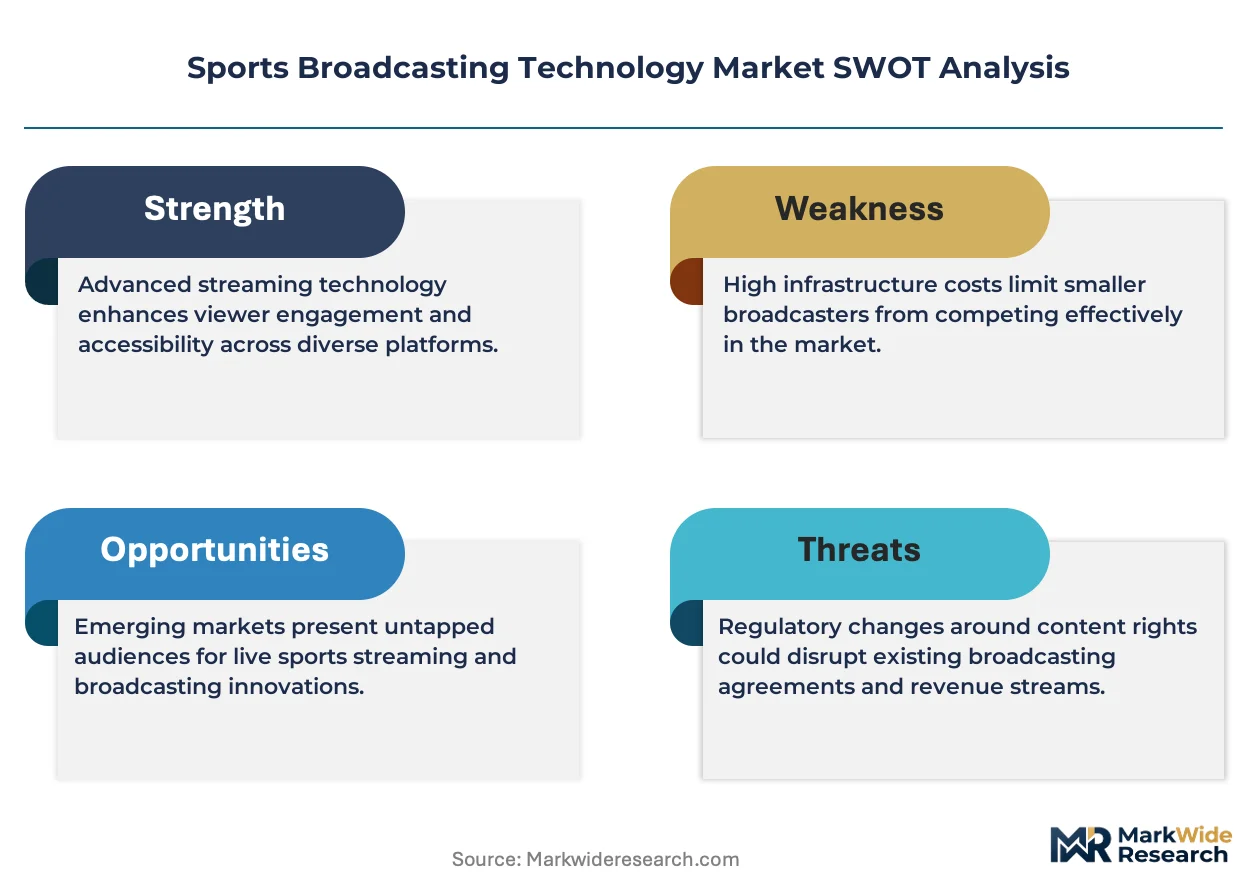
IP-based production workflows are compressing capital cycles for broadcasters retiring SDI infrastructure, while latency requirements below 100 milliseconds lock in premium pricing for real-time synchronization systems.
Growth Catalysts
- SMPTE ST 2110 adoption:Packetized video transport over IP networks reduces cabling density and enables remote production models across tier-one sporting venues.
- EU AI Act transparency mandates:Automated highlight generation and real-time analytics systems face new disclosure requirements, creating compliance-driven refresh cycles for European broadcasters.
- Live streaming platform expansion:OTT services are capturing younger demographics previously unreachable through linear distribution, expanding addressable audiences for rights holders.
Market Restraints
- Codec licensing complexity:HEVC and emerging VVC patent pools fragment royalty structures, raising uncertainty for encoder manufacturers and broadcast operators.
- Fiber backhaul gaps:Premium tier-one events in remote locations still require satellite transmission where terrestrial infrastructure remains unavailable, constraining cost optimization.
- GDPR data localization:Cross-border streaming platform operations face storage and processing restrictions that increase operational overhead for multi-territory rights holders.
Strategic Opportunities
- Cloud-native production:Distributed editing and graphics rendering via AWS, Azure, and Google Cloud platforms enables pop-up broadcast operations without permanent venue infrastructure.
- India's sports league proliferation:IPL expansion and emerging kabaddi, football, and athletics franchises create greenfield broadcast technology deployment opportunities.
- Interactive overlay monetization:Multi-camera angle selection and real-time wagering integration open direct-to-consumer revenue streams beyond traditional advertising.
Industry Challenges
- SDI-IP hybrid skill scarcity:Broadcast engineers proficient in both legacy serial digital interface and packetized network architectures command premium compensation, constraining talent pools.
- Latency synchronization complexity:Sub-100 millisecond thresholds for lip-sync and crowd audio alignment require precision timing infrastructure that complicates multi-vendor system integration.
- Cross-border content licensing:Territorial rights fragmentation forces streaming platforms to maintain separate technical stacks for adjacent markets, duplicating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Broadcasting Technology Market |
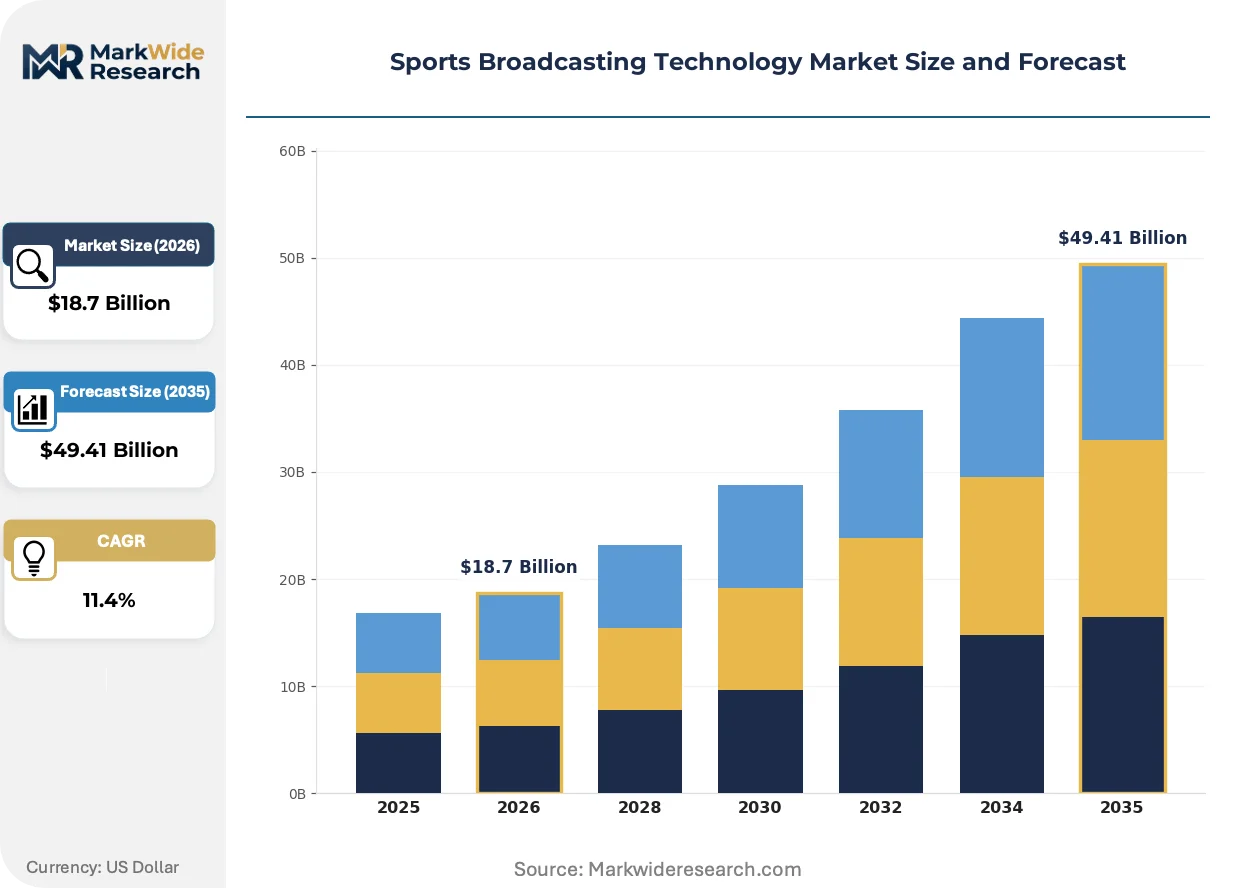
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IP-Based Systems, Satellite Transmission, Video Encoding, Streaming Services Application: Live Broadcasts, Recap Shows, Digital Streaming, E-Sports Coverage Delivery Mode: Over-the-Top, Cable Networks, Satellite Broadcast, Online Platforms End User: Broadcasters, Sports Organizations, Streaming Platforms, Production Houses |
| Companies Covered | IBM Corporation, NEC Corporation, Rohde & Schwarz, Evertz Microsystems Ltd., NEP Group Inc., Sportradar AG, Belden Inc., ESPN Sports Media Ltd., NBC Universal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Broadcasting Technology Market Evolving Landscape
Software-defined architectures are collapsing the distinction between production, post-production, and distribution workflows, compressing timelines from capture to consumer delivery.
Versatile Video Coding (VVC/H.266) is rewriting bandwidth economics for live sports streaming, halving data requirements versus HEVC at equivalent quality tiers. Broadcasters in bandwidth-constrained markets are piloting VVC encoders for 4K and 8K event coverage, though decoder penetration in consumer devices remains limited. This codec transition is rewriting capacity planning assumptions for content delivery networks serving peak concurrent viewership.
The EU AI Act imposes algorithmic transparency obligations on automated systems generating match highlights or predicting viewer engagement patterns. European broadcasters must now document training data provenance and decision logic for AI-driven editorial tools, raising compliance costs but creating differentiation for vendors with auditable systems. France's CNIL and Germany's regional data protection authorities are already enforcing these provisions against streaming platforms with automated content moderation.
Remote integration (REMI) production models are displacing on-site crew deployment for secondary and tertiary sporting events. Rights holders in Germany and the United States are centralizing technical direction, replay operations, and graphics generation to fixed facilities, flying only camera operators and minimal hardware to venues. This operational shift is most visible in mid-tier football leagues and collegiate athletics where production budgets face sustained pressure.
Sports Broadcasting Technology Market Segmentation
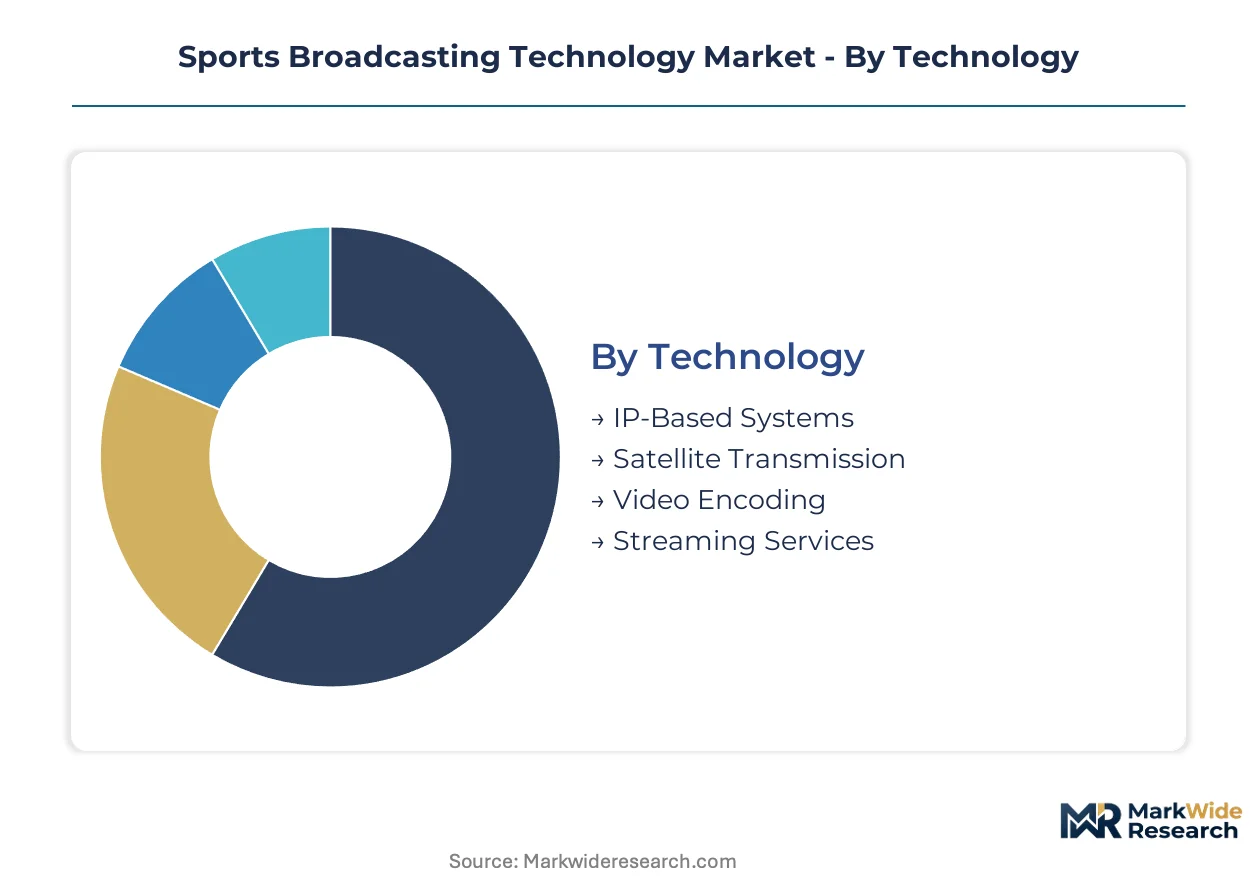
Sports broadcasting technology segments diverge sharply in regulatory exposure and infrastructure requirements. IP-based workflows face FCC equipment authorization and EU cybersecurity certification burdens that satellite transmission largely avoids.
Technology:
Certification intensity varies from voluntary codec interoperability testing to mandatory FCC Part 15 emissions compliance for IP hardware and EU AI Act algorithmic audits for automated production tools.
- IP-Based Systems:Packetized SMPTE ST 2110 workflows replace coaxial SDI infrastructure with Ethernet-based signal routing. Demand concentrates among North American broadcasters retiring legacy copper plant, driven by remote production cost reduction mandates and fiber backhaul availability.
- Video Encoding:HEVC and emerging VVC compression engines reduce bandwidth requirements for 4K distribution. Sports streaming platforms in bandwidth-constrained markets deploy these codecs to manage peak concurrent viewership without CDN capacity expansion.
- Satellite Transmission:Ku-band and Ka-band uplink systems retain necessity for remote venue connectivity where terrestrial infrastructure fails.
- Streaming Services:OTT delivery platforms require adaptive bitrate infrastructure and DRM integration for rights protection.
Leading the category by volume: IP-Based Systems. Growing fastest: Streaming Services.
Application:
Production cost tiers separate single-camera recap assembly from multi-angle live events requiring sub-100 millisecond latency synchronization.
- Live Broadcasts:Real-time multi-camera production with instantaneous replay and graphics overlay demands the lowest latency thresholds. Tier-one sporting leagues in Germany and the United States anchor demand, constrained by precision timing infrastructure costs.
- Digital Streaming:OTT-exclusive distribution bypasses linear carriage negotiations and enables interactive viewer features. Rights holders target younger demographics unreachable through traditional broadcast, expanding addressable audiences.
- Recap Shows:Post-produced highlight packages allow compressed editorial timelines and reduced crew deployment.
- E-Sports Coverage:Gaming tournament broadcasts require specialized observer tools and player perspective feeds.
Live Broadcasts command the highest production budgets. Digital Streaming gains share fastest among emerging rights holders.
Delivery Mode:
Customer type determines infrastructure preference: broadcasters maintain hybrid distribution while pure-play streaming platforms skip legacy carriage.
- Over-the-Top:Direct-to-consumer streaming bypasses gatekeeper fees and enables granular viewer analytics. Younger demographics drive adoption, expanding addressable markets beyond linear television households.
- Online Platforms:Social media and dedicated sports apps aggregate fragmented audiences through mobile-first delivery. Rights holders in India leverage these channels for cricket and emerging league coverage.
- Cable Networks:Traditional linear distribution retains premium advertising rates for marquee events.
- Satellite Broadcast:Direct-to-home satellite maintains reach in rural and geographically dispersed markets.
Over-the-Top leads by subscriber additions. Online Platforms climb fastest among rights holders targeting mobile-first demographics.
End User:
Procurement scale separates national broadcast networks from specialized production houses serving single leagues or events.
- Streaming Platforms:Technology-native operators build cloud-native production stacks without legacy SDI transition costs. Amazon Prime Video and DAZN anchor demand for serverless encoding and automated localization.
- Broadcasters:Incumbent networks manage hybrid IP-SDI infrastructure during multi-year migration cycles. ESPN and Sky Sports concentrate investment in remote integration capabilities and distributed production hubs.
- Sports Organizations:Leagues and federations bring production in-house to control content rights and direct-to-consumer relationships.
- Production Houses:Specialized vendors provide outsourced technical services and mobile unit deployment.
Broadcasters lead by installed base and annual technology spend. Streaming Platforms expand most quickly as rights migrate from linear to digital-exclusive distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of sports broadcast technology while Germany and China concentrate manufacturing and engineering development. Production clusters sit with specialized component fabricators in Southern Germany and broadcast systems integrators across the American Midwest.
United States
ESPN, NBC Universal, and Amazon Prime Video drive infrastructure refresh cycles across linear and streaming platforms. The FCC enforces anti-siphoning rules and spectrum allocation policies that shape how premium sports content reaches households. Production technology procurement concentrates in Connecticut, Los Angeles, and Seattle, where rights holders operate centralized broadcast centers.
Germany
Sky Deutschland and DFL broadcast operations sustain demand for precision timing and multi-camera synchronization systems. The country's regional data protection authorities enforce EU AI Act transparency mandates on automated highlight generation tools. Engineering development clusters in Munich and Nuremberg, where Rohde & Schwarz anchors terrestrial transmission standards development.
China
Streaming platforms iQIYI and Tencent Sports expand 4K and 8K live coverage for CSL football and LPL esports tournaments. MIIT certification requirements and GB standards regulate codec deployment and cross-border platform licensing. Shenzhen and Beijing host the dominant systems integration and hardware manufacturing ecosystems serving domestic broadcasters.
India
IPL cricket expansion and emerging kabaddi and football leagues create greenfield deployment opportunities for cloud-native production stacks. TRAI regulations govern content pricing and platform interoperability for sports streaming services. Mumbai and Bangalore concentrate technology procurement decisions as Star Sports and JioCinema build distributed production capabilities.
United Kingdom
BT Sport and Sky Sports investments in remote integration models reduce on-site crew deployment for secondary football and rugby fixtures. Ofcom broadcast codes and GDPR data handling requirements shape streaming platform operations. London and Salford host the primary production hubs where centralized technical direction and graphics rendering consolidate.
Sports Broadcasting Technology Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sports broadcasting technology landscape. Integrated systems vendors with manufacturing footprints anchor large-scale venue installations, while software specialists capture margin in encoding and analytics layers. The competitive structure separates infrastructure owners from IP licensors and managed service operators. Consolidation pressure runs through technology licensing partnerships and vertical integration into cloud-native production stacks.
Among German engineering-intensive suppliers, Rohde & Schwarz and Rohde occupy positions exemplifying transmission standards development. Evertz Microsystems Ltd. represents the Canadian systems integration archetype with modular routing platforms. NEP Group Inc. anchors the outsourced production services tier through mobile unit deployment and remote integration capabilities.
| Leading Market Players |
|---|
| IBM Corporation |
| NEC Corporation |
| Rohde & Schwarz |
| Evertz Microsystems Ltd. |
| NEP Group Inc. |
| Sportradar AG |
| Belden Inc. |
| ESPN Sports Media Ltd. |
| NBC Universal |
| Others |
Value Network & Pricing Analysis
IP-based production workflow transitions simultaneously compress equipment replacement cycles and concentrate procurement leverage among systems integrators capable of bridging legacy SDI and packetized network architectures. Broadcasters retiring coaxial infrastructure face bundled pricing from vendors supplying complete SMPTE ST 2110 routing ecosystems rather than discrete component sourcing.
Pricing Analysis
Cost-down pressure on encoder hardware accelerates because HEVC and emerging VVC patent pools fragment royalty structures and force manufacturers to absorb licensing uncertainty. Three-tier pricing structure across premium, standard, and economy levels separates tier-one sporting leagues demanding sub-100 millisecond synchronization from collegiate and secondary leagues accepting relaxed latency thresholds. Certification tier and volume scale drive price differentiation, with FCC Part 15 authorized equipment commanding premiums over uncertified alternatives. Streaming platforms exhibit highest price sensitivity due to pure-play digital economics, while incumbent broadcast networks with hybrid infrastructure tolerate premium pricing for interoperability guarantees during migration periods.
Supply Chain Analysis
FPGA and ASIC supply rests on Taiwanese semiconductor foundries and German precision timing component manufacturers. Critical inputs include broadcast-grade fiber optic transceivers, software-defined routing chipsets, and satellite uplink amplifiers. Single-source vulnerability concentrates in specialized SMPTE ST 2110 timing chips where alternative qualified suppliers remain limited. Distribution runs through systems integrators like Evertz Microsystems and NEP Group rather than direct manufacturer-to-broadcaster relationships, with regional service contracts determining downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over cloud-native production stacks and remote integration capabilities determines margin capture. Players are pursuing backward integration into encoding software and distributed graphics rendering to escape hardware commoditization.
For Market Incumbents: To counter cloud-native entrants capturing streaming platform accounts, incumbent broadcast technology suppliers should deepen in-house production of software-defined routing platforms and secure captive supply of FPGA chipsets through long-term foundry agreements. Certification investment in EU AI Act auditable systems creates differentiation against unproven competitors. For New Entrants and Emerging Players: Cloud service providers represent the most accessible channel partner type for encoding software vendors seeking rapid scale. India's emerging kabaddi and football leagues offer penetrable white-space as greenfield deployments without legacy SDI transition burdens. A direct-to-league sales model bypassing established systems integrators accelerates initial reference accounts. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by hyperscale cloud platforms seeking broadcast vertical expertise. Long-term viability hinges on software recurring revenue ratios exceeding hardware dependency. The signal to watch is remote integration contract renewal rates at tier-one sporting leagues as inflection indicator for production model permanence.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Production Stack Development | AWS and Azure partnerships enable pop-up broadcast operations without permanent venue infrastructure investment. |
| SMPTE ST 2110 Certification Investment | FCC equipment authorization and EU cybersecurity certification create compliance moats against unqualified competitors. |
| Remote Integration Capability Expansion | Centralized technical direction reduces on-site crew deployment for mid-tier football and collegiate athletics. |
| VVC Codec Early Adoption | Bandwidth efficiency gains position streaming platforms for 4K and 8K event coverage without CDN expansion. |
| AI Transparency System Auditing | EU AI Act compliance documentation differentiates vendors serving European broadcasters and streaming platforms. |
Research Methodology
Independent corroboration across broadcast technology procurement directors, remote integration operations managers, and streaming platform engineering leads underwrites the qualitative findings. Primary interviews with mobile unit deployment specialists, cloud infrastructure architects, and sports league broadcast rights managers combined with secondary validation from FCC equipment authorization databases, SEC 10-K filings of publicly traded technology suppliers, and EMA regulatory submission records. Bottom-up vendor revenue triangulation against top-down addressable market sizing anchored the segment-level outputs.
Comparable-period anchoring to historical capital expenditure cycles at ESPN, Sky Deutschland, and Tencent Sports established the forecast baseline across the projection horizon. Segmentation dimensions modeled include technology type, application tier, delivery mode, and end-user procurement scale. CAGRs derived from installed base replacement rates and greenfield deployment pipelines in India and China. Industry-specific inputs encompassed fiber backhaul availability maps and satellite transponder lease pricing trends.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwanese semiconductor supply and unanticipated codec patent litigation outcomes. Forecasts reflect documented assumptions about SMPTE ST 2110 adoption velocity and cloud infrastructure capex commitments. A small set of named triggers warrants ongoing watch: EU AI Act enforcement intensity against automated highlight generation tools and TRAI content pricing regulation evolution in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Projection Mapping Market
Digital Media
Wedding Photography Market
Digital Media
Africa Animation Market
Digital Media
Media Gateway Market
Digital Media
Global Virtual Goods Market
Digital Media
Online Movie Market
Digital Media
Photographic Services Market
Digital Media
Drone Wedding Photography Market
Digital Media
China Webtoons Market
Digital Media
Global Streaming Media Device Market
Digital Media
Global Digital Painting Market
Digital Media
Europe Online Video Platform Market
Digital Media
Anime Streaming Tool Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Visual Effects (VFX) Market