
 Global Antiseptic and Disinfectant Market | 2026-2036
Global Antiseptic and Disinfectant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antiseptic and Disinfectant Market Foresight
European chemical manufacturers is realigning production schedules to meet tightened EU biocidal product authorization timelines. Steris leverages integrated sterilization service contracts to anchor long-term hospital partnerships. 3M sustains technology leadership through concentrated hydrogen peroxide formulations that reduce surface contact times.
Antiseptics and disinfectants comprise antimicrobial chemical agents formulated with active concentrations typically ranging from 0.5% to 10% by volume, designed to eliminate or suppress pathogenic microorganisms on living tissue and inanimate surfaces respectively. Alcohol-based solutions dominate outpatient clinical settings due to rapid evaporation and minimal residue profiles, while chlorine-based compounds maintain cost advantages in municipal water treatment and food sanitation infrastructure. Quaternary ammonium salts capture expanding share in hospitality and transportation sanitation programs where low-corrosion properties and extended residual activity justify premium positioning against peroxide alternatives.
FDA oversight of antiseptic drug monographs and EPA regulation of disinfectant efficacy claims create dual compliance pathways that shape product development investment and labeling requirements for US market participants. ECHA biocidal product regulation and REACH chemical safety assessments impose equivalent pre-market authorization burdens across European manufacturing and import channels. Stakeholders must monitor evolving resistance surveillance data from CDC and ECDC to anticipate reformulation mandates before regulatory deadlines force reactive portfolio adjustments.
Market Dynamics
WHO infection control protocol updates are forcing hospital procurement departments to expand bulk disinfectant orders, compressing supplier margins while accelerating formulation standardization across acute care networks.
Growth Catalysts
- EPA disinfectant efficacy claims:Accelerated review pathways for emerging pathogens are shortening time-to-market for novel actives targeting Candida auris and other resistant organisms.
- German healthcare facilities:ECHA biocidal product regulation compliance requirements are driving preference for quaternary ammonium formulations with pre-authorized active substance combinations.
- Electrostatic spraying systems:Terminal disinfection protocols in US long-term care facilities are incorporating charged particle application to reduce surface contact times and labor burden.
Market Restraints
- Isopropyl alcohol feedstock volatility:Propylene supply disruptions from petrochemical crackers are creating margin compression for alcohol-based hand rub manufacturers.
- Chinese active pharmaceutical ingredient concentration:Dependence on Zhejiang and Jiangsu province suppliers for chlorhexidine gluconate intermediates creates geopolitical exposure.
- Sporeicidal efficacy gaps:Quaternary ammonium compounds demonstrate limited activity against Clostridioides difficile endospores, restricting use in oncology and transplant units.
Strategic Opportunities
- Indian outpatient clinics:Low penetration of alcohol-based surgical hand preparation in tier-2 and tier-3 cities creates whitespace for pre-operative antiseptic kits.
- EU Green Deal biocidal sustainability criteria:Biodegradable surfactant formulations meeting forthcoming environmental hazard classifications will capture premium positioning in Nordic hospital systems.
- UV-C and hydrogen peroxide vapor convergence:Automated room decontamination systems integrating photocatalytic and chemical modalities are displacing manual terminal cleaning in Japanese acute care facilities.
Industry Challenges
- Antimicrobial resistance surveillance integration:Hospital infection control teams lack standardized data pipelines connecting CDC NHSN reporting to formulary decision workflows.
- ECHA BPR renewal timelines:Active substance supplier consolidation is creating authorization bottlenecks for legacy phenolic formulations used in veterinary and food processing applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antiseptic and Disinfectant Market |
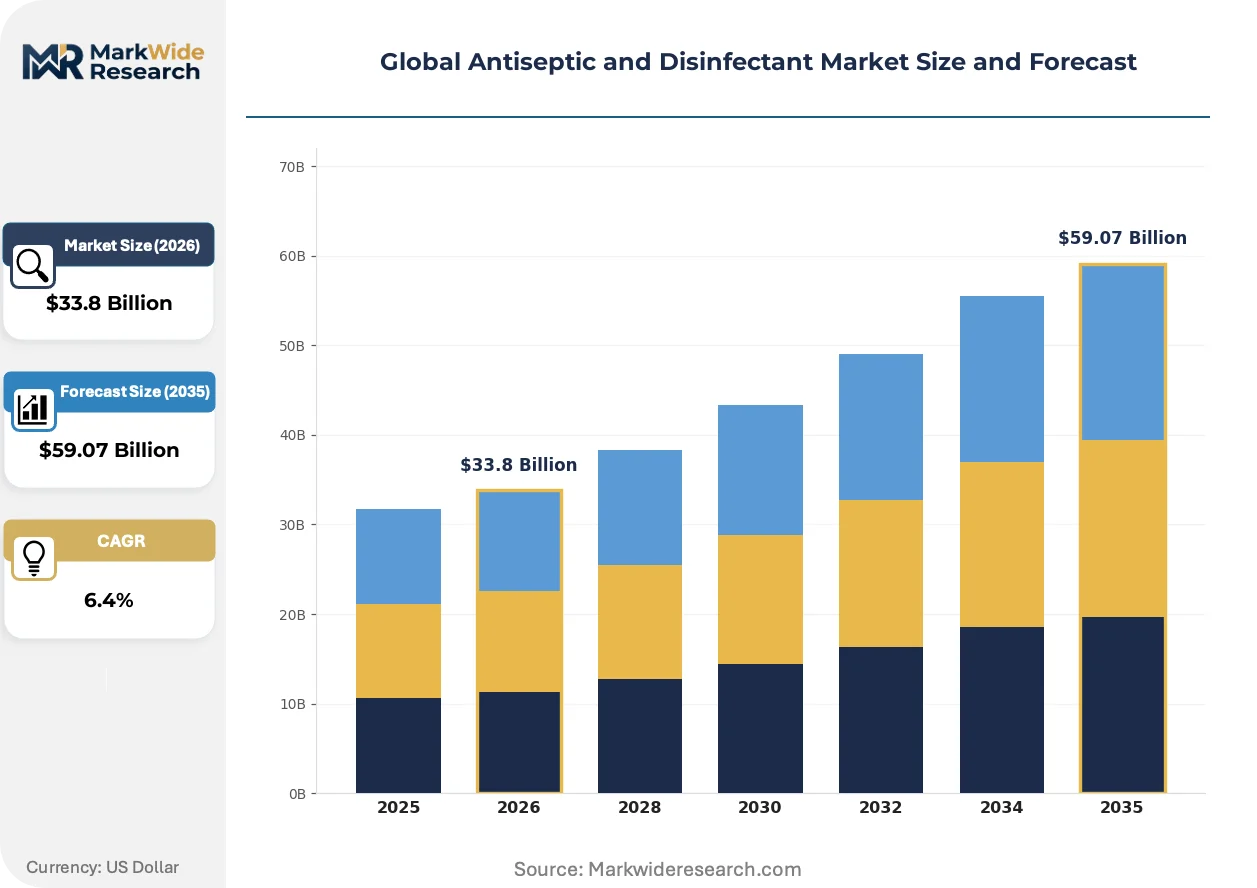
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $59.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol-Based, Chlorine-Based, Phenolic, Quaternary Ammonium, Hydrogen Peroxide Application: Medical Facilities, Food Processing, Pharmaceutical Manufacturing, Hospitality Services, Public Transportation End User: Hospitals, Dental Clinics, Veterinary Clinics, Laboratory Settings, Nursing Homes Packaging Type: Bottles, Sprays, Wipes, Bulk Containers, Sachets |
| Companies Covered | Steris, 3M, Reckitt Benckiser Group, Johnson & Johnson, Kimberly-Clark Corporation, Procter & Gamble, The Clorox Company, Ecolab, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antiseptic and Disinfectant Market Shifts & Advancements
Formulation chemistry and application hardware are converging to reduce human factors in environmental disinfection, with regulatory pressure on contact times accelerating automation adoption across acute care and food processing verticals.
Electrostatic spraying technology is automating surface coverage validation through real-time charge density monitoring and automated path planning algorithms. US hospital environmental services departments are deploying these systems in operating suites and isolation rooms to reduce terminal cleaning labor by thirty to fifty percent. The technology is automating compliance documentation for Joint Commission surveys while compressing room turnover intervals.
REACH chemical safety assessments are forcing reformulation of legacy quaternary ammonium compounds ahead of 2026 authorization deadlines. European manufacturers are submitting dossettes for twin-chain dimethyl ammonium chlorides with enhanced biodegradation profiles to maintain market access. German and Dutch healthcare procurement consortia are prioritizing suppliers with completed substance evaluations, creating first-mover advantages for compliant portfolios.
Consolidated purchasing through regional healthcare alliances is displacing individual hospital formulary autonomy in the United States. Integrated delivery networks in Texas and California are mandating single-source contracts for surface disinfectants across all affiliated facilities, compressing supplier counts from twelve to three in some systems. This concentration is most visible in Medicare Advantage-heavy markets where total cost of ownership metrics dominate vendor selection criteria.
Global Antiseptic and Disinfectant Market Segmentation
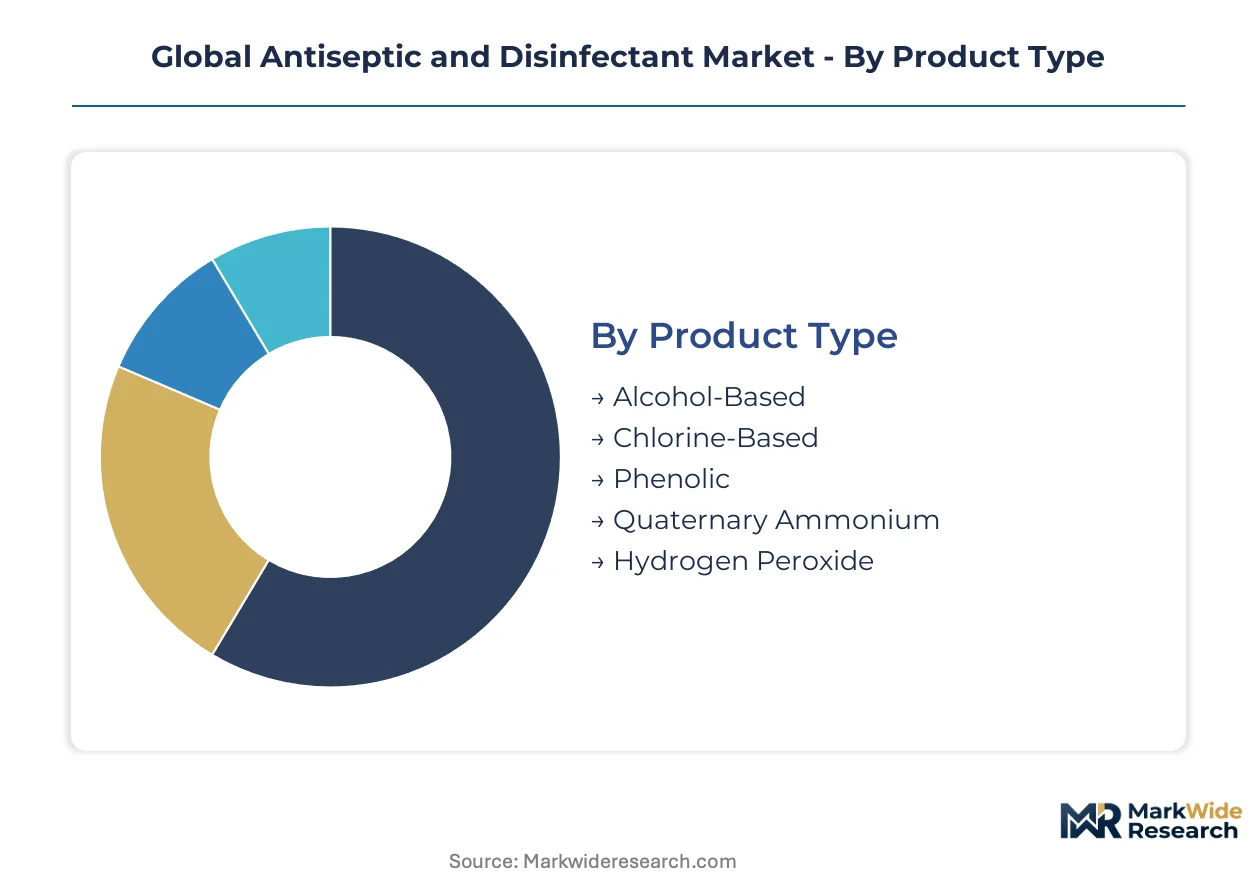
Antiseptic and disinfectant procurement varies sharply across end-use contexts, with hospital infection control teams prioritizing sporicidal efficacy while food processors emphasize residue-free profiles. Formulation chemistry and packaging format decisions cascade through regulatory compliance, storage infrastructure, and application automation requirements.
Product Type:
Capital intensity concentrates in hydrogen peroxide and quaternary ammonium manufacturing, where dedicated reactor vessels and purification systems demand substantial upfront investment.
- Hydrogen Peroxide:Concentrated formulations above 3% by weight require pressure-rated stainless steel processing equipment and explosion-proof handling systems. US hospital systems are adopting these for automated room decontamination to reduce Candida auris transmission in oncology wards.
- Quaternary Ammonium:Twin-chain dimethyl ammonium chlorides with enhanced biodegradation profiles require specialized esterification reactors for REACH-compliant production. German healthcare procurement consortia prioritize suppliers with completed ECHA substance evaluations.
- Alcohol-Based:Ethanol and isopropanol blends dominate outpatient clinical settings for rapid evaporation characteristics.
- Chlorine-Based:Sodium hypochlorite solutions maintain cost advantages in municipal water treatment infrastructure.
- Phenolic:Legacy formulations face ECHA BPR renewal bottlenecks as active substance suppliers consolidate.
Hydrogen peroxide absorbs the bulk of installed capacity; quaternary ammonium is expanding most quickly.
Application:
Volume concentration diverges between acute care networks with standardized formulary mandates and fragmented hospitality operators with variable compliance thresholds.
- Medical Facilities:Operating suites and isolation rooms drive demand for EPA-registered hospital-grade disinfectants with sub-one-minute contact times against enveloped viruses.
- Food Processing:USDA-inspected facilities require no-rinse sanitizers for food-contact surfaces, with chlorine-based compounds dominating poultry and red meat operations.
- Pharmaceutical Manufacturing:EU GMP Annex 1 compliance drives adoption of sporicidal hydrogen peroxide vapor systems for cleanroom terminal disinfection.
- Hospitality Services:Hotel housekeeping departments balance guest turnaround speed against occupational exposure limits for volatile organic compounds.
- Public Transportation:Mass transit authorities in Tokyo and London deploy electrostatic spraying systems for rapid fleet decontamination.
Medical facilities command the steepest pricing premiums; food processing delivers the highest volume throughput.
End User:
Procurement sophistication scales with institutional scale, with integrated delivery networks consolidating purchasing power that individual nursing homes cannot match.
- Hospitals:Infection control committees mandate rotation between disinfectant classes to mitigate antimicrobial resistance development in high-acuity units.
- Dental Clinics:OSHA bloodborne pathogen standards require intermediate-level disinfection for semi-critical instruments between patients.
- Veterinary Clinics:Companion animal practices favor quaternary ammonium formulations for low corrosion against examination table surfaces.
- Laboratory Settings:Biosafety level containment facilities require validated decontamination protocols for biological safety cabinets.
- Nursing Homes:CMS survey deficiencies for environmental cleaning drive investment in automated dispensing systems to standardize dilution ratios.
Hospitals anchor contract value; nursing homes are gaining share fastest as long-term care infection control regulations tighten.
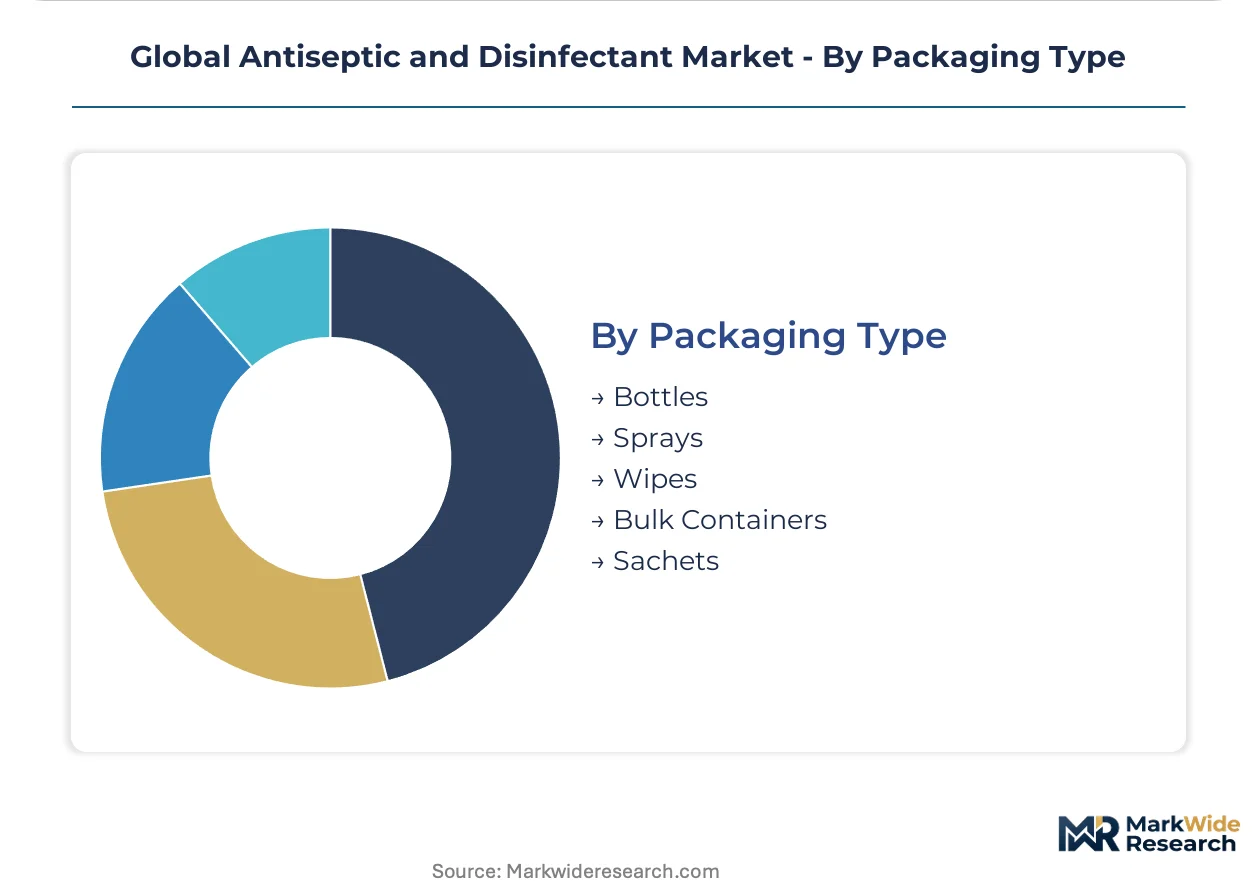
Packaging Type:
Distribution economics favor bulk formats for high-volume institutional accounts while convenience positioning sustains premium pricing in mobile and retail channels.
- Bulk Containers:Five-gallon carboys and totes serve hospital environmental services departments with automated dilution control systems.
- Wipes:Presaturated nonwoven substrates eliminate dilution errors in dental operatories and phlebotomy stations.
- Sprays:Trigger and aerosol formats dominate hospitality housekeeping carts for spot disinfection of high-touch surfaces.
- Bottles:Retail-sized containers serve veterinary clinic reception areas and small dental practices.
- Sachets:Single-use packets support field deployment in emergency medical services and disaster response contexts.
Bulk containers dominate procurement tonnage; wipes are climbing the fastest as point-of-use convenience reshapes clinical workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isopropyl alcohol feedstock availability from petrochemical crackers in the US Gulf Coast and propylene supply chains in Rotterdam anchor regional production economics. Hospital procurement consolidation and biocidal product authorization timelines reshape competitive access across major economies.
United States
Integrated delivery networks in Texas and California mandate single-source disinfectant contracts across affiliated facilities. EPA accelerated review pathways for emerging pathogens shorten time-to-market for novel actives. The Gulf Coast petrochemical corridor supplies isopropyl alcohol feedstock to alcohol-based hand rub manufacturers facing margin compression.
Germany
Healthcare procurement consortia prioritize suppliers with completed ECHA substance evaluations for quaternary ammonium formulations. ECHA biocidal product regulation compliance requirements drive preference for pre-authorized active substance combinations. The Rhine-Ruhr industrial cluster hosts specialized esterification reactor capacity for REACH-compliant twin-chain dimethyl ammonium chloride production.
China
Dependence on Zhejiang and Jiangsu province suppliers for chlorhexidine gluconate intermediates creates geopolitical exposure for downstream formulators. The country's national pharmaceutical regulator aligns with international standards for active pharmaceutical ingredient quality. The Yangtze River Delta concentration of chemical manufacturing capacity supplies both domestic hospital systems and export markets.
India
Low penetration of alcohol-based surgical hand preparation in tier-2 and tier-3 cities creates whitespace for pre-operative antiseptic kits. CDSCO oversees antiseptic drug approvals for hospital and outpatient clinic distribution. Maharashtra and Gujarat pharmaceutical manufacturing clusters expand production of chlorhexidine-based formulations for domestic and export demand.
Japan
Automated room decontamination systems integrating UV-C and hydrogen peroxide vapor displace manual terminal cleaning in Tokyo acute care facilities. METI promotes adoption of advanced sterilization technologies in healthcare infrastructure. The Kanto region's hospital networks deploy electrostatic spraying systems for rapid fleet decontamination in mass transit corridors.
Global Antiseptic and Disinfectant Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and service integration dimensions. The vendor base spans diversified chemical conglomerates, specialized infection control service providers, and consumer health product manufacturers. Three archetypes dominate: integrated sterilization service contractors, concentrated formulation technology specialists, and broad hygiene product portfolios with healthcare verticals. M&A activity concentrates in hospital service integration, while capacity expansion targets REACH-compliant quaternary ammonium production in European manufacturing hubs.
Among US-based diversified industrials, 3M and Steris occupy distinct positioning archetypes within the competitive structure. 3M exemplifies concentrated formulation technology leadership through hydrogen peroxide innovation. Steris represents the integrated sterilization service contractor model anchoring long-term hospital partnerships through bundled equipment and consumable contracts. Reckitt Benckiser Group sits within the consumer health-to-professional hygiene bridge tier, leveraging retail brand recognition into institutional procurement channels.
| Leading Market Players |
|---|
| Steris |
| 3M |
| Reckitt Benckiser Group |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Procter & Gamble |
| The Clorox Company |
| Ecolab |
| BD |
| Others |
Supply & Pricing Matrix
EU Green Deal biocidal sustainability criteria gates qualified supply and premium-tier pricing access, forcing formulators to invest in biodegradable surfactant development or accept exclusion from Nordic hospital procurement channels. REACH-compliant manufacturers capture fifteen to twenty percent pricing premiums over legacy suppliers while non-compliant portfolios face volume erosion.
Pricing Analysis
Equipment-and-service bundling separates integrated sterilization contracts from unbundled chemical-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ECHA authorization status, contact time performance, and dilution automation compatibility. Pricing pressure stems from consolidated purchasing through regional healthcare alliances in Texas and California. Nursing homes exhibit highest price sensitivity due to CMS reimbursement constraints; pharmaceutical manufacturing anchors premium tolerance through EU GMP Annex 1 compliance mandates.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand while distribution partners serve fragmented veterinary and dental segments. Manufacturing concentrates in Germany, the United States, and China, with Zhejiang and Jiangsu provinces supplying chlorhexidine gluconate intermediates. Propylene feedstock draws from Gulf Coast and Rotterdam crackers, tethering alcohol-based formulation costs to petrochemical volatility. Single-source vulnerability in Chinese active pharmaceutical ingredient concentration creates geopolitical exposure for downstream formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrostatic spraying and hydrogen peroxide vapor systems are displacing manual terminal cleaning protocols, compressing margins for legacy chemical-only suppliers while rewarding hardware-integrated service providers.
For Market Incumbents: Deploy ECHA substance evaluation completion as a competitive moat. Accelerate twin-chain dimethyl ammonium chloride esterification capacity in Rhine-Ruhr industrial clusters to capture German healthcare procurement consortium preference. Secure backward integration into propylene feedstock through Gulf Coast petrochemical partnerships to defend margin position against isopropyl alcohol volatility. For New Entrants and Emerging Players: Begin with tier-2 and tier-3 Indian outpatient clinics where alcohol-based surgical hand preparation penetration remains underdeveloped. Target veterinary companion animal practices seeking low-corrosion quaternary ammonium alternatives. Pursue co-development partnerships with electrostatic spraying hardware manufacturers to bypass direct chemical registration barriers. For Investors and Strategic Acquirers: ECHA BPR renewal timeline delays for legacy phenolic formulations signal authorization bottleneck inflection that will consolidate active substance supplier positions. Five-to-ten year viability favors integrated sterilization service contractors with captive hospital system relationships over standalone chemical manufacturers. Monitor EPA accelerated review pathway approvals for emerging pathogen claims as leading indicator of novel active commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Development | Biodegradable surfactant investments unlock Nordic hospital procurement premium tiers. |
| Integrated Sterilization Service Contracts | Equipment-and-consumable bundling anchors long-term hospital partnership stickiness. |
| Electrostatic Spraying System Integration | Hardware partnerships reduce surface contact times and automate Joint Commission documentation. |
| Backward Integration into Propylene Feedstock | Gulf Coast petrochemical partnerships insulate alcohol-based formulation margins from supply disruption. |
| Indian Outpatient Clinic Distribution Buildout | Tier-2 and tier-3 city whitespace captures pre-operative antiseptic kit demand. |
Research Methodology
Multi-period observation of EPA registration timelines, ECHA authorization bottlenecks, and hospital procurement consolidation patterns anchored the trend analysis, supplemented by interviews with infection control committee chairs, environmental services directors, GPO contracts managers, and biocidal product regulatory affairs specialists. Secondary validation drew from FDA antiseptic drug monograph updates, EPA disinfectant efficacy claim databases, ECHA BPR substance evaluation registers, and customs trade data. Bottom-up formulation demand modeling triangulated against top-down healthcare expenditure projections.
Input-output matrices mapped active ingredient supply through formulation manufacturing to end-use application across the projection horizon. Segmentation dimensions included product chemistry class, application context, end-user institutional scale, and packaging format. CAGRs derived from weighted average of historical volume trajectories and forward-looking regulatory event schedules. Forecast inputs incorporated WHO protocol update implementation velocity and integrated delivery network contract consolidation rates.
Underlying measurement precision varies by segment; hospital procurement data carries tighter precision than fragmented hospitality operator estimates. Forecasts reflect assumptions regarding ECHA renewal timeline adherence and propylene supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Hypochlorite Bleaches Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Nisin Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Clinical Grade Disinfectant Market
Disinfectants and Preservatives
Sodium Nitrite Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Preservatives Market