
 Europe Digital Signage Market | 2026-2036
Europe Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Signage Market Foresight
Content management subscription services is expanding how vendors monetize hardware deployments across Europe. Samsung Electronics Co Ltd leverages its display manufacturing scale to bundle cloud-based software with screen installations. LG Electronics Inc ADR anchors its European position through specialized OLED panels for premium retail environments. Sharp NEC Display Solutions Europe GmbH competes on extended warranty and field maintenance contracts that lock in multi-year client relationships.
Europe digital signage encompasses networked electronic display systems comprising LCD, LED, and OLED panels with integrated media players, connectivity modules, and content management platforms, typically operating at 4K resolution with brightness ratings exceeding 2500 nits for window-facing installations. These systems deliver dynamic visual communication for advertising, wayfinding, and real-time information dissemination in commercial and public spaces. LED displays capture the largest installed base due to durability and outdoor readability, while OLED panels command premium positioning in luxury retail and corporate lobbies where contrast ratios and thin form factors justify higher expenditure. The hospitality application segment shows strong momentum as hotels deploy interactive wayfinding and concierge screens across lobbies and conference facilities.
REACH compliance and the EU Green Deal's ecodesign requirements shape material selection and energy consumption benchmarks for display manufacturers selling into Europe. The EU AI Act introduces transparency obligations for signage systems employing facial analytics or audience measurement algorithms, affecting how vendors architect data processing pipelines. Stakeholders must weigh hardware standardization against software customization as regulatory complexity and client-specific content needs diverge across national markets.
Market Dynamics
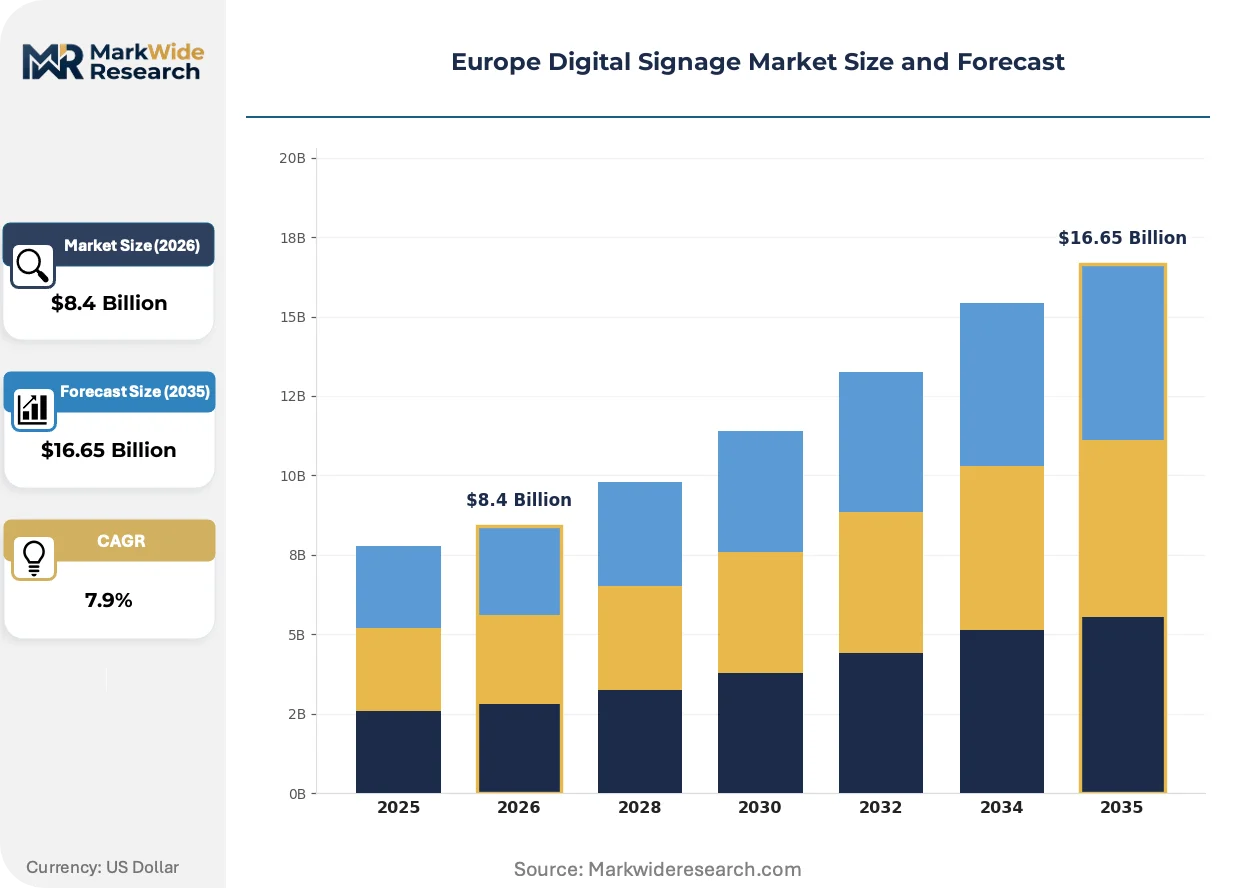
Content management subscription services are restructuring vendor revenue models across Europe, decoupling hardware margins from recurring software income streams. The EU Green Deal's ecodesign mandates and the EU AI Act's transparency requirements are simultaneously reshaping product roadmaps and data architectures for display manufacturers.
Growth Catalysts
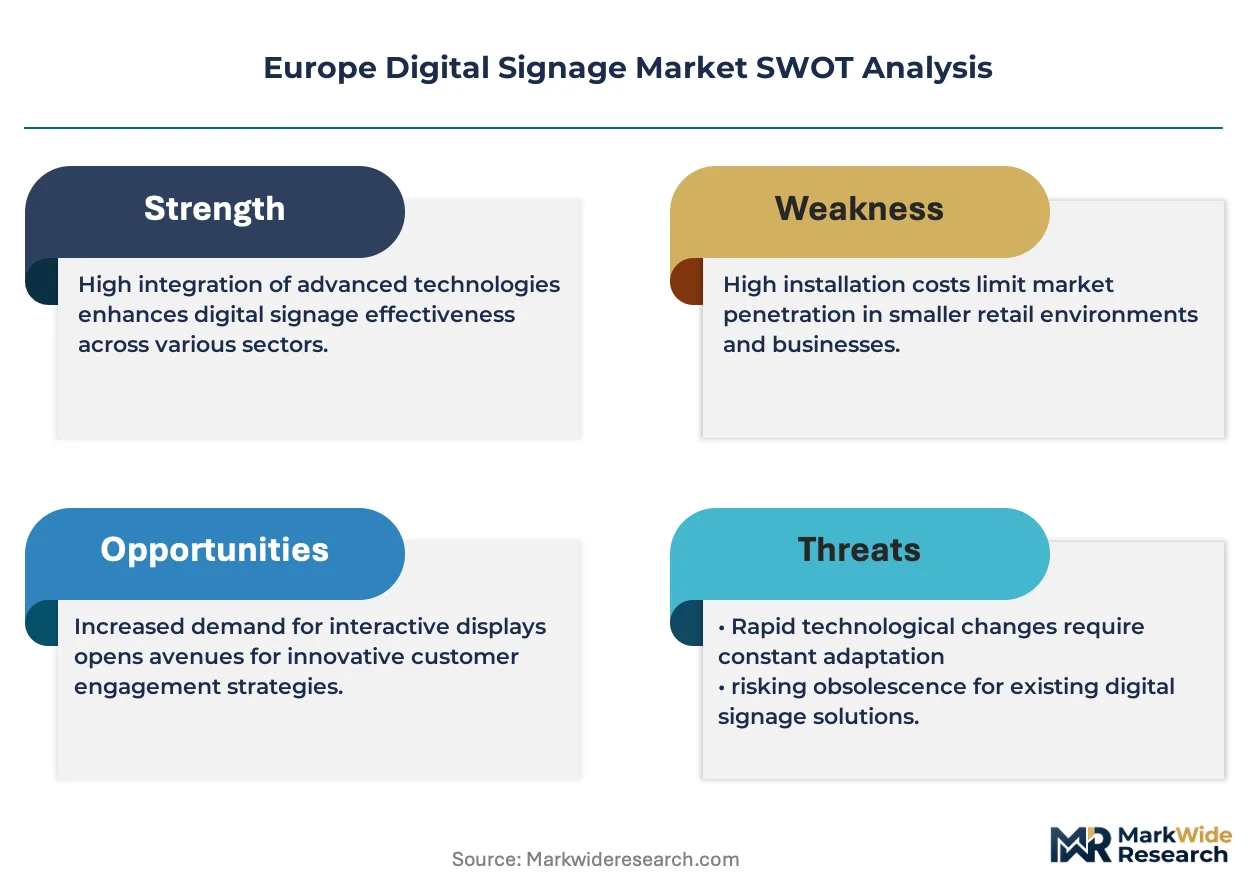
- EU Green Deal ecodesign mandates:Energy efficiency benchmarks are accelerating replacement cycles for aging fluorescent-backlit installations across French retail chains and German transit authorities.
- France's urban transit modernization:RATP and SNCF are expanding screen density in Paris Métro stations and Gare du Nord for real-time passenger information and commercial advertising.
- OLED panel technology maturation:Manufacturing yield improvements are reducing unit costs for premium retail deployments in Milan and London luxury districts.
Market Restraints
- Indium and gallium supply concentration:OLED manufacturing depends on rare earth elements sourced predominantly through Chinese refining operations, creating input cost volatility.
- REACH compliance complexity:ECHA substance restrictions on flame retardants and plasticizers are extending material qualification timelines for enclosure manufacturers.
- Projector-based alternatives:Laser projection systems are capturing temporary event signage contracts where installation flexibility outweighs brightness requirements.
Strategic Opportunities
- Poland and Czech Republic retail modernization:Shopping mall operators in Warsaw and Prague are accelerating digital screen deployment to match Western European fixture standards.
- EU AI Act transparency frameworks:Compliance tooling for audience analytics is creating adjacent software revenue streams for hardware vendors.
- Edge computing convergence:On-device processing for content rendering and analytics is reducing bandwidth dependencies for rural hospitality deployments.
Industry Challenges
- Embedded systems cybersecurity certification:IEC 62443 compliance for networked displays requires specialized firmware engineering capabilities scarce among traditional AV integrators.
- Legacy CMS migration complexity:Hotels and retail chains operating decade-old proprietary platforms face multi-year transition timelines to cloud-native architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Signage Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.65 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, Projectors Application: Retail, Transportation, Hospitality, Education End User: Corporate, Government, Healthcare, Entertainment Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Samsung Electronics Co Ltd, nsign, Sharp NEC Display Solutions Europe GmbH, BrightSign, SpinetiX, Panasonic Industry, Daktronics Inc, Allsee Technologies, LG Electronics Inc ADR, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Signage Market Shifts & Advancements
Software-defined display management is fragmenting traditional hardware-centric business models. Vendors are repositioning around data services and interoperability rather than panel specifications alone.
Edge-based content rendering is decentralizing processing architectures for European digital signage networks. Retail operators in Germany are deploying media players with local AI inference capabilities for real-time audience analytics. This distributed computing model is reducing latency for personalized content triggers while limiting cloud data transfer volumes subject to GDPR scrutiny.
REACH substance restrictions are forcing material transitions across display supply chains. ECHA candidate list updates on microplastics and persistent organic pollutants are compelling enclosure manufacturers to reformulate polycarbonate blends and coating chemistries. Panel assemblers serving the French market are accelerating validation of bio-based alternatives to halogenated flame retardants.
Subscription-based hardware procurement is displacing capital expenditure models among mid-sized European retailers. Dutch and Belgian hospitality groups are adopting managed service contracts bundling installation, content management, and field maintenance into per-screen monthly fees. This financing shift is compressing vendor sales cycles while extending customer lifetime value horizons.
Europe Digital Signage Market Segmentation
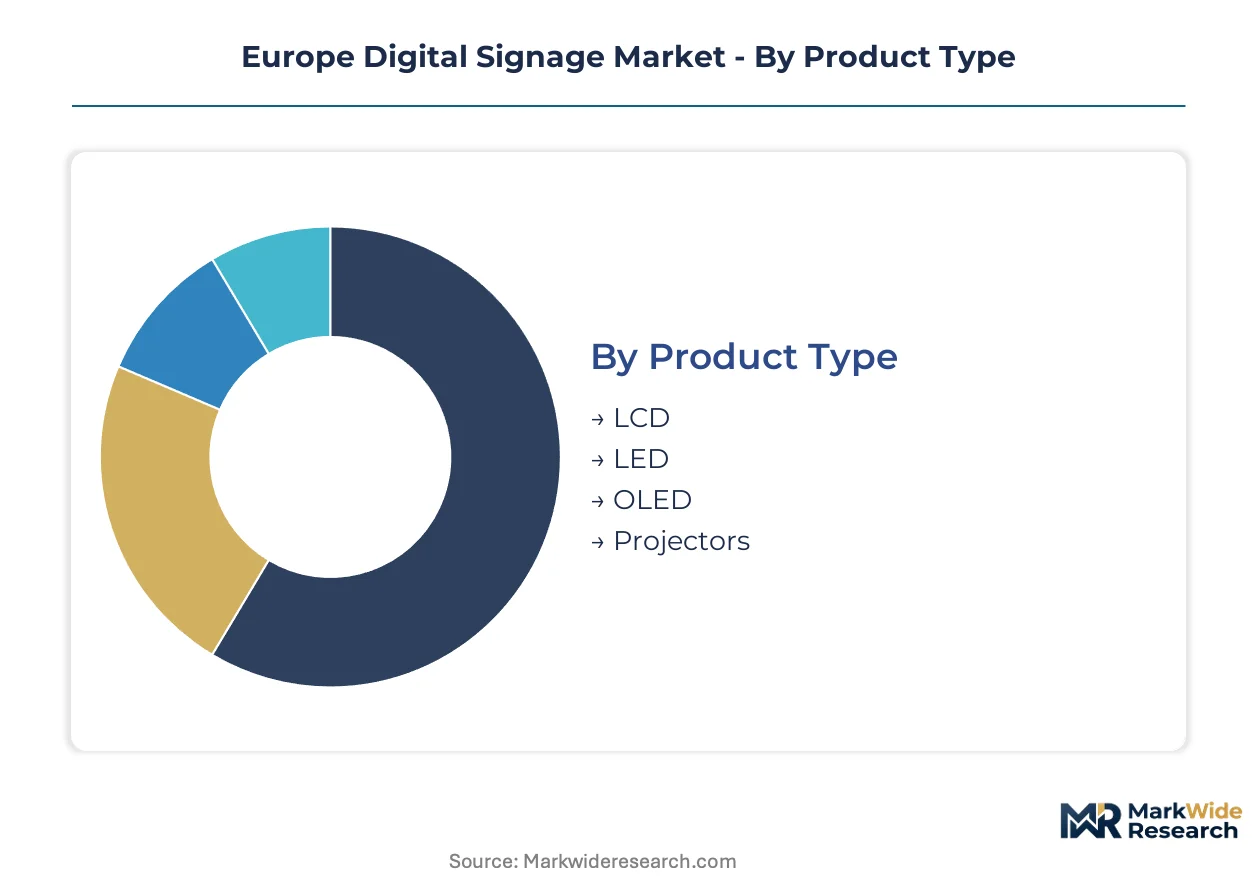
Digital signage purchasing decisions in Europe diverge sharply across product technologies, deployment settings, and procurement channels. Each segment carries distinct compliance obligations under REACH, CE marking, and the EU AI Act that shape vendor qualification requirements and buyer evaluation criteria.
Product Type:
LED panels face lighter substance-restriction burdens than OLED equivalents, while LCD legacy fleets trigger accelerated replacement timelines under Green Deal ecodesign mandates.
- LED:Direct-view LED modules with pixel pitches ranging from 0.9mm indoor to 16mm outdoor configurations dominate high-brightness transit and stadium deployments. German transport authorities and French airport operators specify these for daylight-readable passenger information systems, with energy efficiency benchmarks now filtering procurement shortlists.
- LCD:TFT-LCD panels with edge-lit or direct-lit LED backlights retain cost advantages for indoor retail fixture networks. Italian and Spanish retail chains continue bulk purchasing of 55-inch and 65-inch commercial-grade units despite accelerating OLED substitution in premium positioning.
- OLED:Self-emissive panels with infinite contrast ratios and sub-4mm profiles command luxury retail and corporate lobby specifications in London and Milan, though indium supply concentration inflates unit economics.
- Projectors:Laser-phosphor and RGB laser projection systems capture temporary event signage and immersive experience installations where screen permanence is impractical.
LED sits at the top of the volume ranking, with OLED climbing the fastest.
Application:
Transportation deployments concentrate in France and Germany, while hospitality spending spreads more evenly across mid-tier European markets.
- Retail:In-store digital fixtures for promotional content and endless-aisle kiosks absorb the largest share of annual installations. Polish and Czech mall operators are replicating Western European screen density standards.
- Transportation:Real-time passenger information and advertising networks in Paris Métro stations, Gare du Nord, and Berlin Hauptbahnhof require 24/7 operational reliability and centralized content orchestration.
- Hospitality:Interactive wayfinding, concierge interfaces, and conference room booking displays are expanding across Dutch and Belgian hotel portfolios under managed service procurement models.
- Education:Campus-wide digital communication and hybrid learning infrastructure are gaining traction in Scandinavian universities and UK further education colleges.
Retail captures the dominant revenue position, with hospitality expanding most quickly.
End User:
Corporate buyers prioritize interoperability and cloud-native CMS architectures, while government purchasers emphasize cybersecurity certification and extended warranty terms.
- Corporate:Headquarters lobbies, meeting room signage, and employee communication networks drive demand for premium OLED and fine-pitch LED specifications.
- Government:Municipal information kiosks, public building directories, and citizen service portals require IEC 62443 cybersecurity compliance and open procurement frameworks.
- Healthcare:Wayfinding, queue management, and clinical staff communication systems in NHS trusts and German hospital networks demand antimicrobial surface treatments and HIPAA-aligned data handling.
- Entertainment:Cinemas, concert venues, and gaming establishments deploy immersive LED canvases and projection mapping for experiential differentiation.
Corporate maintains the largest installed base, with healthcare gaining share fastest.
Distribution Channel:
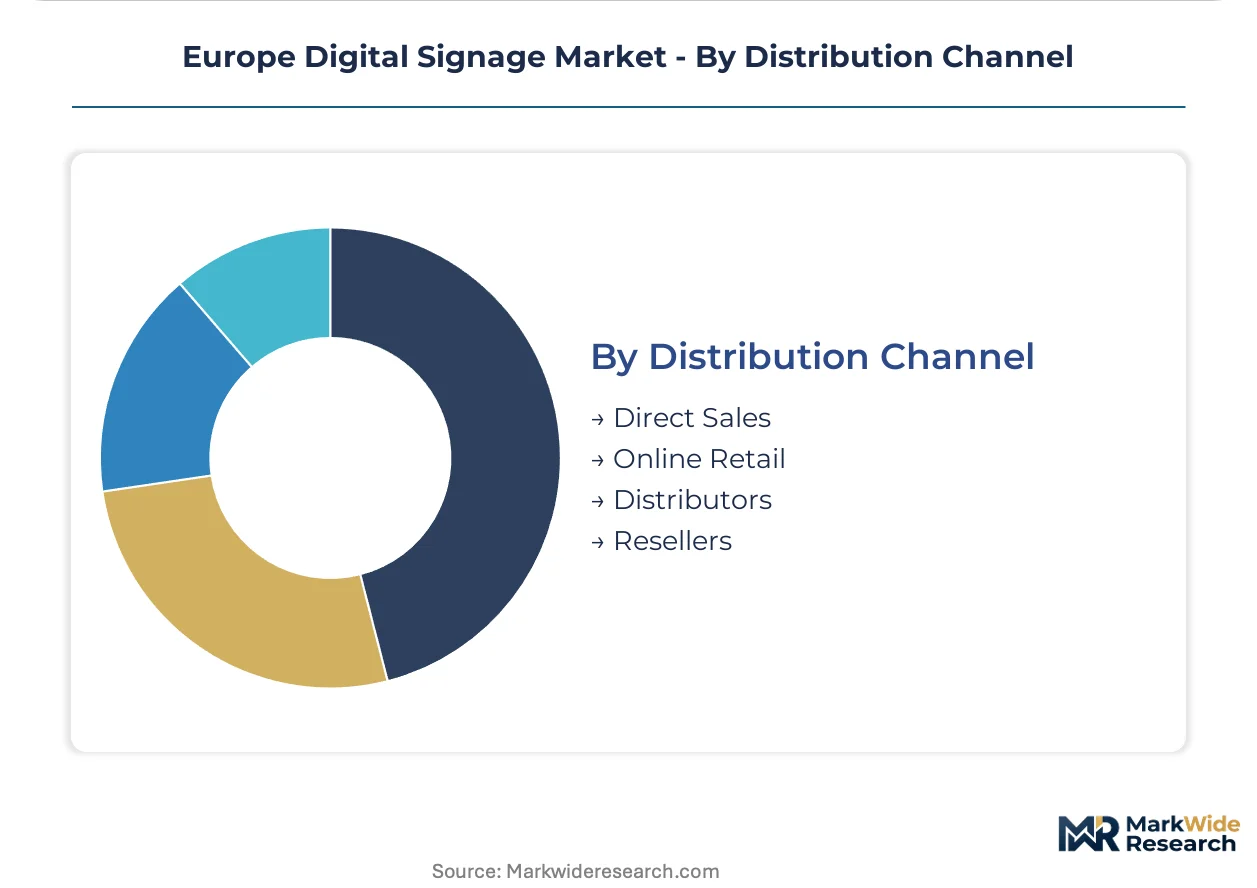
Direct relationships dominate large-format and custom-configuration sales, while standardized products flow increasingly through digital procurement platforms.
- Direct Sales:Manufacturer field organizations engage multinational retail chains and transport authorities on multi-site rollout programs with bespoke integration requirements.
- Online Retail:E-commerce platforms capture small-format and replacement-unit transactions from independent retailers and SME hospitality operators.
- Distributors:Pan-European AV distributors maintain regional inventory positions and credit facilities for systems integrators serving mid-market accounts.
- Resellers:Specialized AV integrators and IT resellers bundle installation, content management, and maintenance services into recurring-revenue contracts.
Direct sales leads by transaction value, with resellers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance costs and EU Green Deal implementation timelines create uneven competitive terrain across Europe. Vendors face sharper cost-of-compliance gaps between established Western European markets and emerging Central European deployments, redirecting manufacturing investment and service center placement toward jurisdictions with streamlined permitting.
Germany
Berlin Hauptbahnhof and Munich Hauptbahnhof drive demand for 24/7 operational LED passenger information systems. The KBA's rail safety standards mandate redundant connectivity modules for transit signage. Bavarian industrial clusters around Munich and Nuremberg host systems integrators specializing in Deutsche Bahn specification compliance.
France
RATP's Paris Métro modernization and SNCF's Gare du Nord expansion absorb fine-pitch LED and OLED commercial displays. ANSM's transparency requirements for biometric analytics shape AI-enabled signage architectures. Île-de-France concentration of luxury retail in Paris and La Défense pulls premium OLED panel procurement.
United Kingdom
NHS trusts deploy antimicrobial-surface wayfinding systems across hospital networks with HIPAA-aligned data handling. The Information Commissioner's Office enforces GDPR constraints on audience measurement algorithms. London's corporate lobby and retail fixture density anchors premium specification demand.
Netherlands
Amsterdam Schiphol and Rotterdam port terminals specify high-brightness outdoor LED for passenger and logistics communication. Dutch managed service procurement models bundle installation, content management, and maintenance into per-screen monthly fees. Eindhoven's technology corridor hosts edge-computing media player development for real-time analytics.
Poland
Warsaw shopping mall operators accelerate screen density to match Western European fixture standards ahead of EU funding cycles. Polish regulatory alignment with REACH and CE marking proceeds on extended timelines, attracting vendor assembly investment. Kraków and Wrocław hospitality groups adopt cloud-native CMS architectures through distributor credit facilities.
Europe Digital Signage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack display vendors capturing premium transit and corporate contracts while white-label assemblers serve price-sensitive retail replacement cycles. Market structure tilts toward consolidated procurement at the top tier—multinational transport authorities and retail chains—while fragmenting across mid-market hospitality and education accounts. Three archetypes dominate: integrated display-and-software vendors, pure-play CMS platform providers, and regional systems integrators with captive installation capabilities. Competitive moves center on subscription revenue model migration and cybersecurity certification pre-qualification for government tenders.
Among Korean and Japanese electronics conglomerates, Samsung Electronics Co Ltd and LG Electronics Inc ADR exemplify integrated-architecture positioning, bundling panel manufacturing with cloud-based content management platforms. Sharp NEC Display Solutions Europe GmbH occupies a distinct tier through extended warranty and field maintenance contracting that locks in multi-year client relationships across German and French transit authorities. These three anchors illustrate divergent paths to recurring revenue: hardware-software bundling, premium specification leadership, and service-contract stickiness.
| Leading Market Players |
|---|
| Samsung Electronics Co Ltd |
| nsign |
| Sharp NEC Display Solutions Europe GmbH |
| BrightSign |
| SpinetiX |
| Panasonic Industry |
| Daktronics Inc |
| Allsee Technologies |
| LG Electronics Inc ADR |
| Others |
Supply & Pricing Matrix
French transit authority consolidation around 24/7 operational specifications and REACH-compliant enclosures is compressing supplier margins while elevating certified component premiums. Vendors must absorb extended material qualification timelines or forfeit procurement shortlists, bifurcating pricing power between qualified incumbents and speculative challengers.
Pricing Analysis
Distributor margins spanning 15-25 percent separate pan-European AV distributors from direct manufacturer relationships with RATP and Deutsche Bahn. Three-tier pricing structure across premium OLED, standard LED, and economy LCD tiers reflects certification grade and after-sales bundling intensity. Cost compression in LCD replacement cycles intensifies as Polish retail chains replicate Western fixture standards. Government transport authorities exhibit lowest price sensitivity due to cybersecurity pre-qualification requirements, while independent hospitality operators drive hardest bargain hunting on per-screen monthly fees.
Supply Chain Analysis
CE marking and IEC 62443 cybersecurity certification gating extends lead times for enclosure manufacturers reformulating halogenated flame retardant alternatives. Panel assembly concentrates in South Korea, China, and Taiwan, with media player integration shifting toward Eindhoven and Munich technology corridors. Indium and gallium sourcing for OLED manufacturing draws from Chinese refining operations, creating single-source vulnerability for premium panel supply. Distribution runs through specialized AV integrators bundling installation and cloud-native CMS migration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED yield improvements and subscription revenue model migration are expanding service gross margins faster than hardware depreciation erodes capital returns. Vendors capturing compliance tooling adjacencies under EU AI Act transparency mandates command premium positioning.
For Market Incumbents: To counter projector-based alternatives capturing temporary event signage contracts, Samsung and LG should deepen captive supply of edge-computing media players with local AI inference capabilities. Extend field maintenance contract stickiness through cybersecurity certification pre-qualification for German KBA rail safety tenders. For New Entrants and Emerging Players: EU AI Act transparency frameworks in France open a window for compliance software specialists to attach audience analytics tooling to hardware deployments. Target Warsaw and Prague shopping mall operators accelerating screen density ahead of EU funding cycles with distributor credit-backed managed service offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native CMS platform providers unburdened by legacy hardware manufacturing overhead. Five-to-ten year viability favors vendors with recurring revenue exceeding sixty percent of total mix. Watch for inflection when edge-computing media player volumes surpass centralized cloud rendering in hospitality procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Pre-Qualification | IEC 62443 compliance unlocks German transit authority tenders and extends contract durations. |
| Edge Computing Media Player Development | Local AI inference capabilities reduce GDPR cloud transfer exposure for French retail analytics. |
| REACH-Compliant Material Transition | Bio-based flame retardant validation secures French market access under ECHA candidate list updates. |
| Subscription Revenue Model Migration | Per-screen monthly fees compress sales cycles and extend customer lifetime value horizons. |
| Managed Service Bundling | Installation, CMS, and maintenance consolidation captures Dutch hospitality procurement preferences. |
Research Methodology
Bottom-up retail and transportation deployment modeling reconciled against top-down panel manufacturing tracking forms the analytical core. Primary interviews with display procurement managers at French transit authorities, German systems integrators, Dutch hospitality groups, and Polish mall operators combined with secondary validation against ECHA substance restriction updates, EU Green Deal ecodesign implementing measures, and customs trade data for display module imports.
Historical trendline analysis of replacement cycle timing and technology substitution patterns informed projection assumptions across the analysis window. Segmentation dimensions modeled include product technology tier, application setting, procurement channel, and national regulatory alignment timeline. CAGRs derived from unit volume trajectories weighted by average selling price evolution, incorporating OLED yield improvement curves and LED energy efficiency benchmark adoption rates.
Revisions become necessary when EU AI Act implementing guidance alters transparency obligation scope or when indium supply disruption triggers OLED panel allocation protocols. Forecasts reflect assumptions about REACH substance restriction timelines and Green Deal ecodesign enforcement intensity. A model refresh is warranted upon material change in edge-computing media player penetration rates or cybersecurity certification requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Conference Room Solutions Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Legaltech Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Data Monetization Market
Digital Solutions
Thin Client Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Dataops Platform Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Decision Support System Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Kazakhstan ICT Market