
 Dataops Platform Market | 2026-2036
Dataops Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Dataops Platform Market Insights
ISO 27001 certification is collapsing the vendor qualification cycle for enterprise DataOps procurement, compressing vendor evaluation from months to weeks. Microsoft Corporation leverages its Azure-native integration to anchor cloud-based deployments across regulated industries. Databricks sustains technology leadership through its lakehouse architecture, while Informatica competes aggressively on data quality specialization for hybrid environments.
A DataOps platform orchestrates the continuous integration, testing, and deployment of data pipelines through automated workflows, schema validation, and real-time monitoring across distributed architectures. Its primary commercial purpose is eliminating data engineering bottlenecks that stall analytics and machine learning initiatives. Cloud-based deployment now captures the fastest expansion as enterprises abandon capital-intensive on-premise infrastructure, while data integration solutions command the deepest margin pools due to their position at the pipeline entry point. Workflow automation within the solution layer is maturing rapidly as vendors embed generative AI for pipeline generation.
The EU AI Act and GDPR compliance requirements are reshaping platform feature roadmaps, particularly around data lineage and auditability for automated decision systems. The US SEC and FDA are intensifying scrutiny of data provenance in financial reporting and clinical trials, directly gating market access for vendors lacking granular governance capabilities. Enterprises must evaluate whether their current DataOps architecture can absorb emerging algorithmic accountability standards without wholesale replacement.
Market Dynamics
Cloud migration mandates under the EU AI Act and comparable data governance frameworks are compressing enterprise procurement cycles while forcing wholesale architecture replacements. ISO 27001 certification now functions as a binary gate for vendor qualification across regulated industries.
Growth Catalysts
- EU AI Act Compliance Mandates:Automated decision system auditability requirements are forcing financial services firms to modernize legacy data pipelines. Real-time lineage tracking has become non-negotiable for market access.
- Generative AI Pipeline Generation:Workflow automation vendors are embedding large language models to auto-generate data transformation code. Data engineering teams are redeploying from boilerplate coding to architecture design.
- India's Digital Public Infrastructure Expansion:Enterprise modernization initiatives across banking and telecommunications are creating concentrated demand for cloud-native DataOps platforms. The country's central bank guidelines on data localization are accelerating platform investments.
Market Restraints
- Specialized Talent Scarcity:Data engineering expertise combining pipeline orchestration with governance automation commands premium compensation. Skills gaps in schema validation and distributed systems architecture are extending implementation timelines.
- Hybrid Environment Complexity:Enterprises maintaining on-premise data lakes alongside cloud warehouses face integration friction. Vendor solutions optimized for single-environment deployments struggle with cross-architecture consistency.
- Input Cost Volatility in Cloud Compute:GPU-intensive workloads for AI/ML pipelines are exposed to hyperscaler pricing fluctuations. Reserved instance commitments lock buyers into vendor-specific cost structures.
Strategic Opportunities
- Underpenetrated Manufacturing Vertical:Industrial IoT data streams remain largely unorchestrated across German automotive and machinery sectors. Predictive maintenance pipelines represent a greenfield application for DataOps tooling.
- Regulatory Tailwind from US SEC Climate Disclosure Rules:Granular emissions data collection and audit trails are creating new compliance-driven procurement. Sustainability reporting automation is emerging as a distinct product category.
- Edge-to-Cloud Architecture Convergence:5G-enabled manufacturing and autonomous vehicle development are generating distributed data pipelines. Platforms supporting federated query execution across edge nodes and central warehouses are capturing early design wins.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Enterprises distributing workloads across AWS, Azure, and Google Cloud face inconsistent metadata management. Cross-platform lineage tracking requires custom integration layers that erode automation benefits.
- ISO 27001 Certification Timeline Compression:Vendor qualification cycles have collapsed from quarters to weeks, straining documentation and audit preparation resources. Certification maintenance costs are rising with annual surveillance requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dataops Platform Market |
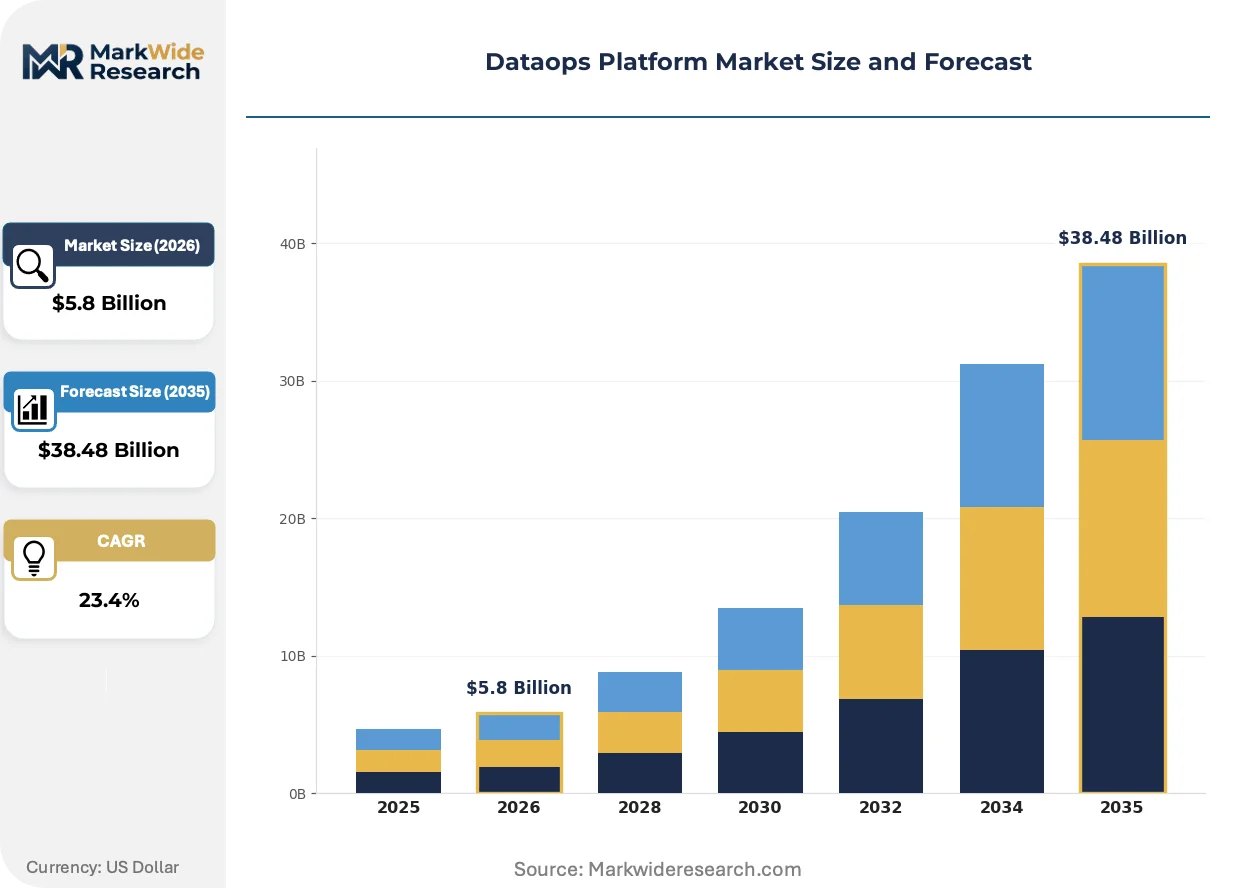
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $38.48 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud Solution: Data Integration, Data Quality, Workflow Automation, Monitoring Tools End User: Financial Services, Retail, Healthcare, Telecommunications Service Type: Consulting, Managed Services, Support Services, Training |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, Amazon Web Services, Informatica, Teradata Corporation, Databricks, DataOps.live, DataKitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dataops Platform Market Trends and Innovations
Generative AI capabilities are redefining pipeline construction workflows while regulatory pressure on algorithmic accountability intensifies technical requirements. Platform differentiation is shifting from connector breadth to governance depth.
Lakehouse architecture is decomposing the traditional warehouse-lake binary that has structured enterprise data strategy for a decade. Financial services firms in the United States and Germany are adopting unified storage-compute layers at accelerated pace. This convergence is decomposing vendor moats built on either pure warehouse optimization or raw data lake flexibility.
The EU AI Act's risk-based classification system for automated decision-making is mandating granular data provenance documentation. High-risk AI system deployers must maintain complete audit trails from training data through inference outputs. Healthcare and credit scoring applications in EU member states are investing heavily in lineage automation to meet conformity assessment timelines.
Enterprise buyers are unbundling professional services from platform subscriptions, demanding transparent API-first pricing for core orchestration capabilities. System integrators and boutique consultancies are capturing implementation and change management margins that vendors previously monopolized. This disaggregation is most visible in the United States, where procurement teams are standardizing on multi-year platform deals with separately negotiated service statements of work.
Dataops Platform Market Segmentation
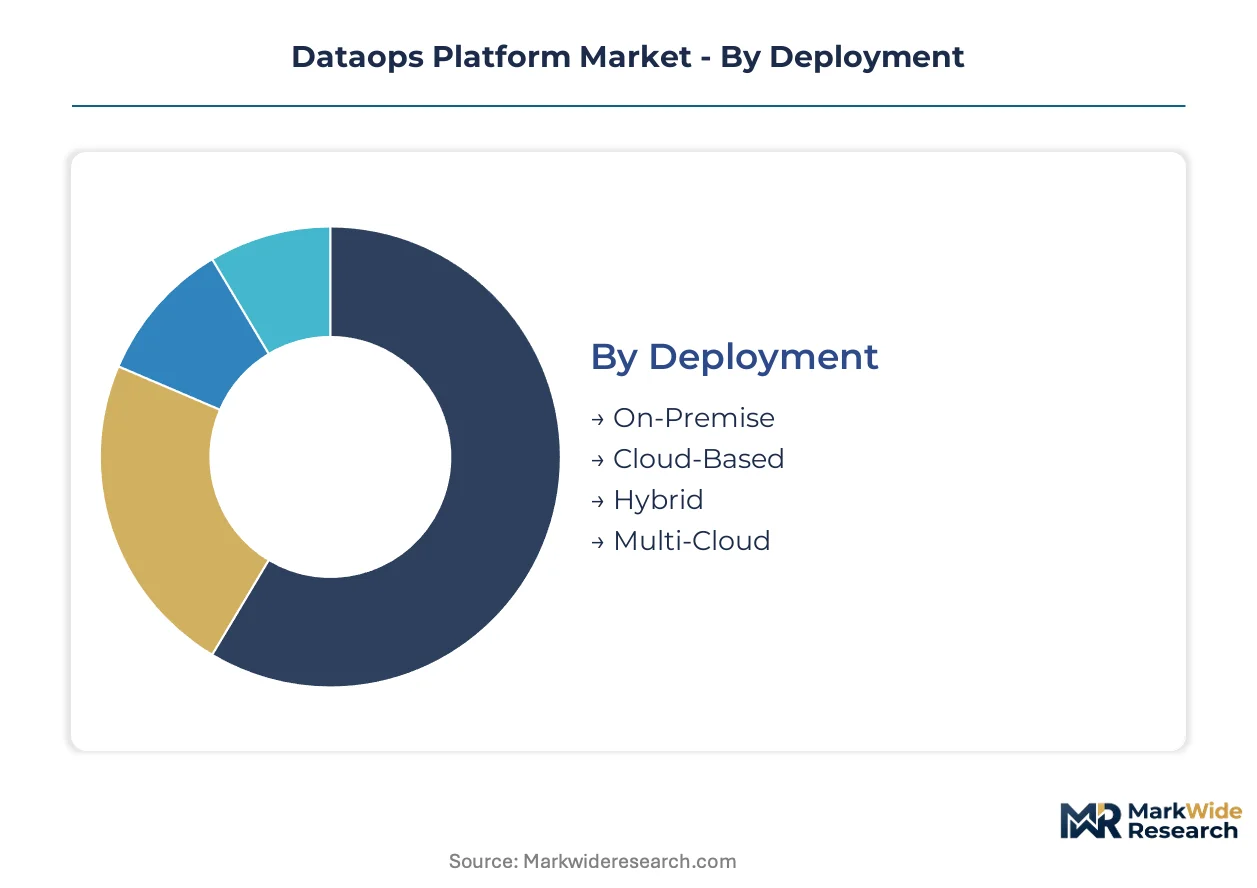
DataOps platform procurement patterns diverge sharply across deployment architectures and governance requirements. Enterprise buyers segment their investments based on regulatory exposure, cloud migration maturity, and internal data engineering capacity.
Deployment:
Cloud-based deployments dominate export-led demand from multinational enterprises, while on-premise retention concentrates in domestic financial services with strict data localization mandates.
- Cloud-Based:Hyperscaler-native orchestration eliminates capital expenditure on physical infrastructure. Financial services firms in Germany and India are migrating core pipelines to cloud-native architectures to satisfy EU AI Act and RBI data localization guidelines simultaneously.
- Hybrid:Split processing across on-premise lakes and cloud warehouses maintains legacy system connectivity. Manufacturing enterprises in the United States retain edge-sensitive workloads on-site while pushing analytics to cloud compute layers.
- On-Premise:Complete infrastructure control for classified government and defense applications.
- Multi-Cloud:Workload distribution across AWS, Azure, and Google Cloud to avoid vendor lock-in.
Cloud-based deployments command the established base. The steepest expansion runs through hybrid architectures bridging legacy and cloud-native stacks.
Solution:
Margin concentration follows pipeline entry-point positioning, with data integration capturing premium pricing for schema validation and connector breadth.
- Data Integration:Unified ingestion from ERP, CRM, and IoT sources through pre-built connector libraries. Healthcare systems in the United States deploy HL7 and FHIR-native pipelines to satisfy FDA audit trail requirements for clinical data provenance.
- Workflow Automation:Generative AI-assisted pipeline generation reduces manual coding overhead. Retail enterprises in Germany automate seasonal demand forecasting pipelines to compress time-to-insight for inventory optimization.
- Data Quality:Automated profiling, cleansing, and validation for downstream analytics reliability.
- Monitoring Tools:Real-time pipeline health dashboards with anomaly detection and alerting.
Data integration solutions anchor the revenue base. Workflow automation is climbing the fastest as generative AI capabilities mature.
End User:
Regulatory intensity varies dramatically across verticals, with financial services and healthcare facing the strictest algorithmic accountability mandates.
- Financial Services:Real-time fraud detection and risk scoring pipelines demand sub-second latency. SEC climate disclosure rules are forcing granular emissions data collection infrastructure across US banking and asset management.
- Healthcare:Clinical trial data lineage and patient record interoperability require HIPAA-compliant orchestration. EU AI Act high-risk system classifications are accelerating investment in automated provenance documentation.
- Retail:Omnichannel customer data unification for personalization and supply chain optimization.
- Telecommunications:Network performance monitoring and subscriber churn prediction at scale.
Financial services represents the deepest spending base. Healthcare is expanding most quickly under regulatory pressure from FDA and EU AI Act conformity assessments.
Service Type:
Enterprise procurement is disaggregating professional services from platform subscriptions, with buyers demanding transparent API-first pricing for core capabilities.
- Managed Services:Outsourced pipeline operations and 24/7 infrastructure monitoring. Mid-market enterprises in India leverage managed services to overcome specialized talent scarcity in distributed systems architecture.
- Consulting:Architecture design and cloud migration strategy for legacy modernization. German automotive firms engage boutique consultancies for industrial IoT pipeline design separate from platform licensing.
- Support Services:Technical issue resolution and platform troubleshooting.
- Training:Certification programs for data engineering teams on specific platform stacks.
Managed services commands the established recurring revenue base. Consulting is gaining share fastest as enterprises unbundle implementation from platform subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in financial services hubs and manufacturing corridors where regulatory pressure intersects with legacy modernization imperatives. Cloud migration mandates from the EU AI Act and RBI data localization guidelines are compressing vendor selection timelines. Buyers prioritize ISO 27001-certified platforms that satisfy multi-jurisdictional compliance requirements.
United States
SEC climate disclosure rules and FDA clinical trial data provenance requirements are driving financial services and healthcare procurement. The SEC mandates granular emissions data collection infrastructure across banking and asset management. New York and Boston financial services clusters are deploying real-time lineage tracking for algorithmic trading systems.
Germany
Automotive and machinery manufacturers are modernizing industrial IoT data pipelines under EU AI Act high-risk system classifications. The EU AI Act mandates complete audit trails from training data through inference outputs for automated decision systems. Bavaria's automotive engineering corridor is investing in predictive maintenance pipeline orchestration.
India
RBI data localization guidelines and digital public infrastructure expansion are accelerating cloud-native platform adoption across banking and telecommunications. The RBI mandates domestic data storage for payment systems and financial transaction records. Mumbai and Bangalore technology clusters are modernizing core banking pipelines to satisfy concurrent EU AI Act and RBI requirements.
United Kingdom
Financial services firms are rebuilding post-Brexit data architectures to maintain EU market access while satisfying domestic regulatory requirements. The UK Financial Conduct Authority intensifies scrutiny of algorithmic trading system auditability. London's asset management district is investing in cross-border lineage automation for dual-jurisdiction compliance.
Japan
Manufacturing enterprises are deploying edge-to-cloud architectures for autonomous vehicle development and smart factory initiatives. METI industrial data governance guidelines emphasize supply chain transparency and cross-enterprise data sharing standards. Nagoya's automotive manufacturing belt is implementing federated query execution across distributed production facilities.
Dataops Platform Market Competitive Landscape
Player mix skews toward hyperscaler-native platforms and specialized data integration vendors with hybrid environment capabilities. Market structure consolidates around three tiers: cloud-native orchestration specialists, legacy enterprise software incumbents with modernization roadmaps, and vertical-specific workflow automation providers. Dominant competitive moves include hyperscaler partnership deepening and generative AI capability embedding for pipeline generation automation.
Among hyperscaler-anchored platforms, Microsoft Corporation and Amazon Web Services exemplify cloud-native deployment archetypes with regulatory compliance specialization. Databricks occupies a position within the lakehouse architecture tier, representing unified storage-compute convergence. Informatica sits within the data quality specialization segment for hybrid environment governance. IBM Corporation and Oracle Corporation exemplify legacy enterprise incumbents executing cloud transition strategies.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| Informatica |
| Teradata Corporation |
| Databricks |
| DataOps.live |
| DataKitchen |
| Others |
Pricing and Supply Chain Analysis
GPU-to-CPU workload substitution in AI/ML pipeline execution is redrawing cost structures across cloud-native and on-premise deployment modes, compressing margins for hyperscaler-dependent vendors while opening pricing latitude for hybrid-optimized platforms.
Pricing Analysis
Cost-plus contracts with hyperscaler compute indexation dominate enterprise procurement, tying platform fees to AWS, Azure, or Google Cloud spot pricing movements. Three-tier pricing structure across enterprise, mid-market, and developer tiers separates ISO 27001-certified governance bundles from basic orchestration licenses. Pricing pressure stems from reserved instance commitments locking buyers into vendor-specific cost structures. Mid-market enterprises exhibit highest price sensitivity due to talent scarcity extending implementation timelines, while regulated financial services show lowest sensitivity given EU AI Act compliance deadlines.
Supply Chain Analysis
Hyperscaler data center concentration in the United States, Ireland, and Singapore underwrites global platform delivery capacity with latent congestion risk during peak provisioning windows. Core infrastructure draws from NVIDIA GPU supply chains, specialized flash storage arrays, and proprietary network backbone investments. Single-source vulnerability concentrates in NVIDIA's dominant AI accelerator position. Distribution runs through direct enterprise sales teams with hyperscaler marketplace co-sell arrangements capturing fastest-growing channel share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform specialization is fragmenting the vendor landscape as EU AI Act compliance requirements splinter demand between governance-heavy and automation-pure buyer archetypes.
For Market Incumbents: Shield recurring revenue bases by embedding generative AI pipeline generation ahead of workflow automation commoditization. Prioritize ISO 27001 certification maintenance as binary vendor qualification gates tighten from quarters to weeks. Deepen hyperscaler partnership tiers to secure reserved instance pricing advantages against emerging multi-cloud orchestration specialists. For New Entrants and Emerging Players: Managed services capacity gaps in India's banking and telecommunications verticals offer immediate attach revenue with lower competitive density. Target German automotive predictive maintenance pipelines where industrial IoT data streams remain largely unorchestrated. Lead with API-first pricing transparency to exploit enterprise procurement teams' disaggregation of professional services from platform subscriptions. For Investors and Strategic Acquirers: The market sits at a compliance-acceleration phase that favors hybrid-environment governance specialists over pure cloud-native orchestration. Long-term viability centers on platforms absorbing algorithmic accountability standards without wholesale architecture replacement. Watch EU AI Act conformity assessment timelines as inflection indicator for high-risk system deployer procurement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Pipeline Embedding | Auto-generated transformation code redeploys data engineering teams to architecture design. |
| ISO 27001 Certification Investment | Binary vendor qualification gates compress evaluation cycles from months to weeks. |
| Hyperscaler Partnership Deepening | Reserved instance pricing advantages counter GPU-intensive workload cost volatility. |
| Hybrid Environment Specialization | Cross-architecture consistency captures manufacturing and financial services procurement. |
| Regulatory Compliance Automation | EU AI Act audit trail requirements mandate granular data provenance documentation. |
Research Methodology
Initial hypotheses were tested against primary input from data engineering directors, cloud procurement officers, compliance leads at financial institutions, and platform integration specialists and refined through secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and healthcare system procurement records. Bottom-up sizing of deployment volumes and top-down cross-check against aggregate enterprise IT spending established analytical triangulation.
Variance decomposition across deployment architecture, solution layer, and end-user vertical dimensions structured the projection framework over the analysis window. CAGRs were derived from segment-level growth rate synthesis with cloud migration velocity and regulatory compliance timeline assumptions. Industry-specific inputs included EU AI Act implementation schedules and RBI data localization guideline enforcement patterns.
Underlying assumptions cover sustained hyperscaler pricing discipline and regulatory enforcement continuity, with deviation risk concentrated in GPU supply chain disruption and algorithmic accountability standard acceleration. Practitioners should keep alternative scenarios live as EU AI Act conformity assessment timelines and central bank data localization rulings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Application Container Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Warranty Management System Market
Digital Solutions
United States ICT Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Utility App Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
On-Shelf Availability Solutions Market