
 Customer Communication Management Market | 2026-2036
Customer Communication Management Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Communication Management Market Analysis
Enterprise-grade multi-channel orchestration is unwinding legacy document-centric workflows across banking and insurance sectors. Quadient SA leverages its heritage in physical mail automation to anchor hybrid cloud transitions for regulated clients. Smart Communications Inc. competes through API-first architectures that sustain real-time personalization at enterprise scale. Messagepoint Inc. specializes in intelligent content management, differentiating through AI-powered compliance review engines that reduce regulatory exposure.
Customer communication management denotes the integrated discipline of designing, delivering, and governing personalized interactions across print, digital, and voice channels, typically governed by SLA-bound delivery windows and template versioning protocols. Its primary commercial purpose centers on reducing operational cost per touchpoint while preserving regulatory audit trails and brand consistency across millions of individualized outputs. Cloud services now lead deployment preferences as financial institutions and healthcare providers retire mainframe-dependent composition engines, while multi-channel platforms capture the fastest expansion as organizations unify previously siloed email, SMS, portal, and paper workflows. On-premise solutions retain margin concentration in defense and government sectors where data residency mandates override cloud economics.
FDA 21 CFR Part 11 and HIPAA shape healthcare communication requirements around electronic record integrity and patient consent documentation, while GDPR and the EU AI Act impose algorithmic transparency obligations on automated content personalization in European jurisdictions. The SEC's marketing rule and FINRA guidance further constrain how broker-dealers deploy predictive analytics in client outreach, creating compliance-layer demand for audit-ready CCM platforms. Stakeholders must weigh captive infrastructure investment against vendor consolidation risk as platform specialization narrows the field of regulation-certified providers.
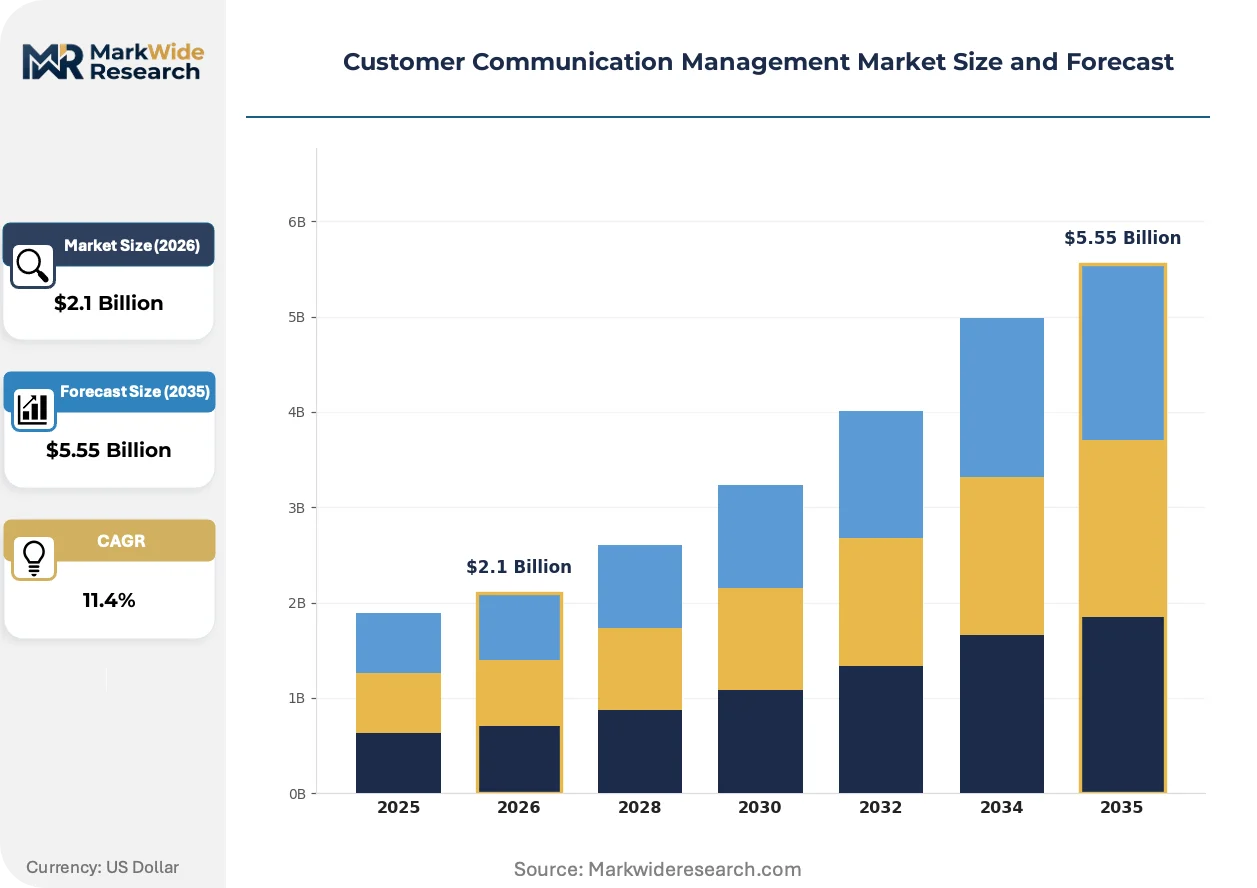
Market Dynamics
Cloud-native orchestration engines are dismantling mainframe-dependent composition architectures across financial services and healthcare, forcing incumbent vendors to rearchitect delivery stacks around API-first microservices that decouple content management from channel execution.
Growth Catalysts
- GDPR and EU AI Act algorithmic transparency mandates:European financial institutions require audit-ready personalization engines that document automated decision pathways, accelerating replacement of black-box legacy systems.
- Healthcare HIPAA electronic record integrity requirements:Patient consent documentation and audit trail preservation drive demand for compliant multi-channel platforms that unify portal, SMS, and paper workflows.
- India's banking sector digitalization:RBI-mandated customer communication modernization and UPI ecosystem expansion create procurement urgency for localized cloud CCM deployments.
Market Restraints
- Mainframe migration cost structure:COBOL-dependent composition engines require multi-year capital commitments for parallel-run validation, freezing procurement cycles at Tier 1 banks.
- Cloud vendor concentration risk:AWS, Azure, and Google Cloud dominate regulated financial services hosting, creating single-supplier dependency for SLA-bound delivery infrastructure.
- Data residency technical limitation:Cross-border content synchronization latency degrades real-time personalization performance below SLA thresholds for sub-100ms delivery windows.
Strategic Opportunities
- Germany's Mittelstand manufacturing sector:Mid-market industrial firms remain underpenetrated for customer communication automation, presenting whitespace for verticalized solutions.
- Voice channel convergence with conversational AI:Integration of large language models with IVR and smart speaker platforms enables new interaction modalities for insurance claims and billing inquiries.
- SEC marketing rule compliance tailwind:Broker-dealer predictive analytics restrictions create demand for audit-ready platforms that document content approval chains and audience targeting logic.
Industry Challenges
- COBOL-to-microservices skill gap:Scarce engineering talent capable of mapping legacy template logic to modern API architectures extends migration timelines and inflates implementation costs.
- Multi-vendor integration complexity:Enterprises average seven distinct communication systems, requiring costly middleware development to synchronize template versioning across disconnected stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Communication Management Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud Services, On-Premise Solutions, Multi-Channel Platforms End User: Retail Sector, Healthcare Providers, Financial Institutions, Telecommunications Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Application: Marketing Communications, Customer Engagement, Billing Notifications, Feedback Management |
| Companies Covered | Quadient SA, Smart Communications Inc., Messagepoint Inc., Doxee S.p.A., Newgen Software Technologies Limited, Sefas Innovation Inc., Pitney Bowes Inc., Cincom Systems, Inc., Doxim Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Communication Management Market Emerging Trajectories
Generative AI is compressing content production cycles while fragmenting traditional vendor control over template design, forcing platform providers to reposition around governance and orchestration rather than composition ownership.
Headless CCM architecture is fragmenting the market structure that tied content creation to specific output channels. Banking and insurance technology teams are adopting API-only platforms that separate content logic from presentation layers, enabling same-source deployment across emerging channels. This decoupling is fragmenting vendor revenue models away from per-page licensing toward consumption-based API metering.
The EU AI Act's risk-based classification system imposes documentation burdens on automated content personalization used in credit and insurance decisions. Financial institutions must maintain technical files proving human oversight of algorithmic outputs. German and French regulators are already enforcing these provisions, driving procurement of platforms with built-in explainability logging and approval workflow capture.
Buyers are consolidating vendor relationships around integrated orchestration suites rather than point solutions for individual channels. Procurement teams at US healthcare systems now require unified platforms covering patient portals, SMS appointment reminders, and EOB document generation. This consolidation pressure is visible most acutely in California and Texas hospital networks, where CIOs prioritize single-vendor accountability over best-of-breed channel specialization.
Customer Communication Management Market Segmentation
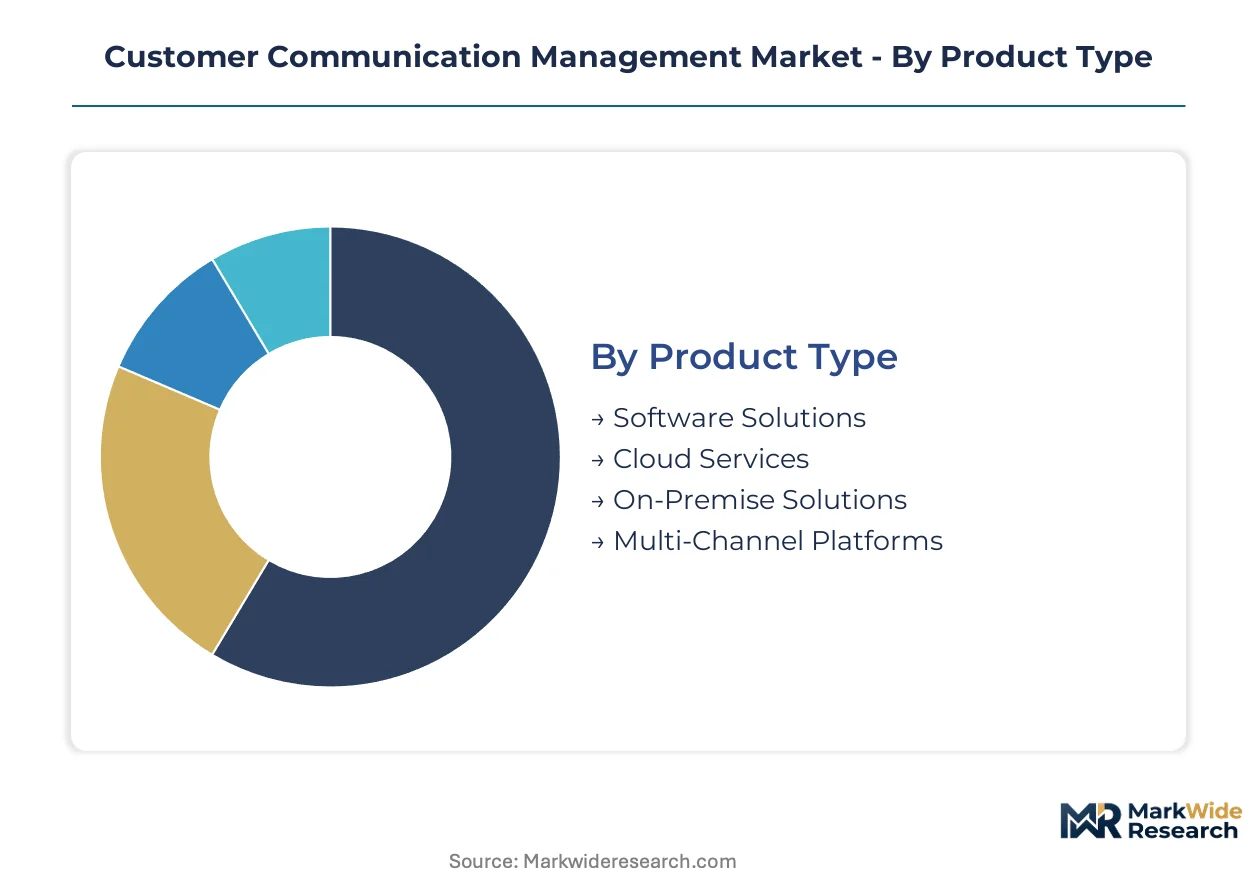
Customer communication management procurement divides sharply between legacy infrastructure replacement and cloud-native expansion, with deployment architecture and end-user verticals determining pricing power and retention economics. Understanding segment boundaries clarifies where vendors capture recurring revenue versus one-time migration fees.
Product Type:
Margin pools concentrate in subscription-based cloud delivery models that embed ongoing compliance updates and reduce customer churn.
- Software Solutions:Traditional licensed platforms with perpetual deployment rights dominate government and defense sectors where capital budgets accommodate upfront acquisition. Procurement freezes at Tier 1 banks extend sales cycles beyond 18 months as COBOL migration validation requirements multiply.
- Cloud Services:API-metered consumption models capture fastest expansion as healthcare systems and regional banks retire mainframe-dependent composition engines. AWS, Azure, and Google Cloud hosting concentration creates vendor lock-in risk for SLA-bound delivery infrastructure.
- On-Premise Solutions:Retain margin concentration in data residency-mandated environments.
- Multi-Channel Platforms:Unify previously siloed email, SMS, portal, and paper workflows.
The dominant share belongs to Software Solutions, while Cloud Services is closing the gap fastest.
End User:
Vertical specialization determines implementation complexity and regulatory certification requirements.
- Financial Institutions:SEC marketing rule and FINRA guidance constrain predictive analytics deployment in client outreach, creating mandatory audit trail functionality. Broker-dealers prioritize platforms documenting content approval chains and audience targeting logic.
- Healthcare Providers:HIPAA electronic record integrity requirements and FDA 21 CFR Part 11 shape procurement around patient consent documentation preservation. California and Texas hospital networks consolidate vendor relationships to single-source accountability.
- Retail Sector:Real-time personalization at scale drives API-first architecture adoption.
- Telecommunications:Billing notification volume and multi-language support requirements dominate platform selection.
Financial Institutions command the largest addressable spend, with Healthcare Providers expanding most quickly as patient portal mandates proliferate.
Deployment:
Architecture choice directly impacts total cost of ownership and data sovereignty compliance.
- Public Cloud:Shared infrastructure economics accelerate adoption among mid-market enterprises lacking dedicated security operations. GDPR and EU AI Act algorithmic transparency mandates drive European financial institutions toward documented decision-pathway platforms.
- Hybrid Cloud:Combines regulated data residency with burst capacity for campaign volume spikes. India's RBI-mandated customer communication modernization creates localized procurement urgency for split-stack deployments.
- Private Cloud:Dedicated tenancy satisfies defense and intelligence community requirements.
- On-Premises:Retains foothold where air-gapped networks are mandatory.
Public Cloud holds established volume leadership, though Hybrid Cloud is gaining share fastest as sovereignty requirements fragment single-vendor strategies.
Application:
Use case specificity determines template complexity and integration depth with core operational systems.
- Billing Notifications:High-volume transactional output requires millisecond-scale composition engines integrated with ERP and payment platforms. Telcos and utilities prioritize delivery window guarantees over creative flexibility.
- Customer Engagement:Real-time behavioral triggers and next-best-action personalization demand sub-100ms response latency. Headless CCM architecture adoption separates content logic from presentation layers across emerging channels.
- Marketing Communications:Campaign orchestration and audience segmentation capabilities drive platform selection.
- Feedback Management:Survey deployment and sentiment analysis integration shape procurement priorities.
Billing Notifications generates the highest transaction volume, while Customer Engagement shows the steepest expansion trajectory as conversational AI integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment concentrates in the United States, Germany, and India as financial institutions and healthcare providers modernize legacy document systems. Regulatory mandates across these markets are accelerating procurement timelines for compliant multi-channel platforms. Local data residency requirements and SLA-bound delivery windows shape deployment architecture decisions in each jurisdiction.
United States
SEC marketing rule compliance and FINRA guidance drive broker-dealer demand for audit-ready personalization engines. HIPAA electronic record integrity requirements shape healthcare procurement around patient consent documentation. California and Texas hospital networks consolidate vendor relationships to single-source accountability across portal, SMS, and paper workflows.
Germany
GDPR and EU AI Act algorithmic transparency mandates force replacement of black-box legacy systems with documented decision-pathway platforms. The country's national data protection regulator enforces technical file requirements for automated credit and insurance communications. Bavaria's Mittelstand manufacturing sector presents whitespace for verticalized customer communication automation solutions.
India
RBI-mandated customer communication modernization and UPI ecosystem expansion create procurement urgency for localized cloud deployments. The central bank's digital payment infrastructure push requires millisecond-scale composition engines integrated with core banking platforms. Mumbai and Bangalore financial technology clusters drive hybrid cloud adoption for split-stack sovereignty compliance.
United Kingdom
FCA conduct rules and GDPR overlap create layered compliance burdens for wealth management and insurance sectors. The national financial regulator's consumer duty requirements mandate documented content approval chains. London's Lloyd's insurance market and fintech corridor prioritize API-first architectures that separate content logic from channel execution.
Japan
METI digital transformation incentives and the national data protection framework accelerate mainframe retirement in banking and insurance. The ministry's cloud-first policy directives reduce procurement friction for regulated institutions. Tokyo and Osaka financial centers adopt headless CCM architectures to enable same-source deployment across emerging digital channels.
Customer Communication Management Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the customer communication management market. Incumbent vendors with heritage physical mail automation compete against API-native challengers for cloud migration contracts. Three strategic archetypes dominate: legacy infrastructure specialists, cloud-native orchestration platforms, and vertical compliance-focused providers. Consolidation pressure intensifies as procurement teams favor integrated suites over point solutions, while strategic partnerships between cloud hyperscalers and compliance engine vendors reshape channel economics.
Within the legacy-to-cloud transition tier, Quadient SA, Smart Communications Inc., and Messagepoint Inc. exemplify divergent architectural approaches to regulated client segments. Quadient SA represents the hybrid cloud migration specialist archetype, leveraging physical mail heritage for regulated financial services transitions. Smart Communications Inc. occupies the API-first real-time personalization position, serving enterprise-scale behavioral trigger requirements. Messagepoint Inc. anchors the AI-powered compliance review segment, reducing regulatory exposure through automated content governance engines.
| Leading Market Players |
|---|
| Quadient SA |
| Smart Communications Inc. |
| Messagepoint Inc. |
| Doxee S.p.A. |
| Newgen Software Technologies Limited |
| Sefas Innovation Inc. |
| Pitney Bowes Inc. |
| Cincom Systems, Inc. |
| Doxim Inc. |
| Others |
Supply Flow & Price Mechanics
EU AI Act algorithmic transparency mandates gate both vendor qualification and pricing tier structure simultaneously, forcing financial institutions to pay premium rates for audit-ready platforms while disqualifying legacy providers lacking explainability logging capabilities. HIPAA and SEC compliance requirements further stratify the market, with certified vendors capturing pricing power over uncertified competitors across healthcare and broker-dealer segments.
Pricing Analysis
EU AI Act documentation burdens dictate the pricing tier structure across European financial services procurement, separating premium vendors with built-in approval workflow capture from standard-tier providers lacking automated governance engines. Price differentiation hinges on certification grade and volume scale, with enterprise-scale behavioral trigger platforms commanding higher rates than template-centric legacy systems. Pricing pressure stems from cloud hyperscaler concentration as AWS, Azure, and Google Cloud hosting fees compress margins for SLA-bound delivery infrastructure. Regional banks exhibit highest price sensitivity due to multi-year mainframe migration capital commitments, while Tier 1 institutions prioritize compliance functionality over cost.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for hardware-dependent on-premise deployments, particularly affecting government and defense sector procurement cycles. Software development concentrates in the United States, India, and Germany, with Indian technology clusters feeding API-first platform engineering and German firms anchoring compliance engine specialization. Raw material dependencies span semiconductor components for data center infrastructure, specialized encryption hardware for regulated environments, and cobalt-dependent server cooling systems. Single-source vulnerability runs through cloud hyperscaler dominance of regulated financial services hosting. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex multi-vendor consolidation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce engineering talent capable of mapping COBOL template logic to modern API architectures constrains market expansion, creating asymmetric returns for vendors that solve the legacy-to-cloud translation bottleneck. This capability gap shapes competitive dynamics across all stakeholder positions.
For Market Incumbents: Consolidate around hybrid cloud migration expertise to defend against API-native challengers, leveraging physical mail automation heritage as an anchor for regulated client transitions. Acquire specialist compliance engine providers to close explainability logging gaps exposed by EU AI Act enforcement. Deepen upstream control over cloud infrastructure partnerships to reduce hyperscaler concentration risk. For New Entrants and Emerging Players: Differentiate on verticalized solutions for Germany's Mittelstand manufacturing sector, where mid-market industrial firms remain underpenetrated for customer communication automation. Target voice channel convergence with conversational AI as a whitespace modality for insurance claims and billing inquiries. Pursue land-and-expand strategies through API-metered consumption models that reduce upfront procurement friction. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy software conglomerates seeking to divest non-core communication management units amid platform consolidation pressure. Long-term viability favors vendors with demonstrated regulatory certification across multiple jurisdictions rather than single-market specialists. Watch for inflection signals in India's RBI-mandated modernization procurement velocity as an indicator of emerging market expansion sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Architecture Migration | Enables Tier 1 banks to satisfy data residency mandates while accessing burst capacity for campaign volume spikes. |
| API-First Platform Development | Separates content logic from presentation layers, allowing same-source deployment across emerging digital channels. |
| AI-Powered Compliance Engine Acquisition | Addresses EU AI Act technical file requirements and SEC marketing rule audit trail obligations simultaneously. |
| Vertical Solution Specialization | Captures whitespace in Germany's Mittelstand manufacturing sector through industry-specific template libraries. |
| Voice Channel Integration Partnership | Combines large language models with IVR platforms for insurance claims and billing inquiry automation. |
Methodological Framework
Initial hypotheses were tested against primary input from CCM platform engineering directors, healthcare CIOs, financial services compliance officers, and systems integration specialists and refined through secondary validation against SEC 10-K filings, FDA 21 CFR Part 11 guidance documents, EU AI Act regulatory texts, and hyperscaler capex disclosures. Bottom-up sizing of deployment volumes across cloud, hybrid, and on-premise architectures was cross-checked against top-down market value estimates derived from vendor revenue disclosures and procurement database tracking.
Variance decomposition across the projection horizon isolates growth contributions from cloud migration velocity, regulatory mandate timing, and vertical expansion patterns. Segmentation dimensions modeled include deployment architecture, end-user vertical, application use case, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized adoption curves calibrated to documented procurement cycles at Tier 1 banks and hospital networks. Industry-specific forecast inputs incorporate RBI modernization mandates and UPI ecosystem expansion metrics for India, plus FDA and HIPAA compliance timeline assumptions for US healthcare.
The analysis sits within stated boundaries; outcomes outside sustained cloud migration investment, stable regulatory enforcement intensity, and resolved mainframe skill gap conditions would require recalibration. Forecasts reflect documented assumptions about procurement cycle duration and vendor consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Online CRM Software Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Europe Cloud CRM Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Global Customer Success Management Market