
 Mobile CRM Market | 2026-2036
Mobile CRM Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile CRM Market Outlook
The EU AI Act is rebalancing how mobile CRM platforms architect data processing pipelines across European deployments. Salesforce leverages its Einstein AI layer to navigate compliance-heavy environments without sacrificing predictive capability. HubSpot anchors its competitive stance through freemium-led product-led growth that sustains rapid user base expansion in mid-market segments. Microsoft Dynamics 365 dominates enterprise accounts through deep integration with Office 365 and Azure infrastructure.
Mobile CRM denotes customer relationship management software architected for smartphones and tablets, operating through native iOS/Android applications or responsive web interfaces with offline synchronization, push notification triggers, and geolocation-enabled field sales workflows. Cloud-based deployment leads structural growth by eliminating on-premise infrastructure overhead and enabling elastic scaling for seasonal sales organizations. Sales automation solutions capture the deepest margin pools by reducing customer acquisition cost through pipeline velocity optimization, while marketing automation segments expand fastest as real-time personalization engines migrate from desktop to handheld interfaces.
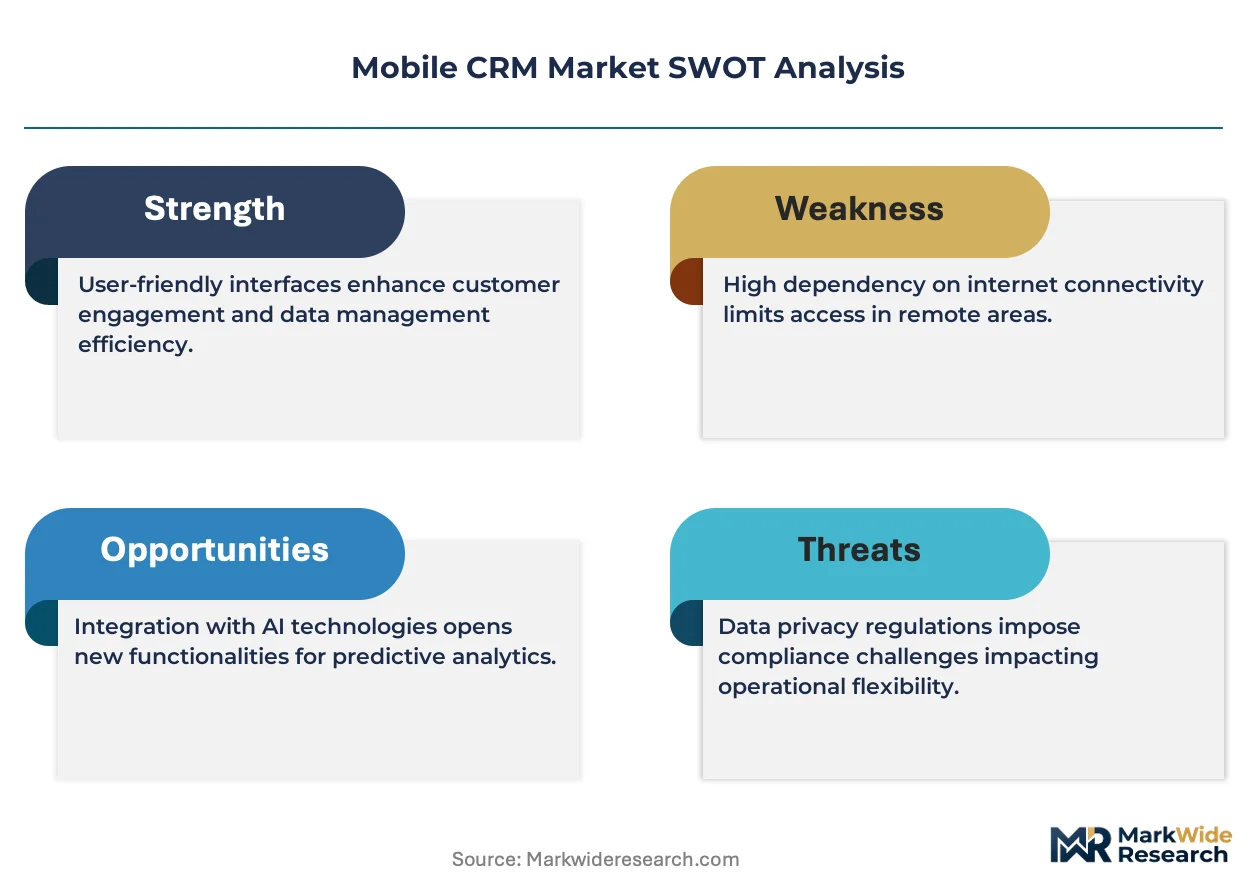
The US Federal Trade Commission scrutinizes data broker practices embedded within CRM ecosystems, pressuring vendors toward explicit consent architectures. GDPR enforcement across EU member states mandates granular data retention policies that increase engineering overhead for cross-border customer databases. ISO 27001 certification has become a non-negotiable procurement filter for healthcare and financial services buyers evaluating mobile CRM vendors. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as platform ecosystems consolidate around hyperscaler infrastructure.
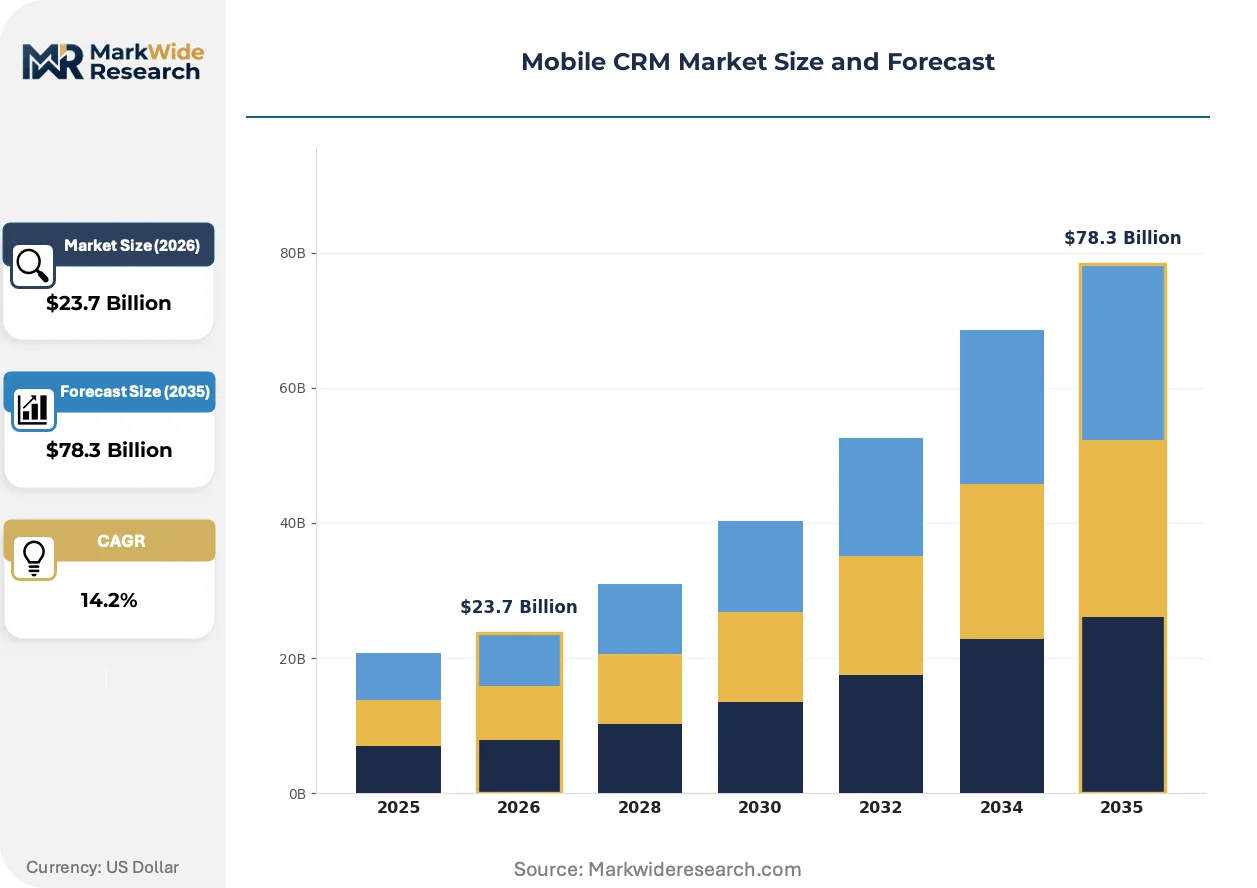
Market Dynamics
Cloud-native architectures are compressing deployment timelines for field sales organizations while simultaneously exposing vendors to data sovereignty enforcement across fragmented regulatory jurisdictions.
Growth Catalysts
- EU AI Act:The regulation mandates algorithmic transparency for automated decision-making in customer scoring, pushing vendors to invest in explainable AI pipelines that differentiate compliant platforms from black-box competitors.
- Geofencing capabilities:Real-time location intelligence enables territory optimization for pharmaceutical and medical device field forces, with push-triggered workflows reducing rep idle time between appointments.
- Healthcare digitization:HIPAA-aligned mobile CRM deployments are accelerating as life sciences firms replace paper-based physician interaction logs with synchronized tablet applications for clinical trial recruitment.
Market Restraints
- GDPR retention mandates:Granular data erasure requirements increase engineering overhead for cross-border customer databases, particularly for vendors serving multinational accounts with divergent member-state interpretations.
- Hyperscaler concentration:Dependence on AWS, Azure, and Google Cloud infrastructure creates single-point-of-failure exposure for SaaS-native vendors during regional outage events or geopolitical data localization disputes.
- Legacy ERP entrenchment:On-premise SAP and Oracle systems in industrial manufacturing segments resist API-based integration, extending sales cycles and inflating professional services margins.
Strategic Opportunities
- LATAM underpenetration:Brazil and Mexico exhibit sub-20% SaaS CRM adoption among mid-market distributors, creating first-mover advantage for localized Portuguese and Spanish interface deployments.
- Voice-to-CRM automation:Natural language processing convergence with mobile microphones enables hands-free call logging for automotive and logistics sales reps operating in hands-busy environments.
- CSRD reporting alignment:The EU Corporate Sustainability Reporting Directive creates demand for carbon-footprint tracking modules within customer visit applications, particularly for industrial equipment vendors.
Industry Challenges
- ISO 27001 certification timelines:Healthcare and financial services procurement committees now require current certification as a gate condition, extending vendor qualification periods by six to nine months.
- Legacy middleware integration:Custom SOAP-based connectors for aging on-premise systems demand scarce specialized engineering talent, inflating implementation costs and delaying go-live dates.
- Cross-border data routing:Schrems II jurisprudence forces architectural rewrites for vendors previously relying on Privacy Shield mechanisms, requiring EU-based data residency investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile CRM Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Mobile End User: Retail, Healthcare, Education, Financial Services Solution: Sales Automation, Customer Support, Marketing Automation, Analytics Feature: Contact Management, Task Management, Reporting, Integration |
| Companies Covered | Salesforce, Zoho CRM, HubSpot, Pipedrive, SugarCRM, Freshworks, Insightly, Agile CRM, Microsoft Dynamics 365, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile CRM Market Strategic Shifts
Edge computing architectures are redistributing processing loads from centralized cloud instances toward handheld devices, enabling responsive offline functionality that reshapes competitive differentiation.
Predictive analytics engines embedded within mobile CRM stacks are expanding into field service scheduling and inventory pre-positioning. Agricultural equipment dealers and HVAC contractors adopt these capabilities fastest, compressing response times from hours to minutes. The technology is expanding into adjacent workflow automation, blurring traditional boundaries between sales and operational execution platforms.
GDPR enforcement patterns across German, French, and Irish supervisory authorities are tightening consent granularity requirements for marketing automation triggers. Vendors must now implement double-opt-in architectures with timestamped audit trails for every push notification. Healthcare and financial services deployments in EU member states face the steepest compliance retrofit costs.
Subscription-based pricing for mobile CRM access is displacing perpetual license models among industrial distributors and construction material suppliers. Buyers prefer operational expenditure treatment that aligns software costs with seasonal revenue fluctuations. This shift concentrates most visibly in North American mid-market segments where private equity ownership pressures working capital optimization.
Mobile CRM Market Segmentation
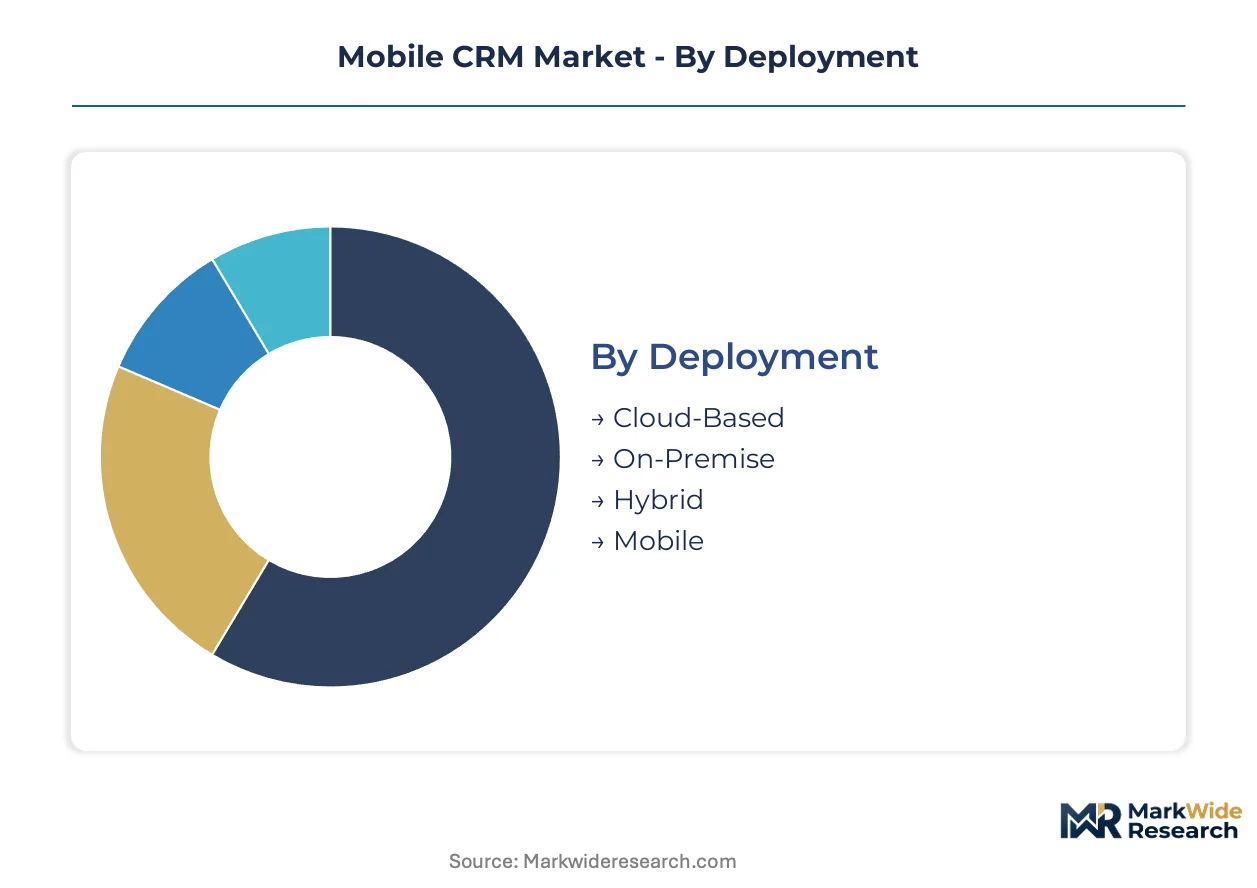
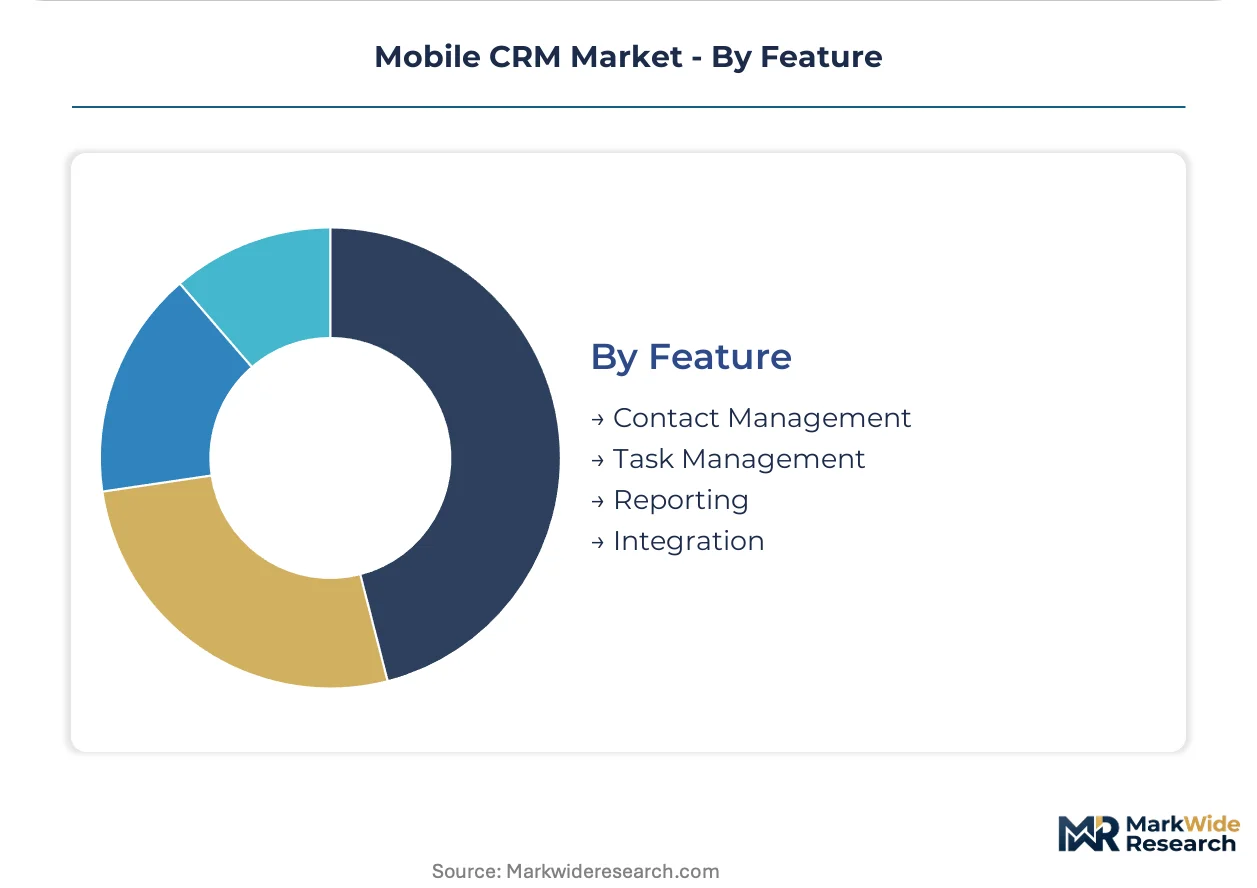
Mobile CRM architectures fragment across deployment modes, end-use verticals, solution types, and functional modules. Each segmentation axis carries distinct margin profiles, compliance burdens, and integration complexity that reshape vendor competitive positioning.
Deployment:
Standardization dominates at the infrastructure layer while customization intensifies at the application tier across this category.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead for field sales organizations. Demand concentrates among United States mid-market distributors seeking elastic capacity during seasonal revenue spikes, with HIPAA-aligned healthcare deployments driving premium tier uptake.
- On-Premise:Dedicated hardware installations within client data centers preserve air-gapped security for defense contractors and classified government accounts. German industrial manufacturers favor this mode to satisfy Works Council data sovereignty requirements, though maintenance contracts inflate total cost of ownership.
- Hybrid:Split architectures synchronize sensitive customer records on local servers while pushing analytics workloads to public cloud instances.
- Mobile:Native iOS and Android applications with offline synchronization capabilities enable territory coverage without continuous connectivity.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Mobile as field-first architectures displace desktop-centric legacy systems.
End User:
Margin concentration follows regulatory stringency, with compliance-heavy verticals commanding premium pricing and extended contract terms.
- Retail:Omnichannel order management and loyalty program integration dominate functional requirements. United States specialty apparel chains and big-box distributors drive volume, with real-time inventory visibility across storefront and warehouse systems reducing stockout rates.
- Healthcare:HIPAA audit trails and physician interaction logging impose the strictest data governance requirements. Life sciences field forces in Massachusetts and New Jersey pharmaceutical corridors represent the highest-value account profiles.
- Education:Alumni fundraising and student recruitment pipelines require donor relationship management with gift processing integration.
- Financial Services:SEC record-keeping mandates and suitability documentation shape workflow design for wealth management advisors.
Healthcare captures the highest average contract values. Retail delivers the broadest installed base expansion.
Solution:
Functional depth determines integration complexity, with all-in-one suites competing against best-of-breed point solutions across this axis.
- Sales Automation:Pipeline velocity optimization and forecast accuracy tools reduce customer acquisition costs for B2B field organizations. United States software vendors and industrial equipment dealers prioritize this module, with AI-powered lead scoring differentiating premium tiers.
- Customer Support:Case routing and SLA management coordinate helpdesk operations across distributed service teams. Telecommunications providers in Texas and California drive enterprise-scale deployments.
- Marketing Automation:Campaign orchestration and behavioral trigger management migrate from desktop to handheld interfaces.
- Analytics:Embedded BI dashboards and predictive forecasting engines consolidate cross-functional visibility.
Sales Automation commands the deepest margin pools. Marketing Automation is climbing the fastest as real-time personalization engines shift to mobile-first delivery.
Feature:
Core utility modules face commoditization pressure while advanced integration capabilities sustain pricing power across this category.
- Contact Management:Centralized customer record repositories with social profile enrichment form the foundational data layer. United States real estate brokerages and insurance agencies standardize on this capability, with duplicate detection algorithms reducing database pollution.
- Task Management:Activity sequencing and deadline tracking coordinate multi-stakeholder sales cycles. Professional services firms in New York and Illinois legal corridors rely on this feature for matter-based billing alignment.
- Reporting:Standardized and custom dashboard generation supports executive visibility and regulatory documentation.
- Integration:API connectivity and pre-built connectors bridge CRM data with ERP, marketing, and communication stacks.
Contact Management anchors the largest installed footprint. Integration capabilities are gaining share fastest as platform ecosystem strategies consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area software architects anchor mobile CRM platform development, with engineering talent pools in Seattle, Boston, and Tel Aviv supplying specialized AI and security expertise to vendors targeting regulated industries.
United States
Enterprise SaaS penetration and remote sales force deployment drive cloud-native CRM adoption among mid-market distributors. FTC scrutiny of data broker practices pressures vendors toward explicit consent architectures for customer scoring algorithms. Massachusetts pharmaceutical corridors deploy HIPAA-aligned tablet applications for physician interaction logging.
Germany
Works Council data sovereignty requirements favor hybrid deployment architectures among industrial manufacturers. GDPR enforcement through German supervisory authorities mandates granular data retention policies with timestamped audit trails. Bavarian automotive suppliers integrate voice-to-CRM automation for hands-busy field sales environments.
United Kingdom
Financial services wealth management advisors demand SEC-aligned record-keeping modules for suitability documentation. Post-Brexit data adequacy negotiations reshape cross-border customer database architectures for vendors serving EU-UK accounts. London fintech clusters pioneer real-time personalization engines migrating from desktop to handheld interfaces.
India
Mid-market distributor SaaS adoption remains underpenetrated, creating first-mover opportunity for localized Hindi and regional language interface deployments. RBI guidelines on customer data protection influence CRM vendor qualification for banking sector procurement. Bengaluru and Hyderabad technology corridors supply engineering talent for platform development and API integration services.
Brazil
Portuguese-language mobile CRM deployments target sub-20% SaaS adoption rates among mid-market distributors and construction material suppliers. ANVISA pharmaceutical regulations shape field force automation requirements for life sciences customer engagement. São Paulo industrial clusters drive demand for subscription-based pricing models aligning software costs with seasonal revenue fluctuations.
Mobile CRM Market Competitive Environment
Capital-heavy platform infrastructure providers compete with asset-light vertical specialists across deployment modes and end-use segments. Market structure consolidates around hyperscaler-backed suites while fragmenting across best-of-breed point solutions for specialized workflows. Three archetypes dominate: full-stack ecosystem vendors anchoring enterprise accounts, freemium-led product-led growth platforms capturing mid-market expansion, and compliance-focused specialists serving regulated verticals. Competitive moves concentrate on M&A for AI capability acquisition and strategic partnerships for ERP integration depth.
Within the full-stack ecosystem tier, Salesforce and Microsoft Dynamics 365 anchor enterprise positioning through deep infrastructure integration and vertical solution marketplaces. HubSpot exemplifies the freemium-led archetype, occupying a position in mid-market segments through rapid user base expansion and inbound marketing automation convergence. Zoho CRM represents the emerging-market-focused specialist, situating within competitive dynamics through localized pricing and multilingual interface deployments.
| Leading Market Players |
|---|
| Salesforce |
| Zoho CRM |
| HubSpot |
| Pipedrive |
| SugarCRM |
| Freshworks |
| Insightly |
| Agile CRM |
| Microsoft Dynamics 365 |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure spot pricing indices cascade through mobile CRM vendor cost structures, compressing margins for SaaS-native providers while hyperscaler-backed platforms absorb volatility through captive compute capacity. This input cost dynamic stratifies end-user pricing across deployment tiers.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise-grade implementations with dedicated implementation support from self-serve mid-market tiers. Subscription-based SaaS pricing dominates, with HIPAA-aligned healthcare deployments and ISO 27001-certified tiers commanding premium positioning against freemium entry points. Price differentiation rests on compliance certification level and integration complexity rather than core feature depth. Pricing pressure stems from hyperscaler economies of scale as AWS, Azure, and Google Cloud squeeze independent vendor margins. Mid-market distributors exhibit highest price sensitivity, while financial services and healthcare buyers prioritize audit-ready architectures over cost minimization.
Supply Chain Analysis
Reverse-logistics flows for device refresh cycles and decommissioned enterprise hardware create secondary market channels for certified pre-owned tablets in field sales deployments. Engineering talent supply concentrates in the United States, India, and Israel, with Bengaluru and Hyderabad feeding API integration services to Western vendors. Raw material dependencies span semiconductor components for edge devices, lithium-ion cells for extended field battery life, and rare earth elements for geolocation hardware. Single-source vulnerability runs through Taiwan-based chip fabrication for tablet processors. Distribution runs through direct vendor sales organizations for enterprise accounts and value-added resellers serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile CRM functions as a stable compounder, with enterprise SaaS retention rates above ninety percent creating predictable revenue bases that compound through expansion selling and seat growth.
For Market Incumbents: Hedge against hyperscaler vertical integration by deepening proprietary AI model development and securing EU-based data residency infrastructure ahead of Schrems II enforcement expansion. Invest in explainable AI pipelines to differentiate from black-box competitors under EU AI Act transparency mandates. Prioritize ISO 27001 certification maintenance as healthcare and financial services procurement gate conditions tighten qualification timelines. For New Entrants and Emerging Players: Mid-market distributors in Brazil and Mexico represent an underserved buyer archetype with sub-twenty percent SaaS CRM penetration and localized Portuguese and Spanish interface requirements. Voice-to-CRM automation for hands-busy automotive and logistics sales reps offers technical differentiation with limited incumbent investment. Pursue product-led growth with freemium tiers that demonstrate offline synchronization capability before enterprise sales engagement. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing HIPAA-aligned healthcare deployments or CSRD-reporting carbon-footprint modules for industrial equipment vendors. Long-term viability favors platforms with demonstrated cross-border data governance architecture rather than generic feature parity. Monitor EU AI Act enforcement patterns and German supervisory authority GDPR interpretation shifts as inflection indicators for compliance-heavy vertical premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Office 365 and Azure embedding captures enterprise accounts with existing Microsoft infrastructure commitments. |
| Acquisition of Specialist Firm | Voice-to-CRM NLP capabilities address hands-busy field sales segments in automotive and logistics verticals. |
| Strategic Partnership | ERP connector development with SAP and Oracle reduces legacy middleware friction in industrial manufacturing. |
| Geographic Expansion | Portuguese and Spanish localization captures first-mover position in Brazilian and Mexican mid-market distributor segments. |
| Product Launch | Edge computing architectures with offline synchronization differentiate field-first deployments from desktop-centric legacy systems. |
Study Parameters
Bottom-up field sales organization modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across healthcare, financial services, and industrial verticals supplied deployment decision criteria and budget allocation patterns. Secondary validation drew from SEC SaaS vendor filings, hyperscaler capex disclosures, App Annie mobile application analytics, and EU regulatory enforcement databases. This dual approach enables triangulation between stated buyer preferences and observed vendor revenue concentration.
Input-output matrices map cloud infrastructure capacity expansion, enterprise seat growth assumptions, and vertical penetration curves into segment-level revenue projections across the analysis window. Segmentation dimensions include deployment model, organization size, end-use vertical, integration complexity, and regional regulatory cluster. CAGRs derive from fitted adoption curves calibrated against historical SaaS transition patterns and elasticity-adjusted pricing trajectories. Forecast inputs incorporate EU AI Act implementation timelines and FTC data broker scrutiny intensity as regulatory demand shifters.
Underlying measurement precision varies by segment; cloud-based and mobile-native deployments carry tighter precision than hybrid architectures with bespoke on-premise components. Forecasts reflect documented assumptions regarding remote sales force permanence and regulatory enforcement consistency. Practitioners should monitor Schrems II jurisprudence evolution and German Works Council data sovereignty interpretations for early signals of architectural compliance requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Global Customer Experience Management Software Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Pharmaceutical Customer Relationship Management (CRM) Software Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
Europe Cloud CRM Market