
 Canada Customer Relationship Management Market | 2026-2036
Canada Customer Relationship Management Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Customer Relationship Management Market Intelligence
Market Context
ISO 27001 certification is bifurcating the Canada Customer Relationship Management Market into enterprise-ready vendors and mid-tier challengers. Salesforce anchors the large-account segment through its Toronto data residency and AppExchange ecosystem. Gestisoft leverages deep Microsoft Dynamics integration to sustain dominance in Quebec's public sector and provincial crown corporation accounts. Introhive specializes in relationship intelligence automation, competing through AI-driven contact enrichment that differentiates its offering from conventional pipeline tools.
Technical Definition and Structural Segments
Customer Relationship Management comprises software systems that orchestrate customer data capture, interaction tracking, and predictive engagement scoring across sales, marketing, and service functions, typically deployed via multi-tenant cloud architectures with API-first integration layers. Cloud-based deployment leads volume expansion as Canadian enterprises migrate from legacy on-premise Microsoft Dynamics and Siebel installations, though hybrid configurations retain share in regulated verticals requiring data sovereignty controls. Within solution type, marketing automation registers the fastest expansion as retailers and financial services firms deploy real-time personalization engines, while customer support analytics commands premium pricing due to workforce optimization demands in telecommunications and healthcare.
Regulatory Framework and Outlook
PIPEDA and provincial privacy statutes including Quebec's Law 25 reshape product roadmaps by mandating consent audit trails, data localization, and automated deletion workflows that vendors must embed natively. Health Canada and provincial health authorities extend this influence through HIPAA-aligned requirements for healthcare CRM deployments handling patient identifiers. Stakeholders must monitor whether forthcoming federal AI governance frameworks impose algorithmic transparency obligations on predictive CRM scoring models.
Market Dynamics
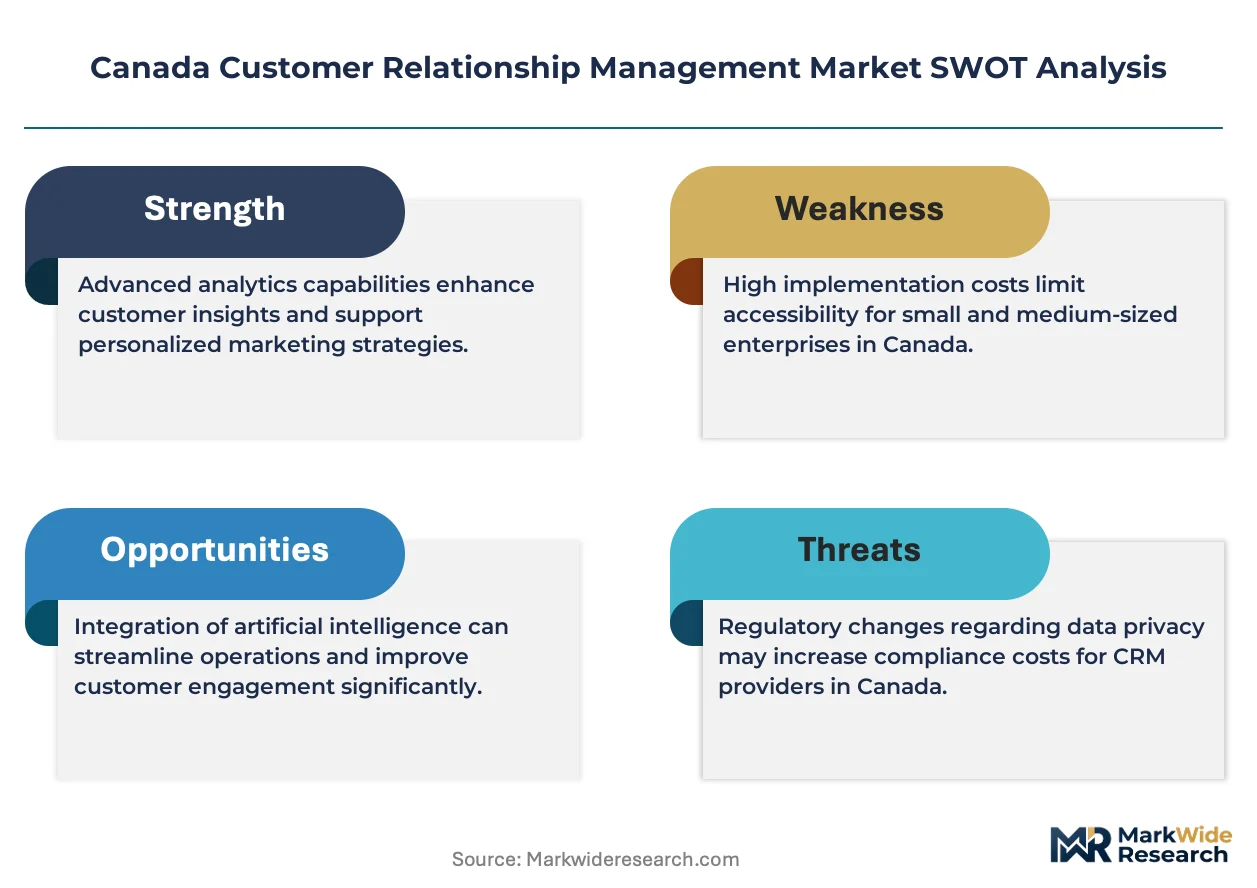
PIPEDA compliance mandates and Quebec's Law 25 are forcing Canadian financial institutions and healthcare providers to rebuild CRM architectures around consent-management workflows, creating procurement urgency for vendors with native audit-trail capabilities and Canadian data residency.
Growth Catalysts
- Law 25 Consent Mandates:Quebec's privacy statute requires automated deletion workflows and granular consent tracking, driving replacement cycles for legacy CRM installations in Montreal's banking sector.
- Open Banking Framework:Consumer-directed finance regulations compel credit unions to deploy unified customer data platforms that aggregate transaction history across multiple institutions.
- AI-Driven Relationship Intelligence:Predictive contact enrichment tools reduce manual data entry burdens for professional services firms managing complex B2B account hierarchies.
Market Restraints
- Cloud Infrastructure Concentration:Limited Canadian data center availability from hyperscale providers restricts SaaS deployment options for organizations requiring strict data sovereignty controls.
- Specialized Talent Scarcity:Shortage of professionals certified in both CRM platform administration and Canadian privacy law implementation extends deployment timelines.
- Legacy System Entrenchment:Deep customization of on-premise Microsoft Dynamics and Siebel installations creates switching costs that delay cloud migration decisions.
Strategic Opportunities
- Healthcare Vertical Expansion:Health Canada HIPAA-aligned requirements for patient identifier handling create demand for specialized CRM deployments in provincial health authorities.
- Real-Time Personalization Engines:Retailers in Toronto-Waterloo corridor seek marketing automation with sub-second latency for in-store behavioral targeting.
- API-First Integration Architectures:Convergence of CRM platforms with open banking APIs enables new product bundles combining transaction data with engagement scoring.
Industry Challenges
- Multi-Jurisdictional Compliance Burden:Vendors must simultaneously satisfy PIPEDA, Quebec Law 25, and sector-specific requirements from Health Canada and provincial regulators.
- Interoperability Complexity:Integration with legacy core banking systems and provincial health record networks demands custom middleware development that strains implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Customer Relationship Management Market |
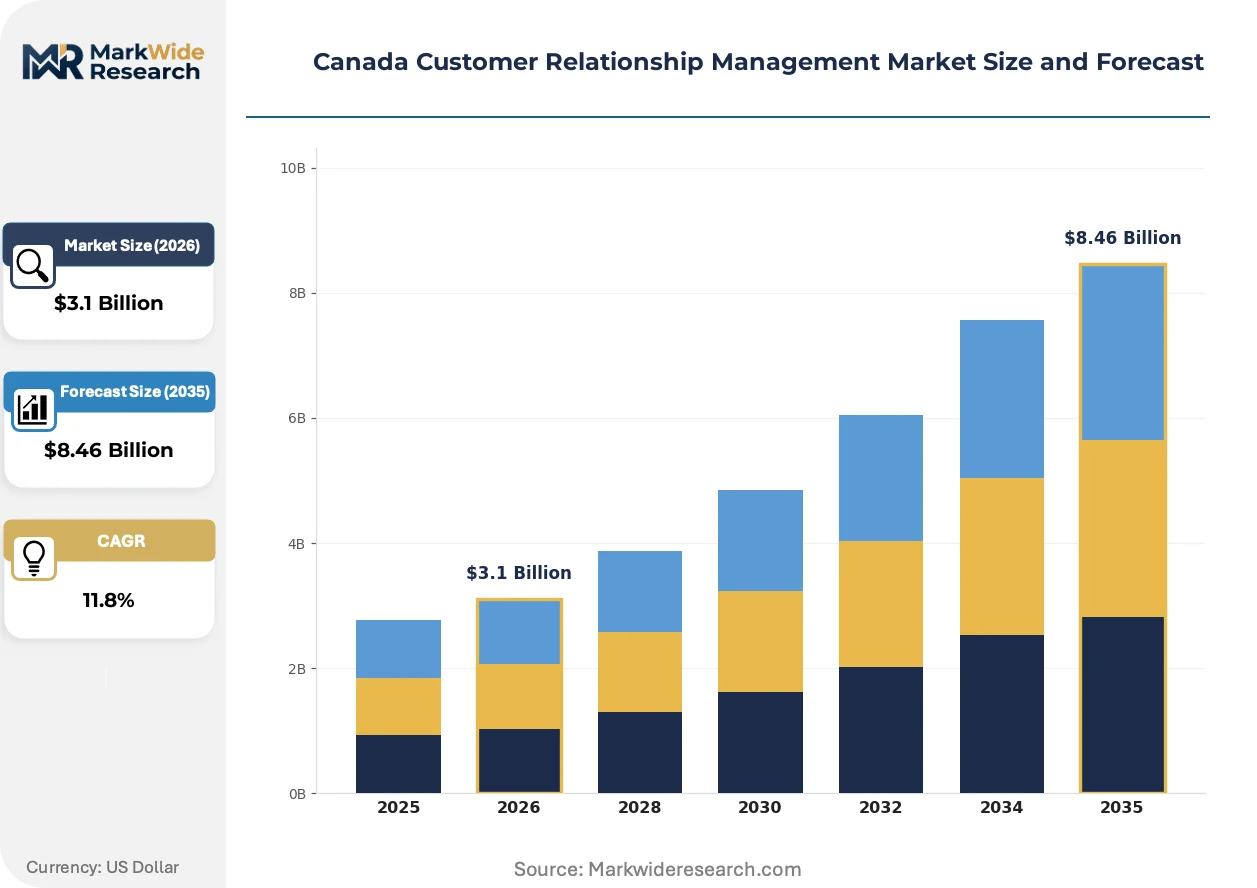
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solution Type: Sales Automation, Marketing Automation, Customer Support, Analytics End User: SMBs, Enterprises, NGOs, Government Industry Vertical: Retail, Healthcare, Financial Services, Telecommunications |
| Companies Covered | JOVACO Solutions, CloudMasonry, Gestisoft, HubSpot, Introhive, Alithya, Set2Close, Salesforce, Hitachi Solutions Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Customer Relationship Management Market Strategic Shifts & Innovations
Canadian CRM markets are pivoting toward composable architectures that separate data storage from engagement orchestration, enabling organizations to swap components without full-platform replacement.
Composable CRM infrastructure is decomposing monolithic platform deployments into modular microservices. Mid-market enterprises in Ontario's manufacturing sector are adopting this approach fastest, selecting best-of-breed components for marketing automation, sales engagement, and service ticketing rather than single-vendor suites. This architecture is compressing vendor lock-in effects and accelerating procurement cycles as buyers mix solutions from multiple providers.
Quebec's Law 25 enforcement timeline is mandating privacy-by-design system architectures with automated data lineage tracking. Financial institutions must demonstrate granular consent audit trails for every customer data touchpoint by 2025 deadlines. Healthcare CRM deployments face parallel pressure from Health Canada requirements for patient identifier governance, pushing vendors to embed deletion workflows natively rather than retrofitting compliance layers.
Subscription fatigue among Canadian enterprises is shortening CRM evaluation cycles and intensifying pilot-to-production demands. Buyers now require proof-of-concept deployments in Toronto-Waterloo corridor data centers before committing to multi-year contracts. Professional services firms and mid-market manufacturers are most aggressive in demanding outcome-based pricing tied to measurable pipeline velocity improvements rather than seat-based licensing.
Canada Customer Relationship Management Market Segmentation
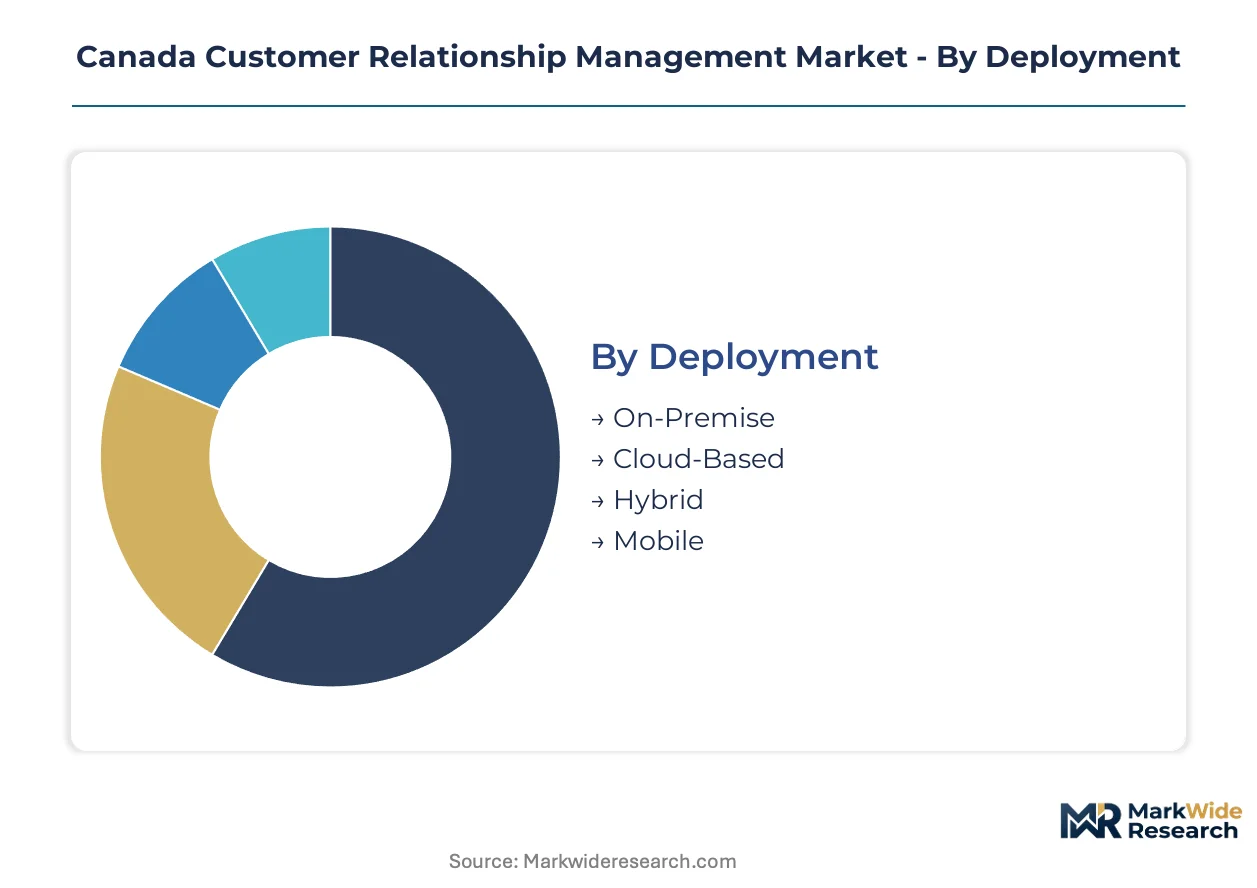
CRM purchasing patterns in Canada diverge sharply across deployment models and industry verticals, with PIPEDA compliance requirements and data sovereignty concerns fragmenting procurement criteria. Understanding these segment boundaries reveals where vendors must architect differentiated go-to-market approaches.
Deployment:
Cloud-based solutions flow through Toronto-Waterloo SaaS vendor clusters and direct enterprise sales teams, while on-premise and hybrid deployments route through systems integrators with Health Canada and provincial regulator relationships.
- Cloud-Based:Multi-tenant architectures with Canadian data residency options dominate new procurement in Ontario's financial services sector. Toronto-based credit unions prioritize vendors offering Toronto-region data centers to satisfy PIPEDA localization mandates without latency penalties.
- Hybrid:Split configurations separating customer engagement data from regulated transaction records command premium pricing in Quebec banking. Montreal institutions deploy these architectures to satisfy Law 25 consent-audit requirements while preserving cloud scalability for non-sensitive workflows.
- On-Premise:Legacy Siebel and Microsoft Dynamics installations persist in federal government accounts with stringent security classifications.
- Mobile:Field-force deployments concentrate in telecommunications technician dispatch and healthcare home-care coordination across Alberta and British Columbia.
By volume, Cloud-Based leads. By growth pace, Hybrid is climbing the fastest as regulated verticals seek middle-ground compliance architectures.
Solution Type:
Procurement concentration varies by functional maturity, with marketing automation commanding the steepest expansion trajectory as retailers invest in real-time personalization infrastructure.
- Marketing Automation:Real-time behavioral targeting engines with sub-second latency requirements drive replacement cycles in Toronto-Waterloo retail clusters. Canadian grocers and apparel chains deploy these systems to unify e-commerce and in-store engagement data.
- Customer Support:Workforce optimization modules with predictive case routing command sustained investment from telecommunications providers managing multilingual service operations across Quebec and Ontario. Bell and Telus procurement teams prioritize these capabilities for cost-per-contact reduction.
- Sales Automation:Pipeline velocity tools with AI-driven forecasting anchor mid-market manufacturing adoption in Ontario's industrial corridor.
- Analytics:Predictive scoring models face emerging scrutiny from federal AI governance frameworks, slowing deployment in financial services pending regulatory clarity.
Marketing Automation captures the most net-new spending. Customer Support delivers the most predictable recurring revenue streams.
End User:
Enterprise accounts concentrate procurement through RFP processes with mandatory ISO 27001 certification, while SMBs purchase through channel partners and self-service marketplaces with faster implementation cycles.
- Enterprises:Multi-year contracts with outcome-based pricing clauses dominate large-account procurement in Toronto's banking headquarters. Royal Bank and TD procurement teams demand proof-of-concept deployments in Canadian data centers before contract commitment.
- SMBs:Subscription fatigue has compressed evaluation cycles to under ninety days for professional services firms and mid-market manufacturers. These buyers increasingly pilot composable architectures mixing best-of-breed components rather than single-vendor suites.
- Government:Federal and provincial crown corporations in Quebec route through Gestisoft and Microsoft Dynamics specialists with existing public sector certifications.
- NGOs:Grant-dependent procurement cycles create lumpy demand concentrated in Toronto and Vancouver social service organizations.
Enterprises anchor total contract value. SMBs are gaining share fastest as composable architectures lower entry barriers.
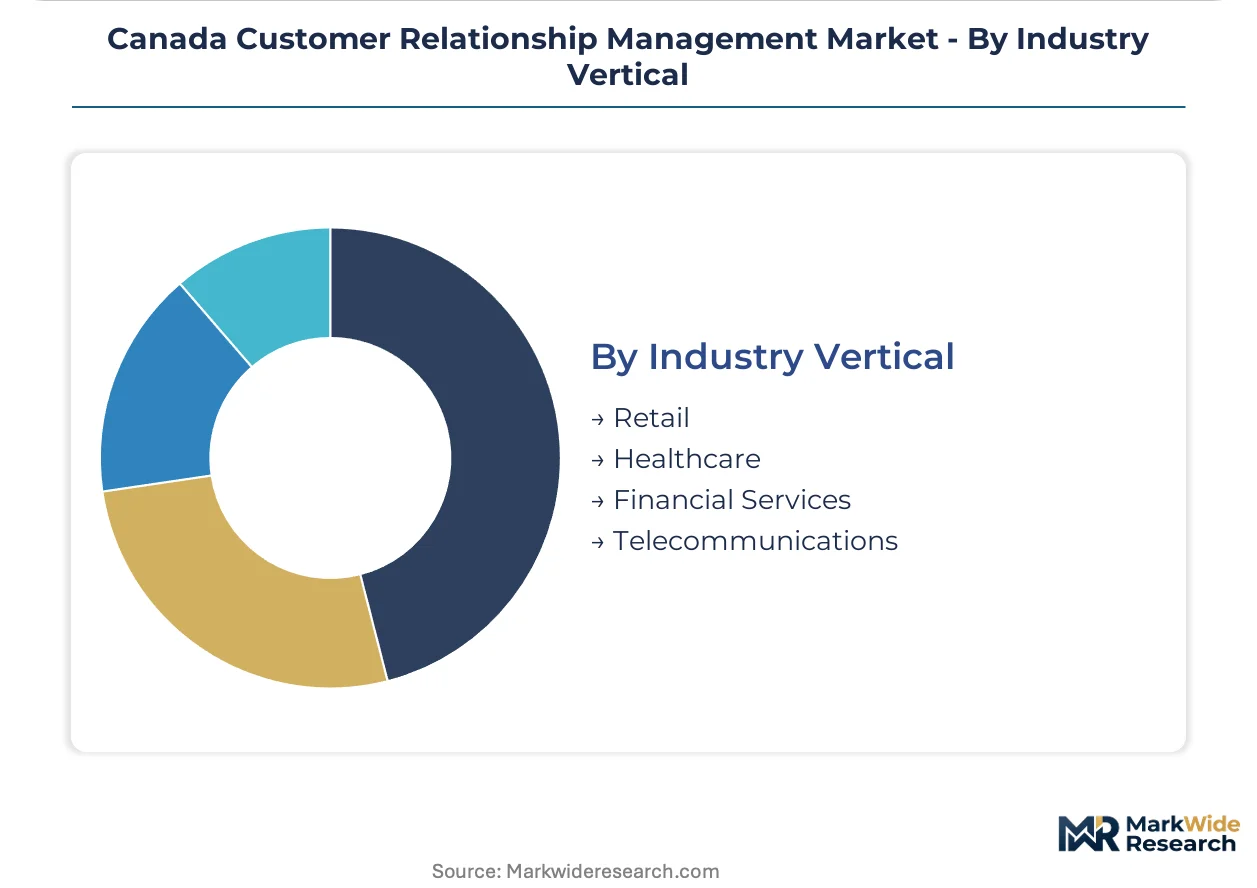
Industry Vertical:
Financial services and healthcare verticals impose the most stringent compliance overlays, bifurcating vendor qualification between enterprise-ready and mid-tier challengers.
- Financial Services:Open banking mandates and PIPEDA consent-management requirements are forcing Toronto credit unions to rebuild unified customer data platforms. These institutions prioritize vendors with native audit-trail capabilities and pre-built connectors to core banking systems.
- Healthcare:Health Canada HIPAA-aligned requirements for patient identifier handling create specialized demand from provincial health authorities in Ontario and Quebec. These deployments require embedded deletion workflows rather than retrofitted compliance layers.
- Retail:Real-time personalization engines with in-store behavioral targeting concentrate demand in the Toronto-Waterloo corridor.
- Telecommunications:Workforce optimization and multilingual support analytics drive sustained procurement from national carriers.
Financial Services leads in total deployment value. Healthcare is expanding most quickly as provincial digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Toronto-Waterloo tech corridor anchors Canadian CRM demand through its dense concentration of SaaS vendors and enterprise buyers, with fiber connectivity and cloud data centers underwriting regional specialization.
Ontario
Toronto's banking headquarters drive unified customer data platform procurement for open banking compliance. PIPEDA mandates push credit unions toward vendors with native audit-trail capabilities. The Waterloo-Kitchener triangle hosts marketing automation specialists serving retail personalization demand.
Quebec
Montreal's provincial crown corporations sustain Microsoft Dynamics integration demand for public sector workflows. Law 25 enforcement compels financial institutions to deploy automated deletion workflows by statutory deadlines. Gestisoft anchors the Quebec City-Montreal corridor with deep provincial certification relationships.
Alberta
Calgary's energy sector procurement concentrates on field-force mobile deployments for technician dispatch coordination. Provincial privacy statutes align with PIPEDA frameworks for cross-border data handling. Edmonton health authorities pilot patient identifier governance systems for home-care coordination networks.
British Columbia
Vancouver's telecommunications carriers invest in multilingual support analytics for cost-per-contact reduction across Pacific operations. Health Canada requirements shape provincial health authority CRM specifications for embedded compliance workflows. The Victoria government cluster maintains legacy on-premise installations with stringent security classifications.
Atlantic Canada
Halifax fintech startups drive composable architecture adoption for lower entry-cost customer engagement platforms. Regional credit unions prioritize Canadian data residency options to satisfy localization mandates without latency penalties. St. John's offshore energy sector lags in cloud migration due to legacy system entrenchment.
Canada Customer Relationship Management Market Key Industry Players
Listed leaders compete with private specialists across certification depth and vertical integration intensity. The Canada Customer Relationship Management Market structures around three tiers: hyperscale platforms with Toronto data residency, Quebec-focused Microsoft Dynamics integrators, and AI-driven relationship intelligence boutiques. Strategic moves concentrate on compliance-native product roadmaps and outcome-based pricing renegotiation.
Within the enterprise-ready tier, Salesforce anchors large-account procurement through AppExchange ecosystem density. Gestisoft occupies a dominant position in Quebec's public sector and provincial crown corporation accounts through Microsoft Dynamics specialization. Introhive exemplifies the relationship intelligence archetype, competing through predictive contact enrichment differentiation from conventional pipeline tools.
| Leading Market Players |
|---|
| JOVACO Solutions |
| CloudMasonry |
| Gestisoft |
| HubSpot |
| Introhive |
| Alithya |
| Set2Close |
| Salesforce |
| Hitachi Solutions Canada |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud capacity utilization in the Toronto-Waterloo corridor concentrates vendor bargaining power and establishes price floors for Canadian data residency options. PIPEDA compliance overhead and Quebec Law 25 certification requirements embed fixed costs that resist downward price pressure across deployment tiers.
Pricing Analysis
Certification level creates the primary spread between enterprise-ready and mid-tier CRM offerings in Canada. Three-tier pricing structure across premium, standard, and economy levels anchors subscription models, with ISO 27001 and PIPEDA-native audit capabilities commanding 40-60% premiums over uncertified alternatives. Cost compression in the mid-market tier is intensifying because composable architectures allow buyers to mix best-of-breed components rather than accepting bundled suites. SMB professional services firms exhibit highest price sensitivity, while federal crown corporations and provincial health authorities prioritize compliance assurance over unit economics.
Supply Chain Analysis
Limited hyperscale data center availability in Canadian jurisdictions creates a chokepoint constraining SaaS deployment velocity for sovereignty-sensitive buyers. Supply concentrates in the United States, Ireland, and Singapore for underlying cloud infrastructure, with Canadian data residency options drawing from Toronto, Montreal, and Vancouver facilities. Raw material dependencies span compute silicon from Taiwan, storage components from South Korea, and networking gear from China. Single-source vulnerability runs through AWS, Azure, and Google Cloud dominance over Canadian enterprise workloads. Distribution runs through direct enterprise sales teams for large accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open banking API convergence and composable CRM microservices are shifting platform economics toward interoperability-first vendor selection. Ecosystem density in the Toronto-Waterloo corridor now determines procurement outcomes more than feature parity.
For Market Incumbents: Secure PIPEDA-native compliance architectures and Quebec Law 25 certification depth before emerging entrants achieve equivalency. Defensive consolidation should prioritize Microsoft Dynamics integration specialists serving Montreal's provincial crown corporations. Channel control through Toronto-based systems integrators with Health Canada relationships represents the critical lever for account retention. For New Entrants and Emerging Players: Differentiate on AI-driven relationship intelligence automation rather than conventional pipeline functionality. White-space targets include Halifax fintech startups seeking lower entry-cost composable platforms and Edmonton health authorities piloting patient identifier governance for home-care networks. A vertical-specific go-to-market angle through HIPAA-aligned healthcare deployments bypasses incumbent saturation in financial services. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-native specialists with embedded deletion workflows and automated consent audit capabilities. Long-term viability hinges on vendors architecting for forthcoming federal AI governance frameworks affecting predictive scoring models. The acquisition target archetype combines Quebec public sector certification depth with API-first integration architectures. Watch for regulatory clarity on algorithmic transparency obligations as the inflection signal for predictive CRM deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Convergence with open banking APIs enables transaction-data-plus-engagement-scoring product bundles for Toronto credit unions. |
| Geographic Expansion | Toronto-region data center investments satisfy PIPEDA localization mandates without latency penalties for Ontario financial institutions. |
| Strategic Partnership | Alliances with Health Canada-certified systems integrators unlock provincial health authority procurement channels. |
| Acquisition of Specialist Firm | Microsoft Dynamics integrators with Quebec crown corporation relationships provide immediate public sector market access. |
| Product Launch | Real-time personalization engines with sub-second latency capture Toronto-Waterloo retail replacement cycles. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with CRM platform executives, IT procurement officers at Canadian financial institutions, Health Canada compliance leads, and Quebec provincial crown corporation technology directors; and secondary validation through PIPEDA regulatory filings, open banking framework disclosures, hyperscaler Canadian data center capex announcements, and provincial health authority procurement databases. Bottom-up deployment volume estimates triangulated against top-down addressable market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derived from segment-level growth rate convergence analysis incorporating open banking mandate timelines, Quebec Law 25 enforcement deadlines, and federal AI governance framework development status as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained PIPEDA enforcement intensity or accelerated federal AI regulation would require recalibration. Forecasts reflect assumptions regarding hyperscale Canadian data center expansion, provincial health digitization funding continuity, and open banking API standardization velocity. Practitioners should keep alternative scenarios live as Health Canada patient identifier governance requirements and Quebec Law 25 audit trail demonstration deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Global Saas Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market