
 Telecom CRM Market | 2026-2036
Telecom CRM Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom CRM Market Analysis
Aftermarket service revenue from subscriber retention analytics is reshaping margin distribution across the Telecom CRM value chain. Salesforce Sales Cloud leverages extensive partner ecosystems to sustain deployment velocity across tier-one carriers. SAP Sales Cloud anchors its position through deep ERP integration with telecom billing systems. Oracle Siebel dominates legacy on-premise installations at incumbent operators navigating hybrid cloud transitions.
Telecom CRM denotes specialized customer relationship management software engineered for communications service providers, incorporating real-time subscriber data ingestion, churn prediction algorithms, and network event correlation at sub-second latency. These platforms orchestrate omnichannel engagement across call centers, mobile applications, and retail touchpoints to maximize lifetime value per connection. Cloud-based deployments now lead adoption curves as carriers retire capital-intensive data center footprints, while enterprise customer segments generate premium pricing due to complex multi-site contract hierarchies and SLA requirements. Analytics functionality represents the fastest-expanding margin pool as operators monetize behavioral data for targeted service bundles.
The Federal Communications Commission shapes US telecom CRM requirements through customer data privacy and consent frameworks tied to broadband subsidy programs. EMA and GDPR compliance obligations in Europe compel vendors to embed granular data governance controls and regional data residency options. India's TRAI mandates subscriber verification protocols that CRM platforms must integrate with biometric identity databases. Stakeholders should monitor regulatory divergence between data localization regimes and cross-border analytics capabilities when selecting deployment architectures.
Market Dynamics
Cloud-first deployment mandates from tier-one carriers are compressing on-premise infrastructure lifecycles and forcing vendors to re-architect data residency controls for multi-jurisdiction compliance.
Growth Catalysts
- GDPR and TRAI mandates:Data localization requirements in the European Union and India's subscriber verification protocols are compelling carriers to upgrade CRM platforms with granular governance controls and biometric identity integration.
- MVNO subscriber management:Mobile virtual network operators are expanding platform adoption to manage churn prediction and upsell data bundles through real-time behavioral analytics.
- Edge computing architectures:Sub-second latency requirements for network event correlation are driving investment in distributed CRM processing nodes closer to cell towers.
Market Restraints
- Legacy system entrenchment:Oracle Siebel and SAP on-premise installations at incumbent operators create technical debt that slows hybrid cloud migration timelines.
- Specialized talent scarcity:Shortages of engineers skilled in real-time data ingestion and churn algorithm development constrain deployment velocity.
- Input cost volatility:Fluctuations in cloud storage pricing and GPU compute costs for AI-driven analytics compress margin predictability for SaaS vendors.
Strategic Opportunities
- Japan enterprise segment:Complex multi-site contract hierarchies and stringent SLA requirements in Japan's corporate telecom market generate premium pricing potential for cloud-native vendors.
- 5G network slicing monetization:CRM platforms that correlate subscriber behavior with quality-of-service tiers can capture revenue from enterprise IoT and private network deployments.
- Cross-border analytics frameworks:Vendors that architect federated learning models compliant with both GDPR and India's data localization rules can unlock multi-territory carrier contracts.
Industry Challenges
- Billing system integration complexity:ERP-to-CRM synchronization with telecom-specific charging engines requires custom middleware that extends implementation cycles.
- Biometric data governance:India's Aadhaar-linked subscriber verification mandates expose carriers to compliance penalties if CRM platforms fail audit trails for identity database access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom CRM Market |
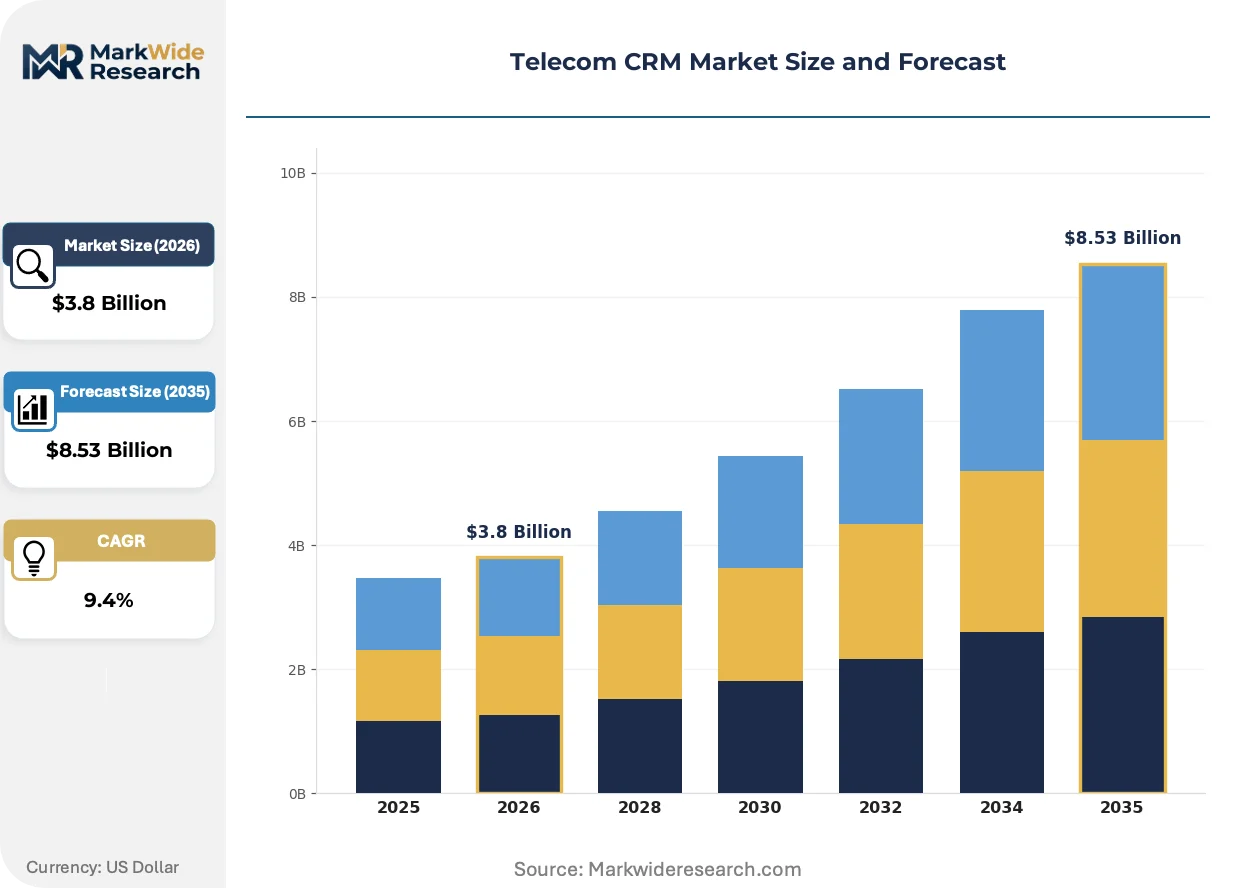
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS Customer Type: Residential, Small Business, Enterprise, Government Functionality: Sales Management, Customer Support, Marketing Automation, Analytics Service Type: Consulting, Integration, Managed Services, Support |
| Companies Covered | Oracle Siebel, Zoho CRM, Salesforce Sales Cloud, HubSpot, LeadSquared, Dynamics 365 Sales, Creatio, Pipedrive, SAP Sales Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom CRM Market Emerging Trajectories
Artificial intelligence and real-time data architectures are compressing decision latency in subscriber engagement, while regulatory fragmentation forces architectural flexibility.
Real-time decisioning engines are hybridizing batch and stream processing architectures to enable sub-second churn intervention. Tier-one carriers in Germany and the United States are deploying these systems at scale. The technology is hybridizing traditional campaign management into always-on, event-triggered engagement that collapses marketing-to-action cycles from days to milliseconds.
GDPR's Article 44 restrictions on international data transfers are forcing CRM vendors to deploy region-locked instances with automated residency enforcement. European carriers now require proof of data-sovereign architecture before contract award. The regulation is compressing vendor consolidation as smaller players lack capital for multi-region infrastructure replication.
Subscription-based pricing for analytics modules is displacing perpetual licenses in enterprise procurement. German and Japanese carriers are leading this shift, unbundling predictive churn and network quality correlation as metered services. Procurement teams now prioritize outcome-linked contracts over feature-checklist evaluations, compressing vendor differentiation to demonstrable retention lift metrics.
Telecom CRM Market Segmentation
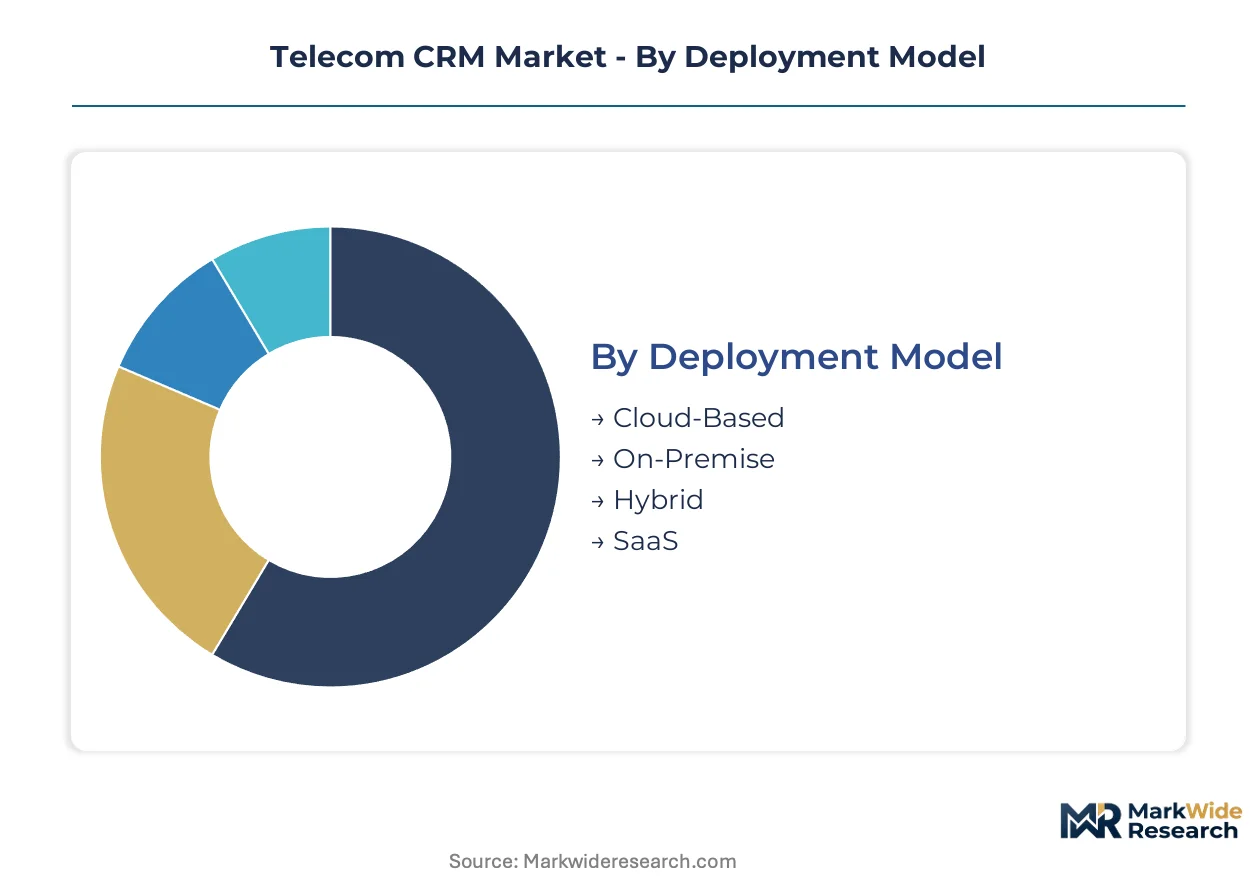
Telecom CRM segmentation reveals how deployment architectures, customer complexity, and service intensity reshape vendor economics. Each dimension carries distinct margin profiles and integration burdens that determine platform selection across carrier tiers.
Deployment Model:
After-sales service intensity varies sharply across deployment architectures, with cloud-native platforms demanding continuous subscription support while on-premise installations require episodic upgrade cycles.
- Cloud-Based:Multi-tenant architectures with automatic scaling and zero-downtime updates dominate tier-one carrier roadmaps in Germany and Japan. Real-time data residency controls satisfy GDPR and India's TRAI mandates without infrastructure ownership. Cloud-based holds the largest share; momentum sits with SaaS.
- SaaS:Metered consumption models unbundle predictive churn and network quality correlation as subscription services. German carriers lead procurement of outcome-linked contracts tied to demonstrable retention lift metrics.
- On-Premise:Oracle Siebel and SAP legacy installations at incumbent operators create technical debt that slows hybrid migration timelines.
- Hybrid:Federated architectures bridge edge computing nodes with centralized data lakes for sub-second latency in network event correlation.
Cloud-native architectures concentrate investment; hybrid configurations address transitional compliance requirements.
Customer Type:
Contract complexity escalates from residential subscribers through government procurements, with enterprise segments generating premium pricing due to multi-site SLA hierarchies.
- Enterprise:Complex contract hierarchies spanning distributed facilities in Japan and the United States command platform customization for quality-of-service tiering. Procurement teams prioritize outcome-linked contracts with network slicing monetization capabilities.
- Small Business:Standardized bundles with self-service portals concentrate adoption in MVNO channels seeking churn prediction without dedicated IT staff.
- Residential:High-volume, low-margin subscriber bases drive automation investment in real-time behavioral analytics for upsell targeting.
- Government:Biometric identity integration and audit trail requirements align with India's Aadhaar-linked verification mandates.
Enterprise commands premium pricing; small business shows steepest expansion trajectory as MVNO adoption accelerates.
Functionality:
Margin pools concentrate in analytics modules where behavioral data monetization outpaces core CRM transaction processing.
- Analytics:Predictive churn algorithms and network event correlation at sub-second latency represent the fastest-expanding revenue component. Subscription-based pricing displaces perpetual licenses in German and Japanese procurement.
- Customer Support:Omnichannel orchestration across call centers, mobile applications, and retail touchpoints maximizes lifetime value per connection.
- Sales Management:Pipeline visibility tools integrate with telecom-specific charging engines through custom middleware.
- Marketing Automation:Always-on, event-triggered engagement collapses campaign-to-action cycles from days to milliseconds.
Analytics captures disproportionate investment; marketing automation gains share as real-time decisioning engines deploy at scale.
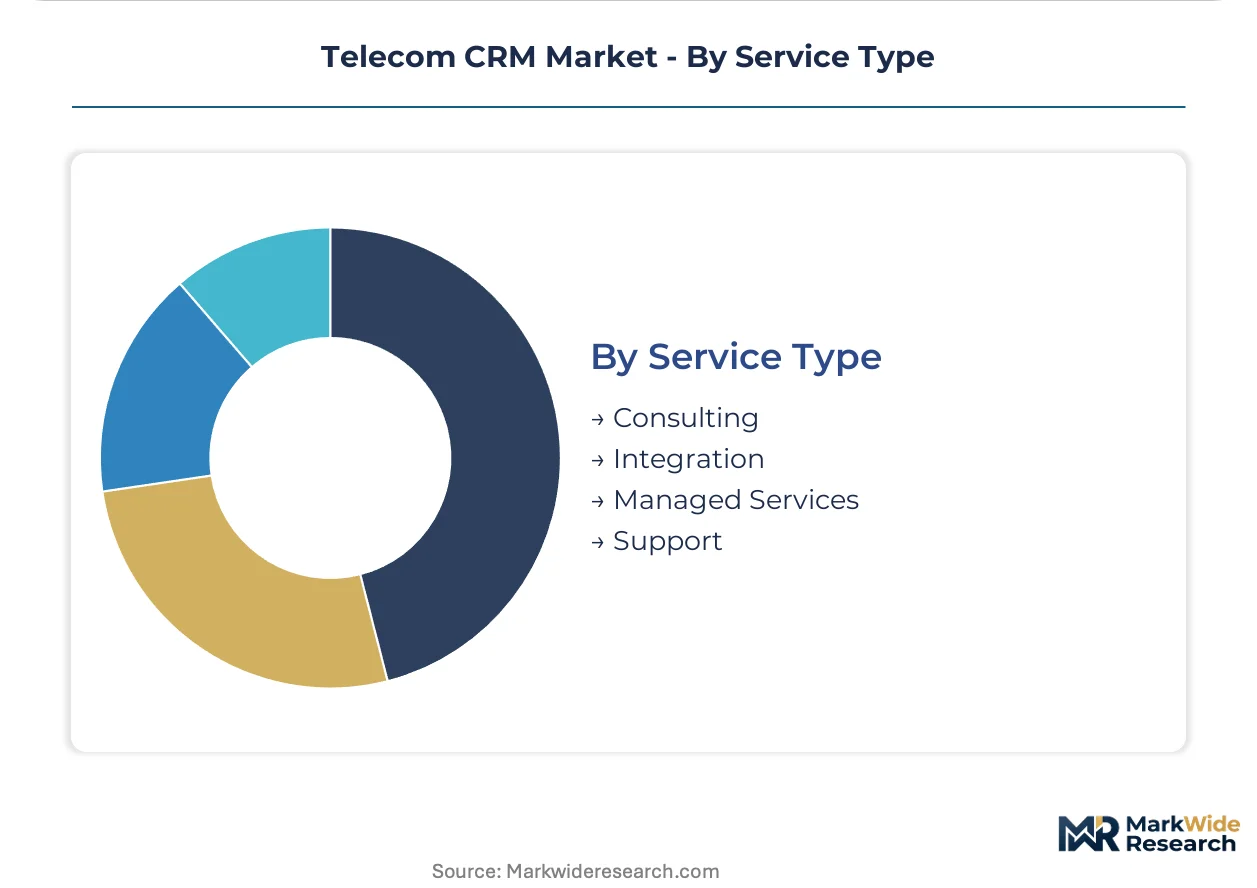
Service Type:
Professional services intensity correlates with billing system integration complexity and regulatory compliance verification.
- Integration:ERP-to-CRM synchronization with telecom charging engines requires specialized middleware that extends implementation cycles. Demand concentrates where legacy SAP installations anchor billing infrastructure.
- Managed Services:Continuous platform operation and update management appeal to carriers retiring capital-intensive data center footprints.
- Consulting:Data governance architecture and residency control design support GDPR Article 44 compliance and India's localization requirements.
- Support:Tiered response structures address biometric data governance audit requirements for subscriber verification protocols.
Integration services dominate professional services revenue; managed services expand fastest as cloud-first mandates accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity for enterprise-grade Telecom CRM platforms, while MVNO-driven markets in India and small business segments in the United States show acute sensitivity to per-seat licensing costs.
United States
Tier-one carriers dominate procurement of real-time decisioning engines with sub-second latency requirements. FCC broadband subsidy programs impose customer data privacy frameworks that CRM vendors must embed for compliance. Seattle and Austin clusters concentrate cloud-native development talent for distributed processing architectures.
Germany
Enterprise telecom contracts with complex multi-site SLA hierarchies generate premium pricing for analytics modules. GDPR Article 44 restrictions mandate region-locked data residency with automated enforcement mechanisms. Frankfurt's financial services corridor drives demand for network slicing monetization capabilities.
Japan
Corporate telecom markets require platform customization for quality-of-service tiering across distributed facilities. METI industrial digitization incentives accelerate retirement of legacy on-premise installations. Tokyo-Osaka corridor leads procurement of outcome-linked subscription contracts.
India
MVNO expansion fuels adoption of churn prediction platforms without dedicated IT infrastructure. TRAI subscriber verification protocols mandate biometric identity integration with Aadhaar-linked audit trails. Bangalore and Hyderabad clusters concentrate SaaS development for localized deployment models.
United Kingdom
Mid-market carriers prioritize hybrid architectures bridging edge computing with centralized data lakes. Post-Brexit data governance divergence from EU frameworks complicates cross-border analytics strategies. London's fintech ecosystem drives demand for real-time behavioral correlation engines.
Telecom CRM Market Vendor Landscape
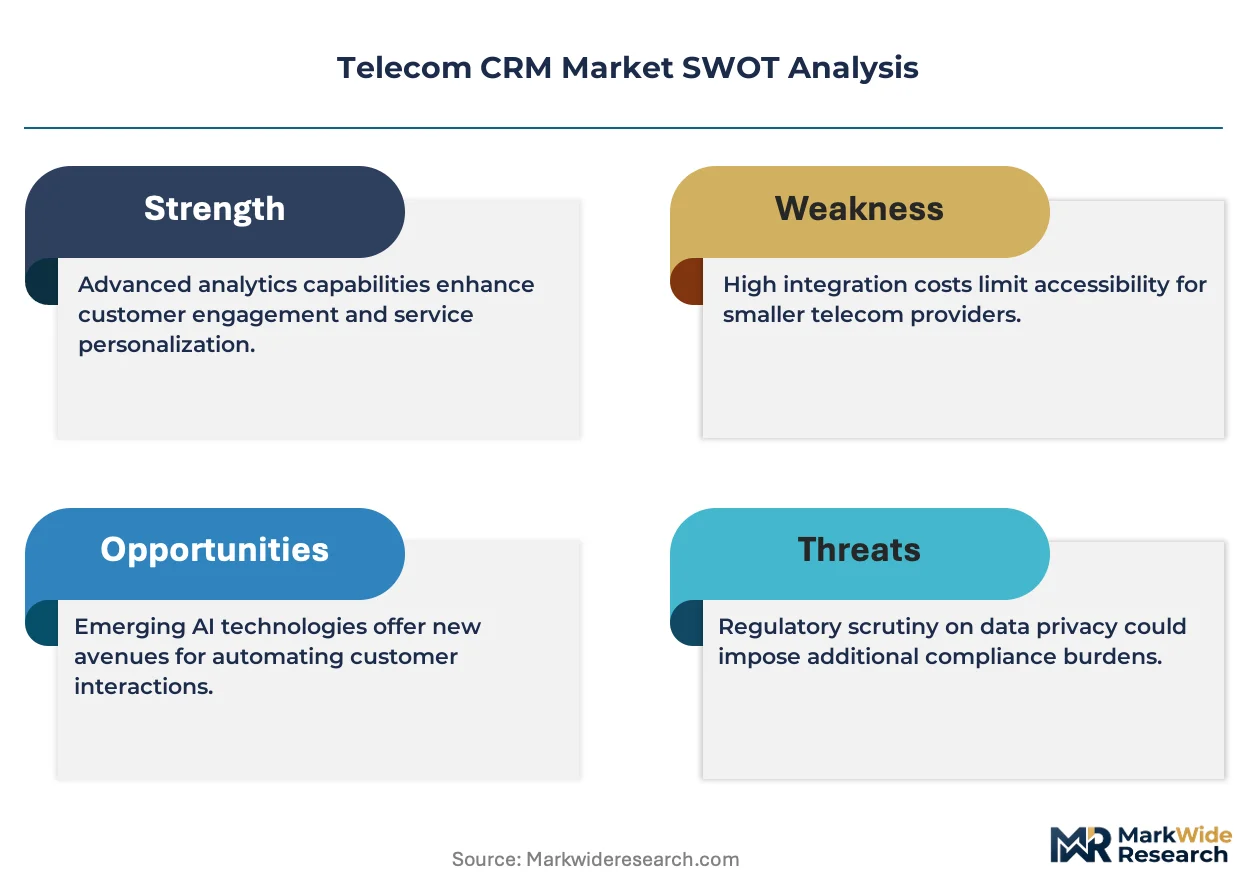
Capability concentration sits with specialized analytics vendors; scale advantage sits with horizontal CRM incumbents with telecom-specific partner ecosystems. The market structures around three tiers: cloud-native challengers unbundling predictive modules, legacy ERP-integrated suites defending billing synchronization dominance, and vertical specialists capturing MVNO channels. Dominant competitive moves include federated learning partnerships for multi-jurisdiction compliance and outcome-based pricing tied to demonstrable retention metrics.
Within the ERP-anchored tier, SAP Sales Cloud and Oracle Siebel exemplify incumbent positioning through deep billing system integration. Salesforce Sales Cloud occupies the cloud-native scale position, leveraging extensive carrier partnerships to sustain deployment velocity. Zoho CRM represents the emerging-market accessibility archetype, capturing small business and MVNO segments with standardized self-service configurations.
| Leading Market Players |
|---|
| Oracle Siebel |
| Zoho CRM |
| Salesforce Sales Cloud |
| HubSpot |
| LeadSquared |
| Dynamics 365 Sales |
| Creatio |
| Pipedrive |
| SAP Sales Cloud |
| Others |
Supply Flow & Price Mechanics
Bangalore's SaaS development corridor anchors cloud-native CRM capacity, with distributed engineering clusters in Hyderabad and Pune feeding subscription pricing power downstream. Indian vendors leverage this concentration to undercut legacy ERP-integrated suites on per-seat licensing, compressing margin structures for on-premise incumbents.
Pricing Analysis
Aftermarket service revenue from subscriber retention analytics drives lifetime value, with subscription-based pricing for predictive modules displacing perpetual licenses in enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native vendors with real-time decisioning from legacy suites with batch processing. Pricing pressure stems from GPU compute cost volatility for AI-driven churn algorithms, squeezing SaaS margin predictability. MVNOs and small business segments exhibit acute price sensitivity, while Japan's enterprise telecom contracts with complex SLA hierarchies demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration for CRM hardware infrastructure sits with Foxconn, Wistron, and Flex holding server assembly capacity across Taiwan, China, and Mexico. Software supply chains draw from open-source stream processing frameworks, hyperscaler cloud infrastructure, and proprietary AI model training pipelines. Single-source vulnerability concentrates in NVIDIA GPU supply for real-time analytics workloads. Distribution runs through direct enterprise sales teams for tier-one carriers, with channel partners and self-service portals penetrating MVNO and small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telecom CRM sits in early-cycle expansion as 5G network slicing and edge computing architectures create fresh monetization vectors for subscriber behavior correlation.
For Market Incumbents: Entrench billing system integration dominance by deepening ERP synchronization with telecom-specific charging engines, defending against cloud-native challengers unbundling predictive analytics. Prioritize federated learning partnerships that satisfy GDPR Article 44 and India's TRAI localization mandates simultaneously, preserving multi-territory carrier contracts. Invest in biometric data governance audit capabilities to capture India's Aadhaar-linked verification procurement. For New Entrants and Emerging Players: Build out white-space positions in Japan's enterprise segment, where complex multi-site contract hierarchies and stringent SLA requirements generate premium pricing with limited incumbent cloud-native presence. Target India's MVNO expansion wave with standardized self-service configurations that bypass dedicated IT staff requirements. Lead with outcome-linked subscription contracts tied to demonstrable churn reduction metrics rather than feature-checklist competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with real-time data ingestion capabilities and regulatory compliance automation. Long-term viability hinges on federated architecture investments spanning data localization regimes. Acquisition target archetype: analytics vendors with sub-second latency engines and established carrier proof points. Monitor 5G private network deployment velocity as inflection signal for enterprise IoT monetization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Enables GDPR-TRAI dual compliance for multi-territory carrier contracts. |
| Biometric Identity Integration | Captures India's Aadhaar-linked subscriber verification procurement mandates. |
| Edge Computing Node Deployment | Delivers sub-second latency for network event correlation at cell towers. |
| Outcome-Linked Subscription Pricing | Aligns vendor economics with demonstrable subscriber retention lift metrics. |
| ERP Billing Synchronization | Defends incumbent position through deep telecom charging engine integration. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FCC filings, TRAI regulatory circulars, GDPR implementation guidance, and hyperscaler capex disclosures. Primary interviews engaged CRM platform product managers, telecom carrier IT procurement officers, MVNO operations executives, systems integration specialists, and data governance compliance leads. Bottom-up triangulation across deployment model, customer type, functionality, and service type segmentation dimensions validates top-down market sizing.
Forecast inputs incorporate cloud-first mandate velocity, 5G network slicing commercialization timelines, and regulatory divergence between data localization regimes. Analytical framework models deployment architecture transitions, enterprise contract complexity premiums, and analytics module unbundling trends across the projection horizon. CAGRs derive from segment-level adoption curves weighted by carrier capital expenditure patterns and SaaS pricing elasticity by geography.
Stress conditions across GPU compute cost volatility, TRAI audit penalty severity, and GDPR Article 44 enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding carrier data center retirement timelines and MVNO market entry velocity. Quarterly review of 5G private network deployment rates and federated learning regulatory clarity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Global Saas Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Customer Communication Management Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Europe Cloud CRM Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
Global CRM197 Market