
 Smart Customer Service System Market | 2026-2036
Smart Customer Service System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Customer Service System Market Analysis
India's expanding IT services corridor is reshaping competitive dynamics in smart customer service infrastructure. Salesforce leverages its Einstein AI layer to anchor enterprise automation pipelines across North American financial institutions. Zendesk sustains mid-market penetration through streamlined ticketing workflows that reduce agent onboarding friction.
Smart customer service systems integrate natural language processing engines, sentiment analysis algorithms, and omnichannel routing protocols to automate inquiry resolution and escalate complex cases to human agents. The technology segment spans chatbots, virtual assistants, AI analytics, and voice recognition modalities, with voice recognition gaining traction in telecommunications due to biometric authentication requirements. Cloud deployment dominates enterprise procurement, though hybrid architectures persist in banking where data sovereignty concerns restrict full SaaS migration.
The EU AI Act imposes risk-classification obligations on automated decision systems used in European customer engagement, while the FDA oversees AI-enabled medical support chatbots in the United States through software-as-medical-device pathways. India's TRAI guidelines on unsolicited commercial communication constrain outbound AI dialing practices for telemarketing use cases. Stakeholders must track evolving algorithmic audit mandates across jurisdictions to preserve cross-border service deployment flexibility.
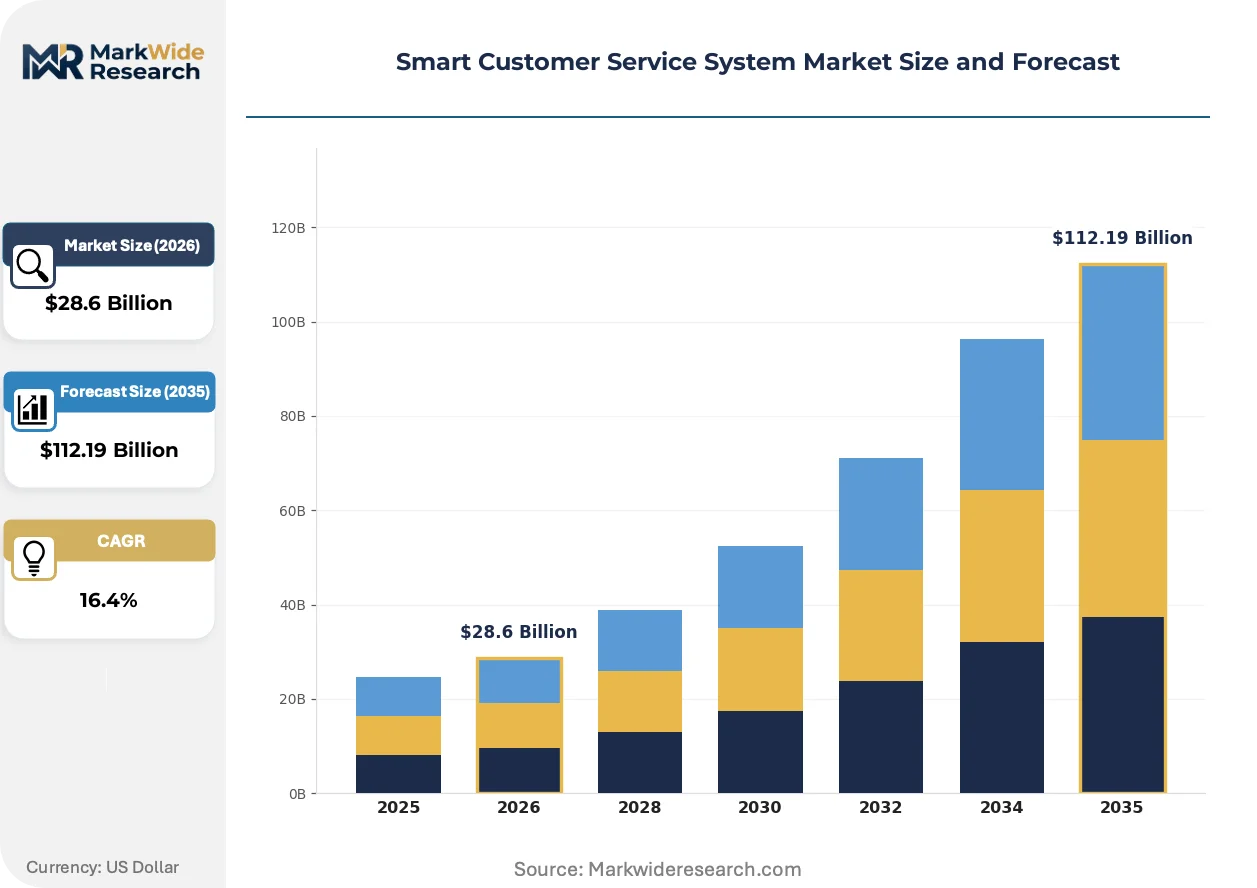
Market Dynamics
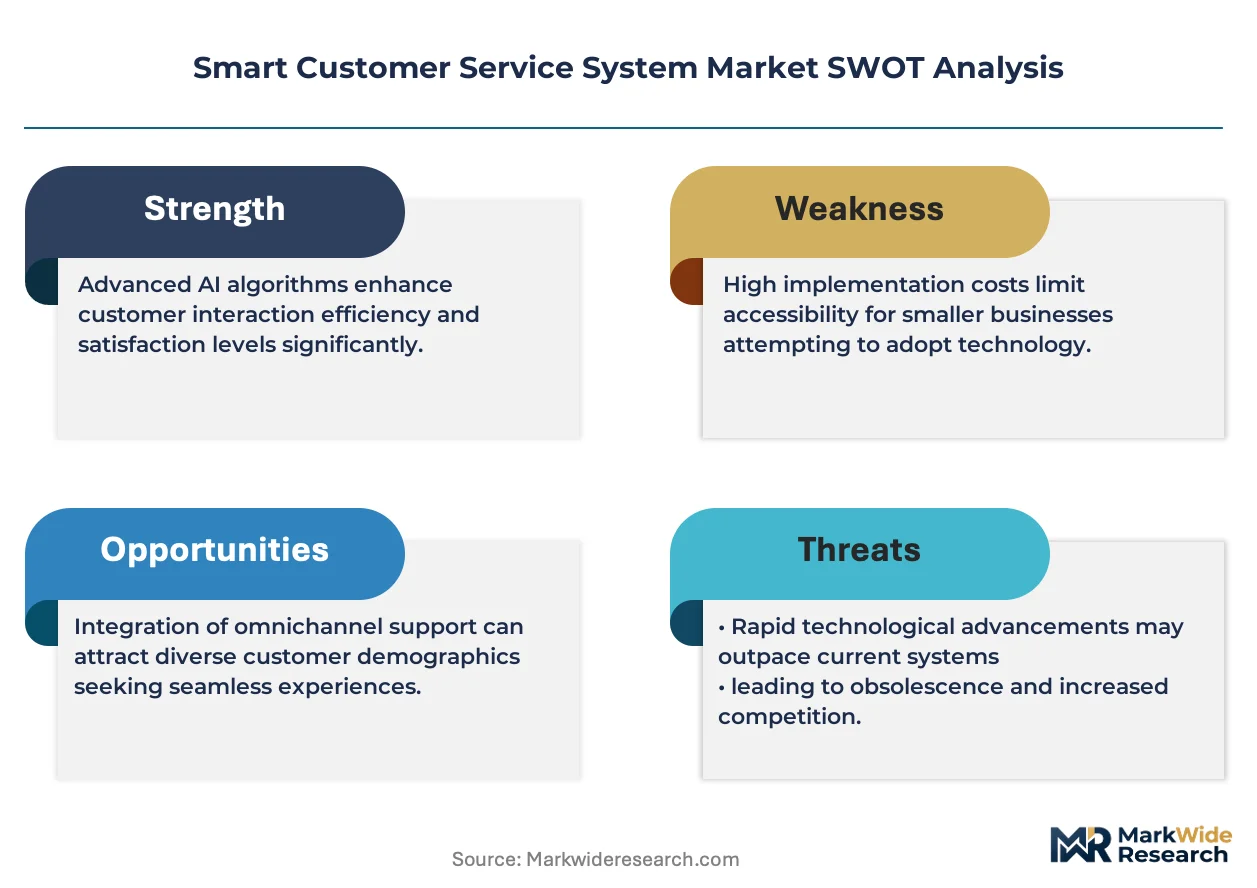
Banking institutions are accelerating cloud migration for contact center modernization while EU AI Act compliance deadlines force algorithmic transparency investments. This dual pressure is restructuring procurement priorities across enterprise service infrastructure.
Growth Catalysts
- EU AI Act transparency mandates:European enterprises must deploy auditable AI decision systems for customer engagement, creating immediate upgrade cycles for legacy chatbot architectures.
- Biometric authentication protocols:Telecommunications carriers are expanding voice recognition deployments to satisfy fraud prevention requirements in high-value account servicing.
- India's IT services corridor:The country's technical workforce concentration is enabling cost-competitive implementation of omnichannel routing platforms for North American financial institutions.
Market Restraints
- Data sovereignty restrictions:Banking regulators in Germany and France block full SaaS migration, forcing expensive hybrid cloud architectures that fragment vendor ecosystems.
- GPU compute cost volatility:Training and inference expenses for large language models underpinning sentiment analysis engines fluctuate with semiconductor supply constraints.
- Human agent substitution limits:Complex escalation protocols require maintaining expensive specialist workforces, capping automation-driven margin expansion.
Strategic Opportunities
- Underpenetrated SME segment:Mid-market enterprises in Spain and Italy lack resources for custom AI deployments, creating whitespace for standardized SaaS ticketing workflows.
- Convergence of NLP and edge computing:On-device inference for voice recognition reduces latency and data transfer costs, opening mobile-first customer service models.
- India's TRAI compliance tooling:Outbound dialing restrictions on unsolicited commercial communication create demand for consent-management platforms integrated with AI dialers.
Industry Challenges
- Prompt engineering talent scarcity:Enterprises struggle to hire specialists capable of optimizing large language model outputs for domain-specific customer queries.
- Cross-jurisdiction audit fragmentation:Algorithmic transparency requirements differ between EU AI Act risk classifications and FDA software-as-medical-device pathways for healthcare chatbots.
- Legacy CRM integration complexity:Decades-old customer databases in insurance and banking resist seamless API connectivity with modern sentiment analysis pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Customer Service System Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chatbots, Virtual Assistants, AI Analytics, Voice Recognition End User: Retail, Telecommunications, E-Commerce, Banking Deployment: Cloud, On-Premises, Hybrid, SaaS Service Type: Technical Support, Customer Engagement, Ticketing System, Feedback Management |
| Companies Covered | Salesforce, Zendesk, Freshworks, Microsoft, Oracle, IBM, ServiceNow, Alibaba Cloud, Huawei Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Customer Service System Market Emerging Trajectories
Generative AI architectures are compressing traditional software development cycles for customer service automation. Vendors and enterprises alike are racing to embed these capabilities before regulatory frameworks solidify.
Multimodal large language models are collapsing the distinction between text, voice, and visual customer service channels. Banking institutions in the United States are deploying unified inference engines that handle chat, email, and call transcription through single model weights. This convergence eliminates the vendor fragmentation that previously required separate contracts for each channel modality.
The EU AI Act's risk-classification framework is forcing documentation investments for high-risk automated decision systems. Customer service platforms used in credit scoring or insurance claim triage must maintain algorithmic audit trails. European financial institutions are responding by segregating European customer data processing from global AI training pipelines to limit compliance scope.
Subscription-based pricing for AI agent capacity is displacing traditional per-seat licensing in enterprise procurement. North American technology firms are negotiating consumption models tied to resolved inquiry volumes rather than software licenses. This shift concentrates vendor risk on automation effectiveness and accelerates performance benchmarking between competing platforms.
Smart Customer Service System Market Segmentation
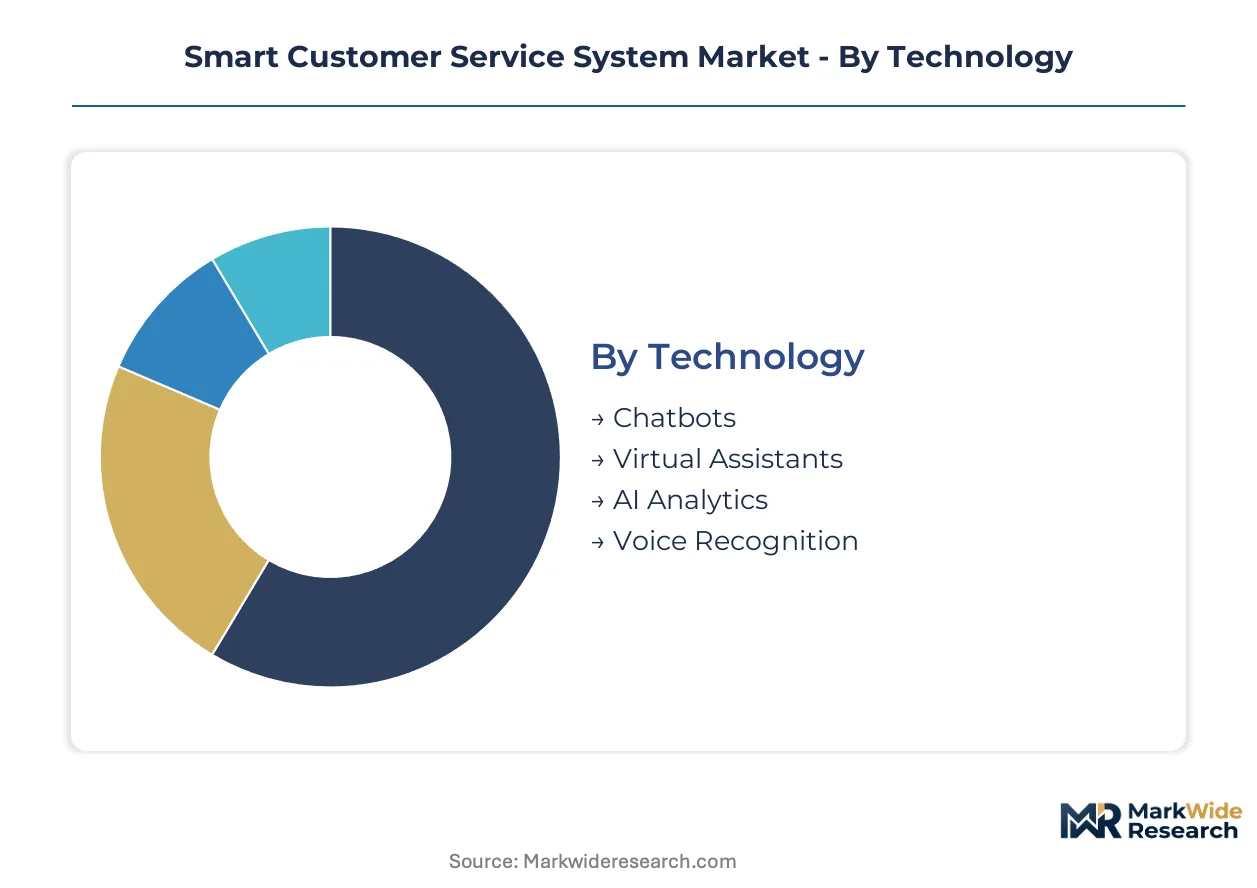
Smart customer service systems fragment across technology modalities, deployment architectures, and service applications. Procurement patterns diverge sharply between regulated banking environments and high-velocity retail operations, forcing vendors to maintain parallel product roadmaps.
Technology:
Mature natural language processing stacks dominate enterprise procurement while emerging multimodal architectures reshape competitive dynamics.
- Chatbots:Rule-based and retrieval-augmented dialogue systems handle transactional queries across retail and telecommunications. Banking institutions in the United States deploy these for balance inquiries and payment scheduling, constrained by FFIEC guidance on automated financial advice.
- Virtual Assistants:Conversational AI agents with persistent context memory manage multi-turn interactions. E-commerce platforms in India leverage these for order tracking and return processing, driven by TRAI-mandated response time standards for digital commerce grievances.
- AI Analytics:Sentiment classification and intent prediction engines.
- Voice Recognition:Biometric speaker identification and speech-to-text transcription.
Chatbots retain volume leadership; virtual assistants hold the steepest expansion curve.
End User:
Cost-tier stratification separates capital-intensive banking deployments from lightweight retail implementations.
- Retail:High-volume, low-complexity inquiry handling across brick-and-mortar and digital channels. Seasonal demand spikes drive preference for elastic cloud capacity in the United States.
- Telecommunications:Account security and fraud prevention applications. German carriers deploy voice biometric authentication to satisfy BSI technical guidelines for telecommunications security.
- E-Commerce:Return logistics and delivery coordination automation.
- Banking:Credit decision support and wealth management triage. Hybrid architectures predominate due to ECB data localization expectations for payment service records.
Retail captures the largest deployment base; banking commands the highest average contract value.
Deployment:
Application-criticality determines infrastructure choices, with regulated workloads resisting full SaaS migration.
- Cloud:Scalable compute for model training and inference. North American technology firms prioritize this for rapid experimentation cycles.
- On-Premises:Air-gapped installations for classified government and defense customer service operations.
- Hybrid:Sensitive data processing on local infrastructure with model training in cloud enclaves. French banking regulators encourage this architecture for algorithmic audit trail preservation.
- SaaS:Fully managed multi-tenant platforms with standardized APIs.
Cloud deployments scale fastest; hybrid configurations expand most quickly in regulated European markets.
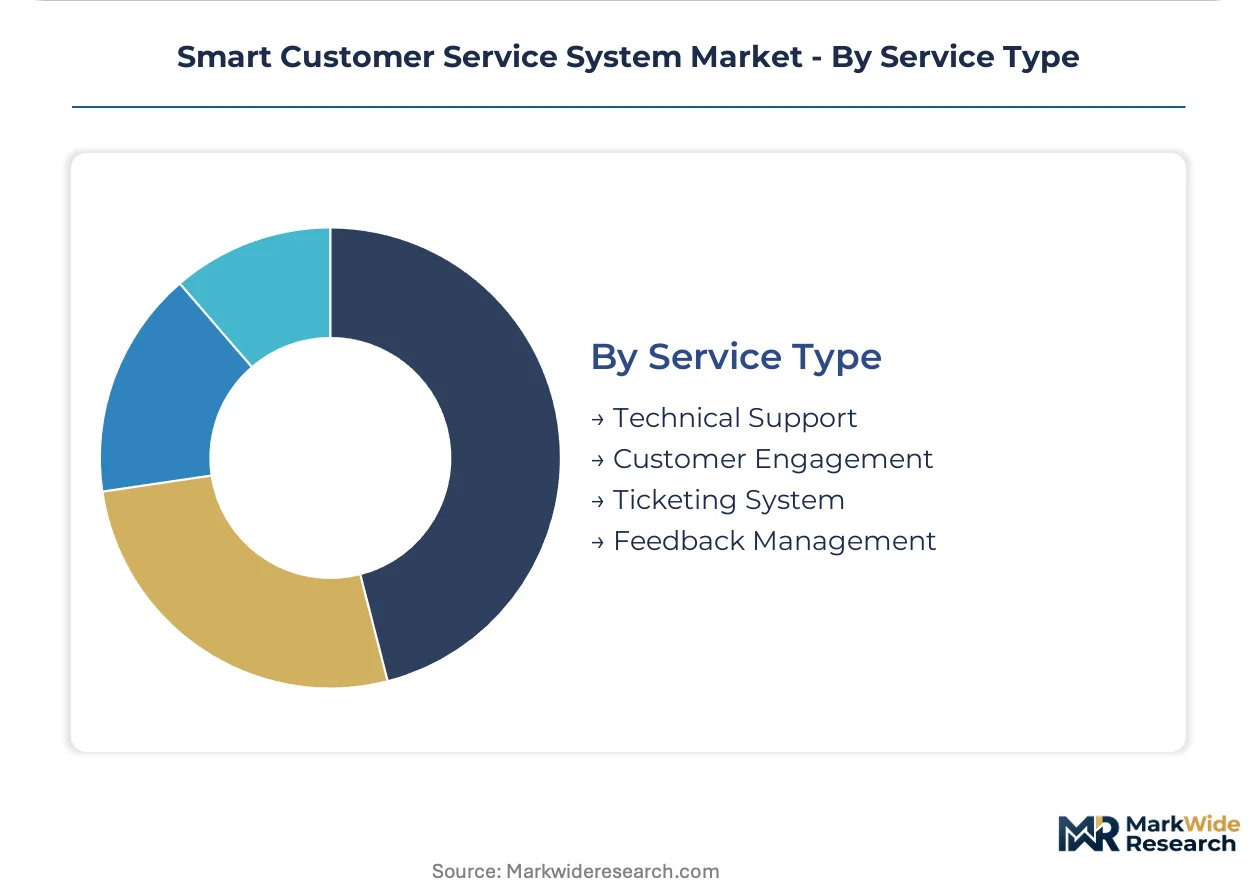
Service Type:
Customer type stratification separates enterprise-grade technical support from self-service engagement tools.
- Technical Support:Diagnostic troubleshooting and escalation management for complex hardware and software products. IT vendors in India deliver these services through 24/7 follow-the-sun operations.
- Customer Engagement:Proactive outreach and loyalty program management. GDPR consent requirements constrain outbound automation in European markets.
- Ticketing System:Case routing and resolution tracking workflows.
- Feedback Management:Survey orchestration and review aggregation platforms.
Technical support maintains the deepest incumbent vendor relationships; customer engagement platforms are gaining share fastest in subscription-economy sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure providers cluster in the United States, while implementation services concentrate in India's technical workforce corridors. Regulatory divergence across jurisdictions fragments deployment architectures.
United States
Financial institutions drive contact center modernization through AI-powered platforms. The FDA regulates AI-enabled medical support chatbots through software-as-medical-device pathways. Silicon Valley and Seattle host cloud-native vendors developing unified inference engines for multimodal customer interactions.
Germany
Banking regulators enforce data localization through ECB expectations for payment service records. The BSI mandates technical guidelines for telecommunications security including voice biometric authentication. Frankfurt and Munich sustain hybrid cloud architectures that segregate sensitive customer data processing from global AI training pipelines.
India
North American financial institutions outsource omnichannel platform implementation to cost-competitive technical workforces. TRAI guidelines constrain outbound AI dialing practices for telemarketing use cases. Bangalore and Hyderabad deliver 24/7 follow-the-sun technical support operations for IT vendors.
France
Banking regulators encourage hybrid architectures for algorithmic audit trail preservation. The EU AI Act imposes risk-classification obligations on automated decision systems in credit scoring and insurance claim triage. Paris hosts enterprises segregating European customer data processing from global AI training to limit compliance scope.
China
Domestic cloud providers expand AI analytics and voice recognition capabilities for telecommunications fraud prevention. MIIT standards govern data processing in customer engagement platforms. Shenzhen and Beijing anchor development of multimodal large language models collapsing distinctions between text, voice, and visual service channels.
Smart Customer Service System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying NLP engines, sentiment analysis algorithms, and voice recognition modules. The vendor landscape consolidates around full-stack cloud providers while point-solution specialists defend niche positions in biometric authentication and edge inference. Three archetypes dominate: horizontal SaaS platforms, vertical industry suites, and infrastructure-as-a-service providers. Competitive moves concentrate on strategic partnerships bundling AI capacity with legacy CRM integration, and geographic expansion into underpenetrated European mid-markets.
Within the horizontal platform tier, Salesforce and Zendesk occupy positions anchoring enterprise automation pipelines across North American financial institutions. Freshworks exemplifies the mid-market penetration archetype through streamlined deployment models. Alibaba Cloud and Huawei Cloud represent the infrastructure-centric approach, leveraging domestic scale in voice recognition and edge computing deployments for telecommunications carriers.
| Leading Market Players |
|---|
| Salesforce |
| Zendesk |
| Freshworks |
| Microsoft |
| Oracle |
| IBM |
| ServiceNow |
| Alibaba Cloud |
| Huawei Cloud |
| Others |
Supply Flow & Price Mechanics
Bangalore's technical workforce concentration anchors global implementation capacity for smart customer service platforms, concentrating deployment expertise in a single corridor that shapes downstream pricing power for North American financial institutions procuring omnichannel modernization.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for automated customer engagement systems deployed across European banking and insurance sectors. Pricing stratifies across premium, standard, and economy tiers based on algorithmic audit trail completeness and GDPR-compliant data residency certification. Cost compression in the economy tier intensifies because India's IT services corridor enables competitive labor arbitrage for implementation and maintenance. Mid-market enterprises in Southern Europe exhibit the highest price sensitivity due to constrained IT budgets, while German banking incumbents accept premium positioning to satisfy ECB data localization expectations.
Supply Chain Analysis
US semiconductor export controls on advanced GPU clusters limit training infrastructure availability for large language model development in certain jurisdictions. Taiwan, South Korea, and the United States anchor the geographic supply concentration for high-performance inference chips that underpin sentiment analysis engines. The technology stack draws from NVIDIA data center GPUs, specialized AI accelerators, and cloud-hosted model weights as core inputs. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant supply chain risk. Distribution runs through hyperscaler marketplaces and direct enterprise licensing channels rather than traditional value-added reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart customer service systems function as a service-attach opportunity where AI agent capacity subscriptions and ongoing compliance tooling expand faster than perpetual software licenses. Recurring revenue from algorithmic audit maintenance and consent-management platform integration outpaces upfront deployment fees.
For Market Incumbents: Entrench platform dominance by embedding Einstein AI layers deeper into existing CRM footprints across North American financial institutions. Acquire specialized voice biometric authentication vendors to neutralize emerging point-solution threats in telecommunications fraud prevention. Expand hybrid cloud certification programs to satisfy French and German banking regulator preferences for algorithmic audit trail preservation.
For New Entrants and Emerging Players: Build out standardized SaaS ticketing workflows targeting mid-market enterprises in Spain and Italy where custom AI deployments remain cost-prohibitive. The most penetrable whitespace sits in underpenetrated SME segments lacking resources for bespoke implementation. Pursue a channel partnership go-to-market angle bundling with regional system integrators already embedded in target accounts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists supplying NLP engines and sentiment analysis algorithms to platform integrators. Long-term viability hinges on defensible data moats and regulatory compliance tooling rather than generic chatbot architectures. Watch for inflection signals around EU AI Act enforcement actions that would accelerate replacement cycles for non-compliant legacy systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies multimodal inference engines across chat, voice, and email channels for banking clients. |
| Regulatory Compliance Tooling | Builds algorithmic audit trail capabilities satisfying EU AI Act risk-classification mandates. |
| Geographic Expansion | Captures underpenetrated mid-market opportunities in Southern European SME segments. |
| Strategic Partnership | Bundles AI capacity with legacy CRM integration to reduce procurement friction. |
| Acquisition of Specialist Firm | Consolidates voice biometric authentication capabilities for telecommunications fraud prevention. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with contact center operations directors, AI platform engineers, regulatory compliance officers, and enterprise procurement leads at North American financial institutions and European banking groups. Secondary validation drew from SEC filings of cloud infrastructure providers, EU AI Act implementation guidance documents, TRAI regulatory circulars, and hyperscaler capex disclosures. Bottom-up deployment volume estimates were triangulated against top-down market sizing derived from vendor revenue disclosures and channel partner surveys.
Calibration across the analysis window employed a segmented growth model disaggregating by technology modality, deployment architecture, end-user industry vertical, and regional regulatory cluster. CAGRs were derived from fitting logistic adoption curves to historical penetration data and adjusting for regulatory mandate timing. Forecast inputs included GPU compute cost trajectories, EU AI Act compliance deadline schedules, and cloud migration velocity indicators from enterprise IT spending surveys.
Sensitivities concentrate around semiconductor supply constraints affecting training costs and EU AI Act enforcement intensity altering upgrade cycle timing. Forecasts reflect documented assumptions regarding cloud adoption rates and regulatory implementation schedules. Material shifts in US-China technology trade restrictions or ECB data localization guidance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Global Saas Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Europe Cloud CRM Market
Customer Relationship Management (CRM)
Global Customer Experience Management Software Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market