
 Spending in Digital Customer Experience and Engagement Solutions Market | 2026-2036
Spending in Digital Customer Experience and Engagement Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Spending in Digital Customer Experience and Engagement Solutions Market Outlook
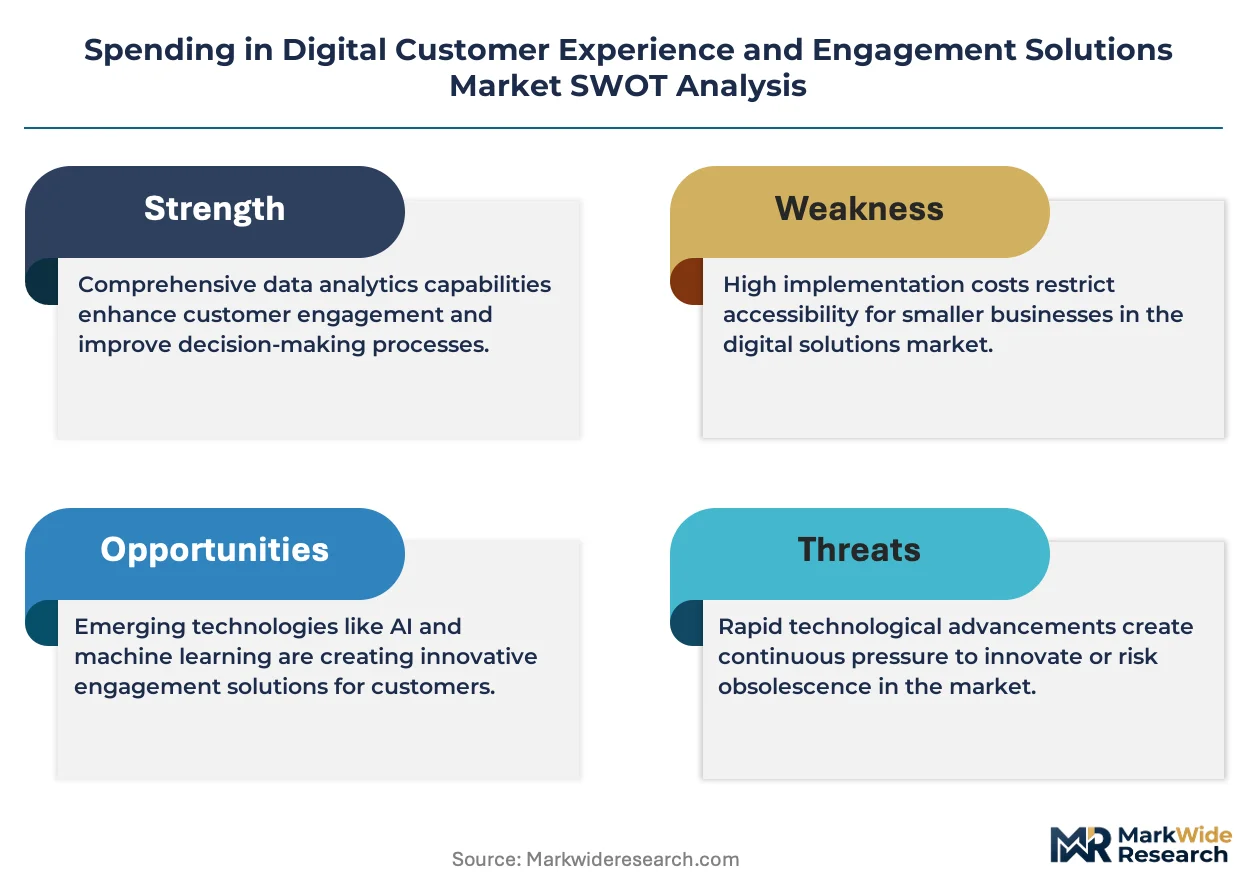
Subscription-based SaaS financing is narrowing the competitive field for mid-tier enterprises seeking enterprise-grade customer engagement capabilities. Salesforce leverages its native cloud architecture to sustain recurring revenue density across banking and retail verticals. IBM Corporation anchors hybrid deployment credibility through its Red Hat integration and on-premises legacy modernization. Adobe differentiates via creative-asset-to-personalization workflow continuity, occupying a defensible margin pool in content-driven engagement.
Spending in digital customer experience and engagement solutions encompasses software, platforms, and services that orchestrate real-time interaction management across multiple touchpoints, typically integrating natural language processing engines with sub-100-millisecond response latency for live customer interactions. The primary commercial purpose is to reduce churn cost and increase lifetime value by predicting intent signals from behavioral data streams. Cloud-based and SaaS deployment models are capturing the fastest expansion as IT departments trade capital expenditure for operational flexibility, while on-premises installations retain share in European banking where data residency requirements persist. Personalization engines and analytics tools concentrate margin pools because they require proprietary algorithmic development and deep client data integration that resists commoditization.
The EU AI Act and GDPR framework in Europe, alongside HIPAA in the United States, are mandating algorithmic transparency and consent audit trails that reshape vendor product roadmaps and procurement criteria. The Federal Trade Commission has intensified scrutiny of dark-pattern design in digital interfaces, forcing engagement platforms to embed ethical interaction guardrails. Stakeholders must weigh compliance architecture against speed-to-market as regulatory fragmentation across jurisdictions becomes a permanent cost of competing in customer experience technology.
Market Dynamics
Financial services firms are accelerating their migration toward explainable AI personalization engines as the EU AI Act and GDPR compliance deadlines reshape procurement criteria across European banking infrastructure.
Growth Catalysts
- Real-time data infrastructure:Enterprise cloud migration in the United States is unlocking sub-100-millisecond response capabilities for live customer interactions, compressing churn cost recovery timelines.
- EU AI Act compliance mandates:Algorithmic transparency requirements are forcing banks toward explainable personalization engines that embed consent audit trails by design.
- Natural language processing integration:Behavioral data stream analysis is enabling intent prediction models that anticipate customer needs before explicit query submission.
Market Restraints
- Data residency requirements:European banking regulations mandate on-premises installations that resist full cloud migration, fragmenting vendor deployment architectures.
- Algorithmic development costs:Proprietary personalization engines require sustained R&D investment that mid-tier enterprises cannot sustain without subscription financing.
- Regulatory fragmentation:Divergent compliance frameworks across the FTC's dark-pattern scrutiny and HIPAA consent requirements multiply architectural complexity.
Strategic Opportunities
- Hybrid deployment models:Red Hat-integrated architectures are capturing European banking demand for legacy modernization without full cloud surrender.
- Creative-asset-to-personalization workflows:Content-driven engagement platforms are opening defensible margin pools in retail verticals where visual merchandising dominates.
- Ethical interaction guardrails:FTC-mandated design constraints are creating first-mover advantage for vendors embedding compliance-by-construction.
Industry Challenges
- Explainable AI engineering talent:The intersection of machine learning expertise and regulatory interpretation is concentrating in a narrow labor pool.
- Legacy system integration friction:Mainframe-era customer data architectures resist real-time API connectivity without expensive middleware layers.
- Cross-jurisdiction compliance timelines:Simultaneous GDPR, EU AI Act, and HIPAA audit trails require parallel certification tracks that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spending in Digital Customer Experience and Engagement Solutions Market |
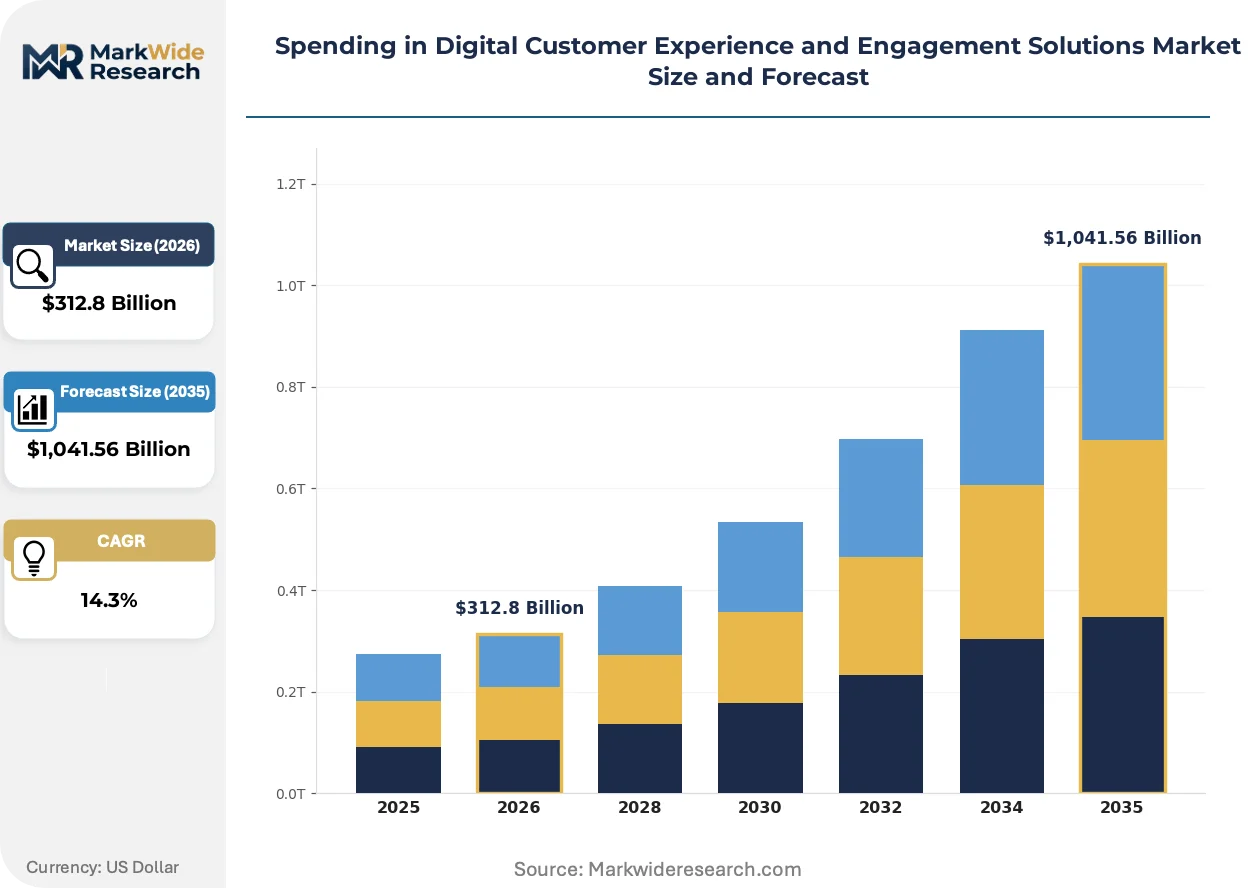
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $1,041.56 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Chatbots, CRM Software, Personalization Engines, Analytics Tools Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retail, Banking, Telecommunications, Healthcare Customer Interaction Channel: Web, Mobile, Social Media, Email |
| Companies Covered | Accenture, Capgemini, Cognizant, IBM Corporation, Salesforce, Adobe, Oracle Corporation, SAP, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spending in Digital Customer Experience and Engagement Solutions Market Strategic Shifts
Customer engagement architecture is migrating from batch-processed segmentation toward continuous behavioral inference, compressing the window between signal detection and response execution.
Generative personalization engines are migrating from template-based content assembly toward dynamic creative generation that adapts messaging tone and visual assets to individual interaction histories. Retail banking divisions are piloting these systems for wealth management client onboarding, reducing creative production cycles from weeks to hours. The structural compression of content supply chains is migrating from agency-dependent workflows toward in-house algorithmic production.
The EU AI Act's risk-based classification system is mandating human-in-the-loop oversight for high-stakes financial recommendations, forcing vendors to rebuild inference pipelines with interruptible decision points. Credit underwriting and investment advisory modules face the strictest compliance burdens, requiring explainability documentation that traces each output to specific input features. European banks are responding by segmenting their AI estates into auditable and non-auditable tiers, with procurement teams disqualifying vendors lacking pre-built transparency tooling.
Enterprise buyers are consolidating vendor relationships around platforms offering unified customer data infrastructure rather than point solutions for individual channels. Procurement teams in United States retail and banking verticals are prioritizing vendors with native identity resolution across web, mobile, and contact center touchpoints. This consolidation pattern is most visible in mid-market enterprises that previously stitched together best-of-breed components but now face integration cost overruns.
Spending in Digital Customer Experience and Engagement Solutions Market Segmentation
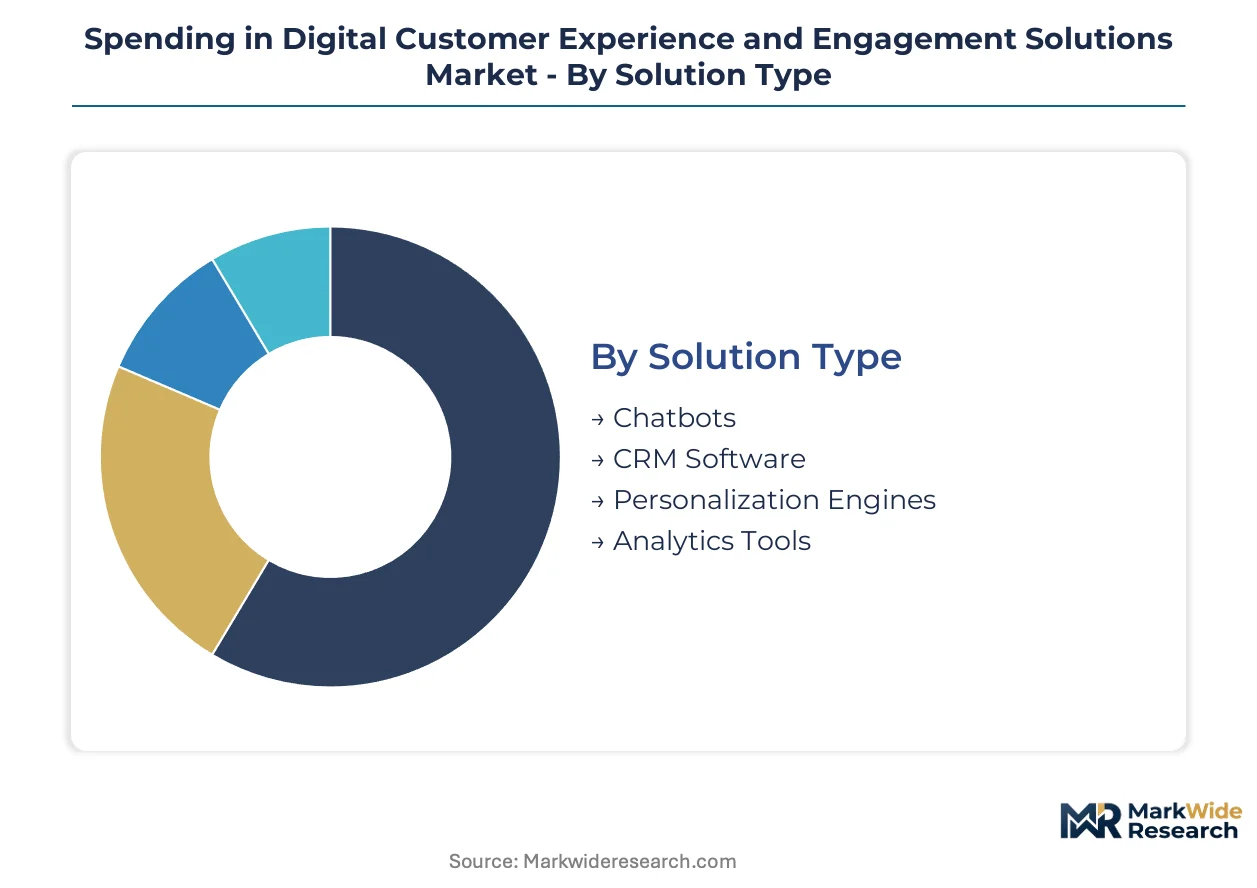
Solution architecture in digital customer experience and engagement solutions fragments across technical capability, infrastructure preference, and interaction modality. Procurement teams evaluate segments based on integration complexity, regulatory compliance burden, and lifetime value impact rather than standalone feature comparison.
Solution Type:
After-sales service intensity varies sharply across solution categories, with personalization engines demanding continuous algorithmic tuning and analytics tools requiring ongoing data pipeline maintenance.
- Personalization Engines:These systems orchestrate real-time behavioral inference using proprietary machine learning models that adapt messaging and offers to individual interaction histories. Banking procurement teams in the United States concentrate spending here as churn cost reduction justifies premium pricing for explainable AI architectures.
- Analytics Tools:Platforms aggregating cross-channel behavioral data streams into predictive intent signals, typically requiring deep data warehouse integration. European retail divisions prioritize these for consent audit trail compliance under GDPR and the EU AI Act.
- CRM Software:Customer relationship management systems with embedded workflow automation and sales pipeline visibility.
- Chatbots:Natural language processing interfaces for automated query resolution with sub-100-millisecond response latency requirements.
By volume, CRM Software leads due to enterprise-wide deployment mandates. By growth pace, Personalization Engines are climbing the fastest as explainable AI procurement accelerates.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises installations from operational-expenditure-focused cloud alternatives, with hybrid architectures capturing mid-market enterprises seeking regulatory flexibility without full legacy abandonment.
- Cloud-Based:Fully managed infrastructure with elastic compute scaling and vendor-operated security patching. United States retail and banking verticals dominate procurement as real-time data infrastructure investments compress churn recovery timelines.
- Hybrid:Architectures combining on-premises data residency with cloud-based processing layers, typically via container orchestration platforms. European banking demand concentrates here as GDPR data localization requirements persist alongside cloud capability requirements.
- SaaS:Subscription-licensed software with vendor-managed updates and multi-tenant infrastructure sharing.
- On-Premises:Self-managed installations with full operational control over hardware, networking, and security patching cycles.
By volume, Cloud-Based deployments lead. By growth pace, Hybrid architectures are gaining share fastest as regulatory fragmentation multiplies.
End User:
Application intensity diverges across verticals, with financial services demanding algorithmic explainability and healthcare prioritizing consent audit granularity.
- Banking:Institutions deploying explainable personalization engines for wealth management client onboarding and credit underwriting decision support. EU AI Act compliance deadlines are reshaping procurement criteria toward auditable AI tiers with human-in-the-loop oversight.
- Healthcare:Providers integrating HIPAA-compliant engagement platforms with electronic health record systems for appointment scheduling and care continuity. United States hospital systems concentrate spending on consent management architectures with granular audit trails.
- Retail:Merchants deploying creative-asset-to-personalization workflows for visual merchandising and dynamic pricing.
- Telecommunications:Carriers managing subscriber lifecycle across multiple touchpoints with churn prediction models.
By volume, Retail leads. By growth pace, Banking is expanding most quickly as regulatory mandates concentrate procurement.
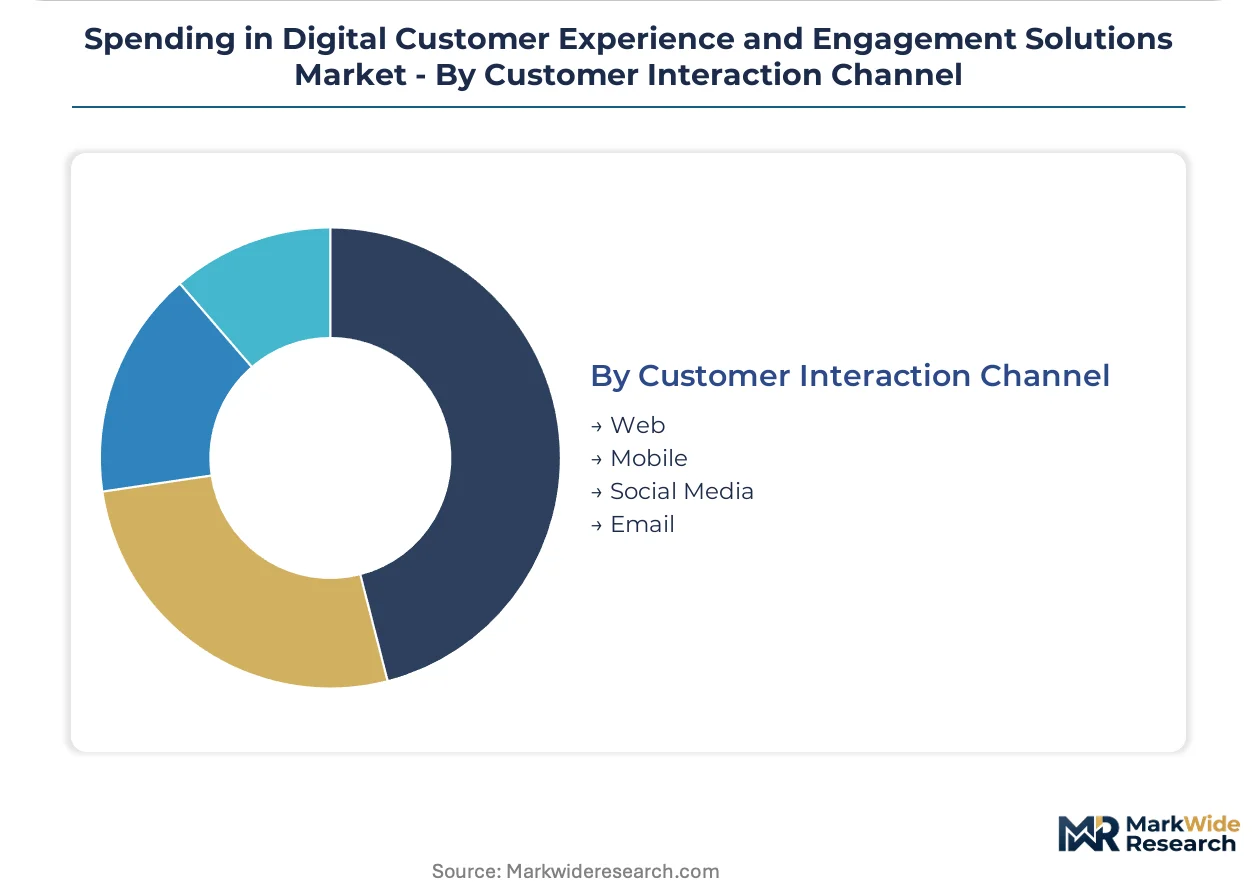
Customer Interaction Channel:
Channel maturity stratifies by data capture richness, with mobile applications offering the deepest behavioral signal density and email retaining cost efficiency for broadcast communications.
- Mobile:Native applications with push notification capabilities, biometric authentication, and precise geolocation triggering. United States retail banking divisions prioritize mobile-first architectures as primary account access shifts from web to handheld devices.
- Web:Browser-based experiences with cookie-based identity resolution and real-time personalization injection. European e-commerce operators concentrate investment here as FTC dark-pattern scrutiny forces ethical interaction guardrails into design systems.
- Social Media:Platform-embedded messaging and advertising integrations with third-party audience targeting.
- Email:Direct communication channel with template-based personalization and deliverability optimization.
By volume, Web leads. By growth pace, Mobile is climbing the fastest as real-time engagement expectations intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade in digital customer experience solutions flows predominantly from US-based SaaS exporters toward European importers navigating regulatory complexity. Capital expenditure patterns diverge sharply between cloud-native American enterprises and compliance-constrained European banking infrastructure. Procurement budgets concentrate where real-time data infrastructure investments intersect with strict algorithmic transparency mandates.
United States
Enterprise cloud migration and sub-100-millisecond response capability investments dominate procurement budgets across retail banking divisions. FTC scrutiny of dark-pattern design forces engagement platforms to embed ethical interaction guardrails into product roadmaps. New York and San Francisco metropolitan clusters concentrate vendor headquarters and financial services technology procurement decisions.
Germany
Data residency requirements and legacy mainframe architectures sustain hybrid deployment demand across Frankfurt and Munich banking centers. BaFin supervision and EU AI Act implementation timelines reshape vendor selection criteria toward explainable personalization engines. Baden-Württemberg automotive manufacturers are piloting customer engagement platforms for connected vehicle service ecosystems.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for vendors serving both UK and EU financial institutions. FCA consumer duty rules intensify scrutiny of algorithmic decision-making in wealth management client onboarding. London's fintech cluster drives demand for unified customer data infrastructure spanning traditional banking and neobank competitors.
Japan
Financial Services Agency guidelines on AI governance push domestic banks toward auditable engagement platforms with human-in-the-loop oversight. METI digital transformation subsidies accelerate cloud migration among regional banking associations resisting full legacy abandonment. Tokyo and Osaka metropolitan areas concentrate both vendor delivery centers and enterprise procurement headquarters.
India
RBI guidelines on digital lending and customer protection mandate consent audit granularity for engagement platforms serving non-banking financial companies. IT services export hubs in Bengaluru and Hyderabad are transitioning from implementation partners to product development centers for global SaaS vendors. Domestic retail banking expansion drives demand for multilingual natural language processing capabilities.
Spending in Digital Customer Experience and Engagement Solutions Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in analytics and personalization modules. Market structure tilts toward consolidation as enterprise buyers favor unified customer data infrastructure over point solutions. Three archetypes dominate: cloud-native SaaS platforms with native identity resolution, hybrid deployment specialists leveraging container orchestration, and creative-asset workflow vendors occupying content-driven verticals. Competitive moves concentrate on strategic partnerships for legacy modernization and portfolio diversification into explainable AI tooling.
Within the cloud-native platform tier, Salesforce and Adobe exemplify divergent margin strategies—Salesforce anchoring recurring revenue density through banking and retail verticals, Adobe occupying defensible creative-to-personalization workflow continuity. IBM Corporation represents the hybrid deployment archetype, with Red Hat-integrated architectures capturing European banking demand for data residency compliance without full cloud surrender. These three entities illustrate how vendor positioning fragments across deployment model preference and vertical specialization rather than converging on uniform platform dominance.
| Leading Market Players |
|---|
| Accenture |
| Capgemini |
| Cognizant |
| IBM Corporation |
| Salesforce |
| Adobe |
| Oracle Corporation |
| SAP |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific fiber-optic cable capacity costs directly shape how cloud-native SaaS vendors price subscription tiers, with latency-sensitive financial services buyers absorbing premium markups while mid-tier enterprises face compressed margins from infrastructure concentration in United States hyperscaler regions.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, where explainable AI certification tiers and real-time response latency guarantees drive differentiation. Subscription financing concentrates price sensitivity among mid-tier enterprises unable to sustain proprietary algorithmic development costs. Pricing pressure stems from hyperscaler infrastructure commoditization eroding margin pools in basic analytics tiers. Healthcare providers exhibit least price sensitivity due to HIPAA compliance mandates requiring granular consent audit architectures.
Supply Chain Analysis
Export control restrictions on advanced GPU clusters limit flows from United States hyperscalers toward Chinese and Russian data center operators, fragmenting global deployment architectures. Cloud compute capacity concentrates in United States, Ireland, and Singapore regions. Proprietary personalization engines draw from specialized ML engineering labor pools, open-source NLP frameworks, and enterprise data pipeline middleware. Single-source vulnerability sits with NVIDIA accelerator supply for training workloads. Distribution runs through direct enterprise sales with embedded professional services for legacy integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from generative AI-native entrants offering dynamic creative generation without legacy infrastructure drag, forcing defensive architecture investments.
For Market Incumbents: Pre-empt generative AI-native displacement by acquiring specialist firms with dynamic creative generation capabilities and embedding compliance-by-construction into product roadmaps before EU AI Act enforcement hardens procurement criteria. Vertical integration into proprietary training data pipelines secures algorithmic differentiation against open-source model commoditization.
For New Entrants and Emerging Players: Mid-market European banking divisions represent the most penetrable entry point, where GDPR data residency requirements and legacy mainframe friction create incumbent blind spots. Target hybrid deployment architectures with container orchestration expertise as the go-to-market angle, positioning against cloud-native vendors unable to satisfy BaFin supervision timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy system integrators with captive financial services client relationships and dormant explainable AI development programs. Long-term viability centers on vendors capturing recurring revenue density through embedded workflow continuity rather than point solution displacement. Watch for FTC dark-pattern enforcement actions as inflection indicator for ethical interaction guardrail demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Captures explainable AI engineering talent concentrated in narrow labor pools. |
| Platform Integration | Unifies customer data infrastructure across web, mobile, and contact center touchpoints. |
| Strategic Partnership | Secures Red Hat-integrated hybrid deployment credibility for European banking procurement. |
| Geographic Expansion | Establishes Frankfurt and Munich delivery centers for BaFin-supervised client onboarding. |
| Product Launch | Introduces human-in-the-loop oversight modules for EU AI Act high-risk classification compliance. |
Study Parameters
A standing panel of CTOs, IT procurement officers, platform engineers, and integration specialists provided ongoing calibration across primary fieldwork, supplemented by SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and EU regulatory submission databases. Bottom-up deployment model sizing triangulated against top-down vertical spending analysis.
Scenario-bracketing framed projections across the analysis window, modeling segmentation dimensions including deployment model, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derived from historical spending trajectory analysis combined with procurement intention surveys and vendor pipeline visibility. Explainable AI compliance timeline acceleration and real-time infrastructure investment cycles served as key forecast inputs.
Practitioners should monitor EU AI Act enforcement granularity and FTC dark-pattern penalty severity for early signals of procurement criteria hardening. Forecasts reflect assumptions about regulatory implementation timelines and hyperscaler capacity expansion. Material shifts in export control restrictions on GPU clusters or abrupt GDPR interpretation changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Customer Communication Management Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market