
 Cupcake Tray Machines Market | 2026-2036
Cupcake Tray Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Cupcake Tray Machines Market Outlook
The gap between premium stainless-steel systems and commodity-grade aluminum units is expanding as bakeries face divergent margin pressures. ElastoTech leverages its polymer-coating expertise to differentiate on durability in high-wash environments. Demmler GmbH anchors German engineering standards across European distribution channels. ACS Coating Systems GmbH specializes in surface treatment technologies that extend equipment lifecycles in corrosive production settings.
Cupcake tray machines are automated or semi-automated forming, depositing, and conveying systems designed to shape batter into uniform cavities at throughput rates typically ranging from 1,000 to 15,000 units per hour, with primary application in commercial food production facilities seeking labor reduction and portion consistency. Automatic systems dominate installed base value due to integration with continuous baking lines, while semi-automatic units capture fastest growth among mid-tier bakeries balancing capital constraints against throughput targets. Electric technology leads technology segmentation for precision motor control, though pneumatic systems retain share in facilities with existing compressed-air infrastructure.
The FDA governs food-contact surface materials under 21 CFR 177.1520, compelling manufacturers to validate polymer and coating compositions for thermal stability and migration limits. The EU Machinery Directive 2006/42/EC mandates CE conformity for safety interlocks and emergency stop systems on equipment imported into member states. Stakeholders must monitor evolving EFSA opinions on recycled content eligibility for food-contact applications, as these will reshape material specifications and supplier qualification protocols without explicit regulatory deadlines.
Market Dynamics
Commercial bakeries across Germany, the United States, and Japan are accelerating replacement cycles for pneumatic tray handling systems as electric servo motors achieve price parity and superior washdown durability. This technology substitution is compressing the installed base renewal timeline from seven years toward four-year cycles.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for safety interlocks and emergency stop systems are forcing bakeries to upgrade legacy equipment, creating replacement demand across member states.
- Electric motor precision control:Servo-driven depositing heads enable ±2% batter weight consistency, reducing ingredient waste and quality rejects in high-volume production.
- Munich-Hamburg industrial baking cluster:Concentrated facility investment in southern and northern Germany drives regional equipment procurement at scale.
Market Restraints
- Stainless steel input cost volatility:Grade 304 and 316 sheet metal price swings compress margins for equipment fabricators, forcing pass-through clauses or material substitution toward coated aluminum.
- Pneumatic infrastructure lock-in:Bakeries with sunk compressed-air investments face high switching costs to electric systems, slowing technology migration in mature facilities.
- FDA migration testing timelines:21 CFR 177.1520 validation protocols for new polymer coatings extend product launch cycles by 8-14 months.
Strategic Opportunities
- India FSSAI modernization:The Food Safety and Standards Authority of India's expanding enforcement capacity is driving organized sector bakeries toward automated portioning equipment.
- Polymer-metal hybrid surfaces:ElastoTech-style coating technologies applied to aluminum substrates bridge the durability gap against full stainless systems at 40% lower material cost.
- Direct-to-bakery digital distribution:Equipment manufacturers are bypassing regional distributors to capture margin and reduce lead times through configuration-to-order platforms.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of integrated servo-pneumatic hybrid systems requires cross-trained personnel that vocational pipelines in Germany and the United States currently undersupply.
- Legacy PLC integration complexity:Retrofitting new tray machines into existing Allen-Bradley or Siemens baking line controllers demands custom middleware development, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cupcake Tray Machines Market |
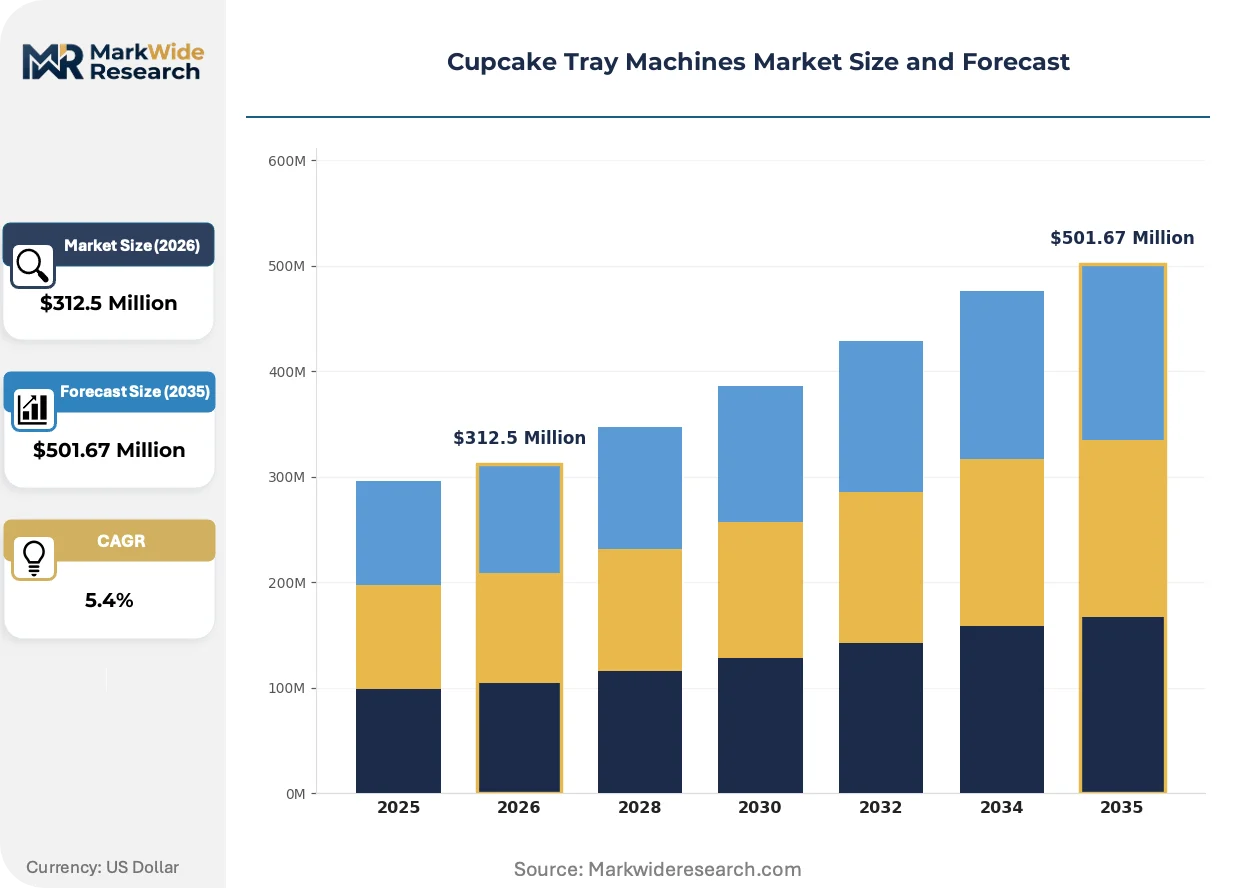
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Customizable Technology: Electric, Pneumatic, Hydraulic, Mechanical End User: Bakeries, Restaurants, Catering Services, Retail Outlets Capacity: Small Scale, Medium Scale, Large Scale, Commercial |
| Companies Covered | ElastoTech, Demmler GmbH, ACS Coating Systems GmbH, Modul-bake KFT, Sipaldis SA, ENO SAS, Elite Restaurant Equipment, Vollrath Foodservice, B.E Atlas Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cupcake Tray Machines Market Strategic Shifts
Surface engineering and control architecture advances are redefining equipment lifecycle economics. Manufacturers are prioritizing corrosion-resistant coatings and modular drive systems that extend washdown durability while simplifying field upgrades.
Polymer-ceramic composite coatings for aluminum tray contact surfaces are converging with high-pressure washdown protocols common in commercial bakeries. German and Dutch facilities with three-shift operations are adopting these surfaces to reduce pitting corrosion and extend cavity dimensional stability. The technology is converging with predictive maintenance platforms that flag coating degradation before quality deviation occurs.
EFSA opinions on recycled polymer eligibility for food-contact applications are reshaping material qualification protocols. Equipment manufacturers must now document chain-of-custody for regrind content and validate thermal stability under baking temperatures. European importers are responding by dual-sourcing virgin and certified recycled feedstock to maintain CE compliance flexibility.
Mid-tier bakeries are unbundling after-sales service contracts from equipment purchases, opting for third-party maintenance or in-house technician training. This procurement pattern disrupts traditional OEM recurring revenue models and shifts margin capture toward spare parts and remote diagnostics subscriptions. The behavior is most pronounced in the United States, where independent service organizations have consolidated technical capabilities.
Cupcake Tray Machines Market Segmentation
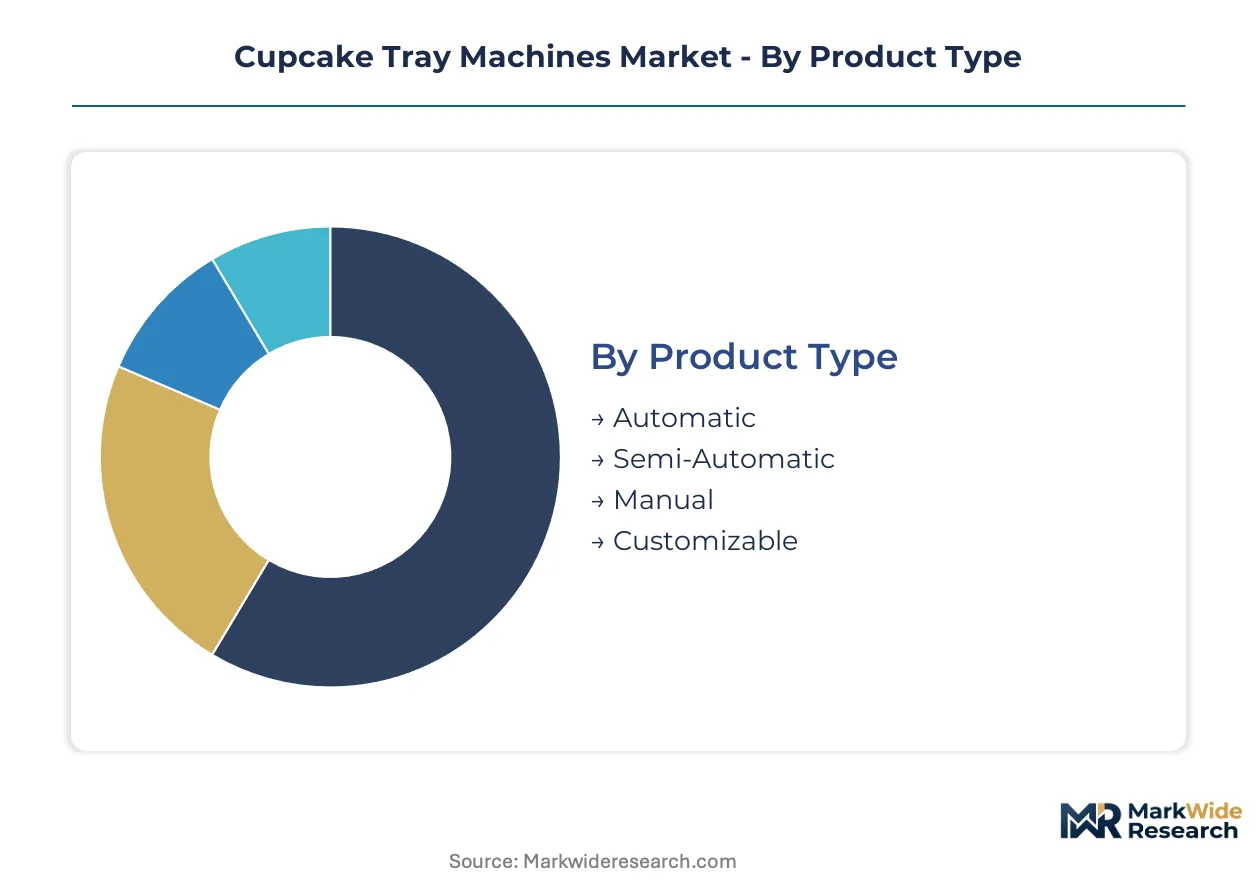
Segmentation in the cupcake tray machines market reflects divergent compliance burdens, capital intensities, and operational scale requirements across commercial baking operations. Equipment purchasers prioritize certification alignment, throughput targets, and integration complexity when selecting from available configurations.
Product Type:
CE marking under the EU Machinery Directive and FDA food-contact validation requirements apply differentially across automation tiers, with full automatic systems bearing the heaviest documentation load.
- Automatic:Continuous-forming systems integrate servo-driven depositing heads with baking line PLCs for throughput rates exceeding 10,000 units per hour. German industrial bakeries around Munich and Hamburg dominate procurement as these facilities replace pneumatic legacy systems to meet EU safety interlock mandates.
- Semi-Automatic:Batch-fed units with operator-assisted loading balance capital constraints against labor reduction, achieving 3,000-8,000 units per hour with lower compliance documentation. Mid-tier bakeries in the United States favor this tier for flexibility across product changeovers.
- Manual:Hand-cranked or simple lever-actuated forming tools for artisan operations with minimal regulatory exposure.
- Customizable:Modular architectures permitting cavity reconfiguration and retrofit upgrades for specialty product lines.
Automatic systems sit at the top of the volume ranking, with semi-automatic climbing the fastest as mid-tier bakeries defer full line integration.
Technology:
Cost stratification across drive technologies reflects infrastructure sunk costs, precision requirements, and washdown durability specifications in three-shift production environments.
- Electric:Servo motor architectures deliver ±2% batter weight consistency through precision motor control. Japanese commercial bakeries are accelerating adoption as electric systems achieve price parity with pneumatic alternatives and eliminate compressor maintenance overhead.
- Pneumatic:Compressed-air actuation retains installed base share where existing infrastructure reduces switching costs, though seven-year replacement cycles are compressing toward four years.
- Hydraulic:High-force forming for dense batter applications and industrial-scale throughput.
- Mechanical:Cam-driven simplicity for low-maintenance operation in emerging market facilities with limited technical support access.
Electric technology commands the premium tier by margin, while pneumatic retains volume leadership in facilities with legacy air systems.
End User:
Customer type determines service contract structure, spare parts procurement patterns, and the feasibility of remote diagnostics integration.
- Bakeries:Commercial production facilities with continuous operation requirements and stringent FDA or EFSA food-contact compliance obligations.
- Restaurants:On-premise baking operations with intermittent use patterns and lower throughput demands.
- Catering Services:Event-driven volume spikes requiring rapid changeover capability and portable equipment configurations.
- Retail Outlets:In-store bakery departments balancing visual merchandising with production efficiency.
Bakeries generate the dominant revenue concentration, with catering services expanding most quickly as event-format dining rebounds.
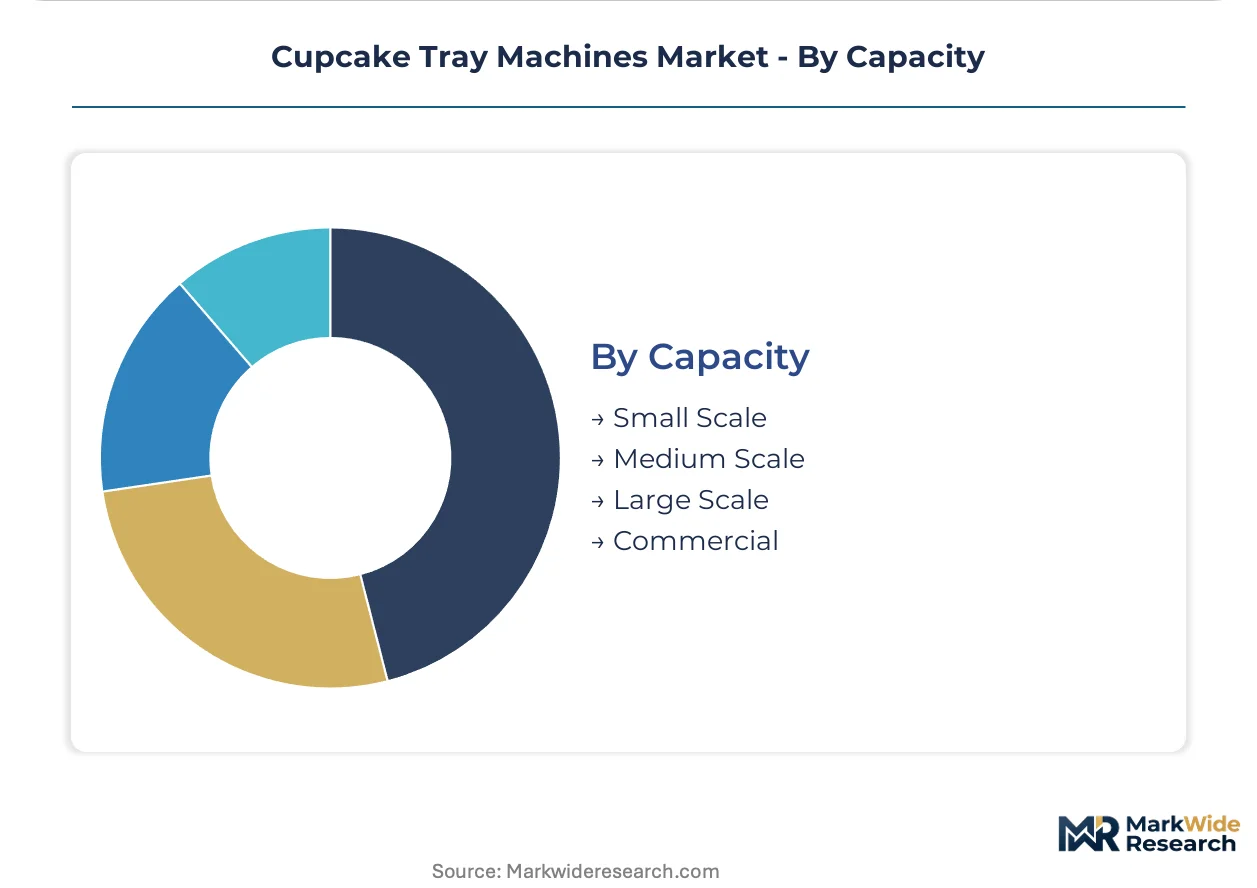
Capacity:
Scale tier selection correlates with facility footprint, labor availability, and the economics of ingredient waste reduction through portion precision.
- Large Scale:Integrated line systems serving national distribution networks with 24-hour production schedules.
- Commercial:Mid-volume configurations for regional bakery chains balancing throughput against equipment utilization rates.
- Medium Scale:Independent bakeries with localized distribution and seasonal demand fluctuation.
- Small Scale:Micro-bakeries and startup operations with limited capital and batch production requirements.
Commercial capacity anchors procurement value, with medium scale gaining share fastest among independent operators automating to offset labor scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces Japan in electric servo adoption for tray handling systems, while the United States concentrates semi-automatic procurement among mid-tier independent bakeries. Regulatory divergence across FDA, EU Machinery Directive, and FSSAI jurisdictions is reshaping supplier qualification protocols and equipment specification requirements.
Germany
Industrial bakeries around Munich and Hamburg are compressing replacement cycles from seven years toward four years as electric systems achieve price parity with pneumatic alternatives. CE marking under the EU Machinery Directive 2006/42/EC mandates upgraded safety interlocks and emergency stop systems on all new installations. The Bavaria-Lower Saxony corridor anchors European demand for high-throughput automatic systems serving continental distribution networks.
United States
Mid-tier bakeries favor semi-automatic configurations that balance capital constraints against labor reduction targets across product changeovers. FDA 21 CFR 177.1520 governs food-contact surface validation, extending polymer coating launch timelines by 8-14 months. The Midwest industrial baking belt spanning Illinois, Michigan, and Ohio drives replacement demand as facilities modernize legacy pneumatic infrastructure.
Japan
Commercial bakeries are accelerating electric servo adoption to eliminate compressor maintenance overhead and achieve ±2% batter weight consistency. METI industrial efficiency standards incentivize equipment upgrades through accelerated depreciation allowances. The Kanto region around Tokyo concentrates procurement for integrated continuous baking lines serving dense urban retail networks.
India
Organized sector bakeries are automating portioning equipment as FSSAI enforcement capacity expands and food safety compliance tightens. The Production Linked Incentive scheme for food processing machinery reduces effective capital costs for domestic equipment purchases. Maharashtra and Gujarat host the fastest-growing clusters of commercial bakery automation among regional chain operators.
China
Domestic equipment fabricators are capturing share from European imports through localized servo motor supply chains and competitive pricing on medium-scale configurations. GB standards for food machinery safety are converging with EU technical specifications for export-oriented facilities. The Yangtze River Delta baking equipment manufacturing hub around Shanghai supplies both domestic demand and Southeast Asian export markets.
Cupcake Tray Machines Market Competitive Environment
Top-tier vendors anchor premium stainless-steel and polymer-coated system supply, while mid-tier fabricators compete on configurable semi-automatic platforms and regional service density. The vendor base stratifies across German engineering specialists, Asian scale manufacturers, and North American distribution-focused players. Three archetypes dominate: surface engineering specialists extending equipment lifecycles, modular system integrators enabling rapid cavity reconfiguration, and coating technology providers bridging aluminum cost advantages with stainless durability. Competitive moves concentrate on geographic expansion through distributor partnerships and backward integration into servo motor and control system supply.
Among German engineering specialists, Demmler GmbH and ACS Coating Systems GmbH exemplify the surface-treatment archetype, occupying positions that emphasize coating durability in corrosive washdown environments. ElastoTech represents the polymer-metal hybrid approach, anchoring a tier that applies elastomer expertise to aluminum substrates at material cost advantages against full stainless systems. These three entities sit within a competitive structure where technical validation credentials and CE marking compliance separate premium positioning from commodity alternatives.
| Leading Market Players |
|---|
| ElastoTech |
| Demmler GmbH |
| ACS Coating Systems GmbH |
| Modul-bake KFT |
| Sipaldis SA |
| ENO SAS |
| Elite Restaurant Equipment |
| Vollrath Foodservice |
| B.E Atlas Company |
| Others |
Value Chain & Pricing Dynamics
EU Machinery Directive compliance mandates for CE-marked safety interlocks are forcing commercial bakeries toward premium electric servo systems, compelling equipment fabricators to absorb Grade 304 stainless steel volatility or shift toward polymer-coated aluminum substrates. This specification drift is compressing margins in the commodity tier while concentrating pricing power with surface engineering specialists.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for medium-scale electric configurations. Three-tier pricing structure across premium, standard, and economy levels separates full stainless-steel systems with FDA-validated coatings from commodity aluminum units. Price differentiation hinges on CE certification tier and after-sales service bundling. Cost compression in the semi-automatic tier is intensifying because mid-tier bakeries unbundle maintenance contracts. Independent bakeries in the United States exhibit highest price sensitivity; German industrial clusters around Munich show lowest.
Supply Chain Analysis
Direct-to-bakery digital channels handle hyperscale buyer demand from national distribution networks, bypassing regional distributors to capture margin and reduce lead times. Supply concentrates in Germany, China, and Japan for servo motor and control system production. Raw material flows draw from Taiwanese semiconductor foundries for PLC components, German steel mills for Grade 304/316 sheet metal, and Chinese aluminum smelters for substrate materials. Single-source vulnerability in servo motor supply creates exposure to logistics chokepoints through the Suez corridor. Distribution runs through OEM-direct platforms for large-scale buyers and regional equipment dealers for mid-tier independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Commercial bakeries are consolidating procurement around equipment with validated polymer-ceramic coatings and predictive maintenance integration, privileging durability over upfront capital cost.
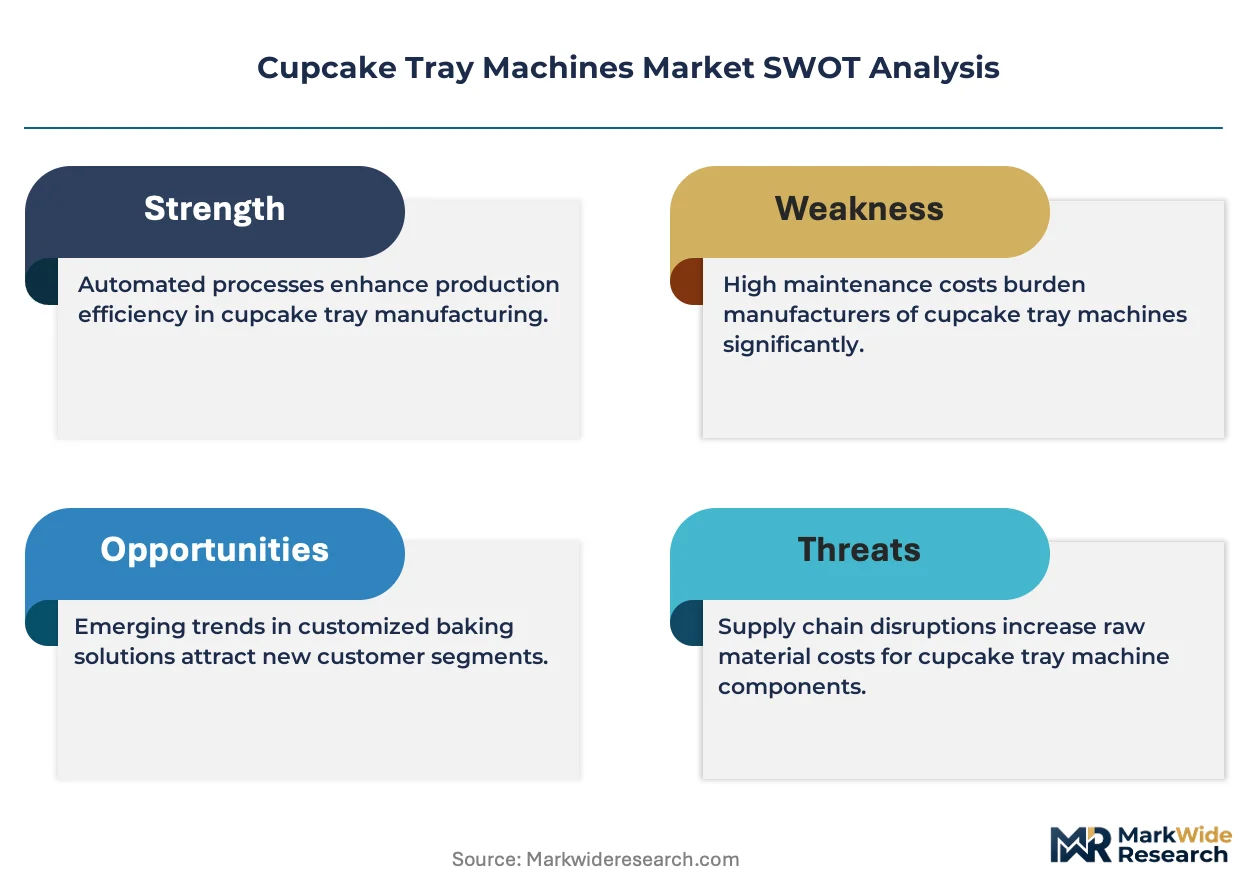
For Market Incumbents: Extend coating technology roadmaps to bridge stainless durability at aluminum cost points, defending against Chinese fabricators with localized servo supply chains. Anchor position through backward integration into polymer formulation and captive CE marking validation capacity. Deepen technical training partnerships with German vocational institutes to offset mechatronics technician scarcity. For New Entrants and Emerging Players: Servo motor price parity creates entry opportunity in India's FSSAI-mandated modernization wave. Target medium-scale independent bakeries in Maharashtra and Gujarat with configurable semi-automatic platforms and third-party financing. Go-to-market through direct digital configuration platforms, bypassing distributor margin capture. For Investors and Strategic Acquirers: Asymmetric upside sits with surface engineering specialists holding validated coating portfolios and dual-source virgin-recycled feedstock flexibility. Five-to-ten year viability favors vendors with CE marking competence and predictive maintenance software integration. Signal to monitor: EFSA opinions on recycled polymer eligibility reshaping material qualification protocols and supplier consolidation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-Metal Hybrid Surface Development | ElastoTech-style coatings bridge durability gaps at 40% lower material cost than full stainless systems. |
| Direct-to-Bakery Digital Distribution | Configuration-to-order platforms capture distributor margin and compress lead times for national bakery chains. |
| Servo Motor Backward Integration | In-house production of precision drive systems insulates margin from Taiwanese semiconductor supply volatility. |
| Predictive Maintenance Platform Launch | Coating degradation monitoring flags field failures before quality deviation, enabling subscription revenue streams. |
| CE Marking Validation Investment | Documented safety interlock compliance accelerates EU market access and defends premium positioning against imports. |
Study Parameters
Coverage spans Germany, the United States, Japan, India, and China, with primary inputs from each market gathered through structured interviews with plant engineers at commercial bakeries, OEM procurement teams, aftermarket service heads, and coating technology R&D directors. Secondary validation draws from EU Machinery Directive implementation guidance, FDA 21 CFR 177.1520 food-contact material databases, EFSA scientific opinions, METI industrial efficiency standards, and FSSAI enforcement bulletins. Bottom-up equipment shipment data triangulates against top-down baking industry capacity estimates.
Granularity-level modeling disaggregates volume and value across automation tier, drive technology, end-user type, and capacity scale, with additional dimensioning for regional regulatory cluster and coating material specification. CAGRs derive from equipment replacement cycle compression trends and installed base penetration rates. Industry-specific inputs include pneumatic-to-electric substitution velocity, polymer coating validation timelines, and three-shift operational intensity by geography.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA recycled content rulings, stainless steel price volatility, and mechatronics technician supply constraints. Forecasts reflect documented assumptions on replacement cycle compression and technology substitution elasticities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food & Beverages
Global Mineral Fortification Market
Food & Beverages
Baking Ingredients Market
Food & Beverages
Venezuela Fruits and Vegetable Market
Food & Beverages
Synthetic Food Colors Market
Food & Beverages
United Kingdom Gelatin Market
Food & Beverages
Fruit Ripening Agents Market
Food & Beverages
Africa Dairy Protein Market
Food & Beverages
Horseradish Sauce Market
Food & Beverages
Dairy Stabilizer Market
Food & Beverages
Food Processor Market
Food & Beverages
RTD Bottled Cocktails Market
Food & Beverages
Natural Food Color Additives Market
Food & Beverages
GCC Bottled Water Market
Food & Beverages
Asia-Pacific Pasta and Noodles Market
Food & Beverages
Canned Sardines Market
Food & Beverages
Africa Plant Protein Ingredients Market