
 TV Mirror Market | 2026-2036
TV Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
TV Mirror Market Insights
Subscription-based leasing models for luxury bathroom fixtures is fragmenting the competitive landscape, allowing smaller design studios to compete alongside capital-intensive electronics manufacturers. Samsung Electronics leverages its display panel supply chain to control component costs across integrated mirror-television units. Seura specializes in custom frame finishes and embedded installation systems for high-end residential projects. Electric Mirror, Inc. anchors the hospitality channel through direct relationships with major hotel chains requiring bulk procurement of waterproof LED mirror displays.
A TV mirror combines a partially silvered dielectric mirror with a thin liquid-crystal or OLED panel, transmitting video content when powered while retaining reflective functionality when dormant, typically rated at IP44 or higher ingress protection for bathroom deployment. The hospitality end-user segment leads absolute volume as hotel renovation cycles standardize in-mirror entertainment across premium and mid-tier properties. Smart mirrors incorporating touchscreen interfaces and voice control represent the fastest-expanding feature category, though wall-mounted installation remains the dominant configuration due to structural compatibility with existing bathroom layouts.
The Federal Communications Commission regulates electromagnetic emissions from integrated wireless connectivity modules in TV mirrors sold in the United States, while the EU's Radio Equipment Directive governs Bluetooth and Wi-Fi functionality in European markets. The EU Ecodesign Directive increasingly shapes product development roadmaps by mandating standby power thresholds for always-connected display surfaces. Stakeholders must weigh certification costs against channel access when prioritizing regional product portfolios, as divergent efficiency and connectivity standards fragment the addressable market into jurisdiction-specific compliance clusters.
Market Dynamics
The hospitality renovation cycle in the United States and Western Europe is consolidating procurement power among hotel chains, compressing supplier margins while expanding volume commitments for waterproof mirror-television units.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power thresholds for always-connected displays are accelerating R&D investment in ultra-low-power dielectric mirror panels.
- Hospitality channel consolidation:Major hotel chains in Germany and France are standardizing in-mirror entertainment across premium and mid-tier property renovations.
- Thin-film OLED diffusion:Panel thickness reduction below 3mm enables frameless architectural integration previously impossible with legacy LCD substrates.
Market Restraints
- Input cost volatility:Indium tin oxide sputtering targets face supply concentration from Chinese rare earth processors, destabilizing transparent electrode pricing.
- Technical limitation:IP44 ingress protection ratings cap maximum display brightness in steam-saturated bathroom environments, constraining outdoor-adjacent applications.
- Regulatory friction:FCC electromagnetic emission testing for integrated Wi-Fi modules adds 8-12 weeks to US product launch timelines versus non-connected mirrors.
Strategic Opportunities
- Underpenetrated residential segment:German bathroom renovation rates exceed EU averages, yet mirror-television penetration in private homes remains below 4%.
- Voice control convergence:Integration of far-field microphone arrays with existing smart home ecosystems opens hospitality upsell channels.
- Subscription leasing models:Design studios in Milan and Copenhagen are piloting fixture-as-a-service contracts for luxury residential developments.
Industry Challenges
- Certification timeline compression:CE marking under the EU Radio Equipment Directive requires simultaneous electromagnetic and safety testing, extending validation cycles.
- Integration complexity:Retrofit installations in existing European hotel stock demand structural reinforcement for wall-mounted units above 32 inches diagonal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TV Mirror Market |
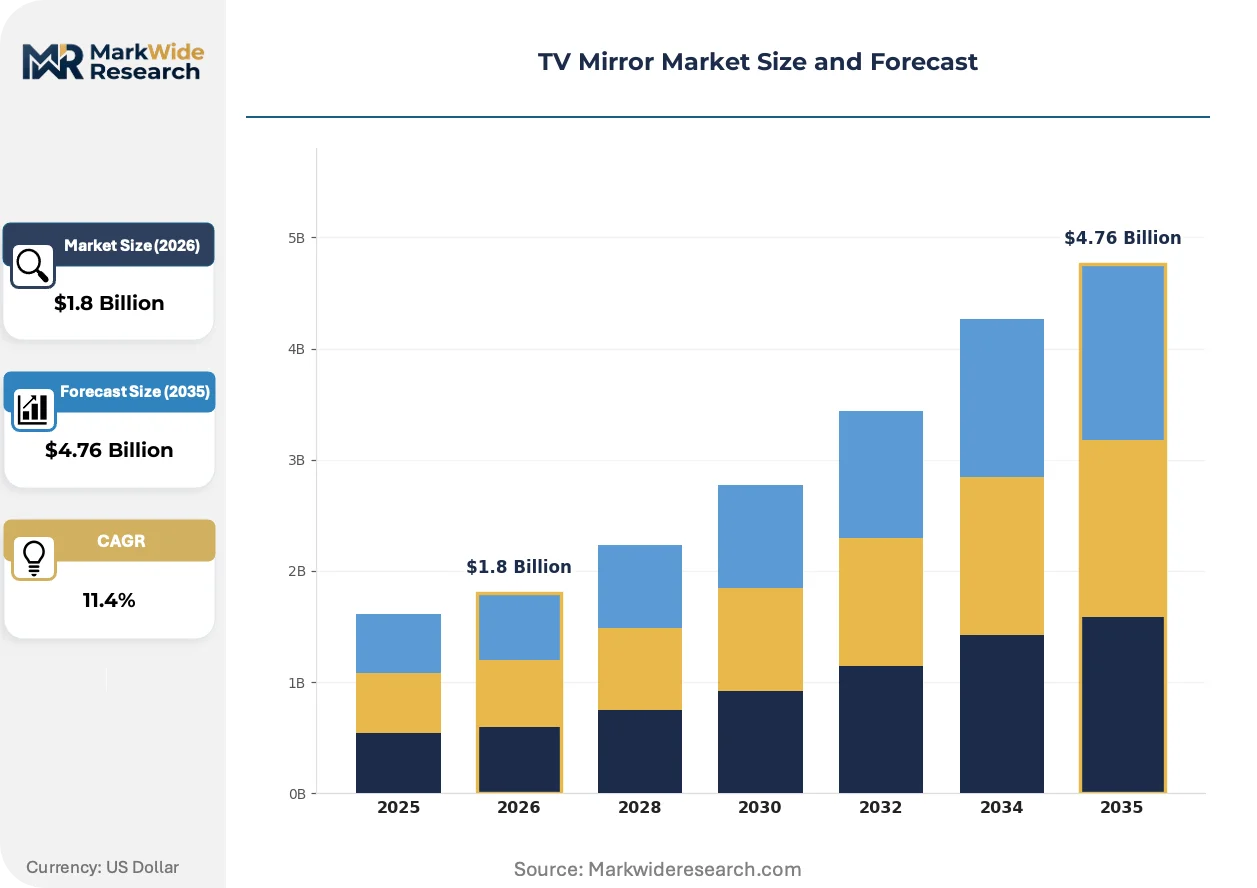
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Mirrors, LED Mirrors, Digital Mirrors, Custom Mirrors End User: Residential, Commercial, Hospitality, Healthcare Installation: Wall-Mounted, Freestanding, Embedded, Portable Feature: Touchscreen, Voice Control, Bluetooth Connectivity, Ambient Lighting |
| Companies Covered | Samsung Electronics, Seura, Electric Mirror, Inc., Ad Notam AG, Evervue, LG Electronics, Sony, Panasonic, MirrorMedia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TV Mirror Market Trends and Innovations
Dielectric mirror coatings and voice-interface modules are converging to redefine bathroom fixture architecture, shifting value capture from hardware margins toward embedded software and installation services.
Micro-lens array backlighting is rendering obsolete edge-lit LED configurations in mirror-television hybrids. Hospitality procurement teams in France and Germany are specifying full-array local dimming for premium property tiers. This technology is rendering obsolete the 8-10mm bezel standards that previously constrained mirror-to-display size ratios.
REACH substance restrictions on hexavalent chromium in mirror coatings are forcing electroplating process migrations across European manufacturing facilities. Industrial consequence includes 15-20% yield loss during qualification of trivalent chromium alternatives. German component suppliers are most affected, accelerating partnerships with Korean chemical deposition specialists.
Buyer consolidation among hotel ownership groups is compressing supplier negotiation cycles from annual to quarterly reviews. Direct procurement relationships are displacing traditional distributor networks in the United States hospitality channel. This pattern is most visible in Marriott and Hilton renovation programs across Texas and Florida properties.
TV Mirror Market Segmentation
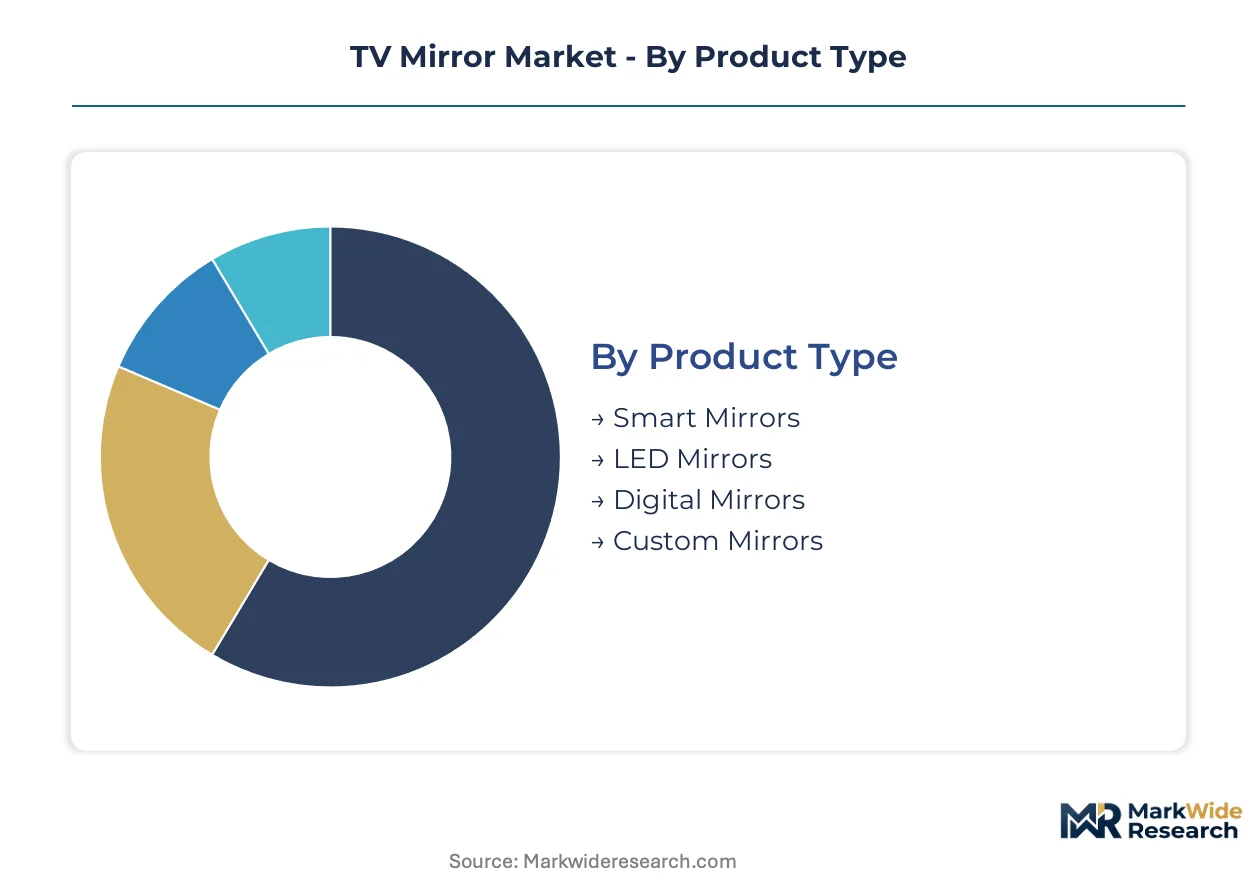
TV mirror segmentation reveals divergent technical requirements across hospitality renovation cycles and residential bathroom upgrades. Product architecture, installation constraints, and connectivity specifications fragment addressable demand into distinct procurement channels with incompatible vendor qualification criteria.
Product Type:
Mature dielectric mirror configurations coexist with emerging OLED-integrated formats, creating a bifurcated supply base serving legacy renovation and new construction respectively.
- Smart Mirrors:These units integrate partial silvering with embedded computing modules for streaming and voice interface, typically specified at IP44 ingress protection. Hospitality procurement teams in Germany and France are standardizing these across mid-tier property renovations to differentiate guest bathroom experiences.
- LED Mirrors:Edge-lit or full-array backlighting behind dielectric glass provides illumination without active video display. Residential demand concentrates in German bathroom renovations where premium fixture upgrades outpace EU averages, though penetration remains below single-digit levels.
- Digital Mirrors:LCD-panel hybrids prioritize display brightness over reflective clarity, finding niche adoption in fitness and retail environments.
- Custom Mirrors:Bespoke frame finishes and non-standard dimensions serve high-end residential projects in Milan and Copenhagen design studios.
LED mirrors retain volume leadership; smart mirrors hold the steepest expansion curve.
End User:
Customer type determines pricing tolerance, with commercial bulk procurement compressing margins while residential single-unit sales sustain premium positioning.
- Residential:Private homeowners in Germany drive above-average uptake of integrated mirror-television units during bathroom renovations, constrained by structural compatibility with existing wall configurations.
- Commercial:Office and retail deployments prioritize durability specifications over entertainment functionality, with procurement cycles tied to lease renewal schedules rather than renovation timelines.
- Hospitality:Hotel chains in the United States and Western Europe are consolidating procurement power through direct supplier relationships, expanding volume commitments for waterproof mirror-television units across premium and mid-tier properties.
- Healthcare:Clinical environments demand antimicrobial surface treatments and compliance with medical device electromagnetic standards, limiting addressable vendor base.
Hospitality retains volume leadership; residential holds the steepest expansion curve.
Installation:
Mounting configuration dictates structural engineering requirements and retrofit feasibility across European hotel stock with varying wall construction standards.
- Wall-Mounted:The dominant configuration due to compatibility with existing bathroom layouts, though units above 32 inches diagonal demand reinforcement in older European hotel properties.
- Freestanding:Full-length mirror-television hybrids serve luxury residential dressing rooms and hospitality suite configurations without wall modification requirements.
- Embedded:Frameless architectural integration enabled by sub-3mm OLED panel thickness, specified in new German premium residential construction.
- Portable:Battery-powered units with limited brightness specifications address temporary hospitality installations and event deployments.
Wall-mounted retains volume leadership; embedded holds the steepest expansion curve.
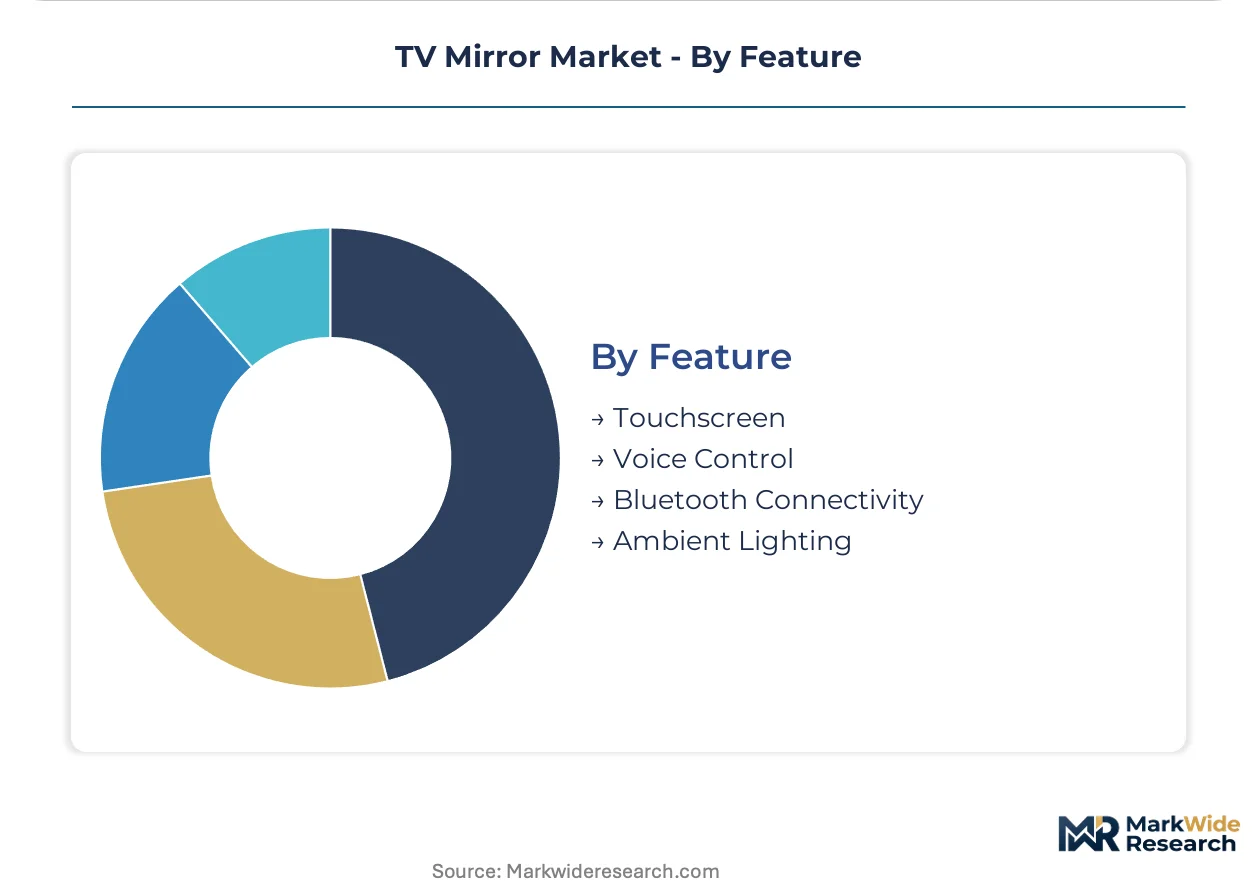
Feature:
Connectivity and interface modules are expanding bill-of-materials complexity while shifting value capture toward embedded software and recurring service revenue.
- Touchscreen:Capacitive interface layers add cost and reduce reflective surface area, finding adoption in hospitality properties where guest interaction novelty justifies premium positioning.
- Voice Control:Far-field microphone arrays integrated with smart home ecosystems are climbing fastest, opening hospitality upsell channels and residential ecosystem lock-in.
- Bluetooth Connectivity:Audio streaming functionality without video display serves fitness mirror applications and secondary bathroom installations.
- Ambient Lighting:Circadian-tunable LED backlighting addresses wellness positioning in premium residential segments without active display requirements.
Touchscreen retains volume leadership; voice control holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement teams in Germany and the United States concentrate bulk purchasing power, while residential demand clusters in premium renovation markets across Western Europe. Buyer archetypes fragment across direct hotel chain relationships, design studio intermediaries, and distributor networks serving single-unit residential upgrades.
United States
Marriott and Hilton renovation programs across Texas and Florida properties drive standardized in-mirror entertainment specifications. The FCC regulates electromagnetic emissions from integrated Wi-Fi modules, adding certification lead time for connected units. Direct procurement relationships are displacing traditional distributor networks in the hospitality channel.
Germany
Bathroom renovation rates exceeding EU averages sustain above-average uptake of integrated mirror-television units in private homes. The EU Ecodesign Directive mandates standby power thresholds for always-connected displays, accelerating R&D in ultra-low-power dielectric panels. Component suppliers in Baden-Württemberg face yield loss during trivalent chromium process migrations under REACH restrictions.
France
Hotel ownership groups are consolidating procurement power through quarterly supplier reviews, compressing negotiation cycles. The EU Radio Equipment Directive governs Bluetooth and Wi-Fi functionality, requiring simultaneous electromagnetic and safety testing for CE marking. Hospitality procurement teams in Paris specify full-array local dimming for premium property tiers.
United Kingdom
Design studios in London pilot subscription-based leasing models for luxury residential developments, fragmenting competitive access. The UKCA marking regime post-Brexit maintains alignment with EU safety standards while diverging on electromagnetic testing protocols. Premium residential construction in the Southeast anchors bespoke frame finish demand.
South Korea
Display panel supply chain concentration enables cost control across integrated mirror-television manufacturing. Korean chemical deposition specialists partner with German component suppliers on trivalent chromium alternative qualification. Seoul-based electronics manufacturers leverage thin-film OLED diffusion for sub-3mm frameless architectural integration.
TV Mirror Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. The vendor base separates into electronics conglomerates with captive display supply, custom fabrication studios serving architectural specifications, and hospitality-focused volume suppliers. Three archetypes dominate: scale-driven panel integrators, design-centric custom finish specialists, and direct-contract hospitality anchors. Competitive moves concentrate on strategic partnerships with hotel ownership groups and backward integration into dielectric coating processes.
Within the scale-driven tier, Samsung Electronics and LG Electronics occupy positions anchored by captive display panel supply chains. Seura exemplifies the design-specialist archetype through custom frame finish capabilities. Electric Mirror, Inc. anchors the hospitality channel vector through direct procurement relationships with major hotel chains.
| Leading Market Players |
|---|
| Samsung Electronics |
| Seura |
| Electric Mirror, Inc. |
| Ad Notam AG |
| Evervue |
| LG Electronics |
| Sony |
| Panasonic |
| MirrorMedia |
| Others |
Pricing and Supply Chain Analysis
Indium tin oxide supply concentration from Chinese rare earth processors determines both the spread between premium and standard tier pricing and the geographic shape of component sourcing networks. This single-source dependency compresses margins on mid-range dielectric mirror panels while forcing European manufacturers toward Korean chemical deposition partnerships.
Pricing Analysis
Cost-plus contracts with indium tin oxide indexation dominate procurement between display panel integrators and mirror-television assemblers. Pricing stratifies across premium, standard, and economy tiers based on ingress protection certification grade and customization level for frame finishes. Cost compression in the standard tier is intensifying because hospitality procurement teams are consolidating annual contracts into quarterly reviews. Hotel chains exhibit the highest price sensitivity, while design studios serving luxury residential projects in Milan and Copenhagen tolerate premium positioning for bespoke specifications.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for transparent electrode sourcing. Manufacturing concentrates in South Korea, China, and Germany, with display panel fabrication drawing from Korean chemical deposition specialists and German component suppliers. Raw material dependencies include indium tin oxide sputtering targets, thin-film OLED substrates, and dielectric mirror coatings. Distribution runs through direct procurement relationships with major hotel chains, displacing traditional distributor networks in the hospitality channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TV mirror market sits in a cyclical recovery phase driven by the post-pandemic hospitality renovation surge across Western Europe and the United States. Hotel property owners are accelerating bathroom upgrade timelines after deferred maintenance periods.
For Market Incumbents: Entrench hospitality channel control through multi-year service contracts bundling installation, maintenance, and software updates. Samsung Electronics and LG Electronics should deepen backward integration into dielectric coating processes to offset indium tin oxide price volatility. Incumbents must defend against emerging design studios piloting subscription leasing models by anchoring direct relationships with Marriott and Hilton procurement teams.
For New Entrants and Emerging Players: Establish a beachhead in the underpenetrated German residential segment where bathroom renovation rates exceed EU averages but mirror-television penetration remains below single-digit levels. Voice control integration with existing smart home ecosystems offers the most penetrable feature category. New entrants should pursue design studio partnerships in Copenhagen and Milan to access luxury residential developments without competing head-to-head against scale-driven panel integrators.
For Investors and Strategic Acquirers: The market sits at an expansion phase that favors hospitality-focused volume suppliers with captive display supply chains. Long-term viability over the next decade hinges on regulatory compliance capabilities across FCC and EU Ecodesign Directive frameworks. The signal to watch is the pace of trivalent chromium process qualification among German component suppliers, as REACH restrictions on hexavalent chromium will determine which vendors maintain European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Coating | Samsung Electronics controls component costs across integrated mirror-television units through captive supply. |
| Voice Control Platform Integration | Far-field microphone arrays with smart home ecosystem compatibility open hospitality upsell channels. |
| Subscription Leasing Model Launch | Design studios in Milan and Copenhagen fragment competitive access through fixture-as-a-service contracts. |
| Direct Hospitality Channel Expansion | Electric Mirror, Inc. anchors procurement relationships with major hotel chains requiring bulk waterproof LED mirror displays. |
| EU Ecodesign Compliance Certification | Ultra-low-power dielectric panel R&D accelerates as standby power thresholds mandate efficiency investment. |
Research Methodology
A spread of perspectives from hospitality procurement directors, bathroom fixture design studios, display panel supply chain managers, and regulatory compliance officers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of electronics manufacturers, EU Ecodesign Directive documentation, and customs records of indium tin oxide trade flows. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product architecture, end-user category, installation configuration, and connectivity feature tier. CAGRs derived from regression analysis of historical hospitality renovation cycles and residential construction permits. Industry-specific forecast inputs incorporated thin-film OLED diffusion rates and REACH substance restriction implementation timelines.
Sensitivities concentrate around indium tin oxide price volatility, hospitality renovation cycle timing, and regulatory compliance cost escalation. Forecasts reflect documented assumptions about technology adoption curves and procurement pattern shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Consumer Electronics Retail Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Ultra-Portable Speakers Market
Consumer Electronics
Global 4K TV Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
Mouse Pad Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Digital Writing Instruments Market