
 Pre-Shave Products Market | 2026-2036
Pre-Shave Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Shave Products Market Analytics
Specialized cosmetic chemists with expertise in plant-derived emulsification is reorganizing how pre-shave formulations achieve skin barrier compatibility. Procter & Gamble Company leverages its mass-market distribution infrastructure to sustain volume leadership in shaving gel. Beiersdorf AG anchors its European position through dermatological credibility in hypoallergenic pre-shave development. L'Oréal SA competes across multiple price tiers through brand portfolio breadth in men's grooming.
Pre-shave products comprise topical formulations applied before blade contact to soften keratinized facial hair, reduce friction coefficient, and hydrate the stratum corneum through humectant and occlusive agents such as glycerin, essential fatty acids, and silicone derivatives. Their commercial purpose centers on preventing razor burn, ingrown hairs, and epidermal abrasion in wet-shaving routines. Shaving cream retains the largest volume share as the conventional entry format, though pre-shave oil captures disproportionate margin pools in specialty and direct-to-consumer channels. Natural and organic formulations represent the fastest-expanding formulation category, reflecting ingredient transparency preferences among millennial and Generation Z purchasers.
FDA cosmetic labeling requirements and EU REACH substance restrictions govern ingredient safety disclosures and preservative limitations across pre-shave formulations sold in the United States and Europe. The EU Green Deal accelerates pressure on petrochemical-derived emollients, prompting reformulation toward bio-based alternatives. Stakeholders must monitor evolving dermatological testing standards and channel-specific regulatory thresholds as specialty retail and online platforms impose divergent compliance expectations.
Market Dynamics
EU REACH substance restrictions and the EU Green Deal are forcing wholesale reformulation of petrochemical-derived emollients toward bio-based alternatives, compressing margins for conventional suppliers while opening premium positioning for plant-derived specialists.
Growth Catalysts
- Artisanal barbering resurgence:Professional grooming services in Germany and France are standardizing pre-shave oil application protocols, creating institutional demand pull through certified barber academies.
- REACH chemical disclosure mandates:Ingredient transparency requirements are accelerating consumer switching from synthetic to natural formulations across European retail channels.
- Plant-derived emulsification:Cosmetic chemists are engineering lecithin and saponin-based systems that replicate silicone slip without petrochemical feedstocks.
Market Restraints
- Jojoba and argan oil price volatility:Climate-induced harvest fluctuations in Morocco and Argentina are compressing gross margins for natural-positioned brands.
- Preservative limitation technical barriers:EU Cosmetics Regulation Annex V restrictions on parabens and formaldehyde releasers are shortening shelf-stable formulation windows.
- Depilatory cream substitution threat:Chemical hair removal products are capturing price-sensitive consumers in mass retail, particularly in Southern European markets.
Strategic Opportunities
- Direct-to-consumer subscription models:Specialty oil brands are bypassing traditional retail markups through curated delivery services targeting urban millennials.
- EU Green Deal bio-based transition incentives:Member state recovery funds are subsidizing R&D for renewable emollient production facilities.
- Dermatological clinic channel expansion:Post-procedure soothing pre-shave protocols are creating institutional adoption pathways in medical aesthetics practices.
Industry Challenges
- Specialized cosmetic chemist talent scarcity:Formulation expertise in natural emulsification systems commands premium compensation and extended recruitment cycles.
- Dual regulatory compliance complexity:Simultaneous FDA cosmetic labeling and EU REACH substance registration creates documentation burdens for cross-Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Shave Products Market |
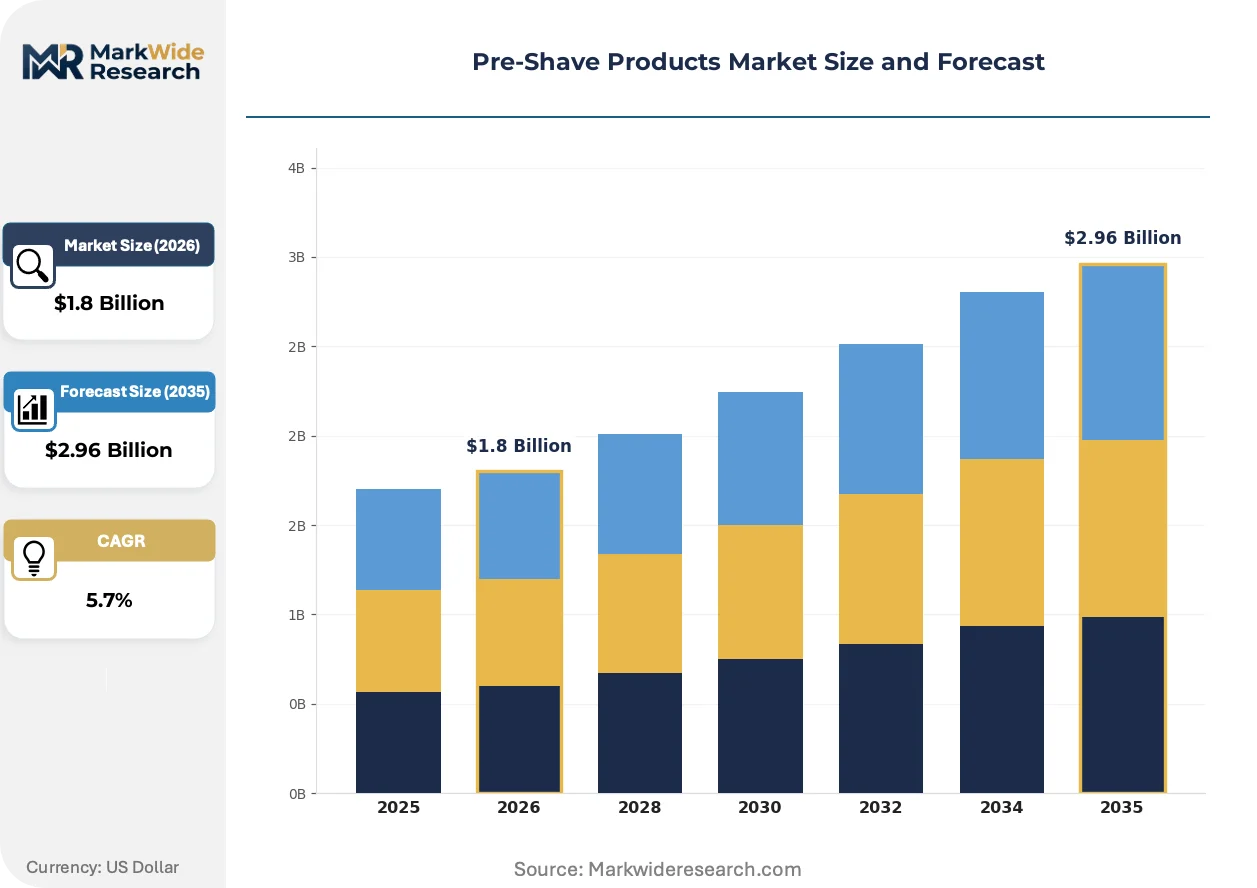
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving Cream, Shaving Gel, Pre-Shave Oil, Moisturizing Balm Formulation: Natural, Organic, Scented, Hypoallergenic Gender: Male, Female, Unisex, Non-Binary Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Drugstores |
| Companies Covered | L'Oréal SA, Johnson & Johnson, Beiersdorf AG, Procter & Gamble Company, Acqua di Parma, Proraso, Geo F Trumper, D.R. Harris, eShave, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Shave Products Market Evolving Landscape
Formulation science and procurement patterns are diverging sharply between mass-market efficiency and premium natural positioning, with regulatory chemistry mandates accelerating technical investment requirements.
Microbiome-friendly pre-shave formulations are bifurcating competitive positioning in the premium segment. Brands incorporating prebiotic oligosaccharides and postbiotic lysates are commanding shelf space in French and German apothecary channels. This technology is compressing conventional preservative-dependent formulations into commodity price tiers while enabling margin expansion for skin-barrier-compatible alternatives.
EU Green Deal carbon-border adjustment mechanisms are reshaping raw material sourcing economics for pre-shave manufacturers. Petrochemical-derived emollients face incremental compliance costs that bio-based alternatives avoid through certified supply chains. German formulators are responding fastest, restructuring supplier relationships toward domestic rapeseed and sunflower oil processing cooperatives.
Subscription-based replenishment models are displacing conventional retail purchasing for oil-format pre-shave products. Direct-to-consumer platforms in the United States and United Kingdom are capturing repeat-purchase loyalty through personalized scent profiling and automated delivery scheduling. This channel shift is most pronounced among millennial purchasers in metropolitan clusters, where convenience positioning outweighs immediate price comparison behavior.
Pre-Shave Products Market Segmentation
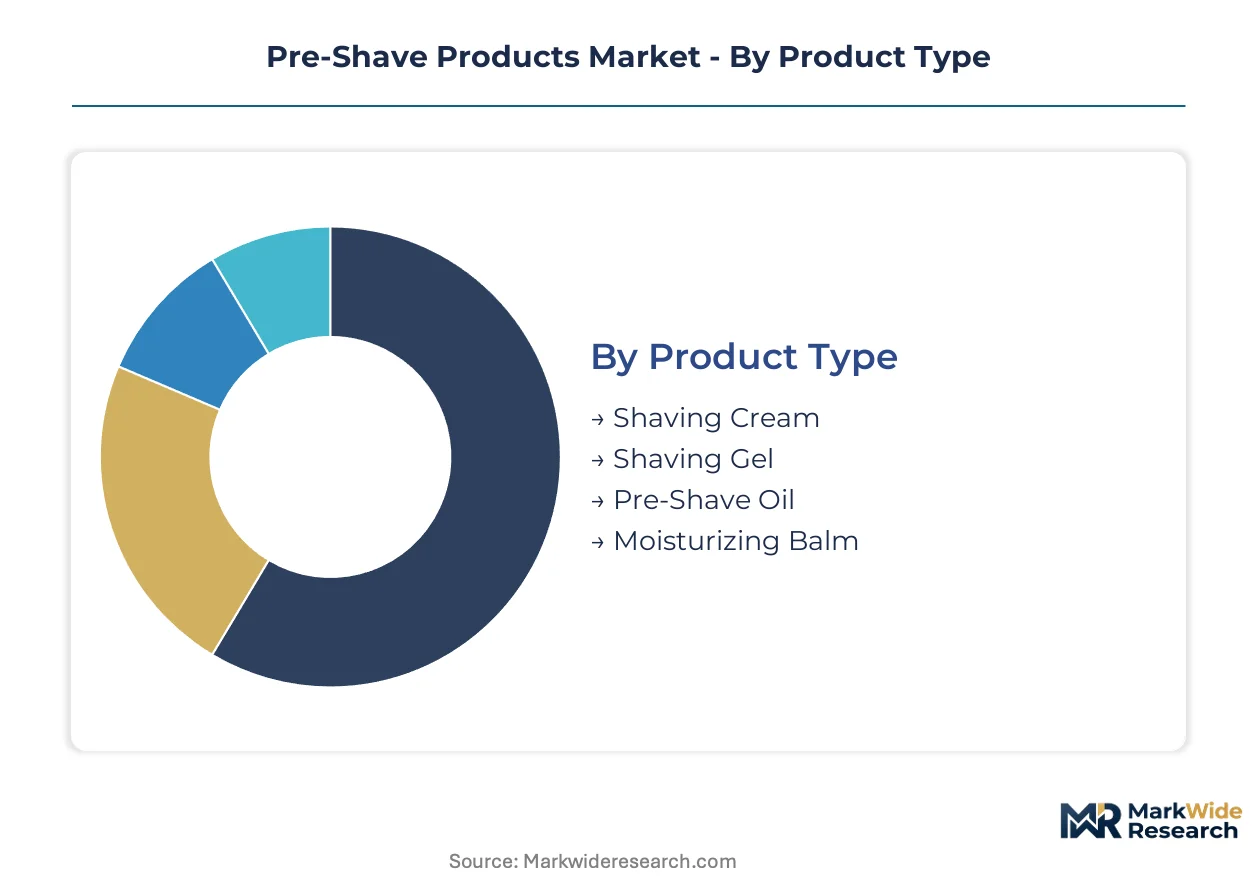
Pre-shave product segmentation reveals divergent growth mechanics across formulation technologies and channel economics. Understanding these divides helps suppliers allocate R&D investment and distribution resources against diverging margin profiles and regulatory exposure.
Product Type:
Shaving cream and gel formats dominate domestic mass-market consumption across Germany, France, and the United Kingdom, while pre-shave oil skews heavily toward export-led specialty trade into North American and Asian premium channels.
- Shaving Cream:Water-in-oil emulsions with stearic acid and triethanolamine soap bases deliver dense, brush-activated lather for traditional wet-shaving routines. German barber academies and French grooming institutes standardize cream protocols, institutionalizing demand through certified training curricula.
- Pre-Shave Oil:Occlusive botanical formulations using jojoba, castor, and essential oil blends create protective lipid barriers before blade contact. Moroccan argan oil supply chains and Bulgarian rose otto distillers feed premium positioning in direct-to-consumer channels across the United States and Japan.
- Shaving Gel:Polymer-thickened transparent gels enable precision visibility for facial hair styling and body grooming applications.
- Moisturizing Balm:Post-shave hybrid formats with allantoin and panthenol bridge pre-shave preparation and post-procedure skin recovery functions.
Shaving cream holds the largest share; momentum sits with pre-shave oil.
Formulation:
Cost tier stratification separates commodity petrochemical emulsions from premium bio-certified alternatives, with EU Green Deal compliance costs widening the pricing gap between conventional and natural-positioned offerings.
- Natural:Plant-derived emulsification systems using lecithin, saponins, and xanthan gum replace synthetic surfactants. REACH substance restrictions on silicone derivatives and petrochemical emollients are accelerating reformulation timelines across German and French manufacturing facilities.
- Hypoallergenic:Fragrance-free, preservative-minimized formulations with microbiome-compatible pH buffering target reactive skin conditions and post-procedure protocols. Dermatological clinic channels in Switzerland and Austria are adopting these formats for pre-laser hair removal preparation.
- Organic:Certified organic formulations meeting COSMOS or USDA NOP standards command shelf space in French apothecary and German organic specialty retail.
- Scented:Fragrance-forward positioning using synthetic or natural aromatic compounds targets mass-market impulse purchasing.
Natural formulations command the steepest expansion trajectory; hypoallergenic formats are gaining share fastest in institutional channels.
Gender:
Application breadth varies sharply, with male-identified segments concentrating in facial grooming while female and unisex categories expand into body grooming and depilatory preparation functions.
- Male:Traditional wet-shaving protocols for facial hair management sustain volume concentration in European barbering services and North American mass retail. Beard conditioning oil hybrids are extending product use occasions beyond daily shaving into grooming maintenance routines.
- Unisex:Gender-neutral positioning with minimalist packaging and universal scent profiles captures urban millennial purchasing across London, Berlin, and Amsterdam direct-to-consumer platforms.
- Female:Leg and underarm preparation formulations with lower-viscosity textures and floral scent positioning target body hair removal routines.
- Non-Binary:Explicitly inclusive marketing and formulation neutrality serve emerging demographic segments in metropolitan North American and Western European markets.
Male-identified segments retain volume leadership; unisex positioning is climbing the fastest.
Distribution Channel:
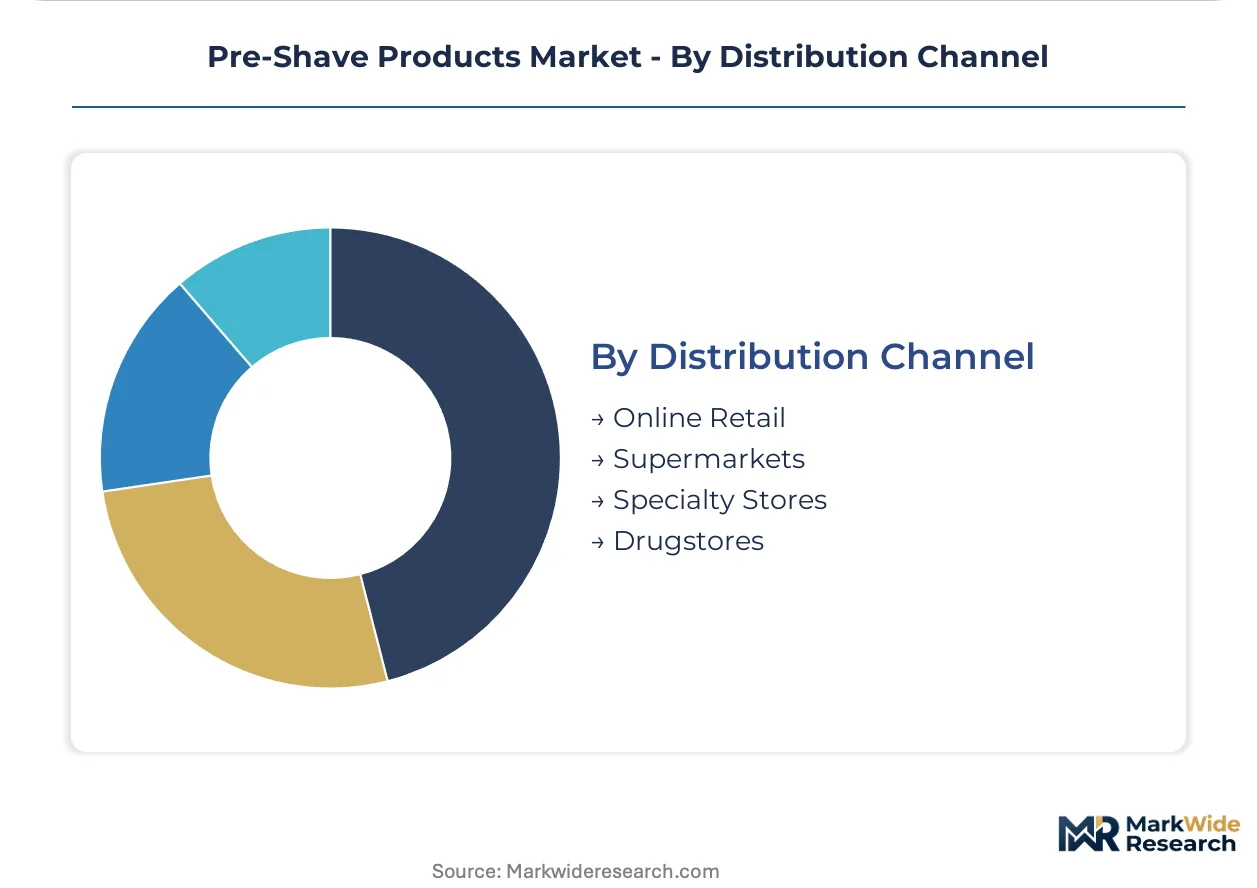
Customer type divergence separates convenience-driven replenishment from experiential discovery purchasing, with channel selection correlating to format complexity and education requirements.
- Specialty Stores:Curated brick-and-mortar environments with trained staff enable education-intensive oil and balm formats. German shaving specialty retailers and French parfumeries maintain artisanal brand exclusivity through controlled distribution agreements.
- Online Retail:Subscription replenishment models with personalized scent profiling and automated delivery scheduling capture repeat loyalty among metropolitan millennials in the United Kingdom and United States.
- Supermarkets:Mass-volume cream and gel formats with price-promotional mechanics serve routine replenishment purchasing.
- Drugstores:Hypoallergenic and sensitive-skin positioned formats leverage pharmacy credibility and dermatological recommendation networks.
Specialty stores hold the largest share in value terms; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions through ECHA govern the dominant European geography, where artisanal shaving culture and professional barbering services sustain premium demand for pre-shave formulations. Regulatory chemistry mandates are accelerating reformulation investments across manufacturing clusters.
Germany
Barber academy certification programs in Berlin and Munich institutionalize pre-shave oil protocols, creating trained professional demand. The EU Green Deal carbon-border adjustments incentivize domestic rapeseed and sunflower oil processing cooperatives in Lower Saxony. Hamburg-based formulators are restructuring supplier relationships toward bio-certified feedstock networks.
France
Apothecary channel expansion in Paris and Lyon drives microbiome-friendly formulation adoption among premium purchasers. ANSM cosmetic surveillance requirements enforce stringent preservative disclosure for sensitive-skin positioned products. Grasse fragrance houses are integrating essential oil distillation capabilities into pre-shave oil supply chains for export markets.
United States
Direct-to-consumer subscription platforms in New York and Los Angeles metropolitan clusters capture millennial repeat-purchase loyalty through automated replenishment. FDA cosmetic labeling requirements mandate ingredient transparency disclosures across interstate commerce. Brooklyn-based specialty retailers are curating artisanal oil brands through controlled distribution agreements.
United Kingdom
Traditional wet-shaving revival in London and Manchester sustains brush-activated cream consumption through heritage barbering establishments. UK REACH implementation maintains substance registration requirements post-Brexit, preserving compliance continuity. Jermyn Street fragrance specialists are expanding pre-shave oil assortments through parfumerie channel partnerships.
Japan
Precision grooming culture in Tokyo and Osaka metropolitan areas supports high-viscosity gel formats for facial hair styling applications. METI chemical substance management frameworks govern silicone derivative usage in cosmetic formulations. Osaka-based cosmetic chemists are engineering lecithin-based emulsification systems for skin-barrier-compatible alternatives.
Pre-Shave Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mass-market distribution infrastructure separating volume players from margin-focused artisans. The competitive terrain stratifies across three archetypes: multinational consumer goods conglomerates with dermatological credibility, heritage European barbering houses with apothecary channel control, and direct-to-consumer specialists with subscription platform expertise. Dominant competitive moves include portfolio diversification across price tiers and strategic partnerships with certified barber academies.
Within the heritage specialist tier, Acqua di Parma and Proraso exemplify Italian barbering tradition through controlled apothecary distribution, while Geo F Trumper anchors British grooming heritage through Jermyn Street retail presence. These houses occupy positions defined by artisanal formulation credibility rather than scale economics.
| Leading Market Players |
|---|
| L'Oréal SA |
| Johnson & Johnson |
| Beiersdorf AG |
| Procter & Gamble Company |
| Acqua di Parma |
| Proraso |
| Geo F Trumper |
| D.R. Harris |
| eShave, Inc. |
| Others |
Value Network & Pricing Analysis
EU REACH substance restrictions gate both supplier qualification and price differentiation simultaneously, compressing margins for petrochemical-dependent formulators while granting premium positioning to bio-certified alternatives that command shelf space in German apothecary and French parfumerie channels.
Pricing Analysis
German pre-shave oil commands a 40-60% premium over mass-market gel formats in Southern European supermarkets, reflecting artisanal positioning and barber academy certification value. Three-tier pricing structure across premium, standard, and economy levels separates COSMOS-certified organic oils from hypoallergenic dermatological formats and commodity petrochemical emulsions. Cost compression in the natural tier is intensifying because climate-induced argan and jojoba harvest volatility in Morocco and Argentina is squeezing gross margins. Price-sensitive mass-market purchasers in Spain and Italy drive volume through promotional mechanics, while German and Japanese premium buyers exhibit low elasticity for certified botanical formulations.
Supply Chain Analysis
Inventory lead times for Moroccan argan oil and Bulgarian rose otto extend to 8-14 weeks during harvest windows, forcing German formulators to pre-position feedstock before seasonal availability. Supply concentrates in Morocco for argan oil, Argentina for jojoba, and Germany for lecithin-based emulsification chemistry. Raw material dependencies rest on petrochemical-derived silicones, botanical fixed oils, and essential oil distillates. Single-source vulnerability in Moroccan argan cooperatives creates disruption exposure for premium-positioned brands. Distribution runs through certified barber academies in Berlin and Munich, direct-to-consumer subscription platforms in London and New York, and apothecary channels in Paris and Lyon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-shave product economics are shifting toward platform-mediated recurring revenue, with subscription interoperability and personalized scent-matching algorithms redefining customer lifetime value capture away from transactional retail.
For Market Incumbents: Shield market position by acquiring formulation talent in plant-derived emulsification systems before competitor recruitment cycles complete, and deepen backward integration into domestic rapeseed and sunflower oil processing cooperatives in Lower Saxony to offset EU Green Deal carbon-border adjustment exposure. Depilatory cream substitution in Southern European mass retail threatens volume concentration in conventional gel formats. For New Entrants and Emerging Players: COSMOS certification fast-track enables entry into French apothecary and German organic specialty retail where incumbent control is weakest. White-space concentrates in post-procedure soothing protocols for dermatological clinic channels in Switzerland and Austria, and in gender-neutral unisex positioning for urban millennial clusters in Amsterdam and Berlin. Go-to-market should anchor in direct-to-consumer subscription with automated replenishment and scent profiling. For Investors and Strategic Acquirers: UK REACH implementation post-Brexit reshapes the acquisition landscape by preserving compliance continuity for British heritage brands while fragmenting cross-Atlantic regulatory coordination. Long-term viability favors targets with captive botanical supply relationships and barber academy certification partnerships. Watch for ECHA substance restriction expansion announcements as the signal indicating reformulation cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Barber Academy Certification Partnership | Berlin and Munich academies institutionalize pre-shave oil protocols through standardized training curricula. |
| Direct-to-Consumer Subscription Launch | Automated replenishment with personalized scent profiling captures repeat-purchase loyalty among metropolitan millennials. |
| Bio-Based Emollient Manufacturing Scale-Up | Domestic rapeseed and sunflower processing in Lower Saxony reduces EU Green Deal carbon-border exposure. |
| Microbiome-Friendly Formulation Pipeline | Prebiotic oligosaccharide integration commands apothecary shelf space in Paris and Lyon premium channels. |
| Dermatological Clinic Channel Expansion | Post-laser preparation protocols in Swiss and Austrian medical aesthetics practices create institutional adoption pathways. |
Research Methodology
A spread of perspectives from cosmetic chemists at German formulators, procurement leads at French apothecary distributors, brand managers at direct-to-consumer subscription platforms, and barber academy curriculum directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through ECHA substance registration databases, EU Cosmetics Regulation Annex V filings, customs records for Moroccan argan and Argentine jojoba trade flows, and Nielsen retail audit data for European mass-market channels. Bottom-up triangulation of formulation-grade demand and top-down reconciliation against macro grooming expenditure trends anchored volume estimates.
Segmentation dimensions modeled span product type, formulation certification tier, gender positioning, and distribution channel complexity across the projection horizon. CAGRs were derived from regression analysis of historical premiumization trajectories and regulatory-driven substitution elasticities. Industry-specific forecast inputs include barber academy certification rollout schedules, EU Green Deal subsidy allocation patterns for bio-based R&D, and climate-induced harvest variance in Moroccan argan cooperatives.
Underlying assumptions cover REACH substance restriction enforcement continuity, barber academy protocol standardization rates, and subscription platform customer acquisition cost stability, with deviation risk concentrated in preservative limitation technical barriers and climate volatility in botanical feedstock regions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Women Face Razor Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Feminine Hygiene Products Market