
 Women Face Razor Market | 2026-2036
Women Face Razor Market Size, Share, and Industry Trends Forecast 2026-2036
Women Face Razor Market Analytics
Subscription-based leasing of precision blade manufacturing equipment is fragmenting capital barriers for mid-tier entrants. Procter & Gamble leverages its captive supply chain to control cartridge refill economics. Edgewell Personal Care sustains brand equity through dermatologist-endorsed product lines. KAI Group anchors Asian market share with ceramic blade specialization.
Women face razors are precision cutting instruments designed for facial dermaplaning and fine hair removal, typically featuring single-edge or guarded blades between 0.3 and 0.5 millimeters in exposure length to minimize epidermal trauma. Stainless steel variants dominate professional settings due to autoclavable sterilization compatibility, while plastic-handle disposables lead home-use volume. Cartridge razors capture the highest margin pool through proprietary blade-lock ecosystems. Electric razors represent the fastest-growing segment as battery miniaturization enables portable facial devices.
FDA cosmetic device regulations and EU MDR blade reclassification frameworks are elevating biocompatibility testing burdens for new market entrants. REACH compliance on nickel content in stainless steel blades shapes European sourcing decisions for manufacturers. Stakeholders must monitor evolving dermatological device classifications across FDA and EMA jurisdictions to anticipate channel restrictions and reimbursement eligibility shifts.
Market Dynamics
Subscription-based equipment leasing is fragmenting capital barriers for precision blade manufacturers, while FDA and EU MDR reclassifications of dermaplaning tools intensify biocompatibility testing burdens across all market tiers.
Growth Catalysts
- EU MDR blade reclassification:Tighter biocompatibility requirements for stainless steel variants are accelerating professional-grade product development cycles and raising entry barriers for low-quality competitors.
- Dermatology clinic expansion:Seoul, Tokyo, and New York facilities are scaling facial hair removal services, creating concentrated demand pull for autoclavable instruments.
- Ceramic blade specialization:Advanced ceramic formulations are displacing traditional steel in sensitive-skin applications across Japanese and South Korean professional channels.
Market Restraints
- Nickel content compliance:REACH restrictions on stainless steel blade composition are forcing European manufacturers toward costlier surgical-grade alloys.
- Supply concentration in East Asia:Precision grinding equipment and ceramic substrate production cluster in Japan and South Korea, creating single-source vulnerability.
- Autoclavable sterilization requirements:FDA device guidelines mandate repeated thermal cycling compatibility that plastic-handle disposables cannot meet, limiting home-use product premiumization.
Strategic Opportunities
- Battery miniaturization convergence:Portable electric facial devices combining precision motors with dermatological safety standards are opening premium home-use segments.
- Professional-to-consumer channel migration:Salon-grade cartridge systems with proprietary blade-lock ecosystems are transferring into direct retail through dermatologist endorsement networks.
- EMA reimbursement pathway development:Evolving dermatological device classifications in Europe are creating eligibility frameworks for medically indicated facial hair removal procedures.
Industry Challenges
- Biocompatibility certification timelines:FDA cosmetic device and EU MDR parallel review processes extend product launch cycles by 18-24 months for novel blade coatings.
- Precision grinding talent scarcity:Specialized technicians capable of maintaining 0.3-0.5 millimeter exposure tolerances are concentrated in legacy Japanese manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Face Razor Market |
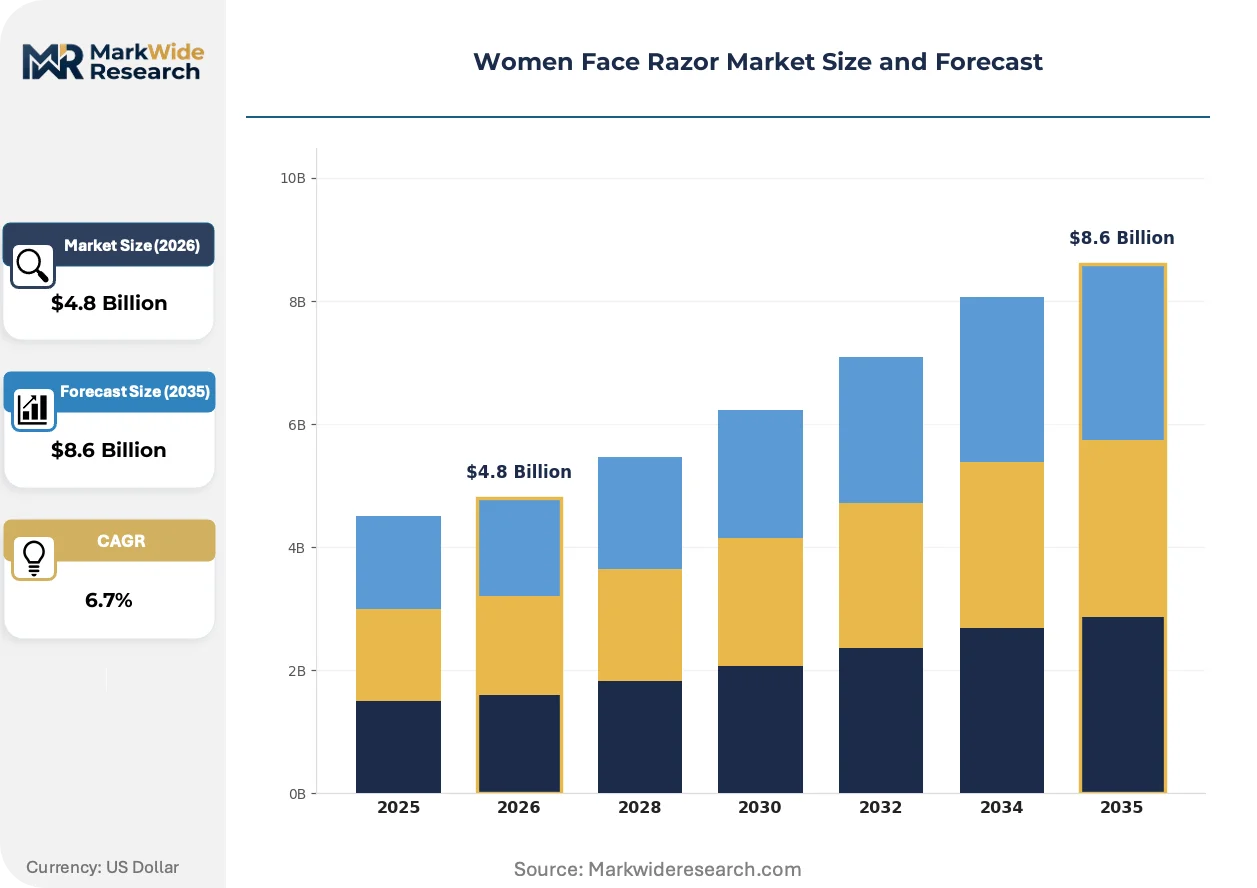
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Razors, Disposable Razors, Electric Razors, Cartridge Razors Material: Stainless Steel, Plastic, Ceramic, Aluminum End User: Beauty Salons, Home Users, Spa Centers, Dermatology Clinics Brand: Gillette, Schick, Bic, Harry's |
| Companies Covered | KAI Group, Revlon, Procter & Gamble, Plush, Dorco, Edgewell Personal Care, Empower, Tweezerman, BIC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Face Razor Market Evolving Landscape
Hybrid device architectures are compressing the boundary between professional salon instruments and home-use appliances, while regulatory convergence across FDA and EMA jurisdictions is standardizing safety testing protocols.
Ceramic-steel composite blade systems are hybridizing material properties for thermal stability and edge retention. Seoul-based dermatology chains are adopting these hybrids for high-frequency treatment protocols. The technology is hybridizing equipment procurement decisions by forcing capital planners to reconcile disposable economics with reusable instrument lifecycles.
EU MDR reclassification of certain dermaplaning tools as Class IIa medical devices is elevating clinical evidence requirements. Manufacturers must now submit biocompatibility testing under ISO 10993 standards for nickel ion release. Professional cartridge razor segments in Germany and France are responding by consolidating supplier relationships to share regulatory compliance costs.
Salon clients are purchasing take-home maintenance instruments following professional treatments, blurring historical channel boundaries. Subscription refill models are replacing discrete retail purchases in United States and Japanese urban markets. This pattern is most visible in Tokyo and New York where dermatology clinic density supports integrated professional-retail service bundles.
Women Face Razor Market Segmentation
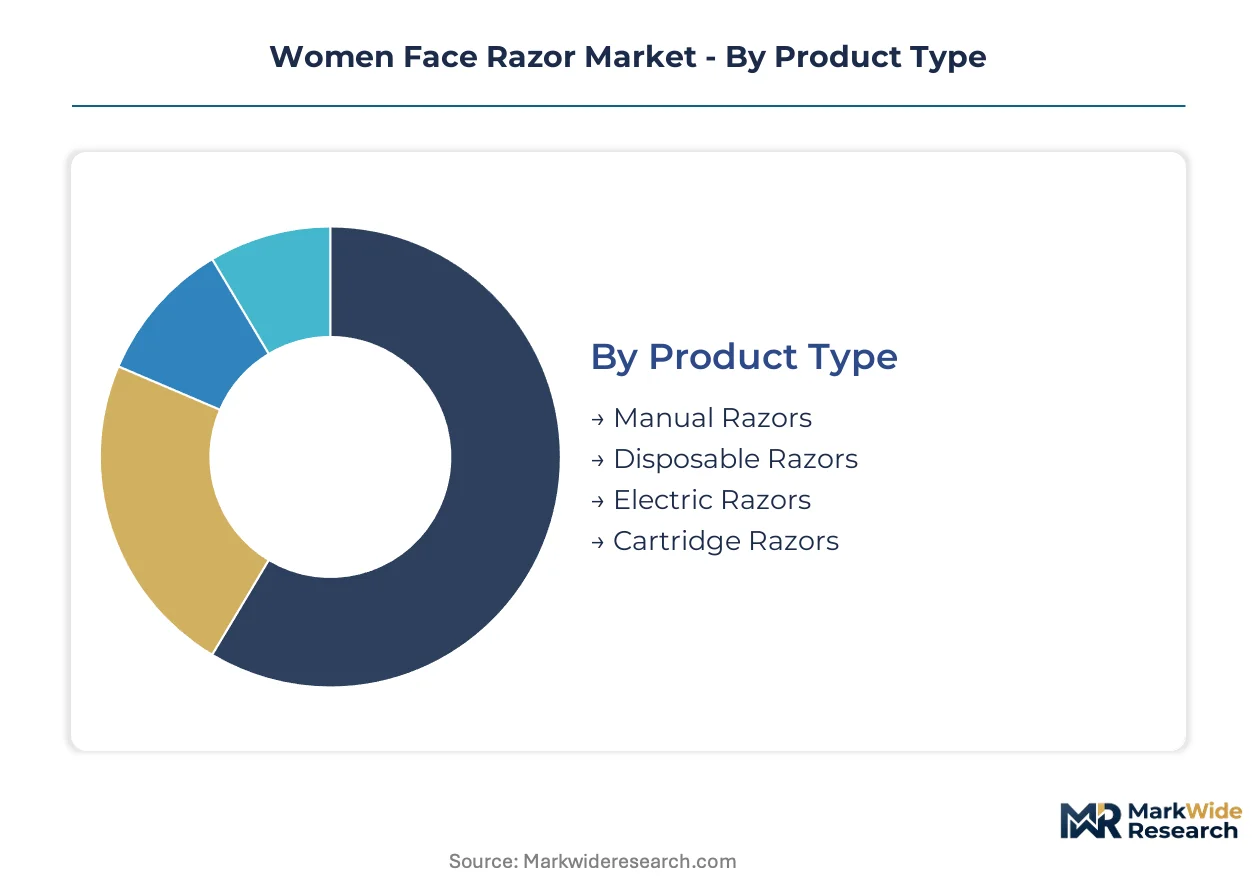
Segmentation in the women face razor market reveals divergent service intensity requirements across product architectures. Cartridge systems demand continuous blade replenishment logistics, while electric devices require warranty networks and motor maintenance protocols. Material composition directly determines sterilization compatibility and regulatory classification pathways.
Product Type:
After-sales service intensity varies dramatically across product architectures, with cartridge systems requiring ongoing refill logistics and electric devices demanding technical support infrastructure.
- Manual Razors:Single-edge or guarded designs with 0.3-0.5 millimeter blade exposure dominate professional dermaplaning protocols. Seoul and Tokyo dermatology clinics specify autoclavable stainless steel variants for high-frequency treatment cycles.
- Disposable Razors:Plastic-handle constructions with fixed blades serve price-sensitive home-use volume. REACH nickel compliance restrictions in Europe are forcing manufacturers toward costlier surgical-grade alloys, compressing margin pools.
- Electric Razors:Battery-miniaturized facial devices with precision motors represent the steepest expansion trajectory in premium home-use segments. Japanese and South Korean manufacturers lead motor miniaturization patents.
- Cartridge Razors:Proprietary blade-lock ecosystems capture recurring refill revenue through locked-in user bases. Procter & Gamble leverages captive supply chains to control cartridge economics across United States and Japanese urban markets.
Cartridge razors hold installed capacity. Electric razors are rotating up the share rankings.
Material:
Cost tier stratification separates medical-grade certifications from commodity disposable economics, with biocompatibility testing burdens concentrated in premium surgical alloys.
- Stainless Steel:Autoclavable variants dominate professional settings due to thermal cycling compatibility under FDA device guidelines. Nickel ion release testing under ISO 10993 standards shapes European sourcing decisions.
- Ceramic:Advanced formulations from Japanese manufacturers displace traditional steel in sensitive-skin applications across South Korean professional channels. KAI Group anchors Asian market share through substrate specialization.
- Plastic:Handle constructions enable cost-efficient disposables but fail FDA autoclavable sterilization mandates, limiting premiumization in professional channels.
- Aluminum:Lightweight handle substrates serve mid-tier home-use price points with reduced thermal stability compared to steel alternatives.
Stainless steel holds installed capacity. Ceramic is rotating up the share rankings.
End User:
Application context determines regulatory scrutiny intensity, with dermatology clinics facing EU MDR Class IIa medical device classifications absent in home-use channels.
- Dermatology Clinics:Facilities in New York, Seoul, and Tokyo scale facial hair removal services, creating concentrated demand pull for autoclavable instruments with ISO 10993 biocompatibility documentation.
- Beauty Salons:Professional cartridge systems with proprietary blade-lock ecosystems are transferring into direct retail through dermatologist endorsement networks in United States and Japanese markets.
- Home Users:Subscription refill models replace discrete retail purchases in urban markets with high dermatology clinic density, enabling integrated professional-retail service bundles.
- Spa Centers:Wellness-oriented facilities favor hybrid ceramic-steel composite systems for thermal stability during high-frequency treatment protocols.
Dermatology clinics hold installed capacity. Home users are rotating up the share rankings.
Brand:
Customer type loyalty patterns separate heritage pharmaceutical-channel relationships from direct-to-consumer digital acquisition strategies.
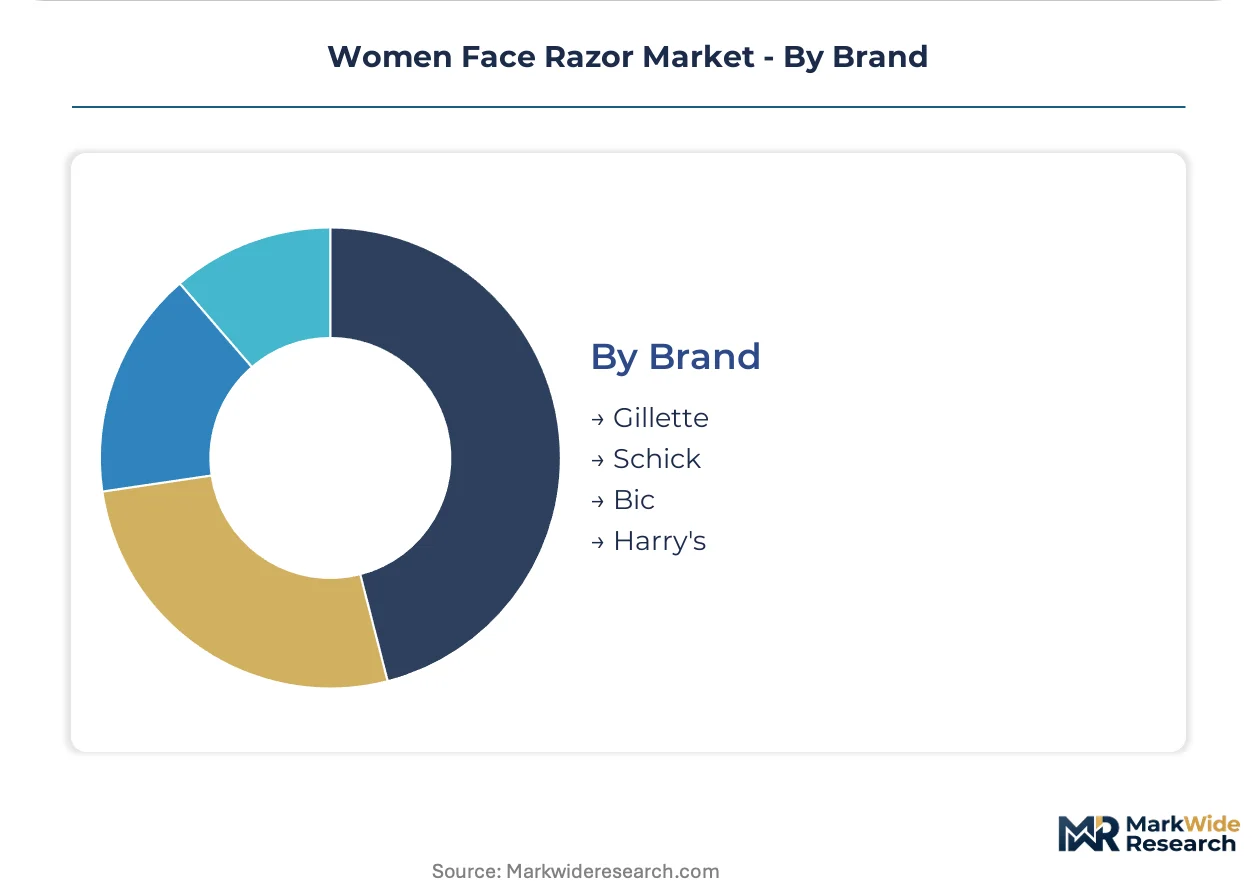
- Gillette:Procter & Gamble's captive supply chain controls cartridge refill economics through locked blade-lock ecosystems across professional and retail channels.
- Schick:Edgewell Personal Care sustains brand equity through dermatologist-endorsed product lines targeting sensitive-skin applications.
- Bic:Mass-market disposable positioning serves price-sensitive volume segments with limited premiumization potential under FDA sterilization requirements.
- Harry's:Direct-to-consumer subscription models disrupt traditional retail replenishment patterns in United States urban markets.
Gillette holds installed capacity. Harry's is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cartridge economics in Japanese and South Korean urban markets command pricing power multiples above mass-market disposables in India and Brazil. Dermatology clinic density in Seoul, Tokyo, and New York creates concentrated demand pull for autoclavable professional instruments. Regulatory divergence between FDA cosmetic device guidelines and EU MDR blade reclassifications fragments compliance pathways across Atlantic and Pacific markets.
United States
Dermatology clinic expansion in Manhattan and Los Angeles concentrates demand for autoclavable stainless steel instruments under FDA cosmetic device oversight. The agency's sterilization compatibility mandates shape professional procurement specifications. Subscription refill models proliferate in urban markets with high clinic density, transferring salon-grade cartridge systems into direct retail channels.
Japan
KAI Group anchors domestic ceramic blade specialization for sensitive-skin applications across Tokyo and Osaka professional channels. METI industrial standards govern precision grinding equipment certification for 0.3-0.5 millimeter exposure tolerances. Nagoya-area manufacturing clusters supply ceramic substrate formulations displacing traditional steel in high-frequency treatment protocols.
South Korea
Seoul dermatology chains scale facial hair removal services, creating concentrated demand pull for hybrid ceramic-steel composite systems. MFDS medical device classification frameworks elevate biocompatibility documentation requirements for professional instruments. Busan-Ulsan precision grinding facilities face talent scarcity for maintaining edge retention specifications under thermal cycling.
Germany
REACH nickel content restrictions on stainless steel blade composition force manufacturers toward costlier surgical-grade alloys in Frankfurt and Munich procurement networks. EU MDR Class IIa reclassification of certain dermaplaning tools mandates ISO 10993 biocompatibility testing under EMA jurisdiction. Bavarian medical device distributors consolidate supplier relationships to share regulatory compliance burdens.
India
Price-sensitive home-use volume concentrates in Mumbai and Delhi mass retail channels, with plastic-handle disposables dominating first-time purchaser segments. BIS standards for cosmetic appliances shape import specifications for electric facial devices. Local manufacturing clusters in Gujarat and Maharashtra assemble battery-miniaturized units for domestic distribution under cost-optimized specifications.
Women Face Razor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in blade substrate and precision grinding equipment. The market structures around three tiers: multinational consumer goods conglomerates with captive cartridge ecosystems, mid-tier specialists in ceramic or surgical-grade materials, and mass-market disposable fabricators competing on unit economics. Strategic moves concentrate on dermatologist endorsement networks for professional channel access and subscription-based equipment leasing to fragment capital barriers for precision manufacturing entrants.
Within the multinational platform tier, Procter & Gamble and Edgewell Personal Care exemplify divergent positioning archetypes—one leveraging supply chain captivity for refill economics, the other sustaining brand equity through clinical endorsement relationships. KAI Group occupies a distinct position as a geography-named specialist anchoring ceramic formulation expertise. These three entities represent the spectrum from integrated consumer platforms to materials-focused component depth.
| Leading Market Players |
|---|
| KAI Group |
| Revlon |
| Procter & Gamble |
| Plush |
| Dorco |
| Edgewell Personal Care |
| Empower |
| Tweezerman |
| BIC Group |
| Others |
Value Network & Pricing Analysis
Osaka-Nagoya ceramic substrate clusters anchor blade material supply, translating concentrated upstream capacity into pricing leverage for Japanese manufacturers over European REACH-compliant alloy alternatives.
Pricing Analysis
Configured-to-order pricing for autoclavable stainless steel instruments commands substantial premiums over standard plastic-handle disposables. Pricing stratifies across premium, standard, and economy tiers based on certification grade and sterilization compatibility. Cost compression in disposable segments is intensifying because REACH nickel compliance forces surgical-grade alloy substitution. Home users exhibit highest price sensitivity, while dermatology clinics prioritize biocompatibility documentation over unit cost.
Supply Chain Analysis
Upstream feedstock for precision blade manufacturing draws from Japanese ceramic substrate facilities, South Korean precision grinding equipment, and German surgical-grade steel mills. Raw material dependencies center on zirconium dioxide ceramic powders, nickel-reduced stainless steel billets, and cobalt-chromium alloys. Single-source vulnerability concentrates in Nagoya-area ceramic formulation plants. Distribution runs through professional salon channels in Seoul and Tokyo before migrating to subscription-based direct retail in United States urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery miniaturization convergence with dermatological safety standards creates high-growth disruption potential as portable electric devices capture premium home-use segments previously reserved for professional instruments.
For Market Incumbents: Pre-empt ceramic blade displacement by securing exclusive substrate supply agreements with Osaka-area formulation specialists. Accelerate ISO 10993 biocompatibility documentation for hybrid ceramic-steel composite systems before EU MDR Class IIa reclassification tightens clinical evidence requirements. Lock in dermatology clinic procurement contracts through integrated professional-retail service bundles.
For New Entrants and Emerging Players: Pursue subscription-based equipment leasing models to fragment capital barriers for precision grinding capacity acquisition. Target underserved spa center channels in secondary United States metropolitan areas with thermal-stable hybrid instruments. Leverage direct-to-consumer digital acquisition strategies with dermatologist endorsement networks bypassing traditional retail gatekeepers.
For Investors and Strategic Acquirers: Long-term, this sits as a component-specialist consolidation play because materials science differentiation increasingly determines margin capture over brand equity alone. Prioritize acquisition targets with captive ceramic substrate formulation capabilities and existing ISO 10993 testing infrastructure. Watch FDA-EMA regulatory convergence timelines as the signal for channel restriction severity and reimbursement eligibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | Captive zirconium dioxide supply secures margin control against Osaka-Nagoya cluster pricing volatility. |
| EU MDR Class IIa Certification Investment | ISO 10993 documentation unlocks German and French dermatology clinic procurement channels. |
| Battery Miniaturization R&D Partnership | Precision motor integration with dermatological safety standards opens premium home-use segments. |
| Subscription Refill Model Launch | Locked blade-lock ecosystems transfer salon-grade economics into direct retail urban markets. |
| Dermatologist Endorsement Network Expansion | Clinical credibility bridges professional-to-consumer channel migration in Tokyo and New York. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic procurement managers, precision grinding equipment technicians, ceramic substrate R&D directors, and beauty salon chain category buyers. Secondary validation incorporated FDA 510(k) device filings, EU MDR technical documentation databases, METI industrial standards registries, and REACH compliance certification records. Bottom-up demand modeling triangulated against top-down industry value chain estimates.
Calibration across the analysis window applied segment-specific growth coefficients to manual razor, disposable, electric, and cartridge product architectures. Modeled dimensions included material composition tier, end-user channel classification, sterilization compatibility grade, and geographic regulatory cluster. CAGRs derived from historical volume trajectories adjusted for EU MDR reclassification impact and battery miniaturization patent filing velocity. Industry-specific inputs incorporated dermatology clinic expansion rates in Seoul and Tokyo and ceramic-steel hybrid adoption curves.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending or medical device reimbursement policy would shift the trajectory. Forecasts reflect assumptions about regulatory timeline adherence and supply chain concentration persistence. Cross-checking against MFDS medical device registration databases and Japanese precision equipment export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
North America Hair Styling Tools Market
Personal Grooming Products
Disposable Electric Toothbrushes Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Latin America Hand Soap Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Hand Hygienic Product Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
Disposable Razor Blades Market