
 Cotton Pads Market | 2026-2036
Cotton Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Pads Market Analysis
Aftermarket service revenue from private-label cotton pad manufacturing is narrowing as branded producers reclaim margin pools through in-house production. Groupe Lemoine leverages its French vertical integration to control raw cotton sourcing from field to finished pad. Septona SA anchors its competitive position through medical-grade certification and hospital supply chain dominance. TZMO SA differentiates via sustainable bamboo-blend formulations that appeal to environmentally conscious European retailers.
Cotton pads are layered nonwoven cellulose structures, typically 30–50 mm in diameter and 2–5 mm thick, manufactured through carding and thermal bonding or needle-punching processes for controlled absorbency and lint-free performance in cosmetic and medical applications. Round pads occupy the largest volume share due to universal compatibility with toner and makeup remover dispensing, while organic pads represent the fastest-expanding margin pool as clean-beauty certifications command shelf price premiums. Compressed pads are gaining traction in travel retail channels where space-efficient packaging reduces logistics costs.
EU REACH regulations govern chemical residues in cosmetic-grade cotton, while the EU Green Deal's packaging waste rules are forcing reductions in plastic film overwrap across bag and box formats. The U.S. FDA maintains Good Manufacturing Practice oversight for medical cotton pads used in wound care and surgical prep. Stakeholders must monitor evolving biodegradability certification schemes and raw material traceability requirements as procurement criteria harden across European and North American retail chains.
Market Dynamics
The EU Green Deal's single-use plastics directive is compressing demand for petroleum-based packaging and redirecting procurement toward cellulose-based alternatives across European retail chains.
Growth Catalysts
- Professional salon channel expansion:Premium cotton pad specifications in hair coloring and facial services are pulling higher-margin organic SKUs into institutional purchasing contracts across France and Italy.
- REACH chemical residue standards:Cosmetic-grade cotton certification under ECHA protocols is locking in compliant suppliers and raising barriers to uncertified imports entering Germany.
- Bamboo-blend material innovation:Sustainable fiber formulations are capturing shelf space in environmentally conscious retail segments where biodegradable claims command price premiums.
Market Restraints
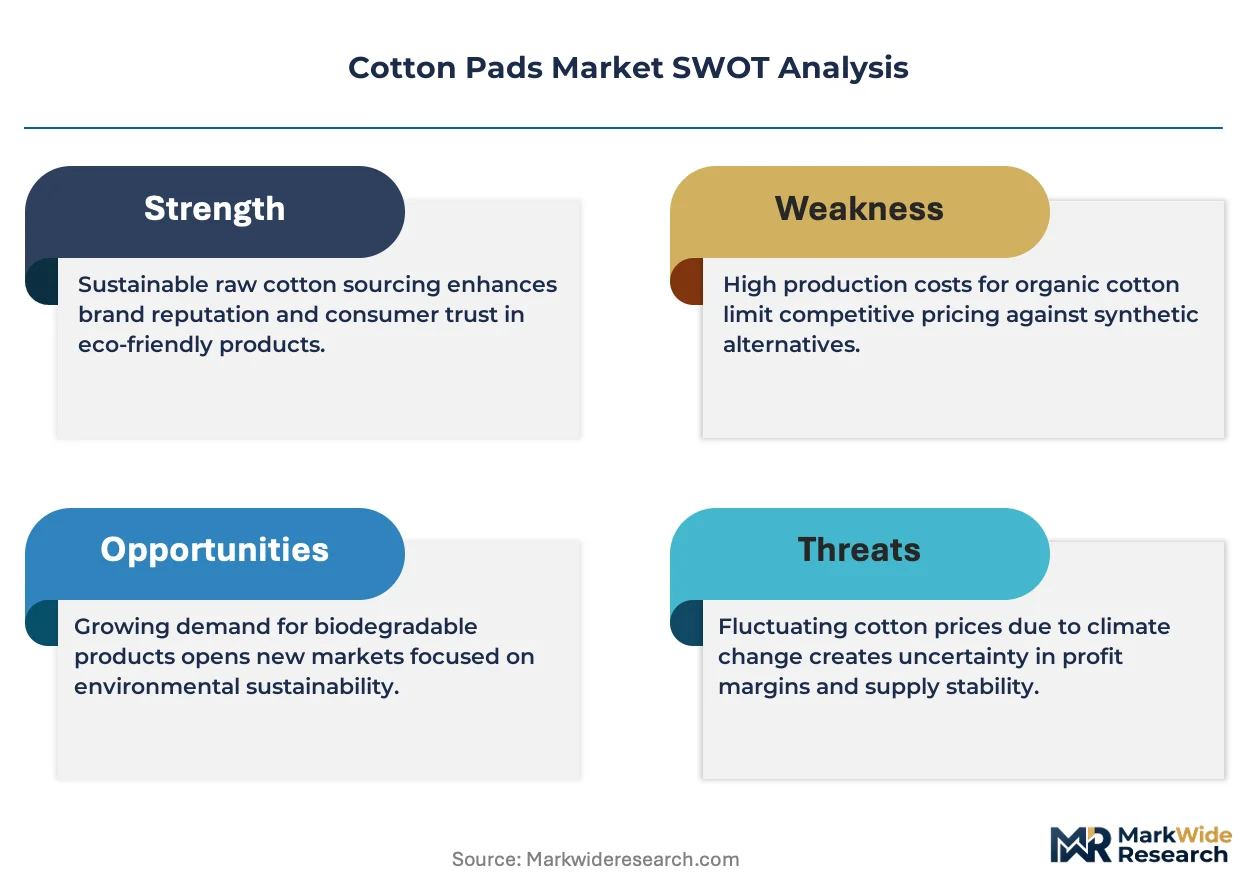
- Raw cotton price volatility:Climate-induced harvest fluctuations in Egypt and India are compressing margins for non-integrated converters lacking captive ginning capacity.
- Medical-grade certification friction:ISO 13485 compliance timelines for wound-care applications are extending 18-24 months and freezing smaller producers out of hospital supply chains.
- Reusable silicone pad substitution:Washable cosmetic applicators are displacing single-use volumes in direct-to-consumer channels targeting zero-waste households.
Strategic Opportunities
- Compressed pad travel retail:Space-efficient packaging formats are penetrating airport duty-free and hospitality amenity channels where logistics cost reduction drives assortment decisions.
- Clean-beauty certification tailwind:COSMOS and ECOCERT organic labels are unlocking shelf placement in prestige beauty retailers across Scandinavia and the Netherlands.
- Needle-punch thermal bonding convergence:Hybrid manufacturing processes are enabling lint-free performance in medical applications previously served by woven gauze alternatives.
Industry Challenges
- Biodegradability certification complexity:Competing standards from TÜV Austria, DIN CERTCO, and BPI are fragmenting testing requirements and delaying product launches.
- Legacy carding equipment retooling:Converting thermal bonding lines for bamboo-cellulose blends requires capital outlays that strain mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Pads Market |
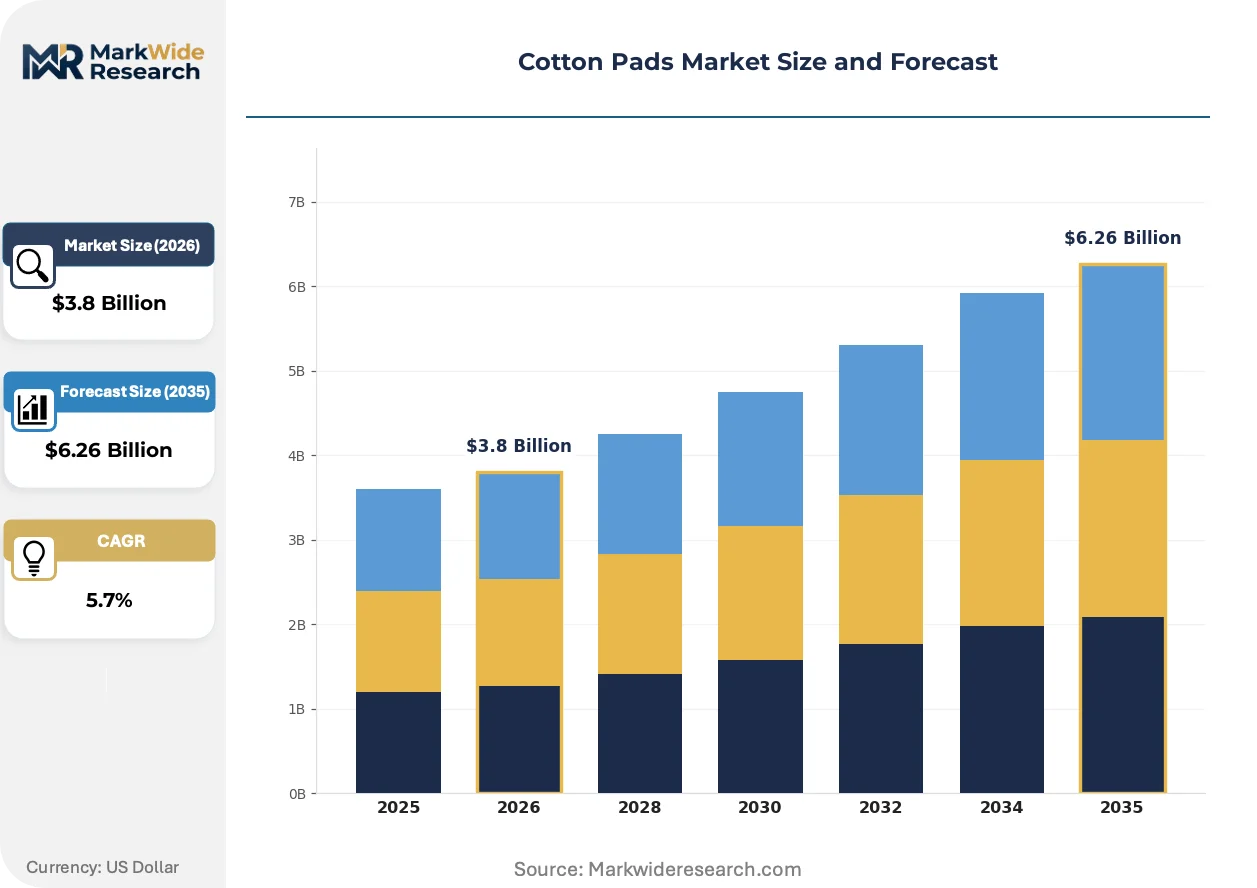
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Pads, Rectangular Pads, Compressed Pads, Organic Pads Material: Cotton, Rayon, Bamboo, Microfiber Application: Cosmetics, Medical, Household, Personal Care Packaging Type: Box, Bag, Sachet, Tray |
| Companies Covered | Groupe Lemoine, Septona SA, Cotton Club Co., Ltd., Shiseido Co. Ltd., TZMO SA, Unicharm Corp., SISMA Spa, Jaycot Industries, Sanitars Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Pads Market Emerging Trajectories
Manufacturing process digitization and fiber traceability systems are reshaping how cotton pad producers verify origin claims and manage quality consistency across distributed supply networks.
Blockchain-enabled fiber tracing is digitizing provenance documentation from ginnery to finished pad. Premium cosmetic brands in Germany and France are mandating lot-level traceability for organic cotton claims. This transparency infrastructure is compressing audit cycles and locking out suppliers lacking digital chain-of-custody capabilities.
EU Green Deal packaging waste rules are forcing reductions in plastic film overwrap across bag and box formats. Retailers in the Netherlands and Belgium are accelerating shifts to paper-based primary packaging. The professional salon segment faces the steepest compliance costs given multi-unit bulk packaging requirements.
Direct-to-consumer subscription models are fragmenting traditional wholesale channel dominance. Clean-beauty brands in Scandinavia are bypassing distributors to capture margin through recurring household deliveries. This channel rotation is most visible in organic pad segments where brand loyalty supports predictable replenishment cycles.
Cotton Pads Market Segmentation
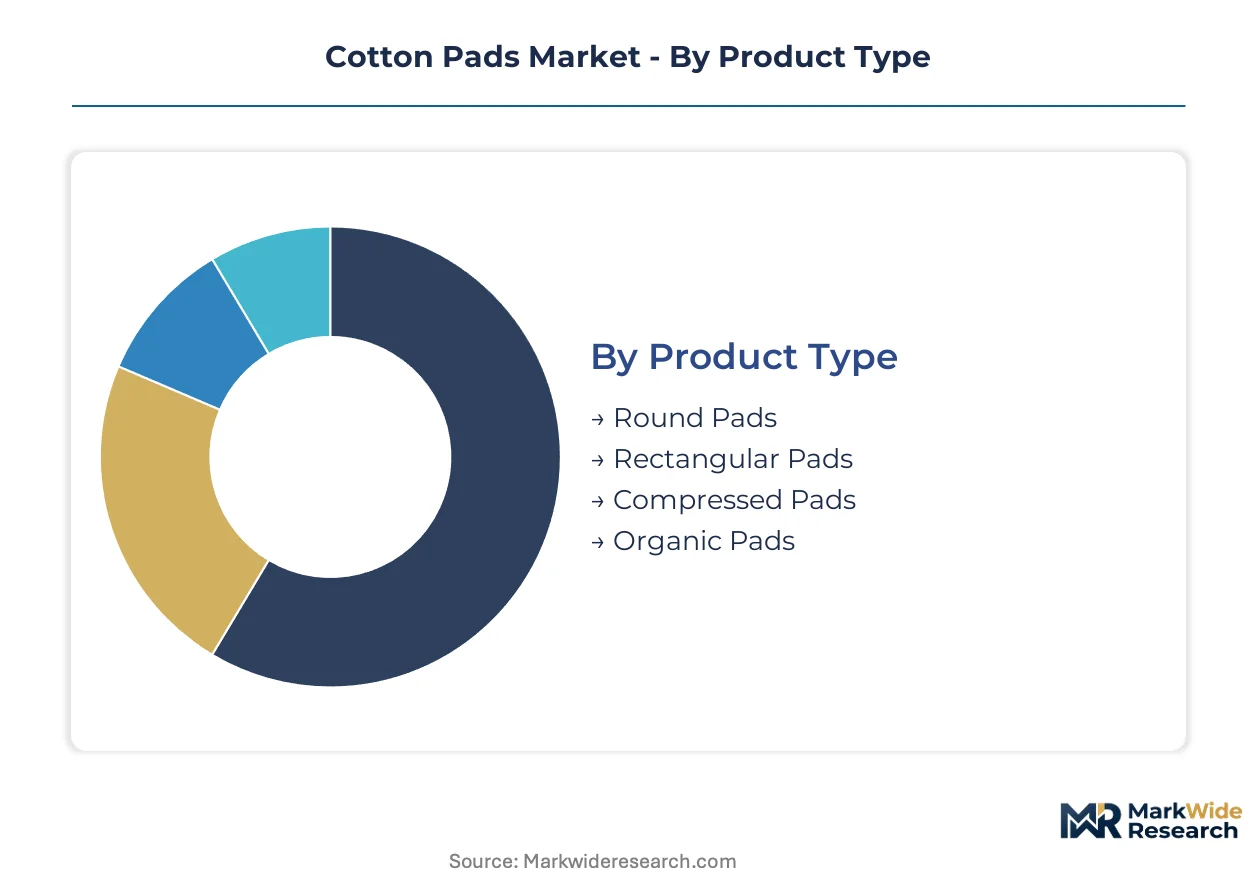
Segmentation in cotton pads reveals how functional specifications, material provenance, and channel packaging create distinct margin pools. Each dimension carries regulatory and supply chain implications that shape procurement decisions across cosmetic, medical, and institutional buyers.
Product Type:
Mature formats dominate volume, while emerging configurations target space-constrained and sustainability-focused channels.
- Round Pads:Circular cellulose structures, typically 30–50 mm in diameter, manufactured through carding and thermal bonding for controlled absorbency. Demand concentrates in professional salon services across France and Italy where universal compatibility with toner dispensing drives bulk procurement. Round pads retain volume leadership; organic pads hold the steepest expansion curve.
- Rectangular Pads:Elongated nonwoven structures optimized for facial masking and nail polish removal with broader surface coverage. German cosmetics manufacturers favor this format for private-label skincare lines targeting precision application.
- Compressed Pads:Space-efficient cellulose disks that expand upon liquid contact, enabling reduced logistics footprint. Travel retail channels in Netherlands and Belgium are adopting compressed formats for hospitality amenity programs where packaging waste rules tighten compliance costs.
- Organic Pads:Certified cellulose from controlled organic cultivation meeting COSMOS and ECOCERT standards. Clean-beauty retailers in Scandinavia command shelf price premiums for biodegradable claims backed by blockchain-enabled fiber tracing.
Round pads retain volume leadership; organic pads hold the steepest expansion curve.
Material:
Cost tiers separate commodity cellulose from specialty fibers commanding certification premiums.
- Cotton:Conventional gossypium-derived cellulose processed through ginning and bleaching for cosmetic-grade purity. Egyptian and Indian harvest volatility compresses margins for non-integrated converters lacking captive supply.
- Rayon:Regenerated cellulose fiber from wood pulp offering uniform absorbency at lower raw material cost. Medical applications in wound care specify rayon for lint-free performance under ISO 13485 protocols.
- Bamboo:Rapid-growth grass fiber blended with cellulose for biodegradable claims. TZMO SA's sustainable formulations capture shelf space in environmentally conscious European retail segments where EU Green Deal directives accelerate material shifts.
- Microfiber:Synthetic polymer filaments engineered for ultra-low lint and high tensile strength. REACH chemical residue standards under ECHA protocols restrict microfiber adoption in cosmetic-grade applications pending biodegradability certification.
Cotton retains cost-competitive volume; bamboo climbs the fastest on sustainability tailwinds.
Application:
Customer type determines specification rigor, from institutional procurement to household discretionary purchase.
- Cosmetics:Premium pad specifications for toner application, makeup removal, and nail care. Professional salon channel expansion across France and Italy pulls higher-margin organic SKUs into institutional purchasing contracts.
- Medical:Sterile-grade pads for wound care, surgical prep, and injection site cleansing. Septona SA anchors hospital supply chain dominance through medical-grade certification and ISO 13485 compliance.
- Household:General-purpose cleaning and surface applications with lower purity requirements. Private-label manufacturing concentrates in Germany's cosmetics manufacturing cluster for cost-optimized bulk supply.
- Personal Care:Individual hygiene applications including baby care and feminine hygiene. Direct-to-consumer subscription models in Scandinavia fragment traditional wholesale channel dominance through recurring household deliveries.
Cosmetics commands margin concentration; personal care gains share fastest via channel rotation.
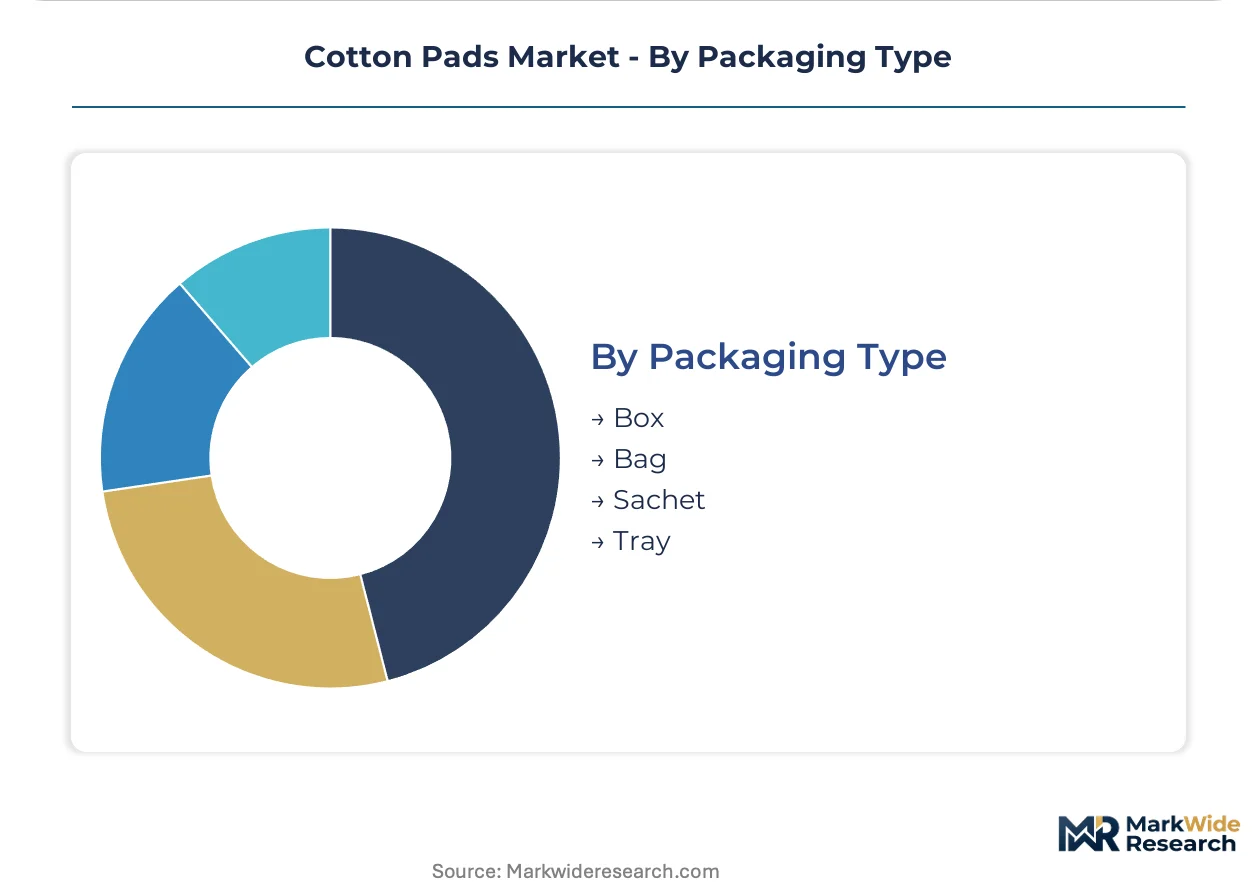
Packaging Type:
Volume scale and retail format dictate primary packaging selection, with regulatory pressure reshaping material choices.
- Box:Rigid paperboard containers for retail shelf presentation and multi-unit storage. EU Green Deal packaging waste rules force reductions in plastic film overwrap across box formats.
- Bag:Flexible film or paper pouches for cost-efficient bulk distribution. Netherlands and Belgium retailers accelerate shifts to paper-based primary packaging.
- Sachet:Single-unit sealed packets for hospitality amenities and travel retail. Compressed pad formats penetrate airport duty-free channels where space-efficient packaging reduces logistics costs.
- Tray:Molded pulp or plastic dispensers for professional salon workstation organization. Professional salon segment faces steepest compliance costs given multi-unit bulk packaging requirements under evolving biodegradability certification schemes.
Bag formats retain volume leadership; sachet configurations expand most quickly in travel and hospitality channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw cotton ginning clusters in Egypt and India anchor upstream supply, while finished pad manufacturing concentrates in European cosmetics hubs and East Asian personal care centers. Regulatory divergence between EU REACH protocols and U.S. FDA medical-grade standards fragments certification requirements across export destinations.
Germany
Professional salon services across North Rhine-Westphalia drive institutional procurement of premium organic SKUs. EU REACH chemical residue standards under ECHA protocols lock in compliant domestic suppliers and raise barriers to uncertified imports. The cosmetics manufacturing cluster around Düsseldorf and Cologne hosts private-label converters serving prestige beauty retailers.
France
Hair coloring and facial service expansion in Paris and Lyon pulls higher-margin cotton pad specifications into salon purchasing contracts. ANSM cosmetic safety oversight reinforces traceability requirements for organic fiber claims. Groupe Lemoine's vertical integration from field to finished pad anchors competitive positioning in the northern agricultural belt.
Netherlands
Retailers in Amsterdam and Rotterdam accelerate shifts to paper-based primary packaging under EU Green Deal waste rules. Clean-beauty certification demand concentrates in Randstad urban centers where COSMOS and ECOCERT labels command shelf price premiums. Compressed pad formats penetrate Schiphol airport duty-free channels for hospitality amenity programs.
Japan
Direct-to-consumer subscription models in Tokyo and Osaka fragment traditional wholesale channel dominance through recurring household deliveries. METI packaging reduction guidelines pressure plastic film overwrap reductions across bag and box formats. Unicharm Corp. exemplifies scale-driven archetypes serving mass-market personal care segments.
United States
Zero-waste household adoption of reusable silicone alternatives displaces single-use volumes in California and New York Metro direct-to-consumer channels. FDA Good Manufacturing Practice oversight governs medical cotton pads for wound care and surgical prep applications. ISO 13485 compliance timelines extend 18-24 months, freezing smaller producers out of hospital supply chains in the Midwest and Southeast.
Cotton Pads Market Vendor Landscape
Vertically integrated specialists and scale-driven multinationals split the market between margin-capture and volume-leadership strategies. Three archetypes dominate: French agricultural integrators controlling raw fiber sourcing, Japanese and Korean mass-market personal care conglomerates, and European medical-grade certification specialists. Competitive moves concentrate on backward integration into captive cotton supply and sustainable fiber formulation patents.
Within the European certification tier, Septona SA and TZMO SA occupy positions anchored by compliance infrastructure. Septona SA exemplifies the medical-grade specialist archetype through ISO 13485-governed hospital supply chain positioning. TZMO SA represents sustainable formulation leadership via bamboo-blend material innovation. Japanese conglomerates Shiseido Co. Ltd. and Unicharm Corp. sit within scale-driven tiers serving mass-market cosmetics and personal care segments.
| Leading Market Players |
|---|
| Groupe Lemoine |
| Septona SA |
| Cotton Club Co., Ltd. |
| Shiseido Co. Ltd. |
| TZMO SA |
| Unicharm Corp. |
| SISMA Spa |
| Jaycot Industries |
| Sanitars Spa |
| Others |
Supply Flow & Price Mechanics
Egyptian and Indian ginning clusters anchor raw cellulose supply for European converters, concentrating margin capture upstream while finished pad pricing stratifies downstream across certification tiers. This geographic asymmetry between fiber origin and manufacturing location creates persistent cost pressure on non-integrated producers lacking captive cotton procurement.
Pricing Analysis
After-sales revenue from institutional supply contracts and recurring subscription replenishment drives lifetime value capture across the professional salon and direct-to-consumer channels. Three-tier pricing structure across premium organic, standard cosmetic-grade, and economy private-label levels segments buyers by certification requirements and volume scale. Pricing pressure stems from climate-induced raw cotton volatility compressing converter margins. Professional salon buyers exhibit lowest price sensitivity given specification rigor, while mass-market household segments demand cost-optimized bulk formats.
Supply Chain Analysis
Supplier-financing facilities and extended payment terms from Egyptian and Indian ginning operations sustain working capital for European converters facing EU REACH compliance costs. Upstream concentration in Egypt, India, and Uzbekistan draws from gossypium harvest cycles subject to monsoon and irrigation variability. Single-source vulnerability runs through Nile Delta ginning infrastructure exposed to water scarcity. Distribution runs through cosmetics manufacturing clusters in Germany and France, hospital supply chains anchored by ISO 13485-certified specialists, and direct-to-consumer platforms in Scandinavia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment story where ECHA REACH certification and ISO 13485 compliance create switching costs that freeze uncertified competitors out of institutional procurement channels.
For Market Incumbents: Pre-empt silicone pad substitution by accelerating biodegradable fiber R&D and locking in blockchain-enabled traceability infrastructure before clean-beauty mandates harden. Secure captive cotton supply through backward integration into Egyptian or Indian ginning assets to insulate margin from harvest volatility. Reinforce hospital supply chain dominance by extending ISO 13485 certification into wound-care adjacencies.
For New Entrants and Emerging Players: Compressed pad penetration in Benelux travel retail and hospitality amenity channels offers the most penetrable white-space target given logistics cost sensitivity and packaging waste rule compliance burdens. Target Scandinavian direct-to-consumer subscription models where brand loyalty supports predictable replenishment cycles and bypasses distributor margin extraction. Pursue COSMOS and ECOCERT certification as the primary go-to-market credential for prestige beauty retailer placement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European medical-grade specialists holding ISO 13485-governed hospital contracts and compliance infrastructure. Long-term viability hinges on regulatory entrenchment deepening across EU Green Deal implementation and biodegradability certification fragmentation. Watch for aggressive moves by Japanese mass-market conglomerates acquiring European sustainable formulation capabilities as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cotton Supply | Egyptian ginning assets insulate Groupe Lemoine from climate-induced price volatility. |
| Bamboo-Blend Formulation Patent Expansion | TZMO SA's sustainable fiber R&D captures EU Green Deal-driven retailer shelf space. |
| Blockchain-Enabled Fiber Traceability Deployment | Lot-level provenance documentation satisfies ANSM cosmetic safety oversight in France. |
| Compressed Pad Travel Retail Channel Entry | Space-efficient formats penetrate Schiphol duty-free under Netherlands packaging waste rules. |
| ISO 13485 Medical Certification Extension | Septona SA's hospital supply chain dominance expands into wound-care adjacencies. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with cosmetics brand managers, professional salon procurement heads, hospital purchasing committee members, and cotton ginning operations directors. Secondary validation drew from ECHA REACH registration databases, EU Green Deal directive filings, ANSM cosmetic safety records, and customs trade data tracking Egyptian and Indian cellulose exports. Bottom-up volume modeling triangulated against top-down value estimates across product type, material composition, application segment, and packaging format dimensions.
Calibration against historical growth patterns and regulatory implementation timelines shaped projections across the analysis window. Segmentation modeling captured round, rectangular, compressed, and organic pad configurations; cotton, rayon, bamboo, and microfiber materials; cosmetics, medical, household, and personal care applications; and box, bag, sachet, and tray packaging types. CAGRs derived from volume trajectory analysis incorporating raw material cost elasticity and channel shift dynamics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Japanese mass-market conglomerates or PE-backed sustainable fiber specialists would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Smart Electric Toothbrush Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Smart Hairbrush Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Compostable Toothbrush Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Hand Hygienic Product Market